
 Wheat Protein Concentrates Market | 2026-2036
Wheat Protein Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Protein Concentrates Market Analytics
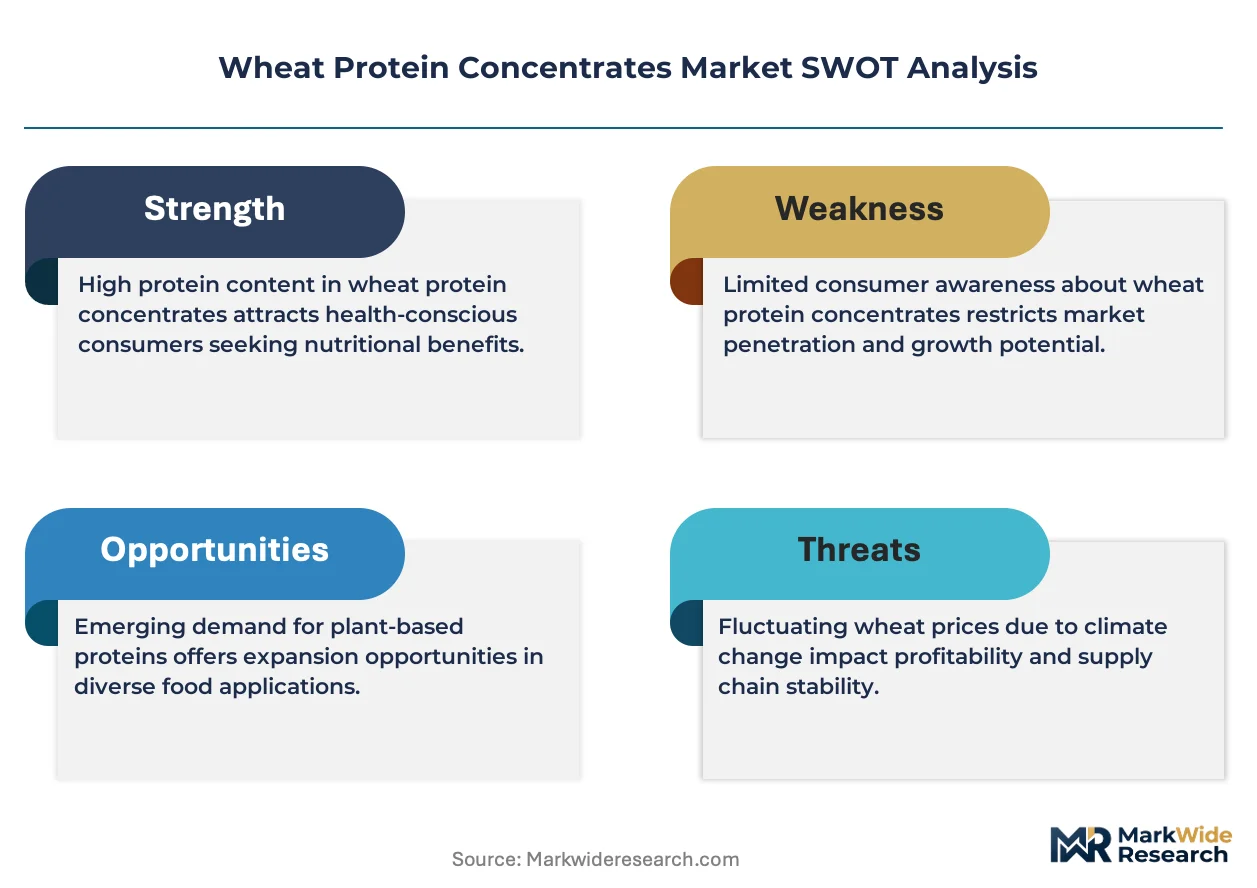
Food-grade protein specification upgrades above 80% dry-basis concentration is redrawing supplier hierarchies in wheat-derived ingredients. Cargill leverages its North American grain origination network to secure feedstock consistency for concentrate production. Manildra Group anchors Australian supply through integrated flour milling and protein extraction assets. Roquette Frères differentiates via European pea-wheat protein blending capabilities that extend formulation options for meat-alternative developers.
Wheat protein concentrates are fractionated gluten-rich proteins typically containing 65–85% protein on a dry-weight basis, produced through aqueous washing of wheat flour dough followed by drying, serving primarily as viscoelastic structure-builders in baked goods and as binding systems in plant-based meats. Concentrate grades dominate current volume owing to cost-positioning in bakery applications, while textured protein variants are gaining fastest as extrusion technologies improve fibrous morphology for meat-analogue bite. Hydrolyzed protein occupies a narrower but higher-margin niche in nutraceutical and sports-nutrition formulations where solubility and rapid absorption command premium positioning.
EFSA and FDA both maintain allergen-labeling mandates that classify wheat gluten as a major food allergen, directly shaping product formulation transparency and cross-contamination protocols across export markets. REACH registration requirements in Europe and EPA discharge permits for wet-milling facilities impose capital intensity thresholds that favor scaled producers over regional entrants. Stakeholders must monitor evolving protein-content certification standards and carbon-footprint disclosure rules that will determine eligibility for clean-label and climate-neutral product positioning.
Market Dynamics
Plant-based meat formulators are rewriting protein procurement specifications, forcing wheat protein concentrate suppliers to reengineer extraction protocols for higher purity and functional performance in extruded fibrous matrices.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Binding sustainability targets for crop-derived ingredients are redirecting bakery and meat-alternative manufacturers toward domestically sourced wheat protein concentrates with verifiable carbon footprints.
- Extrusion technology advances:Twin-screw high-moisture extrusion systems are enabling concentrate producers to deliver meat-analogue textures that satisfy foodservice chains' bite and chew specifications.
- German processing cluster concentration:Integrated flour milling and protein extraction facilities in Baden-Württemberg and Bavaria are shortening supply chains for European meat-alternative developers.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings disproportionately impact wet-milling operations, where thermal drying consumes 40-60% of production energy.
- Allergen labeling mandates:EFSA and FDA wheat gluten classifications trigger costly segregation protocols and limit formulation flexibility in multi-protein facilities.
- Pea protein substitution:Roquette Frères and other suppliers are blending pea-wheat systems that reduce pure wheat concentrate volumes in premium meat-analogue applications.
Strategic Opportunities
- India FSSAI protein fortification mandates:Government-backed school nutrition and processed food enrichment programs are creating import demand for cost-competitive concentrate grades.
- Hydrolyzed protein nutraceutical channel:Sports nutrition and clinical nutrition formulators are sourcing rapidly absorbed wheat peptide fractions for premium positioning.
- Carbon labeling convergence:ISO 14067-compliant product carbon footprint declarations are unlocking preferential procurement terms from climate-neutral brand owners.
Industry Challenges
- Skilled extrusion engineering shortage:High-moisture extrusion operation and die design expertise remains concentrated among a handful of European equipment specialists.
- REACH registration timelines:Novel protein modification chemistries face 18-36 month ECHA evaluation windows that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Protein Concentrates Market |
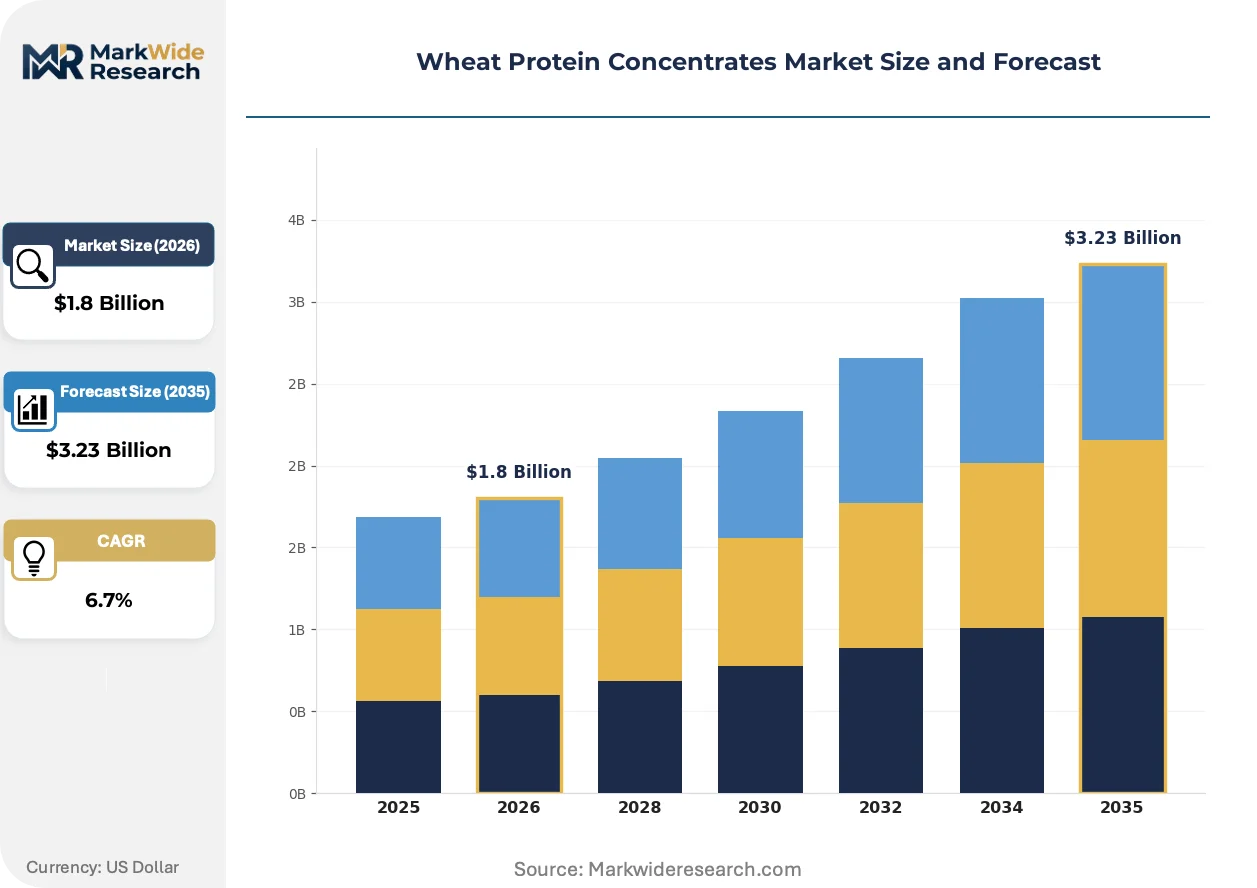
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured Protein, Hydrolyzed Protein Application: Bakery Products, Beverages, Snacks, Meat Alternatives End User: Food Industry, Animal Feed, Nutraceuticals, Personal Care Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Archer Daniels Midland, Manildra Group, Cargill, Tereos, Agrana, MGP Ingredients, Roquette Frères, Crespel & Deiters, AB Amilina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Protein Concentrates Market Evolving Landscape
Fractionation technologies and regulatory disclosure requirements are converging to redefine value capture in wheat-derived proteins, with functional performance and verified sustainability credentials becoming inseparable purchasing criteria.
Enzymatic hydrolysis protocols are displacing traditional acid or alkaline processing routes in concentrate manufacturing. Specialty enzyme suppliers are tailoring protease blends to target specific peptide chain lengths for solubility and emulsification. Meat-alternative developers in Germany and the Netherlands are accelerating adoption of these hydrolyzed fractions for improved water-binding in extruded products. This enzymatic shift is displacing legacy wet-milling investments that cannot achieve the same functional specificity without capital-intensive retrofit.
REACH registration requirements for novel protein modifications are tightening disclosure obligations across European supply chains. ECHA's 2024 updated guidance on polymer and protein substance definitions is forcing concentrate producers to re-evaluate existing dossiers. Small and mid-scale extractors in Eastern Europe are consolidating testing resources through industry consortia to manage registration costs. The regulatory burden is concentrating formulation partnerships among REACH-compliant suppliers with established substance portfolios.
Direct procurement relationships between meat-alternative brands and concentrate producers are compressing traditional ingredient distributor roles. Impossible Foods and Nestlé's Garden Gourmet are establishing multi-year offtake agreements with specified protein content and carbon intensity thresholds. These bilateral arrangements are replacing spot-market purchasing for volume-stable bakery and meat-analogue applications. The channel restructuring is most advanced in Germany, where processing cluster proximity enables just-in-time delivery without distributor warehousing.
Wheat Protein Concentrates Market Segmentation
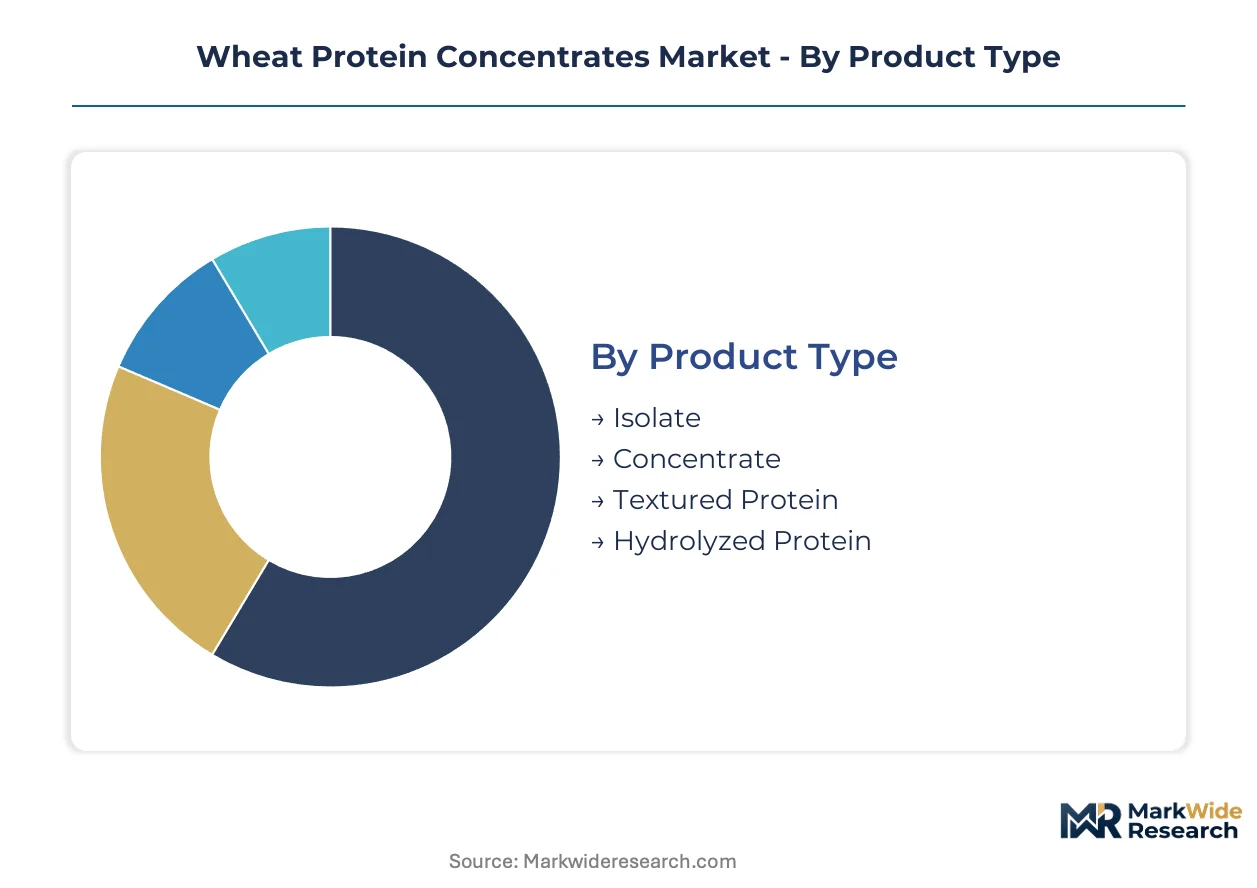
Wheat protein concentrate suppliers face divergent technical demands across end-use categories, with bakery applications prioritizing cost-efficient viscoelastic performance while meat-alternative developers command premium specifications for fibrous texture replication. Segmentation clarity determines which production assets merit capital deployment versus obsolescence risk from protein substitution.
Product Type:
Concentrate grades confront the most acute substitution pressure from pea and soy protein systems in meat-analogue formulations, forcing suppliers to differentiate through functional specificity rather than commodity positioning.
- Isolate:Protein fractions exceeding 90% dry-basis purity serve high-performance applications where minimal carbohydrate content enables clean-label positioning. German meat-alternative developers specify isolate grades for premium extruded products requiring neutral flavor profiles and controlled water absorption kinetics.
- Concentrate:Standard 65–85% protein grades anchor bakery volume through gluten-network formation in bread and pasta systems. Cost positioning relative to dairy and egg alternatives sustains demand from industrial bakers in Baden-Württemberg processing clusters despite energy-intensive wet-milling economics.
- Textured Protein:Extruded fibrous structures replicate meat bite in plant-based analogues. High-moisture extrusion capability gaps limit qualified supplier pools.
- Hydrolyzed Protein:Enzymatically cleaved peptide fractions deliver rapid solubility for sports nutrition and clinical formulations. Soluble grades command premium positioning in nutraceutical channels.
Concentrate retains volume leadership; textured protein holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity bakery volume from premium meat-alternative contracts, with the latter demanding dedicated extrusion lines and technical service support.
- Bakery Products:Viscoelastic gluten networks provide structure and chew in bread, pasta, and pastry systems. Industrial bakers in Germany source concentrate grades through direct mill relationships that bypass distributor markups.
- Meat Alternatives:Binding and fibrous texture replication in plant-based burgers and sausages requires customized protein hydration profiles. Dutch and German foodservice chains specify textured concentrates for bite-matching against animal proteins.
- Beverages:Hydrolyzed fractions enable suspension stability in fortified drinks. Limited solubility of standard concentrates restricts penetration.
- Snacks:Protein fortification in extruded crisps and bars utilizes concentrate cost positioning. Flavor masking requirements constrain isolate adoption.
Bakery products retain volume leadership; meat alternatives hold the steepest expansion curve.
End User:
Customer type maturity varies sharply, with food industry procurement standardization contrasting nutraceutical channel fragmentation around certification requirements.
- Food Industry:Industrial bakers and meat-alternative processors drive bulk concentrate demand through multi-year offtake agreements. German processing cluster proximity enables just-in-time delivery without safety stock.
- Nutraceuticals:Sports nutrition and clinical peptide formulators source hydrolyzed grades with documented amino acid profiles. FSSAI protein fortification mandates in India are redirecting concentrate volumes toward government nutrition programs.
- Animal Feed:Cost-competitive concentrate grades substitute for fishmeal in aquaculture feeds. Price volatility in competing protein sources creates demand elasticity.
- Personal Care:Wheat protein hydrolysates function as film-forming agents in hair and skin formulations. Niche volume relative to food applications.
Food industry retains volume leadership; nutraceuticals holds the steepest expansion curve.
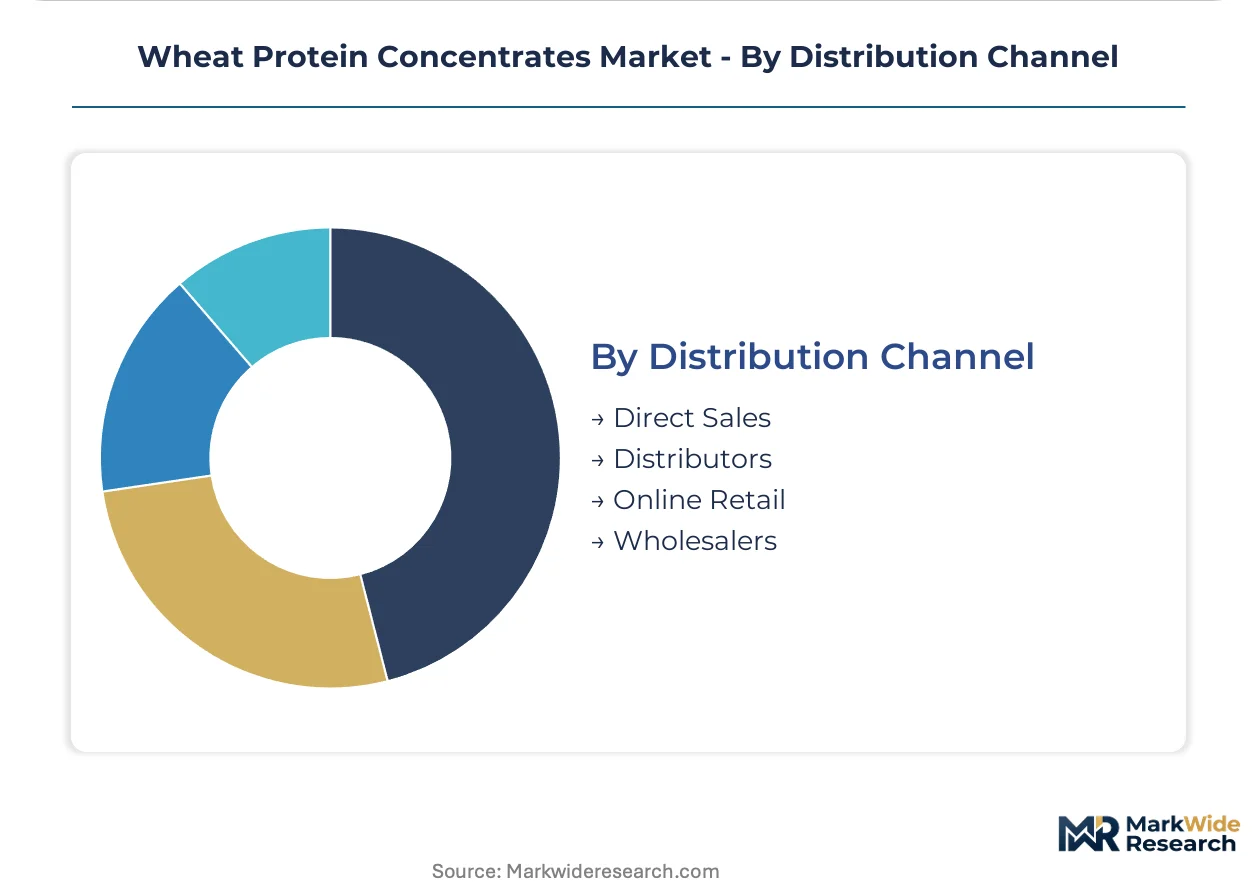
Distribution Channel:
Supply concentration in German milling clusters compresses channel margins through direct procurement relationships that disintermediate traditional ingredient distributors.
- Direct Sales:Bilateral contracts between concentrate producers and meat-alternative brands specify protein content, carbon intensity thresholds, and volume commitments. Nestlé's Garden Gourmet and Impossible Foods have established multi-year arrangements that eliminate spot-market exposure.
- Distributors:Regional ingredient houses serve mid-scale bakery and snack processors lacking procurement scale for direct mill relationships. Inventory carrying costs and technical service limitations constrain value capture.
- Online Retail:Specialty hydrolyzed protein fractions reach sports nutrition consumers through direct-to-brand channels. Limited relevance for industrial concentrate volumes.
- Wholesalers:Bulk concentrate movement for animal feed applications leverages agricultural commodity trading networks. Price transparency and low switching costs intensify competition.
Direct sales retains volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in wheat protein concentrates reflect divergent processing capacities and protein fortification policies across major economies. Germany and the United States maintain structural surpluses in high-purity grades, while India and China import concentrate volumes to meet government-backed nutrition mandates.
Germany
Baden-Württemberg and Bavaria host integrated flour milling and protein extraction clusters supplying meat-alternative developers across the EU. The EU Green Deal Farm to Fork strategy mandates verifiable carbon footprints for crop-derived ingredients, redirecting procurement toward domestic processors. Crespel & Deiters anchors supply from its Ibbenbüren facility, shortening delivery cycles for Dutch and German foodservice chains.
United States
Industrial bakers and plant-based meat formulators drive concentrate demand through direct mill relationships bypassing distributor markups. FDA allergen labeling mandates classify wheat gluten as a major food allergen, triggering segregation protocols in multi-protein facilities. Kansas and Minnesota processing corridors supply cost-competitive grades to North American bakery networks.
India
FSSAI protein fortification mandates for school nutrition and processed food enrichment programs are creating import demand for standard concentrate grades. Government-backed enrichment schemes redirect volumes toward government nutrition programs. Maharashtra and Gujarat food processors source through agricultural commodity trading networks with limited technical service support.
China
Domestic wet-milling capacity expansion is reducing import dependence for bakery-grade concentrates while sports nutrition formulators import hydrolyzed fractions for premium positioning. SAMR food safety standards tighten disclosure obligations for imported protein ingredients. Shandong Province processing clusters are scaling aqueous extraction assets to serve regional bakery chains.
Australia
Manildra Group's integrated flour milling and protein extraction assets anchor supply to Southeast Asian export markets. Wheat belt proximity to processing infrastructure reduces feedstock logistics costs. New South Wales facilities concentrate production for Asian meat-alternative developers seeking non-EU origin certificates.
Wheat Protein Concentrates Market Competitive Landscape
Concentration sits with integrated grain processors and specialized protein extractors that control origination-to-extraction value chains. The supplier base stratifies into three tiers: multinational agribusiness conglomerates with captive wheat supply, regional millers with fractionation capabilities, and niche hydrolyzed protein specialists. Dominant competitive moves include backward integration into grain origination networks and strategic partnerships with extrusion technology providers for textured protein capacity.
Among North American agribusinesses, Archer Daniels Midland and Cargill exemplify scale-driven archetypes with grain origination networks feeding concentrate production. Manildra Group occupies a position as an integrated Australasian supplier with captive milling assets. Roquette Frères represents the European specialist tier, blending pea-wheat protein systems that extend formulation options for meat-alternative developers.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Manildra Group |
| Cargill |
| Tereos |
| Agrana |
| MGP Ingredients |
| Roquette Frères |
| Crespel & Deiters |
| AB Amilina |
| Others |
Value Network & Pricing Analysis
Pea protein substitution in premium meat-analogue formulations is redrawing procurement geography while compressing pricing power for standard wheat concentrate grades. This displacement simultaneously concentrates buyer leverage among Dutch and German foodservice chains and forces suppliers toward functional differentiation to defend margin structures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across concentrate grades. Three-tier pricing structure across premium, standard, and economy levels separates hydrolyzed nutraceutical fractions from bakery-grade concentrates and feed-quality bulk volumes. Cost compression in standard grades is intensifying because energy-intensive wet-milling economics face natural gas price volatility. Mid-scale snack processors exhibit highest price sensitivity, while meat-alternative developers prioritize functional performance over unit cost.
Supply Chain Analysis
Just-in-time delivery preferences dominate German meat-alternative procurement, eliminating distributor warehousing through direct mill relationships. Supply concentrates in Germany, the United States, and Australia, with Baden-Württemberg processing clusters serving EU demand. Production draws from wheat grain feedstock, specialty enzyme inputs for hydrolysis, and natural gas for thermal drying. Single-source vulnerability sits with high-moisture extrusion equipment concentrated among European specialists. Distribution runs through bilateral producer-brand contracts replacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as plant-based meat formulators accelerate extruded protein procurement beyond current supplier capacity. EU Green Deal carbon-footprint mandates are creating first-mover advantages for verified low-intensity producers.
For Market Incumbents: Shield market position by deepening backward integration into grain origination networks that secure feedstock consistency against price volatility. Invest in REACH-compliant hydrolyzed protein dossiers before ECHA evaluation windows tighten further. Prioritize captive supply of specialty enzyme blends that enable functional specificity pea-wheat systems cannot replicate.
For New Entrants and Emerging Players: Differentiate on carbon-verified supply chains that unlock preferential procurement terms from climate-neutral brand owners. Target India's FSSAI protein fortification mandates as the most penetrable demand pocket, where government nutrition programs seek cost-competitive import grades. Pursue direct technical service partnerships with mid-scale bakery processors lacking extrusion expertise.
For Investors and Strategic Acquirers: REACH registration consolidation reshapes the acquisition landscape toward compliant suppliers with established substance portfolios. Five-to-ten year viability favors integrated processors controlling origination-to-extraction value chains rather than standalone fractionators exposed to feedstock volatility. Monitor carbon-labeling convergence as the signal indicating which assets capture climate-neutral procurement premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill and ADM leverage North American origination networks to secure feedstock consistency for concentrate production. |
| High-Moisture Extrusion Capacity Expansion | German suppliers deploy twin-screw systems to meet foodservice chain specifications for meat-analogue bite and chew. |
| REACH Registration Consolidation | Eastern European extractors pool testing resources through industry consortia to manage ECHA disclosure obligations. |
| Carbon Footprint Certification Program | ISO 14067-compliant declarations unlock preferential terms from Nestlé's Garden Gourmet and similar climate-neutral brands. |
| Direct Procurement Relationship Establishment | Impossible Foods bilateral contracts eliminate distributor margins while specifying protein content and carbon intensity thresholds. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, EFSA regulatory filings, and SEC disclosures from agribusiness conglomerates. Conversations with plant-based meat formulators, flour milling procurement leads, extrusion equipment specialists, and sports nutrition peptide buyers informed demand-side assumptions. Technical validation drew from wet-milling plant managers, specialty enzyme suppliers, and REACH compliance consultants. Bottom-up volume estimates triangulated against top-down protein ingredient market allocations.
Segmentation dimensions modeled span product type hierarchy, application cost tiers, end-user procurement maturity, and distribution channel structure across the analysis window. CAGRs derived from elasticity-adjusted volume projections incorporating extrusion technology adoption curves and protein fortification policy implementation timelines. Forecast inputs included energy cost scenario modeling for wet-milling operations and carbon-labeling penetration rates among EU food manufacturers.
Material uncertainties — regulatory timeline slippage, feedstock price dislocations, and substitution elasticity shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and FSSAI mandate enforcement consistency. Revision becomes warranted when pea-wheat blend adoption crosses thresholds that structurally displace pure wheat concentrate volumes in premium applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Africa Food Ingredients Market
Ingredients
Corn Peptide Market
Ingredients
India Soy Protein Market
Ingredients
South America Malt Ingredient Market
Ingredients
Meat Extract Market
Ingredients
Textured Soy Protein Market
Ingredients
Isoamyl Laurate Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Calendula Oil Market
Ingredients
Cacao Extracts Market
Ingredients
Lupin Flour Market
Ingredients
Hydroxytyrosol Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
European Brewing Enzymes Market