
 China Gelatin Market | 2026-2036
China Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
China Gelatin Market Outlook
Clean-label extraction technology is narrowing the quality gap between conventional acid-processed gelatin and enzyme-refined alternatives. Xiamen Hyfine Gelatin leverages enzymatic hydrolysis to serve high-purity pharmaceutical grades. Tianjin Hwashin Biotechnology anchors its position through backward integration into pigskin raw material sourcing. Lanpu Gelatin differentiates via specialized fish gelatin production for halal and kosher export channels.
Gelatin is a collagen-derived protein obtained through controlled hydrolysis of animal connective tissues, yielding gelling, stabilizing, and film-forming properties with bloom strengths typically ranging from 50 to 300 grams. The material functions as a critical excipient in hard and soft capsule manufacturing, a binding agent in confectionery, and a stabilizer in dairy and dessert applications. Pigskin gelatin occupies the dominant volume position due to China's large pork processing base and favorable extraction yields. Bone gelatin from bovine sources faces structural constraints from BSE-related import restrictions and domestic consumer preference shifts. Fish gelatin represents the fastest-growing product type, driven by pharmaceutical companies seeking non-mammalian alternatives for religious and allergen-sensitive formulations.
NMPA gelatin monographs and GB standards for edible and pharmaceutical grades shape product specifications, testing protocols, and facility certification requirements. The country's dual carbon goals from MEE are pressing gelatin processors to retrofit wastewater treatment and reduce energy intensity in rendering operations. SAMR food safety audits and traceability mandates are tightening raw material documentation across the supply chain. Stakeholders must monitor evolving pharmaceutical excipient registration pathways and carbon compliance deadlines to secure long-term manufacturing licenses.
Market Dynamics
NMPA tightening of pharmaceutical excipient standards is compressing supplier qualification timelines while concentrating procurement among certified domestic processors. Shandong and Henan rendering clusters now face dual pressure from quality mandates and MEE carbon compliance deadlines.
Growth Catalysts
- Pharmaceutical capsule demand:Domestic drug manufacturers are expanding hard and soft capsule production lines to serve generic drug volume contracts.
- NMPA quality standards:Stricter excipient monographs are disqualifying uncertified suppliers and redirecting volume toward GMP-compliant facilities.
- Enzymatic hydrolysis:Cleaner extraction yields are opening pharmaceutical-grade pathways for processors upgrading from acid-based methods.
Market Restraints
- Pigskin supply concentration:Rendering operations cluster in Shandong and Henan provinces, creating geographic vulnerability to regional disease outbreaks or environmental enforcement.
- Bovine bone restrictions:BSE-related import constraints and consumer preference shifts limit bone gelatin expansion despite available cattle processing byproducts.
- Energy intensity:Thermal rendering processes face rising costs from MEE dual carbon compliance requirements and natural gas price volatility.
Strategic Opportunities
- Fish gelatin specialization:Non-mammalian alternatives for halal and kosher export channels remain underdeveloped relative to pharmaceutical demand.
- Carbon retrofit incentives:MEE wastewater treatment and energy efficiency mandates create first-mover advantages for processors completing upgrades ahead of license renewal deadlines.
- Traceability systems:SAMR raw material documentation requirements favor integrated operators with captive pigskin sourcing and blockchain-enabled batch tracking.
Industry Challenges
- Pharmaceutical GMP certification:NMPA facility audits and excipient registration pathways demand capital-intensive cleanroom upgrades and extended validation timelines.
- Skilled technician scarcity:Enzymatic process optimization and bloom strength calibration require specialized protein chemistry expertise concentrated among senior rendering engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Gelatin Market |
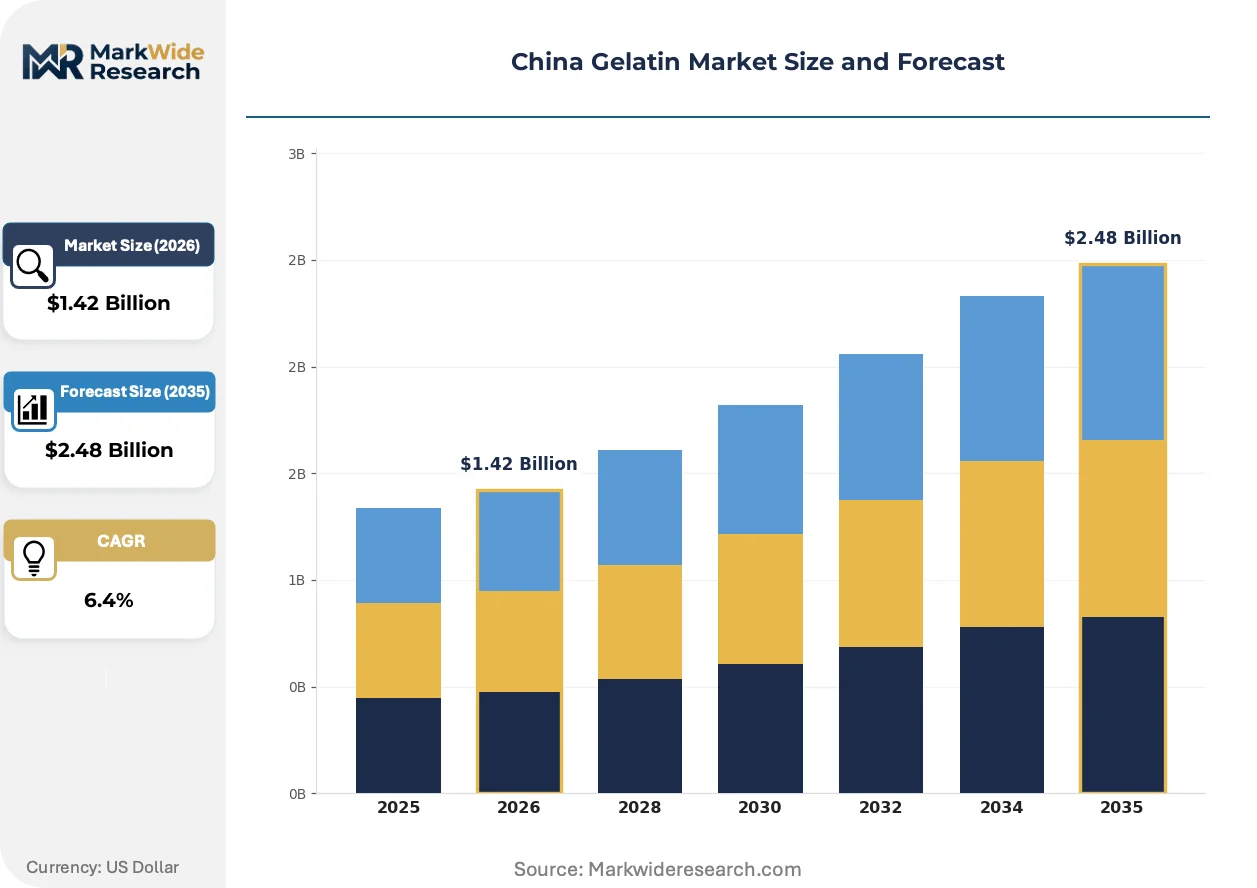
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Gelatin, Pigskin Gelatin, Hide Gelatin, Fish Gelatin Application: Pharmaceuticals, Food & Beverage, Photography, Cosmetics Form: Powder, Granules, Sheets, Capsules End User Industry: Pharmaceutical Companies, Confectionery Manufacturers, Cosmetic Firms, Printing Companies |
| Companies Covered | Xiamen Hyfine Gelatin, Tianjin Hwashin Biotechnology, Lanpu Gelatin, Xiamen Huaxuan Gelatin, Foodmate, Hangzhou Qunli Gelatin Chemical, Henan Boom Gelatin, Hebei Haodong Biological Technology, Luohe Wulong Gelatin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Gelatin Market Strategic Shifts
Clean-label extraction methods and religious-compliant sourcing are redrawing competitive boundaries between conventional processors and specialized alternatives. Technology migration and regulatory digitization are compressing traditional qualification cycles.
Enzyme-refined gelatin production is migrating from niche pharmaceutical applications toward broader food and nutraceutical adoption. High-purity grades now serve probiotic encapsulation and functional gummy manufacturing. This technology is migrating from premium positioning toward mid-tier volume contracts as equipment costs decline and yield consistency improves.
MEE dual carbon goals are forcing rendering facilities to retrofit anaerobic digesters and heat recovery systems before license renewal deadlines. Carbon intensity metrics now factor into pharmaceutical procurement scoring. Shandong processors are responding fastest due to concentrated environmental enforcement and earlier compliance deadlines.
Pharmaceutical buyers are consolidating supplier panels around certified domestic processors with integrated traceability. Multi-source qualification strategies are contracting to dual-source or single-source arrangements with backward-integrated operators. This concentration is most visible among capsule manufacturers supplying government tender contracts.
China Gelatin Market Segmentation
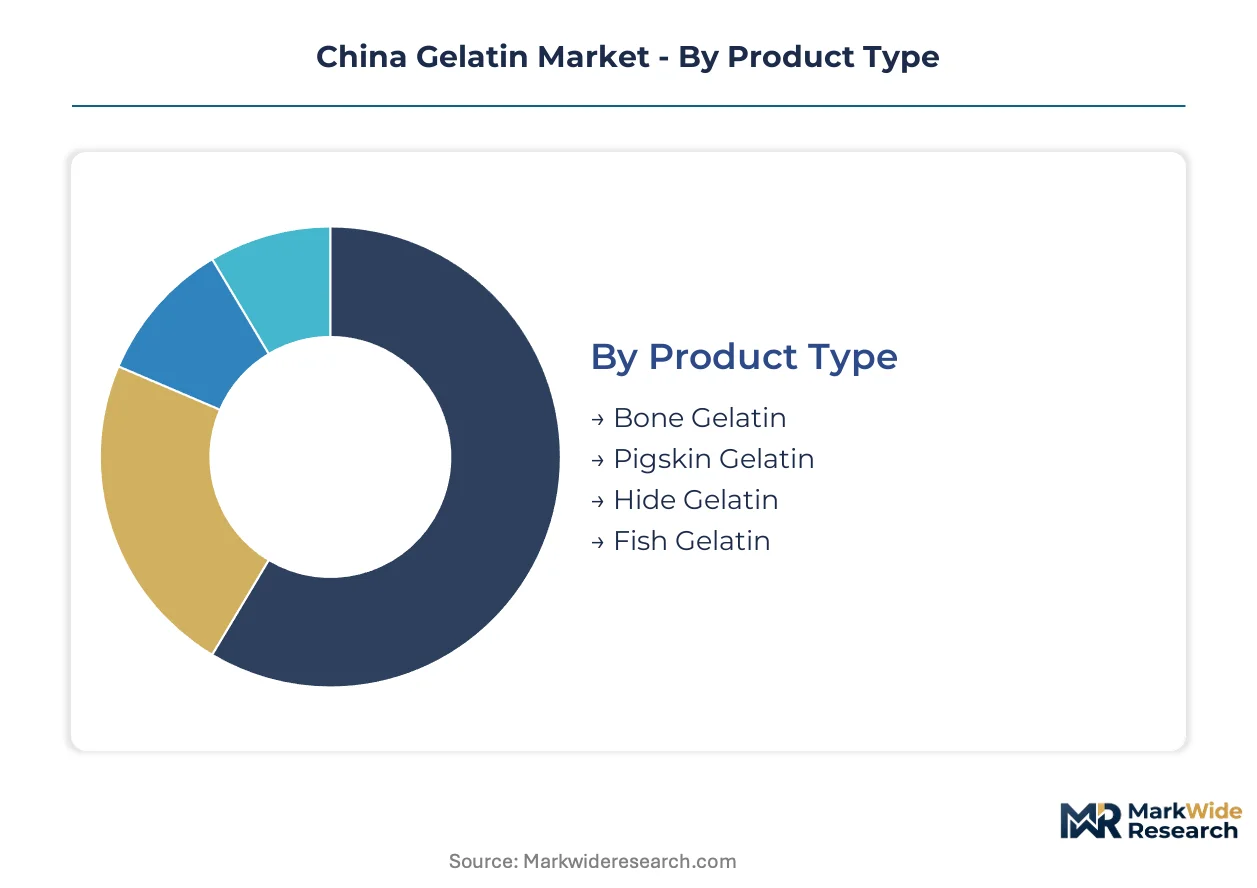
Segmentation in the China gelatin market tracks divergent quality standards, extraction technologies, and regulatory pathways across pharmaceutical and food-grade supply chains. Each dimension captures distinct procurement behaviors, certification requirements, and margin structures that reshape supplier positioning.
Product Type:
Cost tier stratification separates commodity-grade renderings from premium pharmaceutical certifications, with extraction yield and raw material availability driving tier boundaries.
- Pigskin Gelatin:Acid-extracted protein from porcine dermis delivers bloom strengths of 150-250g with superior gel clarity. Pharmaceutical capsule manufacturers in Jiangsu and Zhejiang provinces concentrate procurement here due to NMPA monograph alignment and Shandong-Henan supply proximity.
- Fish Gelatin:Enzyme-hydrolyzed collagen from cold-water species yields non-mammalian grades for halal and kosher pharmaceutical formulations. Demand from export-oriented capsule producers is climbing fastest as religious compliance premiums widen margin pools.
- Bone Gelatin:Bovine-derived collagen faces structural compression from BSE-related import restrictions and domestic consumer preference shifts toward porcine alternatives.
- Hide Gelatin:Cattle hide processing delivers lower-bloom grades for industrial and photographic applications with reduced pharmaceutical penetration.
Pigskin gelatin holds installed capacity. Fish gelatin is rotating up the share rankings.
Application:
Application scope tracks divergent regulatory intensity, with pharmaceutical pathways demanding GMP facility certification and food channels prioritizing cost efficiency.
- Pharmaceuticals:Hard and soft capsule excipients require NMPA-registered facilities with validated cleanroom environments and documented bloom strength consistency. Domestic generic drug manufacturers are expanding capsule production lines under government tender contracts.
- Food & Beverage:Confectionery binding, dairy stabilization, and dessert gelling operate under SAMR food safety audits with lower certification barriers but intensifying traceability mandates.
- Photography:Silver halide emulsion binding represents a contracting niche as digital imaging displaces traditional film chemistry demand.
- Cosmetics:Film-forming and moisture-retention properties serve skincare formulations with moderate volume but premium pricing relative to food grades.
Pharmaceuticals commands certification infrastructure. Food & Beverage is gaining volume leverage through scale procurement.
Form:
Form factor selection correlates with downstream processing automation and dissolution rate requirements across capsule manufacturing and food production lines.
- Powder:Spray-dried gelatin with controlled particle size distribution enables rapid hydration in high-speed capsule filling equipment and industrial food batching.
- Capsules:Pre-formed hard and soft gelatin shells eliminate downstream forming steps for pharmaceutical manufacturers with validated supply agreements.
- Granules:Agglomerated particles reduce dust generation during handling but require longer dissolution cycles in confectionery applications.
- Sheets:Leaf gelatin serves artisanal confectionery and specialized culinary applications with limited industrial scale.
Powder maintains production dominance. Capsules is climbing the value chain through integrated shell-forming partnerships.
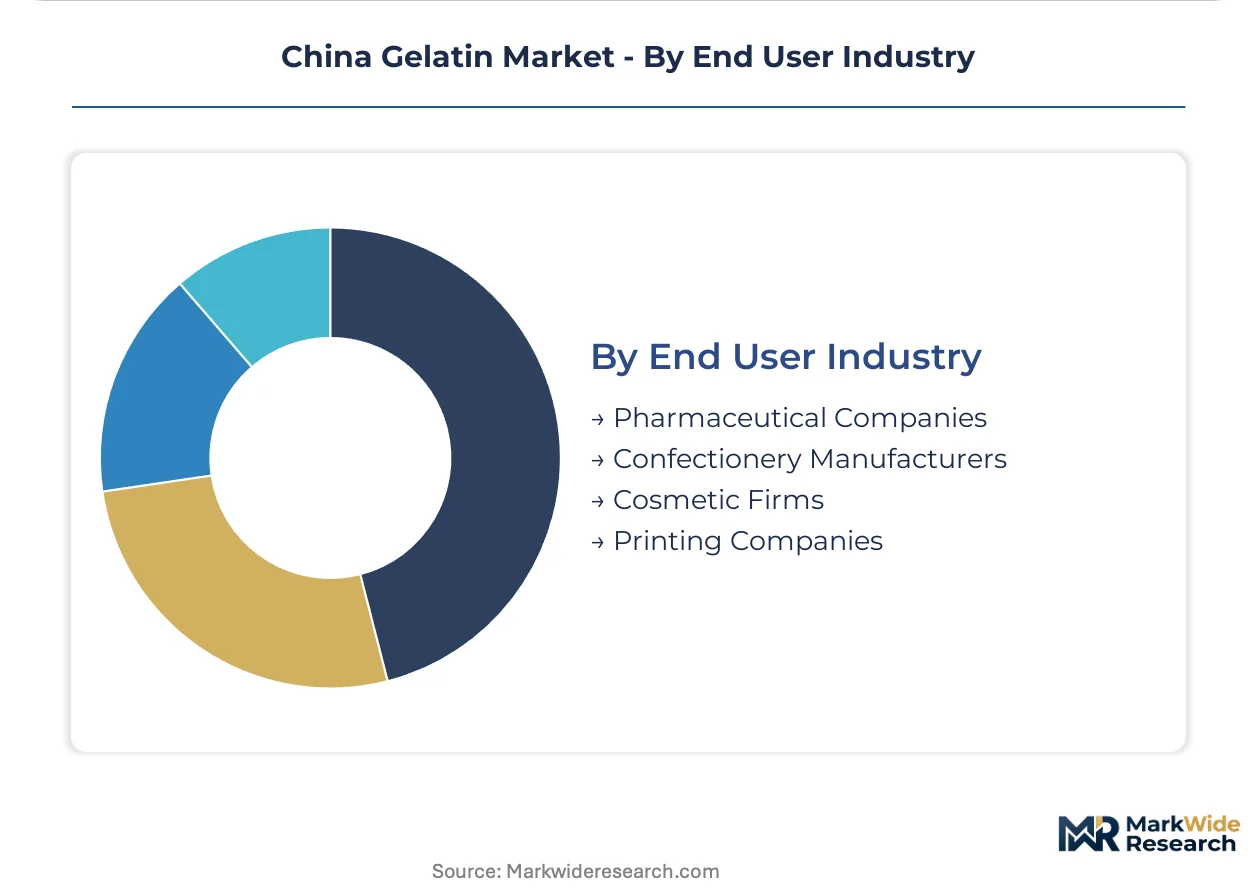
End User Industry:
Customer type segmentation reveals procurement consolidation patterns, with integrated operators capturing volume through backward-linked raw material control.
- Pharmaceutical Companies:Hard and soft capsule producers drive pharmaceutical-grade demand with NMPA excipient registration requirements and dual-source qualification strategies contracting toward single-source arrangements with certified domestic processors.
- Confectionery Manufacturers:Gummy and marshmallow producers prioritize bloom strength consistency and cost efficiency over certification intensity, sourcing through distributor networks with limited direct processor relationships.
- Cosmetic Firms:Skincare and haircare formulators seek film-forming grades with specific viscosity profiles, representing fragmented demand with premium pricing tolerance.
- Printing Companies:Microcapsule encapsulation for carbonless copy paper constitutes a declining industrial segment as digital documentation reduces paper-based transaction volumes.
Pharmaceutical Companies anchor certified capacity. Confectionery Manufacturers is expanding procurement scale through consolidated buying cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's gelatin exports flow primarily toward Southeast Asian pharmaceutical manufacturers and Middle Eastern halal-certified processors, with Shandong and Henan provinces anchoring domestic supply corridors. Trade volumes track NMPA certification tiers, with GMP-registered facilities capturing premium export pricing. Provincial environmental enforcement timelines are compressing regional capacity distribution.
Shandong Province
Hard capsule manufacturers in Jinan and Qingdao drive pharmaceutical-grade procurement, sourcing acid-extracted pigskin gelatin with bloom strengths above 200g. MEE dual carbon deadlines are accelerating anaerobic digester retrofits in rendering clusters near Weifang. Linyi's integrated pork processing corridor now hosts three NMPA-registered facilities completing wastewater treatment upgrades ahead of license renewals.
Henan Province
Zhengzhou-based drug formulators are expanding soft capsule lines under government tender contracts, pulling enzyme-refined gelatin volumes northward from Shandong suppliers. SAMR traceability mandates are forcing documentation system investments across Zhoukou rendering operations. The Nanyang pigskin collection network is consolidating under three processor groups with captive raw material sourcing.
Jiangsu Province
Suzhou and Taizhou pharmaceutical parks house capsule manufacturers qualifying single-source arrangements with certified gelatin suppliers. NMPA excipient registration pathways are extending validation timelines for new facility entrants. Yancheng's emerging rendering zone is attracting processors seeking distance from Shandong-Henan environmental enforcement density.
Zhejiang Province
Hangzhou nutraceutical gummy producers are migrating toward fish gelatin alternatives for export-compliant formulations. SAMR food safety audits are intensifying batch documentation requirements across Jiaxing confectionery supply chains. Ningbo's cold-chain logistics infrastructure is enabling fish gelatin import processing for re-export to Southeast Asian markets.
Guangdong Province
Shenzhen and Guangzhou cosmetic formulators seek film-forming grades with specific viscosity profiles for skincare applications. GB standards for edible gelatin are tightening heavy metal testing protocols at Zhuhai import inspection points. The Pearl River Delta's limited rendering base forces reliance on northern provincial supply with rail-freight cost premiums.
China Gelatin Market Competitive Environment
On the supply side, the industry is consolidating around backward-integrated processors with captive pigskin sourcing and NMPA pharmaceutical registration. The vendor base stratifies into three tiers: large-scale renderers with multi-provincial collection networks, mid-cap specialists leveraging enzymatic extraction for premium grades, and regional commodity suppliers serving food channels. Dominant competitive moves include carbon retrofit completion ahead of MEE deadlines and traceability system deployment to satisfy SAMR documentation mandates.
Among Shandong and Tianjin-based processors, Xiamen Hyfine Gelatin, Tianjin Hwashin Biotechnology, and Lanpu Gelatin occupy positions spanning the specialization spectrum. Xiamen Hyfine Gelatin exemplifies the enzymatic-refinement archetype targeting pharmaceutical purity tiers. Tianjin Hwashin Biotechnology represents backward-integrated sourcing models with upstream control over raw material flows. Lanpu Gelatin anchors the non-mammalian alternative vector through fish gelatin production for religious-compliant export channels. These three patterns illustrate how competitive positioning is diverging along technology, integration, and certification axes.
| Leading Market Players |
|---|
| Xiamen Hyfine Gelatin |
| Tianjin Hwashin Biotechnology |
| Lanpu Gelatin |
| Xiamen Huaxuan Gelatin |
| Foodmate |
| Hangzhou Qunli Gelatin Chemical |
| Henan Boom Gelatin |
| Hebei Haodong Biological Technology |
| Luohe Wulong Gelatin |
| Others |
Value Chain & Pricing Dynamics
NMPA pharmaceutical excipient registration bottlenecks compress supplier qualification timelines while concentrating procurement power among certified domestic processors, widening spreads between GMP-registered pharmaceutical grades and commodity food-tier gelatin while reshaping logistics networks around Shandong-Henan rendering clusters.
Pricing Analysis
Enzymatic hydrolysis technology commands premium positioning over acid-extracted alternatives, with three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels. Certification intensity and bloom strength consistency drive differentiation, with NMPA-registered facilities capturing margin premiums from capsule manufacturers. Cost compression in food-grade tiers intensifies because rendering energy expenses rise under MEE dual carbon compliance deadlines. Confectionery manufacturers exhibit highest price sensitivity, while pharmaceutical capsule producers prioritize supply security over unit cost.
Supply Chain Analysis
Extended payment terms from pharmaceutical capsule manufacturers strain working capital for mid-cap rendering operations without captive raw material sourcing. Supply concentrates in China, with limited qualified import alternatives from India and Southeast Asia due to religious compliance constraints. Raw material flows hinge on pigskin collection networks, enzymatic processing inputs, and pharmaceutical-grade filtration media. Single-source vulnerability escalates as procurement panels consolidate around backward-integrated operators with NMPA registration. Distribution runs through direct processor relationships for pharmaceutical tiers and distributor networks for food applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis adoption represents a high-growth disruption, with NMPA quality standard tightening creating structural separation between certified and uncertified supply tiers.
For Market Incumbents: Build regulatory certification moats through NMPA pharmaceutical excipient registration completion ahead of license renewal deadlines. Secure captive pigskin sourcing through collection network consolidation in Shandong and Henan to defend against raw material cost volatility. Deepen backward integration into rendering operations with anaerobic digester retrofits satisfying MEE carbon compliance mandates. For New Entrants and Emerging Players: Fish gelatin specialization for halal and kosher export channels represents the most penetrable entry point, with pharmaceutical buyers actively qualifying non-mammalian alternatives. Target Zhejiang nutraceutical gummy producers migrating toward religious-compliant formulations for Southeast Asian re-export. Partner with Ningbo cold-chain logistics operators to establish import-processing capabilities for cold-water species raw materials. For Investors and Strategic Acquirers: NMPA dual carbon compliance deadlines reshape the acquisition landscape, favoring targets with completed wastewater treatment upgrades and validated cleanroom infrastructure. Prioritize backward-integrated processors with captive raw material control and blockchain-enabled traceability systems over commodity-grade operators facing margin compression. Monitor SAMR enforcement intensity as the signal indicating regulatory acceleration or moderation.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Upgrade | Xiamen Hyfine Gelatin's pharmaceutical-grade pathway demonstrates premium tier access through cleaner extraction yields. |
| Backward Integration | Tianjin Hwashin Biotechnology's captive pigskin sourcing insulates margin structure from raw material cost volatility. |
| Carbon Retrofit Completion | Shandong processors with anaerobic digester installations secure license renewals ahead of MEE enforcement deadlines. |
| Fish Gelatin Specialization | Lanpu Gelatin's halal and kosher certification opens export channels to Middle Eastern pharmaceutical manufacturers. |
| Traceability System Deployment | Blockchain-enabled batch tracking satisfies SAMR documentation mandates for government tender contract eligibility. |
Study Parameters
A spread of perspectives from rendering plant managers, pharmaceutical procurement leads at capsule manufacturers, NMPA regulatory affairs specialists, and SAMR food safety auditors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through NMPA excipient registration databases, MEE environmental compliance filings, customs trade records, and GB standards documentation. Bottom-up capacity assessments across Shandong and Henan rendering clusters were triangulated against top-down pharmaceutical capsule production forecasts.
Demand-supply balance modeling tracked gelatin consumption by pharmaceutical capsule manufacturers, confectionery producers, and cosmetic formulators against installed rendering capacity and raw material collection network throughput across the projection horizon. Segmentation dimensions included product type, application scope, form factor, and end-user industry procurement behavior. CAGRs were derived from volume trajectory analysis incorporating NMPA registration pathway timelines and MEE compliance deadline phasing. Industry-specific inputs captured enzymatic hydrolysis yield improvements and fish gelatin import processing capacity expansion.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, pork processing byproduct availability, or pharmaceutical export demand would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology migration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Potato Protein Market
Ingredients
Oyster Peptide Market
Ingredients
Hen Egg White Protein Market
Ingredients
Edible Animal Fat Market
Ingredients
Canola Meal Market
Ingredients
Specialty Flours Market
Ingredients
Hydrolyzed Egg Market
Ingredients
High Protein Flour Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Moringa Ingredients Market
Ingredients
Fonio Flour Market
Ingredients
Olive Leaf Extract Market
Ingredients
South America Spirulina Extract Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market