
 Meat Ingredients Market | 2026-2036
Meat Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Ingredients Market Outlook
Ingredient formulation margins is narrowing as commodity meat processors internalize basic blending capabilities. Kerry Group PLC leverages its integrated taste and nutrition platforms to sustain premium positioning in European protein blends. DuPont anchors North American supply through its specialty food ingredient divisions, while WIBERG GmbH competes on precision flavor systems for cured meat applications.
Meat ingredients comprise functional additives, extracts, and protein systems used to modify texture, enhance flavor, extend shelf life, or boost nutritional profiles in processed meat products; typical formulations incorporate hydrolyzed proteins at concentrations between five and fifteen percent to achieve desired water-binding and umami characteristics. Protein blends occupy the largest margin pool due to their dual role in cost reduction and label-friendly positioning, while flavor enhancers represent the fastest-expanding category as sodium-reduction mandates intensify across major consuming regions. Textured proteins in granule form are maturing in Western Europe, whereas concentrate formats gain traction in Asian food processing channels.
EU REACH and EFSA frameworks restrict certain synthetic flavor precursors, compelling reformulation toward yeast-derived and botanical alternatives; China's SAMR enforces GB standards on meat additive maximum limits, directly shaping import specifications for foreign suppliers. FDA and USDA FSIS labeling rules in the United States mandate disclosure of cultured and plant-derived protein content, altering how ingredient portfolios are marketed to American processors. Stakeholders must monitor divergence between EU Green Deal sustainability criteria and emerging market enforcement capacity to calibrate regional product registration strategies.
Market Dynamics
Clean-label protein blend adoption is compressing margins for commodity ingredient suppliers as Brazilian and German processors internalize basic formulation capabilities and source directly from specialized hydrolysate manufacturers.
Growth Catalysts
- EU REACH flavor precursor restrictions:Synthetic additive bans under ECHA frameworks are accelerating yeast-extract and botanical umami system demand across cured meat applications.
- São Paulo meatpacking cluster scale:Brazil's concentrated slaughterhouse operations generate procurement volumes that justify dedicated ingredient production facilities and technical service teams.
- Hydrolyzed protein functionality:Water-binding and texture-modification properties at 5-15% inclusion rates enable cost-efficient reformulation without clean-label penalties.
Market Restraints
- Input cost volatility:Animal protein feedstock prices fluctuate with grain markets and livestock cycles, compressing hydrolysate producer margins unpredictably.
- Supply concentration risk:Specialty enzyme and extract production clusters in Western Europe create single-source dependencies for precision flavor systems.
- Regulatory friction:China's SAMR GB standard updates on additive maximum limits force reformulation cycles that delay product registration timelines.
Strategic Opportunities
- Underpenetrated Asian concentrate formats:Textured protein concentrate adoption in Chinese and Southeast Asian food processing channels lags Western granule penetration by several years.
- EU Green Deal sustainability criteria:Carbon-footprint disclosure mandates create premium positioning for fermentation-derived and upcycled protein ingredients.
- Sodium-reduction regulatory tailwinds:Mandatory salt limits in processed foods across multiple jurisdictions intensify demand for potassium chloride and yeast-extract flavor enhancers.
Industry Challenges
- Formulation chemist scarcity:Clean-label protein blend development requires rare expertise in both sensory science and regulatory compliance across multiple jurisdictions.
- Dual certification timelines:Simultaneous EU organic and USDA organic approvals extend product launch cycles by 18-24 months for export-oriented suppliers.
- Legacy equipment incompatibility:Existing meat processing lines require retrofitting to handle higher-viscosity protein concentrate slurries without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Ingredients Market |
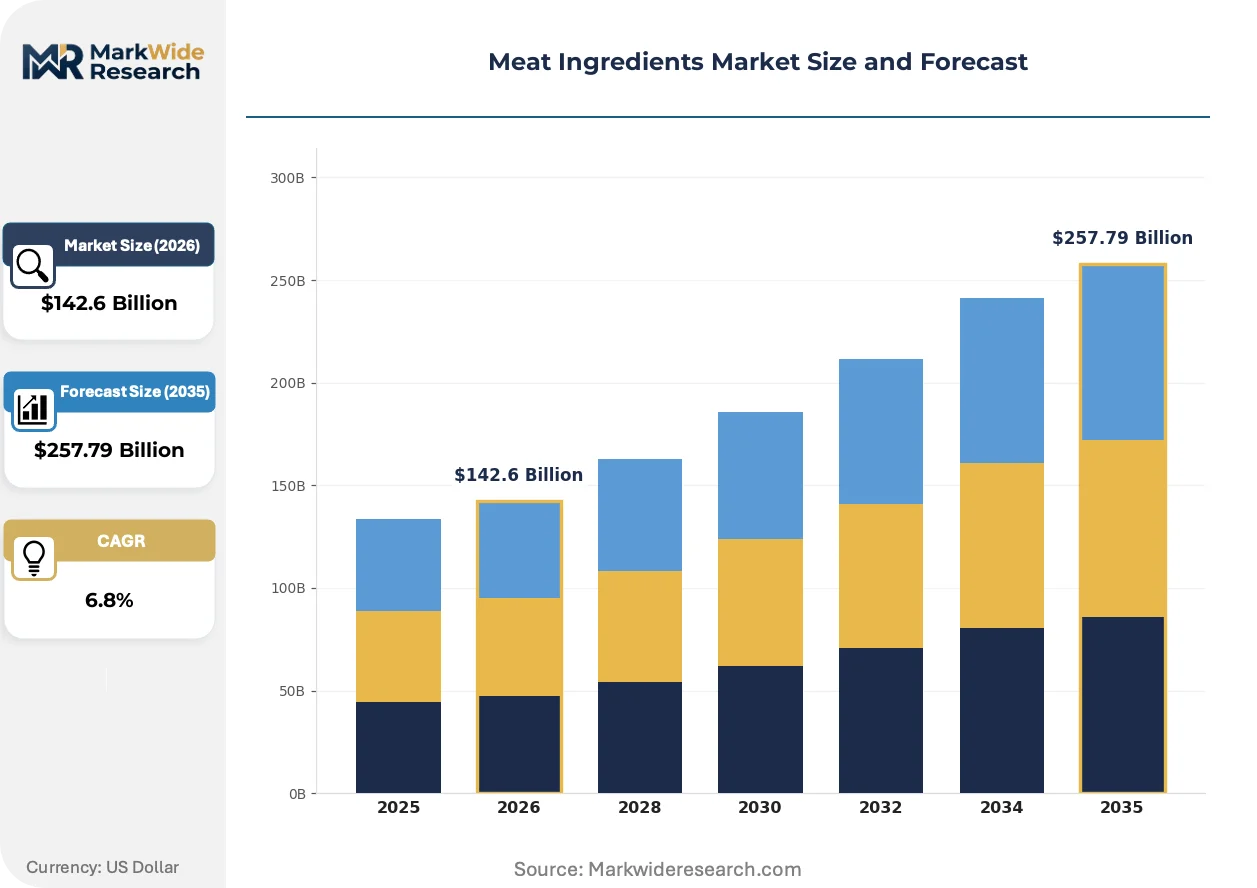
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $257.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Extracts, Protein Blends, Flavor Enhancers, Textured Proteins Form: Powders, Granules, Concentrates, Cubes End User: Food Processing, Household Consumers, Restaurants, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Kerry Group PLC, DuPont, WIBERG GmbH, Proliant Meat Ingredients, Wenda Ingredients, Ohly GmbH, Firmenich SA, Koninklijke DSM NV, Tate and Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Ingredients Market Strategic Shifts
Digital formulation platforms and precision fermentation are converging to reshape how meat processors specify, prototype, and scale ingredient systems across regional regulatory environments.
AI-driven formulation software is digitizing the traditional trial-and-error approach to protein blend optimization. Mid-sized European processors now iterate sensory profiles in silico before bench-scale validation. This compression of R&D cycles is reducing time-to-market for clean-label reformulations from months to weeks.
EFSA's evolving stance on novel protein safety assessments is tightening data requirements for cell-culture and precision-fermentation ingredients. Ingredient suppliers must now submit comprehensive allergenicity and digestibility dossiers before market authorization. The regulatory burden falls heaviest on startups lacking established toxicology departments, favoring incumbent players with dedicated regulatory affairs infrastructure.
Consolidated procurement by multinational meatpackers is displacing fragmented distributor networks across ingredient categories. Direct supplier relationships now dominate volume purchasing for hydrolyzed proteins and flavor systems in Brazil and Germany. This channel compression is most visible in São Paulo state, where JBS and BRF centralize ingredient specification decisions at headquarters level.
Meat Ingredients Market Segmentation
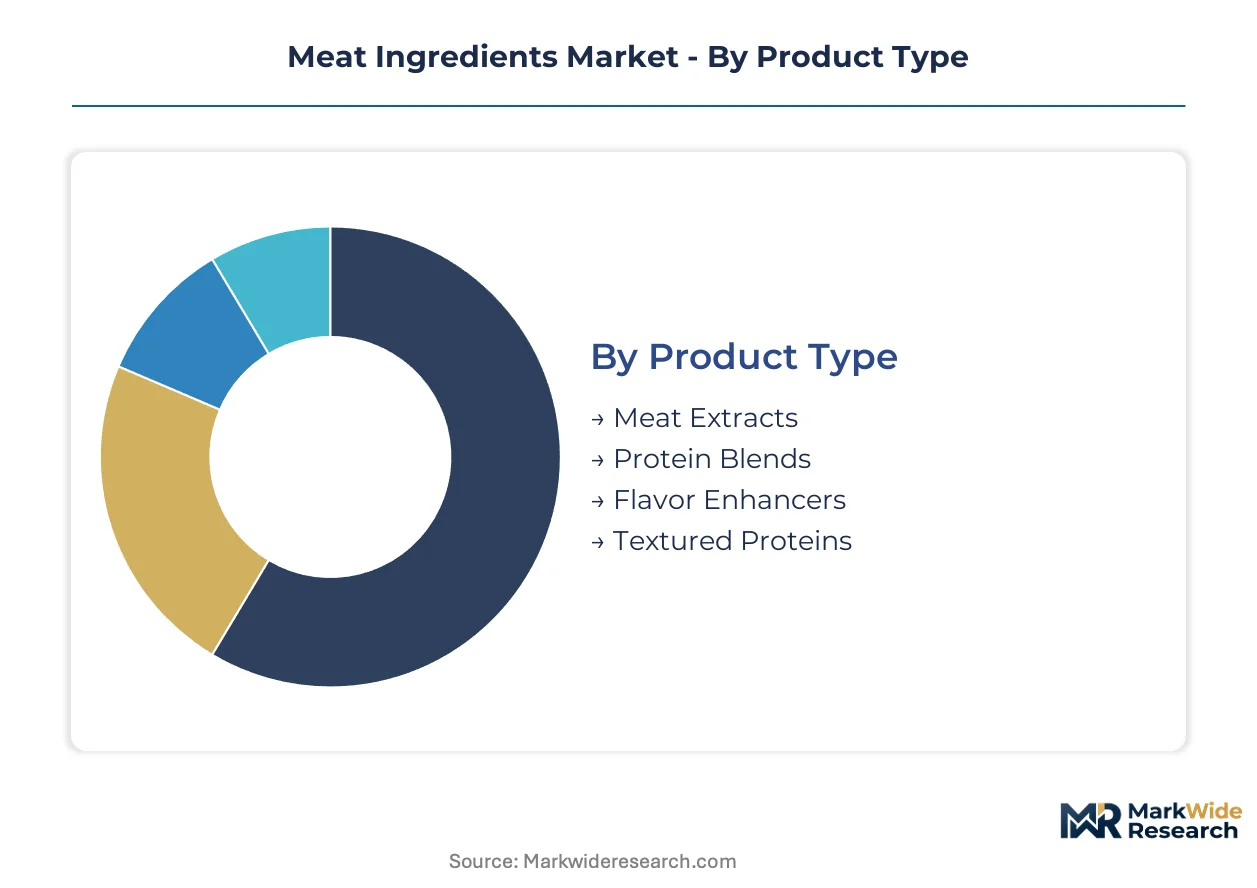
Segmentation in meat ingredients reveals how procurement cycles, formulation complexity, and regulatory exposure vary across product categories. Understanding these distinctions enables suppliers to align R&D investment with the velocity of customer decision-making.
Product Type:
Product categories exhibit starkly different inventory velocities, with commodity hydrolysates turning monthly while precision flavor systems sit on 90-day production schedules.
- Protein Blends:Composite formulations combining animal and plant hydrolysates at 5-15% inclusion rates deliver water-binding functionality and cost optimization. São Paulo's meatpacking clusters source these at scale for processed sausage and restructured meat applications, though internalization by JBS and BRF compresses third-party margins.
- Flavor Enhancers:Yeast extracts, nucleotides, and botanical umami systems replace sodium and synthetic precursors under EU REACH restrictions. Sodium-reduction mandates across Germany, Brazil, and China accelerate procurement cycles for potassium chloride and fermented flavor systems in cured meat formulations.
- Meat Extracts:Concentrated broths and autolyzed tissue preparations supply foundational savory notes to bouillon and sauce bases.
- Textured Proteins:Granule formats dominate Western European extrusion applications while concentrate slurries penetrate Asian food processing channels.
Protein blends anchor the volume base while flavor enhancers gain share at the steepest rate.
Form:
Physical format selection tracks equipment compatibility and regional processing infrastructure maturity.
- Powders:Spray-dried hydrolysates and extract carriers offer longest shelf stability and lowest transport cost per unit protein. German processors favor these for dry-cured sausage seasoning matrices where moisture control is critical.
- Concentrates:High-viscosity protein slurries enable clean-label reformulation without powder dusting hazards. Chinese food manufacturers adopt these for meatball and surimi applications, though legacy equipment retrofit requirements slow penetration.
- Granules:Agglomerated particles improve dispersion in high-shear mixing environments common to European extrusion lines.
- Cubes:Compressed extract formats serve household and small-scale foodservice channels in Brazil and Southeast Asia.
Powders dominate existing installed base while concentrates expand most quickly in Asian greenfield facilities.
End User:
Customer scale determines technical service intensity and contract structure complexity.
- Food Processing:Industrial meat manufacturers specify ingredients against functional targets for yield, texture, and label claims. Brazilian and German processors centralize procurement decisions at headquarters level, demanding integrated taste-nutrition platforms and regulatory dossiers for EU and Chinese export compliance.
- Restaurants:Chain operators and centralized kitchens source standardized flavor systems for menu consistency across locations.
- Catering Services:Volume foodservice operations prioritize cost-stable supply agreements over formulation innovation.
- Household Consumers:Retail bouillon and seasoning purchases respond to brand recognition and shelf placement rather than technical specification.
Food processing commands the revenue concentration while restaurants present the steepest expansion trajectory for customized flavor systems.
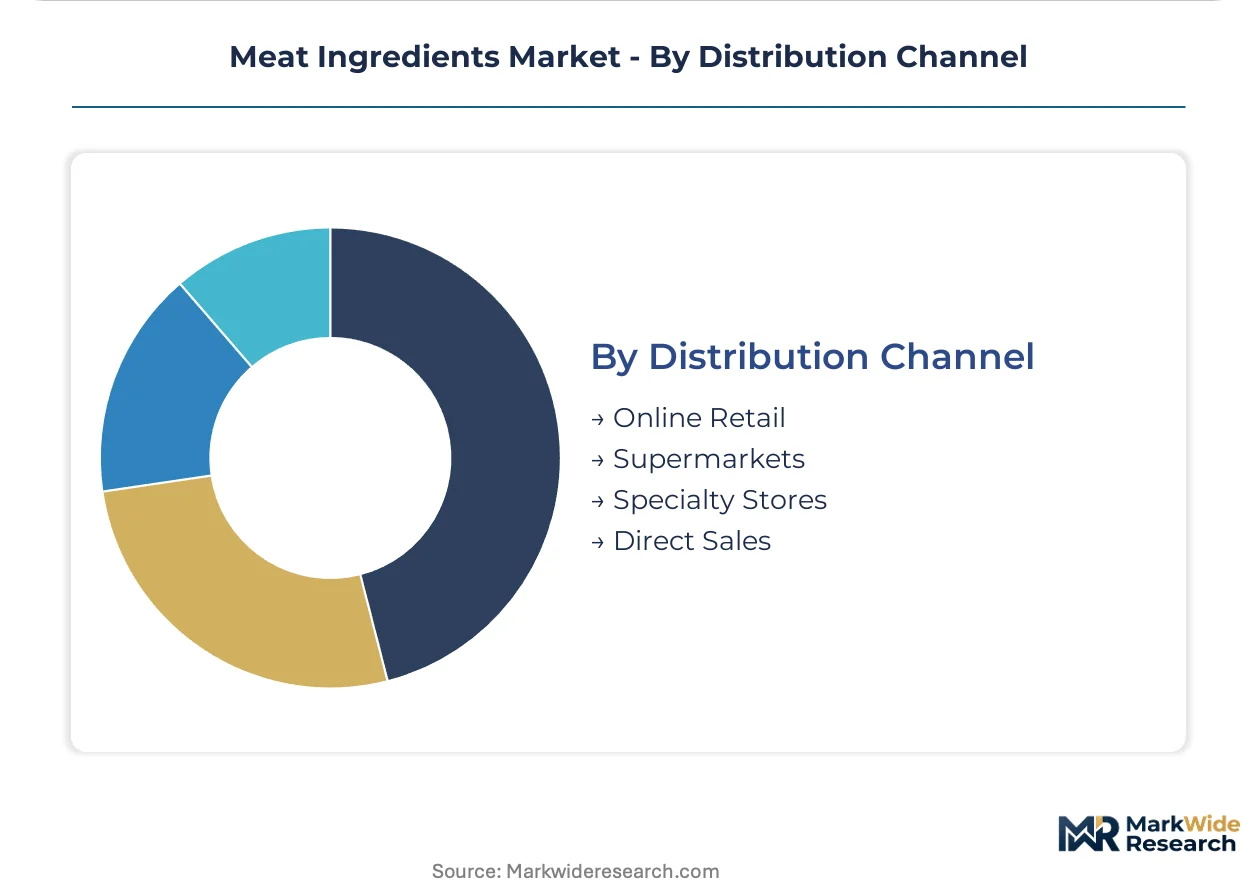
Distribution Channel:
Channel selection reflects order size, technical support requirements, and geographic market development.
- Direct Sales:Technical ingredient suppliers maintain dedicated account teams for São Paulo and German meatpacking headquarters, handling specification negotiations and joint formulation development. This channel captures the highest-margin precision systems.
- Supermarkets:Mass retail moves packaged consumer-facing products with established brand equity and straightforward label claims.
- Specialty Stores:Gourmet and ethnic food retailers distribute premium extracts and artisan curing ingredients.
- Online Retail:E-commerce penetration lags for industrial-grade ingredients due to technical consultation requirements, though small-batch processors increasingly source samples digitally.
Direct sales locks in the volume base while online channels climb fastest for sample and small-order fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian buyers demonstrate the highest price elasticity as commodity processors internalize basic blending, while German and Chinese purchasers absorb premium pricing for regulatory-compliant specialty systems.
Germany
Clean-label protein blend demand from cured meat manufacturers drives ingredient procurement intensity. EFSA and REACH frameworks restrict synthetic flavor precursors, compelling yeast-extract and botanical umami adoption. North Rhine-Westphalia's processing corridor hosts WIBERG GmbH and concentrated sausage production clusters sourcing precision flavor systems.
Brazil
São Paulo state's meatpacking concentration generates procurement volumes justifying dedicated ingredient facilities. ANVISA enforcement of additive maximum limits shapes import specifications for foreign hydrolysate suppliers. JBS and BRF headquarters centralize specification decisions, compressing third-party margins through direct sourcing from specialized manufacturers.
China
Food processing channels adopt protein concentrate slurries for meatball and surimi applications at accelerating rates. SAMR's updated GB standards on meat additive limits force reformulation cycles delaying product registrations. Yangtze River Delta processors retrofit legacy equipment to handle higher-viscosity formulations without throughput degradation.
United States
Processed meat manufacturers specify ingredients against dual FDA and USDA FSIS labeling mandates for cultured and plant-derived protein disclosure. Sodium-reduction tailwinds intensify procurement of potassium chloride and fermented flavor enhancers. Midwest packing corridors concentrate volume purchasing for hydrolyzed protein systems.
Netherlands
Randstad-based ingredient suppliers leverage integrated taste-nutrition platforms to serve export-oriented European processors. EU Green Deal sustainability criteria create premium positioning for fermentation-derived protein ingredients. Dutch formulators specialize in carbon-footprint disclosure-compliant systems for German and Scandinavian export markets.
Meat Ingredients Market Competitive Environment
Integrated taste-nutrition platforms and specialized hydrolysate manufacturers split the market between premium positioning and cost-optimized supply. Consolidated procurement by multinational meatpackers displaces fragmented distributor networks across ingredient categories. Three archetypes dominate: diversified nutrition conglomerates with regulatory dossier capabilities, precision flavor specialists for cured meat applications, and regional hydrolysate producers serving concentrated processing clusters. Competitive moves center on direct supplier relationships with São Paulo and German headquarters and portfolio diversification into yeast-extract and botanical umami systems.
Among Ireland-based nutrition conglomerates, Kerry Group PLC occupies a position exemplifying integrated platform strategies. DuPont anchors North American supply archetypes through specialty food ingredient divisions. Within German precision flavor specialists, WIBERG GmbH represents the regulatory-compliance-focused tier serving cured meat applications. These three entities illustrate how geographic origin and corporate structure map to distinct competitive positioning in a market where formulation chemist scarcity and dual certification timelines favor established regulatory affairs infrastructure.
| Leading Market Players |
|---|
| Kerry Group PLC |
| DuPont |
| WIBERG GmbH |
| Proliant Meat Ingredients |
| Wenda Ingredients |
| Ohly GmbH |
| Firmenich SA |
| Koninklijke DSM NV |
| Tate and Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp barge freight corridors for hydrolyzed protein feedstocks impose cost dynamics that amplify supplier concentration effects in Western Europe while enabling São Paulo processors to extract volume-based price concessions from specialized manufacturers.
Pricing Analysis
Technical service contracts and formulation support agreements generate lifetime value that exceeds base ingredient margins. Three-tier pricing structure across premium, standard, and economy levels separates precision flavor systems with full regulatory dossiers from commodity hydrolysates and generic extracts. Cost compression in standard-tier protein blends is intensifying because Brazilian meatpackers internalize basic formulation capabilities. Commodity processors in São Paulo state exhibit the highest price elasticity, while German cured meat manufacturers absorb premium pricing for EFSA-compliant yeast-extract systems.
Supply Chain Analysis
Animal protein feedstock supply draws from Brazil, Germany, and China's Yangtze River Delta processing clusters. Hydrolyzed proteins, specialty enzymes, and botanical extracts constitute critical input dependencies. Single-source vulnerability concentrates in Western European precision flavor system production. Distribution runs through direct technical sales teams for multinational meatpacker headquarters, supplemented by regional distributors for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated meatpacking headquarters in São Paulo and Germany, where JBS, BRF, and major cured meat manufacturers centralize procurement decisions and compress third-party supplier margins.
For Market Incumbents: Insulate premium positioning by deepening regulatory dossier capabilities for simultaneous EU organic and USDA organic approvals, and anchor capacity in Dutch Randstad fermentation facilities to meet EU Green Deal carbon-footprint disclosure mandates. Emerging precision-fermentation startups threaten specialty protein supply positions. Certification investment represents the critical defensive lever. For New Entrants and Emerging Players: Build out technical service infrastructure for protein concentrate slurry applications in China's Yangtze River Delta, where legacy equipment retrofit requirements have slowed penetration versus Western granule adoption. Asian concentrate formats remain the most penetrable white space. Direct sales teams co-located with food processing clusters offer the strongest go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified nutrition conglomerates seeking to divest non-core specialty ingredient divisions with stranded regulatory affairs infrastructure. Long-term viability over the coming decade hinges on fermentation-derived protein positioning and dual EU-US organic certification capabilities. Watch for ANVISA enforcement intensity in Brazil as an inflection signal for import specification tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Fermentation-derived protein systems command premium positioning under EU Green Deal sustainability criteria. |
| Dual Organic Certification Investment | Simultaneous EU and USDA organic approvals unlock export-oriented German and Dutch processor contracts. |
| Direct Technical Sales Expansion | Dedicated account teams at São Paulo and German headquarters capture high-margin precision flavor specifications. |
| Yeast-Extract Portfolio Diversification | EFSA flavor precursor restrictions accelerate demand for botanical umami alternatives in cured meat applications. |
| Asian Concentrate Format Development | High-viscosity protein slurries address equipment retrofit barriers in Chinese meatball and surimi processing channels. |
Study Parameters
Cross-validation between regulatory filing analysis and trade flow data anchors the qualitative findings in this study. Primary interviews with formulation chemists, meatpacker procurement directors, regulatory affairs specialists, and specialty enzyme manufacturers were combined with secondary validation from EFSA safety assessments, SAMR GB standard updates, ANVISA additive registrations, and customs hydrolysate trade records. Bottom-up volume modeling and top-down value triangulation were applied throughout.
Calibration against historical protein blend adoption curves and flavor enhancer procurement cycles shaped the analytical framework. Segmentation dimensions modeled include product type, physical form, end-user scale, and distribution channel complexity across the projection horizon. CAGRs were derived from fitted growth curves incorporating sodium-reduction regulatory timelines, clean-label reformulation velocity, and meatpacking consolidation patterns.
Stress conditions across grain market volatility, livestock cycle fluctuations, and regulatory enforcement divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EFSA novel protein assessment timelines and SAMR registration processing speeds. Cross-checking against customs trade volume benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Grass Fed Beef Market
Meat Products
Ham Slicers Market
Meat Products
Organic Pork Market
Meat Products
Animal Protein Market
Meat Products
Shark Meat Market
Meat Products
Oman Poultry Meat Market
Meat Products
Pepperoni Foods Market
Meat Products
Global Poultry Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
Bacon Market
Meat Products
Low Fat Sausage Market
Meat Products
China Processed Meat Market
Meat Products
Canned Pork Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Meat Paste Market
Meat Products
India Animal Protein Market