
 Hen Egg White Protein Market | 2026-2036
Hen Egg White Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Hen Egg White Protein Market Foresight
Buyer concentration in the bakery manufacturing sector is decoupling as artisanal and regional producers fragment procurement across smaller volume contracts. Merck KGaA leverages its pharmaceutical-grade purification infrastructure to supply high-specification egg white proteins for clinical nutrition. Kewpie Corporation anchors Japanese supply chains through backward integration into contracted layer farms. Rose Acre Farms competes on shell-to-powder traceability systems that satisfy North American food safety audits.
Hen egg white protein comprises approximately 90% water and 10% dry matter, with ovalbumin constituting roughly 54% of total protein content, and serves primarily as a foaming agent, gelling agent, and nutritional fortifier across food and biomedical applications. Dried egg white commands the dominant share of margin pools due to extended shelf stability and reduced cold-chain dependency, while hydrolyzed variants represent the fastest-growing product type as sports nutrition formulators seek rapid-absorption amino acid profiles. Liquid egg white retains mature demand from industrial bakery manufacturers operating continuous production lines where hydration control is critical.
The FDA enforces Grade A pasteurization standards under the Egg Products Inspection Act, compelling processors to maintain Salmonella-negative certification for interstate commerce, while the USDA oversees shell egg sourcing traceability through the National Poultry Improvement Plan. In Europe, EFSA allergen labeling mandates under Regulation (EU) No 1169/2011 require explicit egg protein disclosure, shaping reformulation strategies for confectionery exporters. Stakeholders must monitor evolving clean-label certification thresholds and regional divergence in heat-treatment standards to preserve market access across jurisdictions.
Market Dynamics
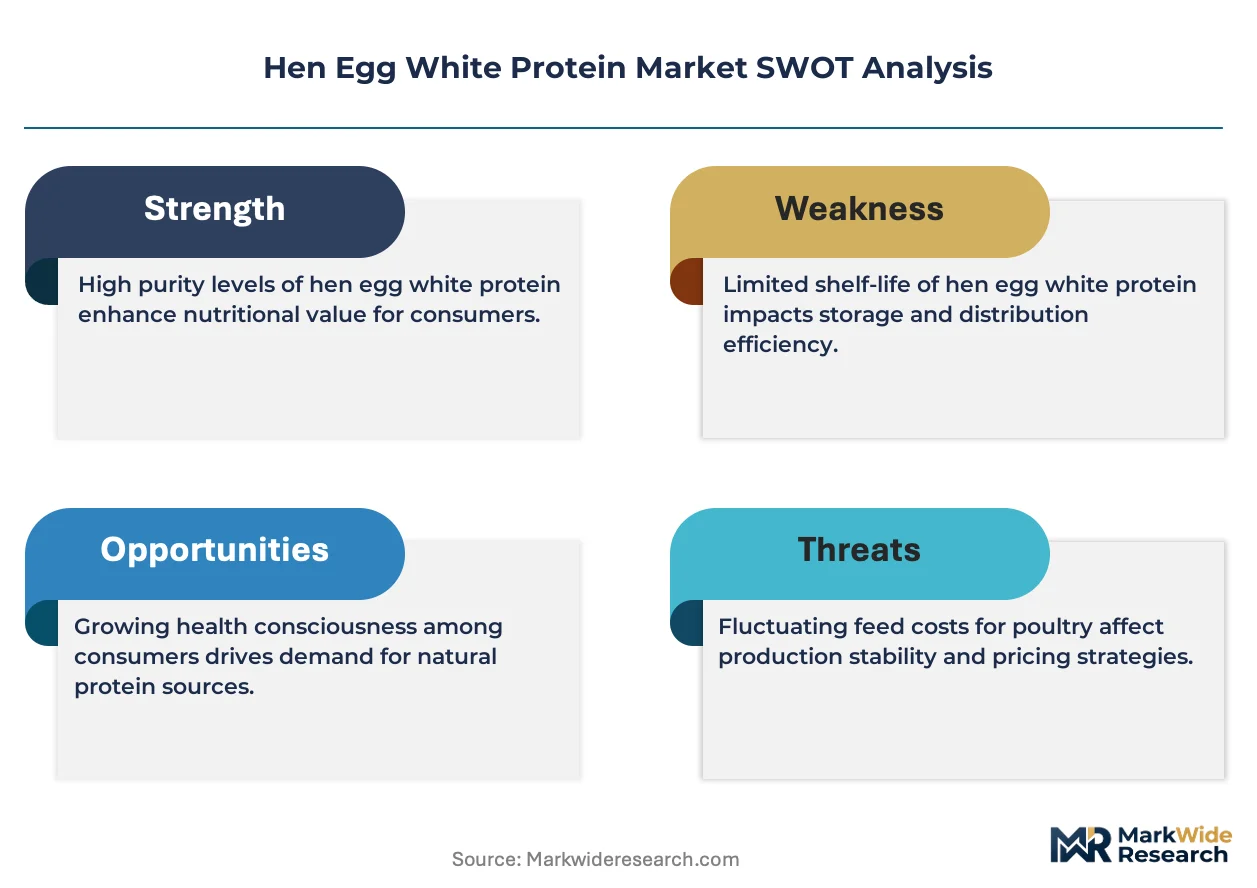
Clean-label certification thresholds are compressing margin structures as bakery manufacturers and sports nutrition brands simultaneously demand higher purity specifications and transparent supply chain documentation. The FDA's updated dietary supplement labeling rules and EFSA allergen mandates are forcing processors to retool purification infrastructure.
Growth Catalysts
- Sports nutrition fortification:Dried egg white isolates are displacing synthetic emulsifiers in protein bar formulations as athletes prioritize whole-food ingredient lists.
- EFSA Regulation (EU) No 1169/2011:Mandatory egg protein disclosure is accelerating reformulation investments by confectionery exporters seeking compliant export certifications.
- German bakery cluster:Artisanal producers in Bavaria and Baden-Württemberg are fragmenting procurement toward regional egg white emulsifier suppliers.
Market Restraints
- Feed cost volatility:Layer farm input expenses for soy and corn meal swing with commodity futures, compressing processor margins on fixed-price contracts.
- Salmonella-negative certification:The FDA's Grade A pasteurization standards under the Egg Products Inspection Act create compliance barriers for small-scale shell-to-powder operators.
- Plant protein substitution:Pea and fava bean isolates are capturing share in vegan bakery applications where foaming functionality is less critical.
Strategic Opportunities
- Clinical nutrition expansion:Pharmaceutical-grade ovalbumin purification for enteral feeding applications remains underpenetrated outside North America and Western Europe.
- Japan's METI biotechnology roadmap:Government incentives for functional food ingredient development are opening R&D partnerships between processors and layer farm cooperatives.
- Direct-to-manufacturer platforms:Digital procurement channels are disintermediating traditional ingredient distributors for mid-volume bakery accounts.
Industry Challenges
- Cross-contamination protocols:Shared production lines between egg and non-egg ingredients require validated cleaning procedures that extend batch turnaround times.
- Traceability system integration:Shell-to-powder documentation must interface with retailer blockchain platforms, forcing legacy ERP upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hen Egg White Protein Market |
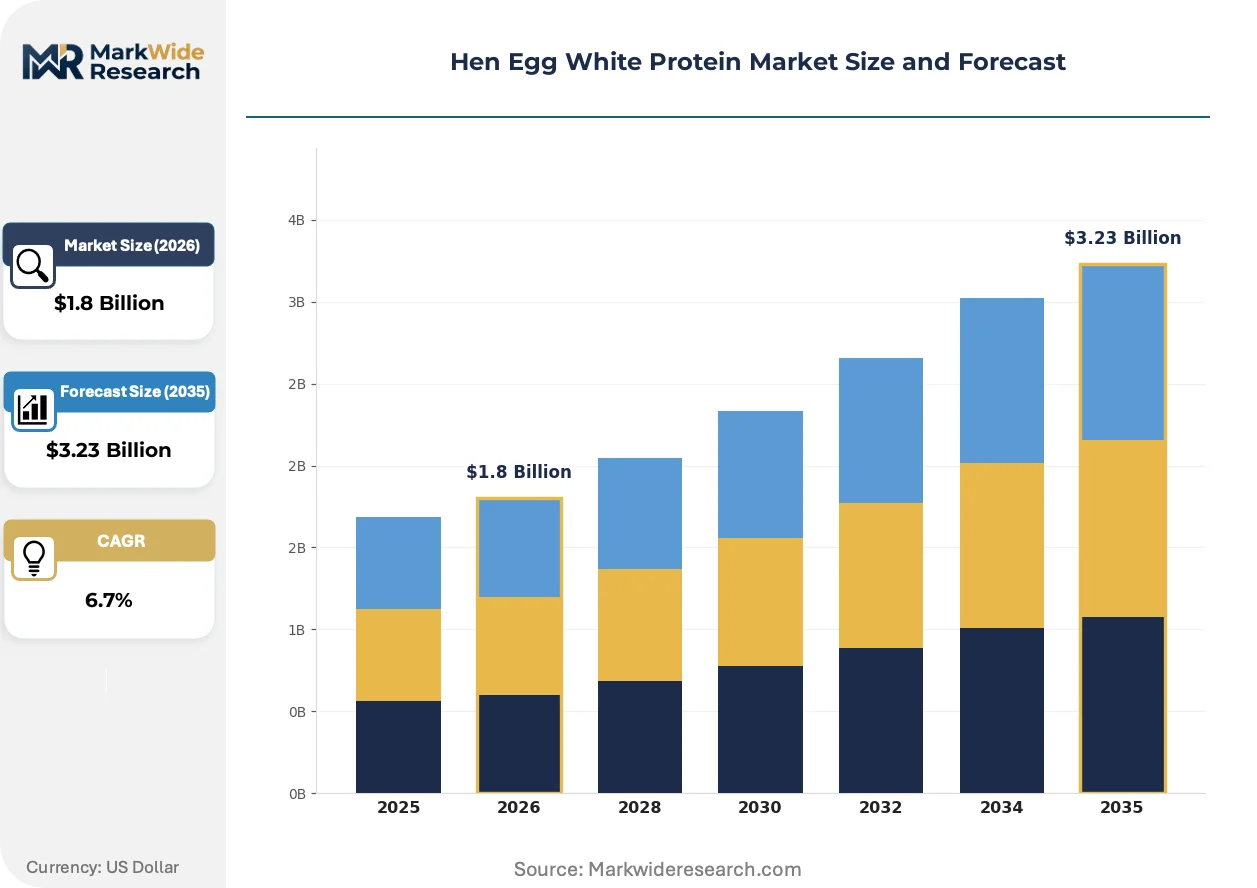
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Egg White, Pasteurized Egg White, Dried Egg White, Liquid Egg White Application: Nutritional Supplements, Bakery Products, Confectionery, Sports Nutrition End User: Food & Beverage Industry, Bakery Manufacturers, Fitness Centers, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Health Stores |
| Companies Covered | Lee BioSolutions, Calzyme, Kewpie Corporation, NOW Health Group, HiMedia Laboratories, Merck KGaA, Rembrandt Enterprises, Rose Acre Farms, Bouwhuis Enthoven, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hen Egg White Protein Market Shifts & Advancements
Membrane filtration and enzymatic hydrolysis are converging to reshape how processors extract and modify egg white proteins for differentiated functional applications. These advances are compressing development cycles for custom ingredient specifications.
Membrane filtration technology is modularizing protein fractionation by enabling processors to isolate specific globulin fractions without heat denaturation. Sports nutrition formulators in Germany and Japan are adopting these cold-processed isolates for rapid-digestion product lines. The technology is modularizing supply chain configurations by allowing regional processors to match pharmaceutical-grade specifications without centralized capital investment.
REACH registration requirements for food-contact processing aids are tightening purity documentation for European egg white protein imports. Manufacturers exporting to the EU must now submit comprehensive substance data sheets for filtration membranes and enzymatic processing aids. The confectionery segment is responding by consolidating supplier qualification programs to reduce audit burden.
Long-term supply agreements with contracted layer farms are displacing spot market purchasing for volume-stable bakery manufacturers. Industrial producers operating continuous production lines in the US Midwest and southern Germany are locking in eighteen-to-twenty-four month contracts with fixed volume tiers. This pattern is most visible among frozen dough manufacturers where hydration consistency demands uninterrupted egg white supply.
Hen Egg White Protein Market Segmentation
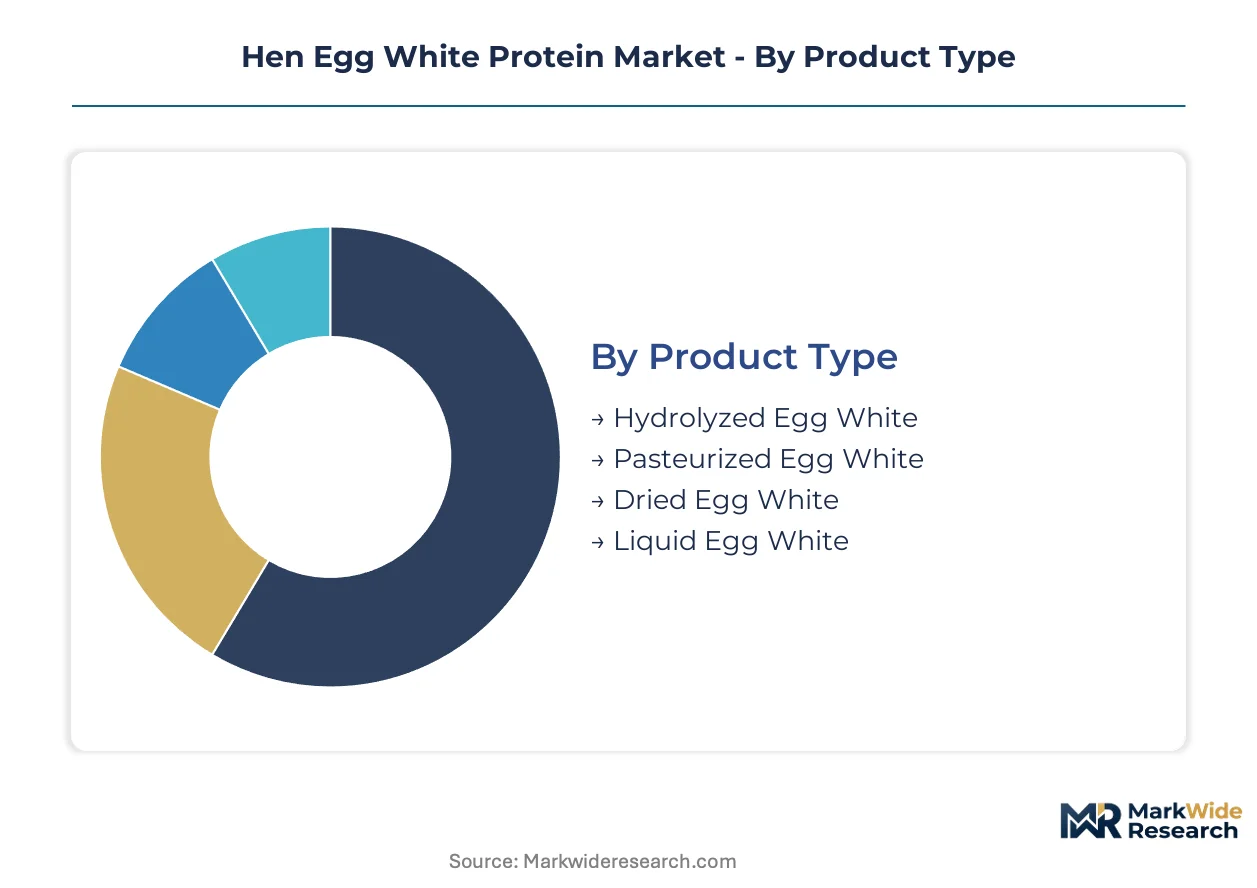
Hen egg white protein exhibits distinct margin and supply chain profiles across product forms, with capital requirements varying sharply between liquid handling infrastructure and spray-drying facilities. Segmentation reveals where purification technology investments concentrate and which customer channels reward specification premiums.
Product Type:
Capital intensity diverges sharply across processing technologies, with spray-drying and membrane filtration systems demanding the heaviest upfront investment.
- Dried Egg White:Spray-drying operations convert liquid to shelf-stable powder with moisture content below 8%, requiring continuous thermal processing lines and powder handling infrastructure. German bakery manufacturers and North American sports nutrition brands anchor procurement of this dominant form, drawn by eighteen-month shelf stability and eliminated cold-chain dependency.
- Liquid Egg White:Pasteurized fluid product retains native protein structure for foaming applications, demanding refrigerated tankage and rapid-turn logistics networks. Industrial bakeries operating continuous production lines in the US Midwest specify this format for precise hydration control in automated dough systems.
- Hydrolyzed Egg White:Enzymatic cleavage produces rapid-absorption peptide fractions for clinical and sports nutrition; requires bioreactor capacity and fractionation expertise.
- Pasteurized Egg White:Heat-treated liquid for foodservice and institutional channels; lower capital barrier than drying but demands validated Salmonella-negative certification systems.
Dried egg white absorbs the bulk of installed capacity; hydrolyzed variants are expanding most quickly.
Application:
End-use specifications drive divergent purity requirements, with pharmaceutical-grade demands commanding premium positioning over commodity foodservice grades.
- Sports Nutrition:Protein bar and shake formulators specify high-gelling isolates with clean-label positioning, displacing synthetic emulsifiers. Japanese and German brands lead procurement of rapid-digestion hydrolyzed grades for post-workout formulations.
- Bakery Products:Foaming and emulsification functionality sustains mature demand from artisanal and industrial producers alike. Bavarian and Baden-Württemberg manufacturers fragment procurement toward regional suppliers capable of lot-level traceability documentation.
- Nutritional Supplements:Capsule and tablet applications require low-moisture powders with standardized protein content; FDA dietary supplement labeling rules tighten purity thresholds for fortification claims.
- Confectionery:Meringue and nougat applications depend on whipping volume stability; EFSA allergen mandates under Regulation (EU) No 1169/2011 force explicit egg protein disclosure on export labels.
Bakery applications command the largest volume footprint; sports nutrition climbs the fastest on specification premiums.
End User:
Customer scale determines contract structure, with multinational food manufacturers locking in long-term supply agreements while smaller accounts rely on spot purchasing.
- Food & Beverage Industry:Broad industrial category spanning sauce emulsifiers to beverage clarifiers; procurement consolidates through qualified supplier programs with validated cross-contamination protocols.
- Bakery Manufacturers:Frozen dough specialists in southern Germany and the US Midwest prioritize uninterrupted supply for hydration-critical continuous lines, favoring eighteen-to-twenty-four month contracts with fixed volume tiers.
- Dietary Supplements:Contract manufacturers serving branded finished goods demand pharmaceutical-grade documentation and blockchain-traceable lot records.
- Fitness Centers:Direct bulk purchasing for on-site smoothie bars; smallest segment with highest price sensitivity and lowest specification requirements.
Bakery manufacturers lock in the longest contract tenors; dietary supplement channels pay the steepest specification premiums.
Distribution Channel:
Channel selection reflects order scale and technical service requirements, with bulk industrial volumes bypassing retail entirely.
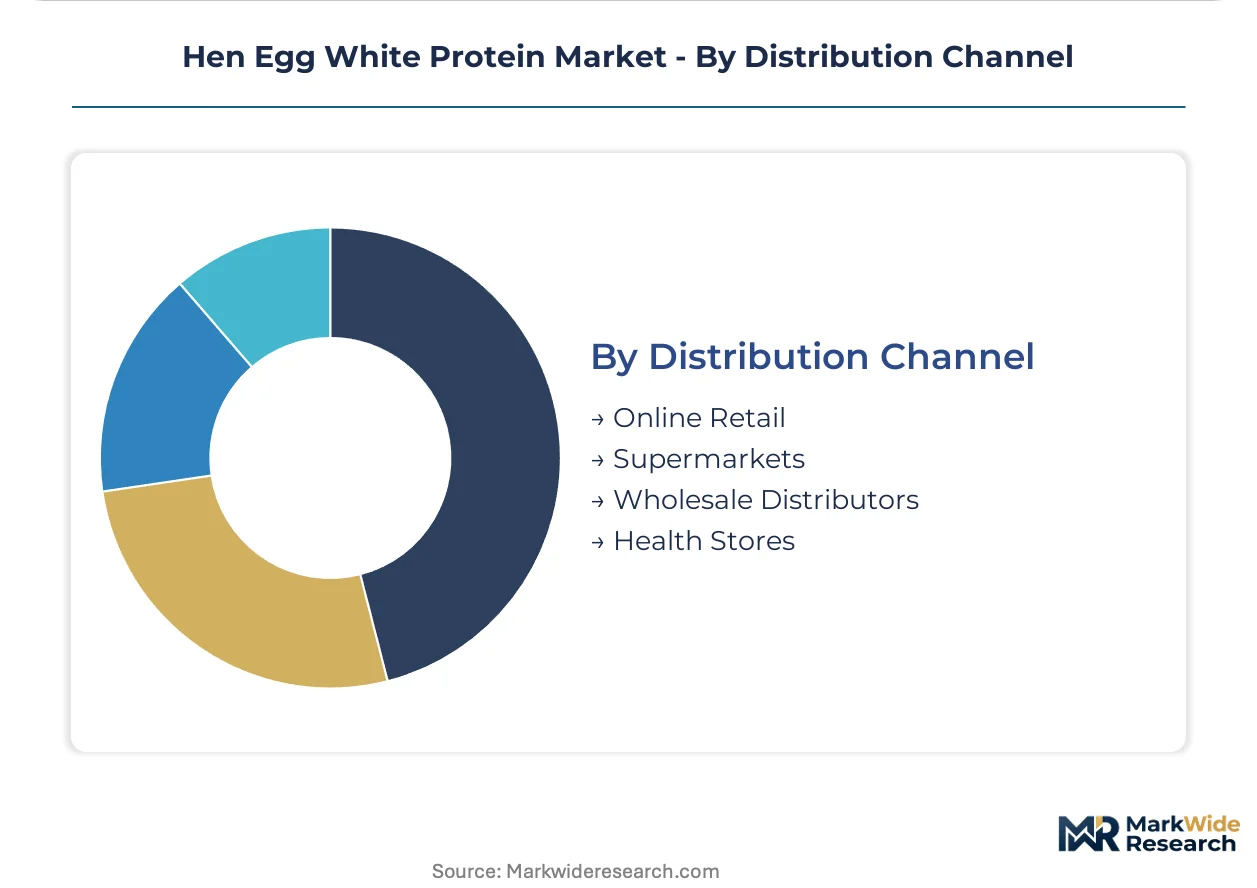
- Wholesale Distributors:Traditional ingredient merchants provide technical specification support and just-in-time delivery for mid-volume bakery accounts; facing disintermediation pressure from direct procurement platforms.
- Online Retail:E-commerce platforms capture small-lot sports nutrition and specialty bakery ingredient demand; fastest-expanding channel for hydrolyzed and organic-certified grades.
- Supermarkets:Consumer-packaged liquid and dried formats for home baking; mature channel with limited growth trajectory.
- Health Stores:Premium-positioned isolates for fitness enthusiasts; narrow assortment focused on clean-label and allergen-free positioning.
Wholesale distributors retain the largest transaction volume; online retail is gaining share fastest among emerging product grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where bakery manufacturers drive procurement of clean-label emulsifiers, while Japan and the United States anchor distinct supply chain configurations for clinical and sports nutrition applications.
Germany
Artisanal and industrial bakery manufacturers in Bavaria and Baden-Württemberg fragment procurement toward regional egg white suppliers capable of lot-level traceability documentation. EFSA allergen mandates under Regulation (EU) No 1169/2011 compel explicit egg protein disclosure on export labels, accelerating reformulation investments by confectionery exporters. The southern German bakery cluster prioritizes uninterrupted supply for hydration-critical continuous production lines.
United States
Sports nutrition brands and frozen dough manufacturers anchor procurement of dried egg white isolates and pasteurized liquid formats for protein fortification and automated baking systems. FDA enforcement of Grade A pasteurization standards under the Egg Products Inspection Act creates compliance barriers for small-scale shell-to-powder operators. The US Midwest industrial bakery corridor locks in eighteen-to-twenty-four month supply contracts with fixed volume tiers.
Japan
Functional food developers and clinical nutrition formulators drive demand for pharmaceutical-grade ovalbumin and rapid-absorption hydrolyzed grades. METI biotechnology roadmap incentives are opening R&D partnerships between processors and layer farm cooperatives for advanced protein fractionation. The Kanto region anchors supply chain integration through backward integration into contracted layer farms.
Netherlands
Confectionery exporters and ingredient distributors manage REACH registration requirements for food-contact processing aids, tightening purity documentation for filtration membranes and enzymatic processing aids. The Randstad logistics hub facilitates re-export of egg white proteins to European bakery and confectionery manufacturers. Dutch traders are consolidating supplier qualification programs to reduce audit burden across multiple jurisdictions.
India
Contract manufacturers serving dietary supplement and bakery ingredient channels are expanding spray-drying capacity for export-grade dried egg white powder. FSSAI food safety standards and BIS quality certifications shape processor investments in Salmonella-negative certification systems. Maharashtra and Gujarat host emerging shell-to-powder operations targeting Middle Eastern and Southeast Asian export markets.
Hen Egg White Protein Market Competitive Landscape
North American producers anchor one tier of the market structure; European and Japanese specialists hold differentiated positions in pharmaceutical-grade and functional food segments. The vendor base spans integrated layer farm operations, specialized ingredient processors, and diversified chemical conglomerates with purification infrastructure. Three archetypes dominate: shell-to-powder traceability specialists, pharmaceutical-grade fractionation operators, and backward-integrated farm-processor hybrids. Competitive moves concentrate on long-term supply contract lock-ins with bakery manufacturers and membrane filtration technology licensing for regional capacity expansion.
Within the pharmaceutical-grade tier, Merck KGaA exemplifies chemical conglomerate leverage of existing purification infrastructure for clinical nutrition applications. Among farm-integrated operators, Kewpie Corporation and Rose Acre Farms occupy positions representing distinct geographic supply chain models—Japanese cooperative backward integration versus North American traceability-focused shell-to-powder systems. These three companies illustrate how scale, integration depth, and end-market specification requirements stratify competitive positioning across regional markets.
| Leading Market Players |
|---|
| Lee BioSolutions |
| Calzyme |
| Kewpie Corporation |
| NOW Health Group |
| HiMedia Laboratories |
| Merck KGaA |
| Rembrandt Enterprises |
| Rose Acre Farms |
| Bouwhuis Enthoven |
| Others |
Supply & Pricing Matrix
Corn and soybean meal futures on the Chicago Board of Trade cascade directly into layer farm feed costs, compressing processor margins and forcing tiered pricing adjustments across pharmaceutical-grade, food-grade, and commodity egg white protein tiers.
Pricing Analysis
Volume concentrates in commodity dried egg white while margin pools concentrate in hydrolyzed and pharmaceutical-grade isolates. Three-tier pricing structure across premium, standard, and economy levels separates cold-processed membrane filtration isolates from heat-denatured powders and unpasteurized liquid formats. Cost compression in the standard tier is intensifying because German and Japanese bakery manufacturers are consolidating procurement through qualified supplier programs. Fitness centers and small-lot sports nutrition buyers exhibit the highest price sensitivity, while clinical nutrition formulators show the least.
Supply Chain Analysis
Shell-to-powder traceability systems enable reverse-logistics documentation for lot-level recall protocols, though egg white proteins rarely flow backward through the chain. Production concentrates in the United States, Germany, and Japan, with emerging capacity expansion in India. The chain rests on contracted layer farm supply, soy and corn feed inputs, and membrane filtration equipment. Single-source vulnerability runs through concentrated German bakery demand clusters. Distribution runs through wholesale ingredient distributors and direct-to-manufacturer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology is displacing legacy heat-denaturation processing, rewarding processors who retool purification infrastructure for cold-processed isolates with premium positioning in sports nutrition and clinical applications.
For Market Incumbents: Anchor long-term supply contracts with US Midwest frozen dough manufacturers and southern German industrial bakeries to lock in volume-stable demand. Invest in Salmonella-negative certification systems that satisfy FDA Grade A pasteurization standards and EFSA allergen disclosure mandates. Defend against plant protein substitution threats by emphasizing foaming functionality and clean-label traceability that pea and fava bean isolates cannot replicate.
For New Entrants and Emerging Players: Capture underpenetrated clinical nutrition markets outside North America and Western Europe where pharmaceutical-grade ovalbumin purification remains scarce. Target India's Maharashtra and Gujarat clusters for export-grade spray-drying capacity serving Middle Eastern and Southeast Asian markets. Enter through R&D partnerships with layer farm cooperatives under Japan's METI biotechnology roadmap incentives.
For Investors and Strategic Acquirers: Distressed-cycle entries favor shell-to-powder traceability specialists in the United States and backward-integrated farm-processor hybrids in Japan with captive layer farm supply. Long-term viability hinges on membrane filtration technology licensing and blockchain-traceable lot documentation capabilities. Watch for FDA enforcement actions on small-scale operators and EFSA clean-label threshold tightening as inflection indicators for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Enables regional processors to match pharmaceutical-grade specifications without centralized capital investment in Germany and Japan. |
| Long-term Supply Agreement Lock-ins | Eighteen-to-twenty-four month contracts with fixed volume tiers secure uninterrupted supply for hydration-critical continuous bakery lines. |
| Backward Integration into Contracted Layer Farms | Kewpie Corporation's cooperative model in Japan demonstrates captive supply control that insulates feed cost volatility. |
| Salmonella-negative Certification Investment | FDA Grade A pasteurization compliance creates barriers for small-scale operators while opening premium market access. |
| Blockchain-traceable Lot Documentation | Rose Acre Farms' shell-to-powder systems satisfy North American food safety audits and retailer platform integration requirements. |
Research Methodology
Multi-period observation of layer farm input costs, spray-drying capacity utilization, and membrane filtration adoption rates anchored the trend analysis, supplemented by interviews with egg protein processors, bakery manufacturing procurement directors, sports nutrition formulators, clinical nutrition specialists, and layer farm cooperative managers. Secondary validation drew from FDA Egg Products Inspection Act enforcement records, EFSA allergen labeling guidance documents, USDA National Poultry Improvement Plan traceability data, and METI biotechnology roadmap policy filings. Bottom-up triangulation across product type, application, and regional demand clusters converged with top-down macroeconomic factor modeling.
Segment-weighting approaches distributed value and volume across dried, liquid, hydrolyzed, and pasteurized product forms, with additional weighting for sports nutrition, bakery, confectionery, and clinical nutrition applications. CAGRs were derived from fitted growth curves across the projection horizon, incorporating layer farm feed cost futures, clean-label certification threshold evolution, and sports nutrition brand procurement patterns as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to plant protein substitution rates, feed commodity price volatility, and regulatory divergence in heat-treatment standards across jurisdictions. Practitioners should monitor FDA enforcement intensity on small-scale shell-to-powder operators, EFSA allergen mandate expansion, and METI biotechnology roadmap funding allocations for early signals of structural shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Organic Pastry Flour Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Konjac Flour Market
Ingredients
Industrial Starch Market
Ingredients
Glucosylglycerol Market
Ingredients
Mung Bean Starch Market
Ingredients
Dried Beet Pulp Market
Ingredients
Phytogenic Market
Ingredients
Virginiamycin Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Xylooligosaccharide Market
Ingredients
Vegetable Concentrates Market
Ingredients
Tapioca Pearls Market
Ingredients
Dry Molasses Products Market