
 Medium Chain Triglyceride (MCT) Oil Market | 2026-2036
Medium Chain Triglyceride (MCT) Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Chain Triglyceride (MCT) Oil Market Insights
The MCT oil market is rebalancing as pharmaceutical-grade specifications split from bulk commodity grades used in general food service. Croda International Plc leverages its lipid chemistry expertise to command premium positions in medical nutrition. IOI Oleo sustains large-scale Malaysian production of refined palm-derived MCT fractions. KLK Oleo anchors Southeast Asian supply through integrated oleochemical complexes.
Medium chain triglyceride oil consists of fatty acids with six to twelve carbon atoms, typically derived from fractionated coconut or palm kernel oil through hydrolysis and re-esterification processes; its rapid hepatic metabolism into ketone bodies makes it valuable for energy-dense clinical and sports formulations. Liquid MCT dominates volume in beverage and shot applications where solubility and mouthfeel matter most. Powdered MCT grows fastest among keto meal replacement brands seeking shelf-stable convenience formats. Sports Nutrition captures the deepest margin pools as performance positioning justifies price premiums over standard dietary supplement SKUs.
The FDA oversees MCT oil safety in dietary supplements under DSHEA while the USDA governs its use in organic-labeled products through National Organic Program standards. EFSA evaluates novel food applications for MCT isolates in European markets, creating divergent approval timelines across jurisdictions. Stakeholders must monitor evolving ketogenic health claims regulation to anticipate which product categories will unlock expanded commercial access.
Market Dynamics
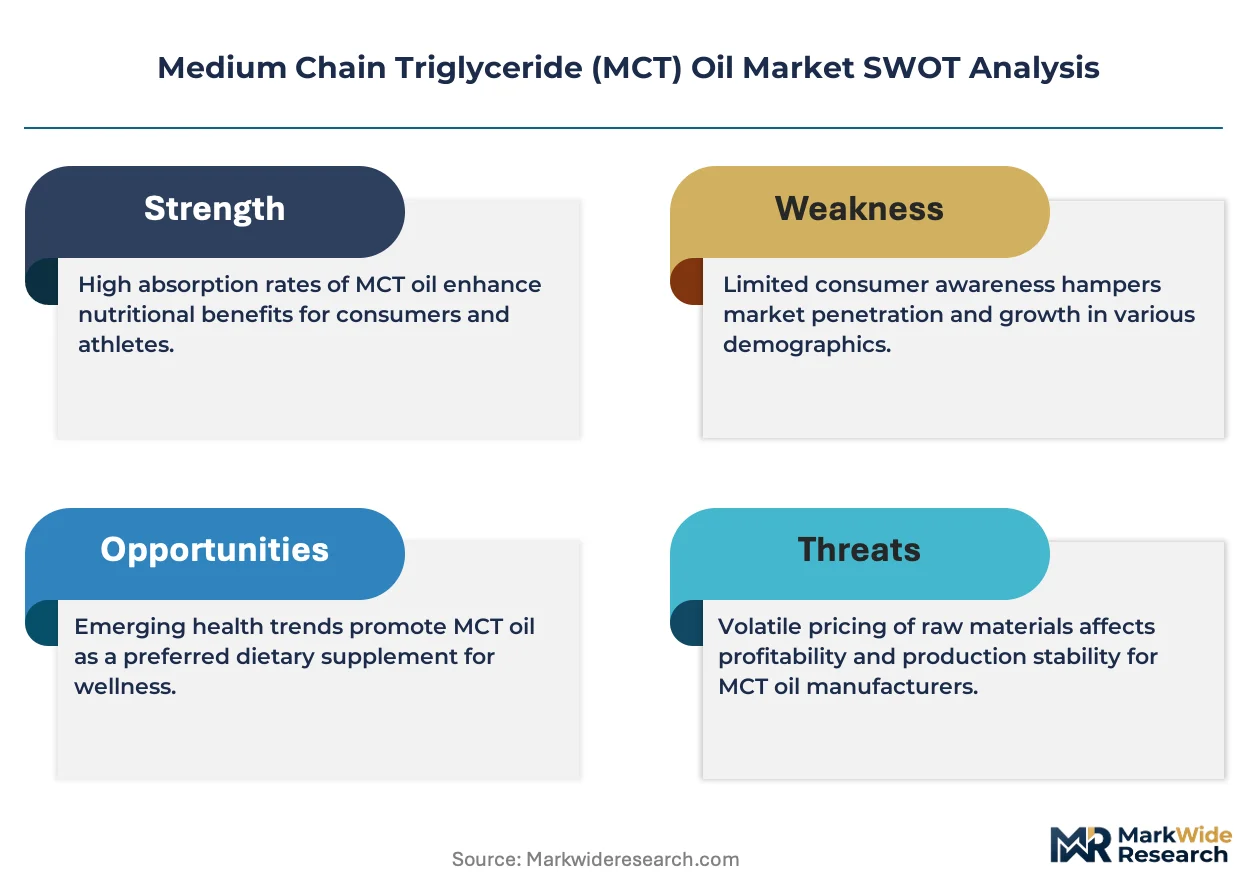
Pharmaceutical-grade MCT specifications are diverging from bulk commodity grades, creating parallel supply chains with distinct certification requirements and margin structures that reshape competitive positioning across medical nutrition and functional food channels.
Growth Catalysts
- Ketogenic Diet Protocols:Clinical adoption of ketogenic therapies for epilepsy and metabolic disorders drives demand for precisely dosed C8 and C10 isolates in hospital and homecare settings.
- FDA DSHEA Pathway:The notification framework for novel dietary ingredients streamlines market entry for concentrated MCT formulations while maintaining safety documentation standards.
- Sports Performance Positioning:Pre-workout and endurance nutrition brands leverage rapid ketone metabolism claims to justify premium pricing in athletic retail channels.
Market Restraints
- Palm Kernel Oil Concentration:Southeast Asian oleochemical complexes control 70% of global C8-C10 fraction supply, exposing buyers to single-origin geopolitical and climate risk.
- EFSA Novel Food Timelines:European approval processes for isolated MCT concentrates extend commercialization timelines by 18-24 months versus US market entry.
- Long-Chain Triglyceride Substitution:Cost-sensitive food service operators revert to conventional lipid systems when MCT premiums exceed formulation budget thresholds.
Strategic Opportunities
- Powdered Format Expansion:Keto meal replacement brands in North American e-commerce channels drive shelf-stable microencapsulation demand for travel and workplace consumption.
- USDA Organic Certification:National Organic Program standards for lipid derivatives create premium positioning for coconut-sourced MCT in natural retail.
- Medical Nutrition Integration:Enteral feeding and malabsorption therapy protocols incorporate structured MCT emulsions for hepatic bypass energy delivery.
Industry Challenges
- Fractionation Expertise Scarcity:Hydrolysis and re-esterification process engineering talent concentrates in Malaysian and Indonesian oleochemical clusters, limiting Western manufacturing scale-up.
- Ketogenic Health Claims Compliance:Evolving FDA and FTC enforcement on therapeutic positioning requires legal review of marketing copy across supplement and food categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Chain Triglyceride (MCT) Oil Market |
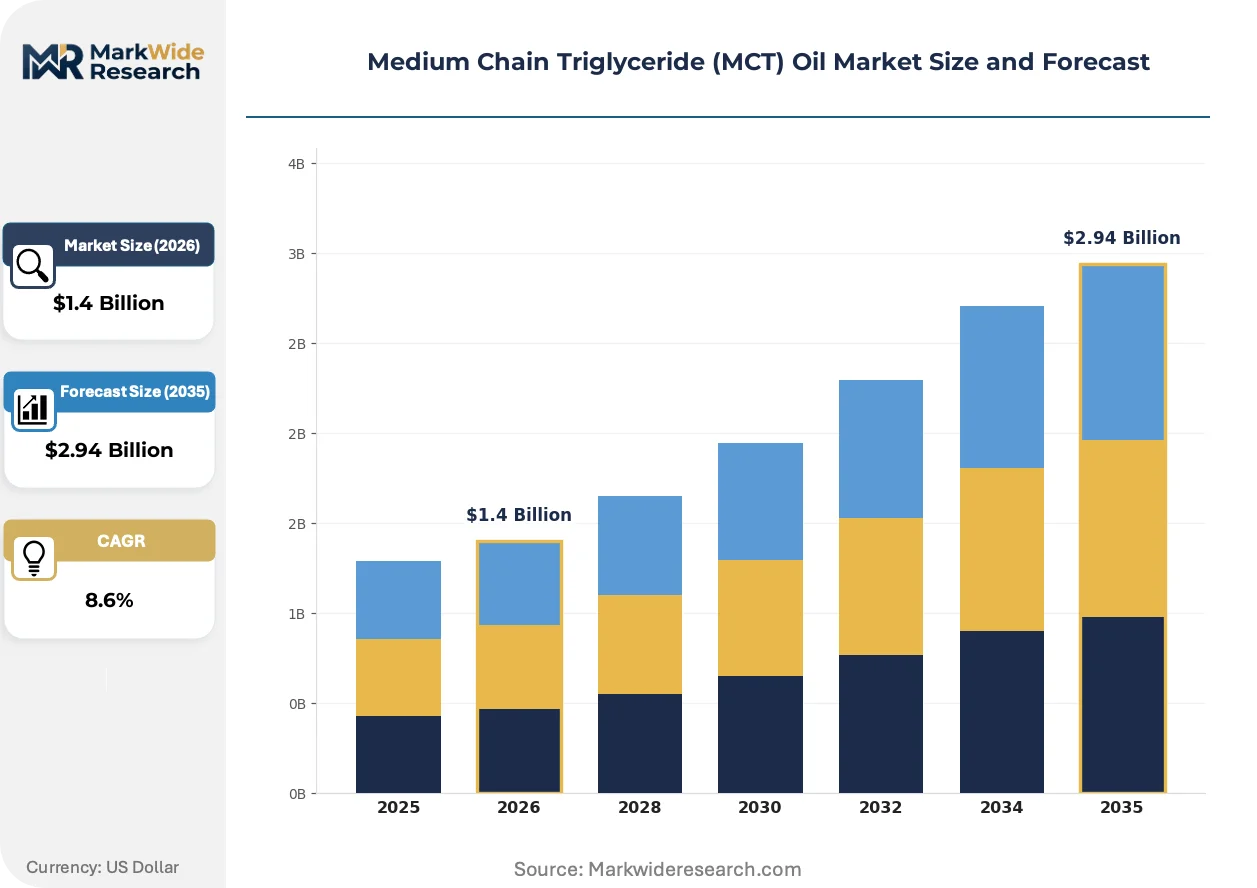
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid MCT, Powdered MCT, Organic MCT, Synthetic MCT Application: Sports Nutrition, Dietary Supplements, Food & Beverages, Personal Care End User: Health Enthusiasts, Athletes, Food Manufacturers, Cosmetic Brands Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Shops |
| Companies Covered | Croda International Plc, IOI Oleo GmbH, KLK Oleo, Musim Mas Group, Stepan Company, Wilmar International Limited, BASF SE, Koninklijke DSM N.V., Lonza Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Chain Triglyceride (MCT) Oil Market Trends and Innovations
Microencapsulation and spray-drying technologies are transforming MCT from liquid bulk commodity into stable powder formats, enabling new product architectures in ready-to-mix nutrition and extending shelf life without hydrogenation.
Enzymatic interesterification is converging with molecular distillation to produce higher-purity C8 caprylic acid isolates. Sports nutrition formulators adopt these concentrates for faster ketone elevation claims. The technology is converging with precision fermentation approaches, compressing the cost gap between plant-derived and biosynthetic MCT routes.
EFSA's novel food evaluation framework for isolated fatty acid ingredients tightens toxicology documentation requirements. European manufacturers delay launch timelines to assemble 90-day rodent studies and human tolerance data. Medical nutrition applications face the steepest compliance burden, prompting some brands to prioritize US FDA notification pathways first.
Direct-to-consumer subscription models displace traditional supplement retail distribution for powdered MCT products. Keto lifestyle brands bypass brick-and-mortar markup by building recurring revenue through proprietary flavor systems and personalized dosing protocols. This channel shift concentrates in North American metropolitan markets with established ketogenic diet practitioner networks.
Medium Chain Triglyceride (MCT) Oil Market Segmentation
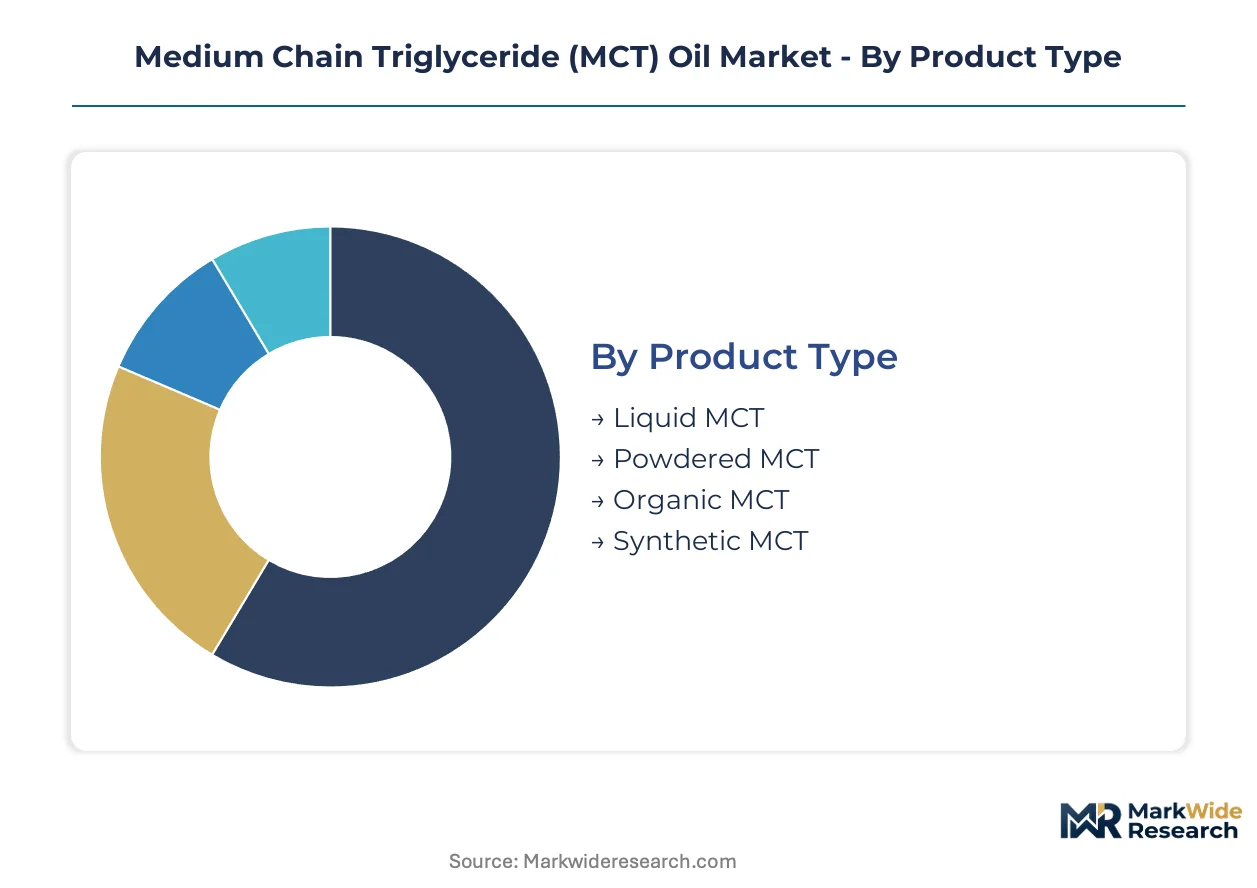
MCT oil segmentation reveals divergent margin architectures across physical formats and end-use channels. Product type determines processing complexity and certification requirements, while application splits separate clinical-grade specifications from commodity food service volumes.
Product Type:
Liquid formats command volume leadership while powder and organic variants extract premium pricing through convenience and certification positioning.
- Liquid MCT:Standard fractionated coconut or palm kernel oil in oil-phase delivery systems. Demand concentrates in beverage formulations and functional shots where rapid dispersion and clean mouthfeel drive formulation decisions. Sports nutrition brands favor this format for pre-workout applications requiring immediate ketone elevation.
- Powdered MCT:Microencapsulated or spray-dried oil particles enabling shelf-stable dry blends. Keto meal replacement brands in North American e-commerce channels deploy this format for workplace and travel consumption scenarios where liquid portability fails.
- Organic MCT:Coconut-derived fractions certified under USDA National Organic Program standards. Natural retail channels in the United States absorb supply at 15-25% premiums over conventional grades.
- Synthetic MCT:Biosynthetic or precision fermentation routes producing C8-C10 isolates. Commercial scale remains limited as enzymatic interesterification costs compress the plant-derived competitive gap.
Mature deployment sits with Liquid MCT. Newer deployment is concentrated in Powdered MCT.
Application:
Performance positioning in athletic channels sustains the steepest margin premiums, while food service integration demands cost-engineered commodity grades.
- Sports Nutrition:Pre-workout powders, endurance gels, and recovery formulations leveraging rapid ketone metabolism claims. Athletic retail channels justify price multiples over standard dietary supplement SKUs through clinical dosing protocols and third-party certification.
- Dietary Supplements:Standalone MCT oil products and ketogenic protocol adjuncts. Direct-to-consumer subscription models displace traditional retail distribution, concentrating recurring revenue in metropolitan markets with established ketogenic practitioner networks.
- Food & Beverages:Functional coffee creamers, salad dressings, and energy-dense clinical foods. Formulation budgets constrain adoption when MCT premiums exceed conventional lipid substitution thresholds.
- Personal Care:Emollient and carrier oil applications in topical formulations. Cosmetic brands specify lighter C8-C10 fractions for skin penetration claims in premium skincare lines.
Volume leadership belongs to Food & Beverages. Value capture concentrates in Sports Nutrition.
End User:
Consumer segments drive branded premium positioning while industrial buyers enforce specification discipline and volume contracting.
- Health Enthusiasts:Ketogenic lifestyle adopters purchasing through subscription and specialty retail. Personalized dosing protocols and proprietary flavor systems build brand loyalty in direct-to-consumer channels.
- Athletes:Endurance and strength training populations seeking ergogenic ketone elevation. This segment demands batch-tested certification and clinical evidence supporting performance claims.
- Food Manufacturers:Industrial formulators integrating MCT into functional food matrices. Procurement prioritizes supply security and price stability over branded ingredient storytelling.
- Cosmetic Brands:Skincare and personal care product developers specifying cosmetic-grade MCT fractions. Stability testing and odor profile consistency drive supplier qualification.
Industrial procurement anchors volume contracting. Consumer direct channels sustain margin expansion.
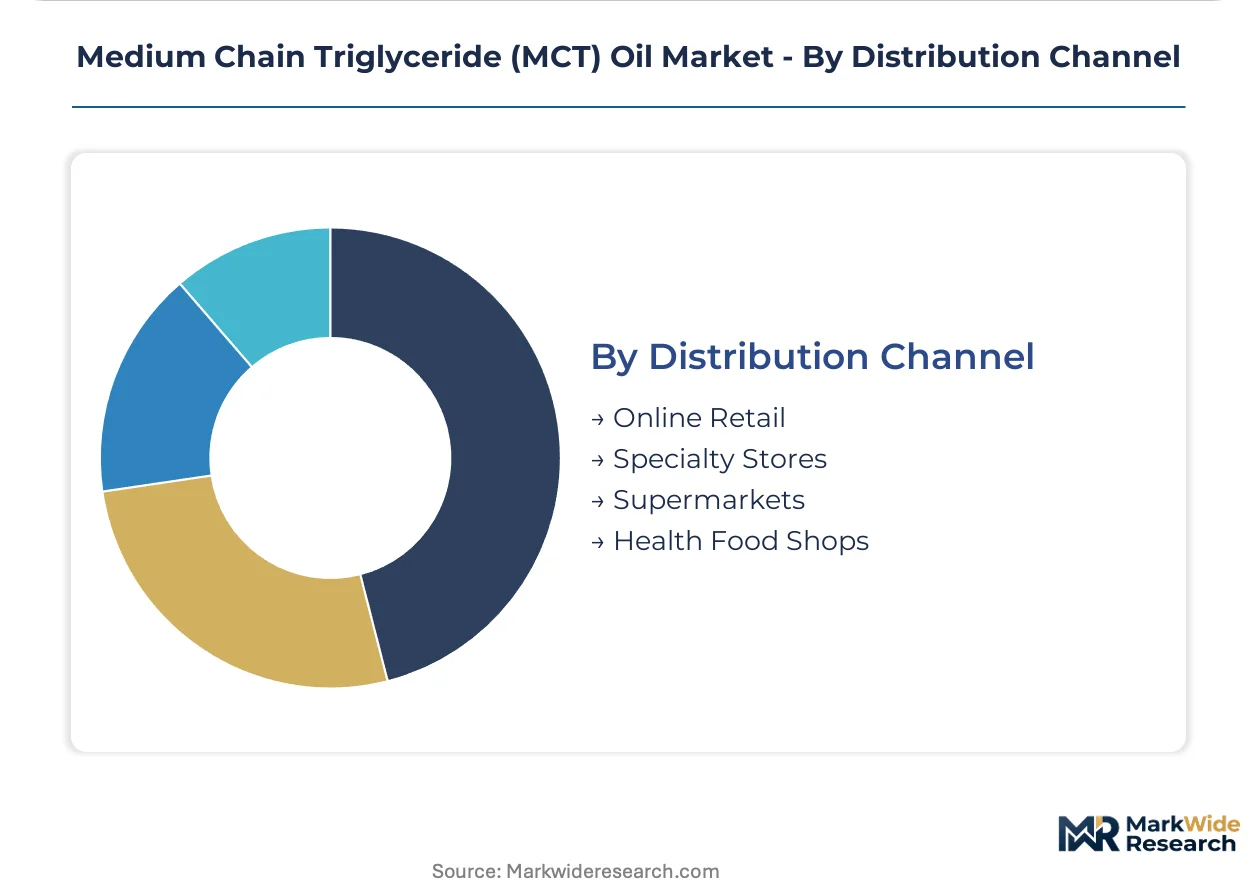
Distribution Channel:
Channel selection determines customer acquisition economics and brand control intensity, with digital-native brands bypassing traditional retail markup structures.
- Online Retail:Amazon, brand-direct storefronts, and keto-focused subscription platforms. This channel captures the fastest expansion as powdered MCT brands build recurring revenue without distributor intermediaries.
- Specialty Stores:Vitamin Shoppe, GNC, and independent supplement retailers. Shelf placement fees and promotional spending compress net margins for emerging brands.
- Supermarkets:Mass-market grocery and club store distribution. Volume potential attracts established food manufacturers with existing retail relationships.
- Health Food Shops:Whole Foods Market, Sprouts, and regional natural grocery chains. USDA Organic certification gates entry for coconut-sourced MCT positioning.
Established presence runs through Supermarkets. Channel shift momentum favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johor Bahru anchors Southeast Asian MCT fractionation capacity through integrated oleochemical complexes processing Malaysian and Indonesian palm kernel feedstocks. This concentration shapes global supply security for C8-C10 isolates used in pharmaceutical and sports nutrition formulations.
United States
Ketogenic diet practitioner networks in metropolitan markets drive direct-to-consumer subscription demand for powdered MCT formats. FDA DSHEA notification pathways streamline novel dietary ingredient entry for concentrated C8 isolates. California-based functional food brands integrate MCT into beverage formulations targeting Silicon Valley wellness consumers.
Germany
EFSA novel food evaluation timelines extend commercialization for isolated MCT concentrates by 18-24 months versus US pathways. German medical nutrition manufacturers formulate structured MCT emulsions for enteral feeding protocols in hospital settings. Hamburg anchors North European distribution for pharmaceutical-grade lipid derivatives.
China
SAMR oversight of novel food ingredients creates dual-track approval requirements for imported MCT isolates versus domestic production. NMPA medical device regulations govern MCT-containing clinical nutrition products for malabsorption therapy. Yangtze River Delta chemical clusters develop enzymatic interesterification capacity for higher-purity C8 production.
Japan
METI industrial policy supports precision fermentation research compressing cost gaps between plant-derived and biosynthetic MCT routes. PMDA pharmaceutical regulations structure clinical evidence requirements for therapeutic ketogenic positioning. Osaka-Kobe oleochemical refiners specialize in cosmetic-grade MCT fractions for premium skincare applications.
Brazil
ANVISA novel food regulations for isolated fatty acids require toxicology documentation similar to EFSA frameworks. Brazilian sports nutrition brands source MCT through import-dependent supply chains given limited domestic fractionation infrastructure. São Paulo anchors South American distribution for functional food ingredient imports.
Medium Chain Triglyceride (MCT) Oil Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and application-channel dimensions. The market structures around three tiers: pharmaceutical-grade specialists commanding medical nutrition premiums, integrated oleochemical majors supplying bulk C8-C10 fractions, and branded ingredient marketers capturing consumer-direct margins. Consolidation pressure concentrates among Malaysian and Indonesian upstream processors. Competitive moves center on backward integration into palm kernel supply and microencapsulation technology licensing for powder format expansion.
Within the integrated oleochemical tier, IOI Oleo GmbH and KLK Oleo exemplify Southeast Asian majors with captive fractionation capacity. Croda International Plc occupies a position among pharmaceutical-grade specialists leveraging lipid chemistry expertise for medical nutrition premiums. BASF SE represents the diversified chemical conglomerate archetype with cross-divisional reach into nutrition and personal care applications.
| Leading Market Players |
|---|
| Croda International Plc |
| IOI Oleo GmbH |
| KLK Oleo |
| Musim Mas Group |
| Stepan Company |
| Wilmar International Limited |
| BASF SE |
| Koninklijke DSM N.V. |
| Lonza Group Ltd. |
| Others |
Pricing and Supply Chain Analysis
Fractionation process engineering talent clustering in Malaysian and Indonesian oleochemical hubs compresses Western labor-cost differentials into pricing-tier spreads across pharmaceutical-grade and commodity MCT segments. This workforce concentration enables Southeast Asian producers to sustain margin advantages even as enzymatic interesterification technology diffuses globally.
Pricing Analysis
Value-based pricing anchored to ketone elevation throughput in sports nutrition applications structures the premium tier, with C8 isolate concentrates commanding multiples over standard C8-C10 blends. Certification grade under FDA DSHEA notification pathways and USDA Organic Program status drive price differentiation alongside volume scale. Pricing pressure stems from long-chain triglyceride substitution in cost-sensitive food service channels. Food manufacturers exhibit highest price sensitivity while sports nutrition brands show lowest, accepting premiums for batch-tested clinical dosing protocols.
Supply Chain Analysis
Refurbishment and re-esterification of off-specification fractions into cosmetic-grade outputs reduces waste in Malaysian oleochemical complexes. Geographic supply concentrates in Malaysia, Indonesia, and the Philippines through integrated palm kernel processing infrastructure. Raw material dependencies center on palm kernel oil feedstocks, coconut oil alternatives, and enzymatic catalysts for interesterification. Single-origin concentration in Southeast Asian fractionation capacity exposes buyers to climate and geopolitical risk. Distribution runs through bulk commodity traders for industrial buyers and direct-to-consumer platforms for branded finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around backward integration capabilities as palm kernel supply control separates viable scale players from margin-compressed assemblers. EFSA novel food timeline differentials favor US-first commercialization strategies for concentrated isolates.
For Market Incumbents: Extend captive palm kernel supply through long-term offtake agreements with Malaysian plantation groups to defend against IOI Oleo and KLK Oleo upstream dominance. Deepen microencapsulation technology licensing partnerships with North American keto meal replacement brands to lock in powder format growth. Fractionation expertise scarcity in Western markets limits rapid capacity replication, protecting incumbent positions. For New Entrants and Emerging Players: Precision fermentation-derived C8 isolates offer a technology-first wedge into synthetic MCT segments as enzymatic costs compress plant-derived competitive gaps. Target USDA Organic-certified coconut-sourced positioning in natural retail channels where established oleochemical majors lack brand recognition. Deploy direct-to-consumer subscription models with proprietary flavor systems to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical-grade specialists given EFSA novel food compliance burdens extending European commercialization timelines and concentrating value in FDA-cleared assets. Long-term viability favors integrated processors with captive Malaysian or Indonesian fractionation infrastructure over pure-play brand marketers. Monitor SAMR novel food approval velocity in China as inflection indicator for Asian market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Kernel Supply | Captive feedstock access insulates margin structures from oleochemical commodity volatility in Malaysian trading hubs. |
| Microencapsulation Technology Licensing | Powder format IP unlocks shelf-stable keto meal replacement partnerships with North American e-commerce brands. |
| FDA DSHEA Notification Pathway Prioritization | First-mover clearance for concentrated C8 isolates captures sports nutrition premium before EFSA timelines delay European entry. |
| USDA Organic Certification Investment | National Organic Program compliance gates placement in Whole Foods Market and Sprouts natural retail channels. |
| Precision Fermentation R&D Partnership | Biosynthetic C8 routes hedge against palm kernel supply concentration and appeal to clean-label positioning requirements. |
Research Methodology
Multi-period observation of FDA DSHEA notification filings, EFSA novel food application timelines, and Malaysian palm kernel export volumes anchored the trend analysis, supplemented by interviews with oleochemical plant managers, sports nutrition brand formulators, and dietary supplement procurement leads. Secondary validation drew from USDA National Organic Program certification databases, USITC trade flow records, and SEC filings of listed oleochemical processors. Bottom-up volume modeling across liquid, powdered, organic, and synthetic product types triangulated against top-down market sizing from customs data and industry association reports.
The input-output matrix framed capacity utilization rates in Malaysian and Indonesian fractionation facilities against downstream demand from sports nutrition, dietary supplement, and medical nutrition channels. Segmentation dimensions modeled include physical format, application vertical, certification tier, and regional regulatory cluster. CAGRs derived from regression analysis of historical volume trajectories adjusted for ketogenic diet adoption curves and clinical protocol expansion in epilepsy and metabolic disorder treatment. Forecast inputs incorporated enzymatic interesterification cost compression curves and precision fermentation scale-up timelines.
Several conditions sit outside the modeled scope, including abrupt palm oil trade policy shifts, breakthrough biosynthetic C8 cost parity achievements, and ketogenic health claims enforcement actions by FDA or FTC. Forecasts reflect documented assumptions about EFSA evaluation timeline stability and Southeast Asian climate patterns affecting palm kernel yields. Practitioners should monitor SAMR novel food approval announcements, METI precision fermentation subsidy allocations, and ketogenic therapy reimbursement decisions by CMS for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Yeast Derivatives Market
Ingredients
Global Dietary Fibers Market
Ingredients
Dairy Ingredients Market
Ingredients
Europe Fruit and Vegetable Ingredients Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Malted Wheat Flour Market
Ingredients
Instant Dry Yeast Market
Ingredients
Omega-3 Encapsulation Market
Ingredients
France Protein Market
Ingredients
Australia Soy Protein Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Safflower Oil Market
Ingredients
Native Starch Market
Ingredients
Valerian Root Oil Market