
 Europe Fruit and Vegetable Ingredients Market | 2026-2036
Europe Fruit and Vegetable Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fruit and Vegetable Ingredients Market Foresight
Single-serve pouch configurations for concentrated fruit bases is hardening as the default format for beverage and snack manufacturers seeking portion control and reduced waste. Döhler Group SE leverages its flavor-compounding expertise to bundle fruit concentrates with natural color systems for turnkey solutions. Kerry Group anchors its position through deep R&D partnerships with European bakery chains requiring consistent hydrated fruit inclusions. AGRANA Beteiligungs-AG specializes in region-specific apple and berry sourcing that sustains its supply security across Central European processing corridors.
Europe fruit and vegetable ingredients comprise processed plant-derived inputs standardized for brix, acidity, and microbiological stability through thermal treatment, concentration, or dehydration, serving as flavor carriers, texturizers, and natural colorants across formulated food and drink. Purees and concentrates carry the heaviest volume flows due to their compatibility with industrial-scale beverage and baby food lines, while powders command premium positioning in nutraceutical and clean-label snack applications where shelf stability and transport efficiency outweigh higher unit costs. Frozen form retains dominance in bakery and foodservice channels where structural integrity of fruit pieces matters, though dried formats are gaining traction in snack bar and cereal segments seeking reduced water activity without refrigeration dependency.
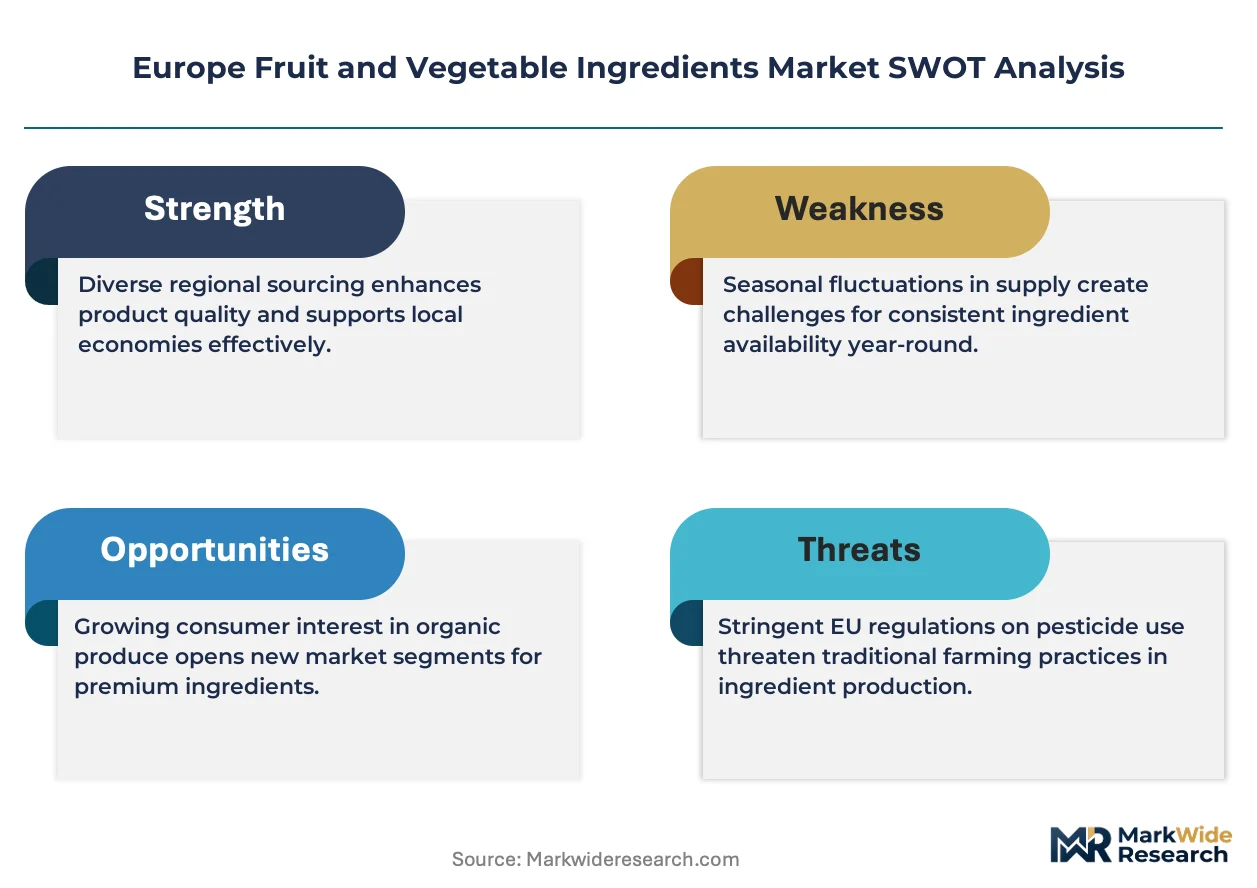
EFSA purity standards and the EU Green Deal farm-to-fork strategy tighten residue limits and traceability requirements, compelling ingredient processors to validate sustainable sourcing and pesticide reduction across their supplier networks. ECHA REACH compliance adds chemical safety documentation burdens that favor larger processors with dedicated regulatory affairs capacity over smaller traders. Stakeholders must weigh backward integration into controlled-origin supply against the capital intensity of meeting escalating sustainability audit requirements.
Market Dynamics
EU Green Deal farm-to-fork sustainability mandates are compressing pesticide residue limits and forcing processors to revalidate entire supplier networks, reshaping procurement economics across the continent.
Growth Catalysts
- EFSA purity standard escalation:Tightening microbiological thresholds for infant nutrition applications are pulling premium concentrate volumes into compliant supply chains.
- Clean-label beverage manufacturing:Industrial drink producers in Germany and France are substituting artificial colorants with standardized fruit-derived color systems at scale.
- Single-serve pouch concentration:Portion-control packaging formats are reducing waste metrics for foodservice operators and unlocking new contract manufacturing demand.
Market Restraints
- Apple and berry input volatility:Central European weather pattern disruption concentrates crop risk in Poland and Hungary sourcing corridors.
- ECHA REACH documentation burden:Chemical safety dossier requirements favor processors with dedicated regulatory affairs capacity over smaller traders.
- Frozen format energy costs:Cold chain electricity intensity in bakery and foodservice channels compresses margin structures during price spikes.
Strategic Opportunities
- Poland and Romania processing expansion:Underdeveloped dehydration capacity in Eastern European growing regions offers backward integration potential for volume players.
- Nutraceutical powder applications:Shelf-stable vegetable protein isolates are penetrating sports nutrition and clinical food segments previously served by synthetic inputs.
- CSRD supply chain disclosure:Corporate sustainability reporting mandates create audit service demand and premium positioning for validated-origin ingredient suppliers.
Industry Challenges
- Traceability system integration:Farm-to-fork digitization requires capital deployment into blockchain and IoT sensor networks across fragmented grower bases.
- Thermal process optimization talent:Shortage of engineers skilled in low-temperature concentration techniques limits brix standardization efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fruit and Vegetable Ingredients Market |
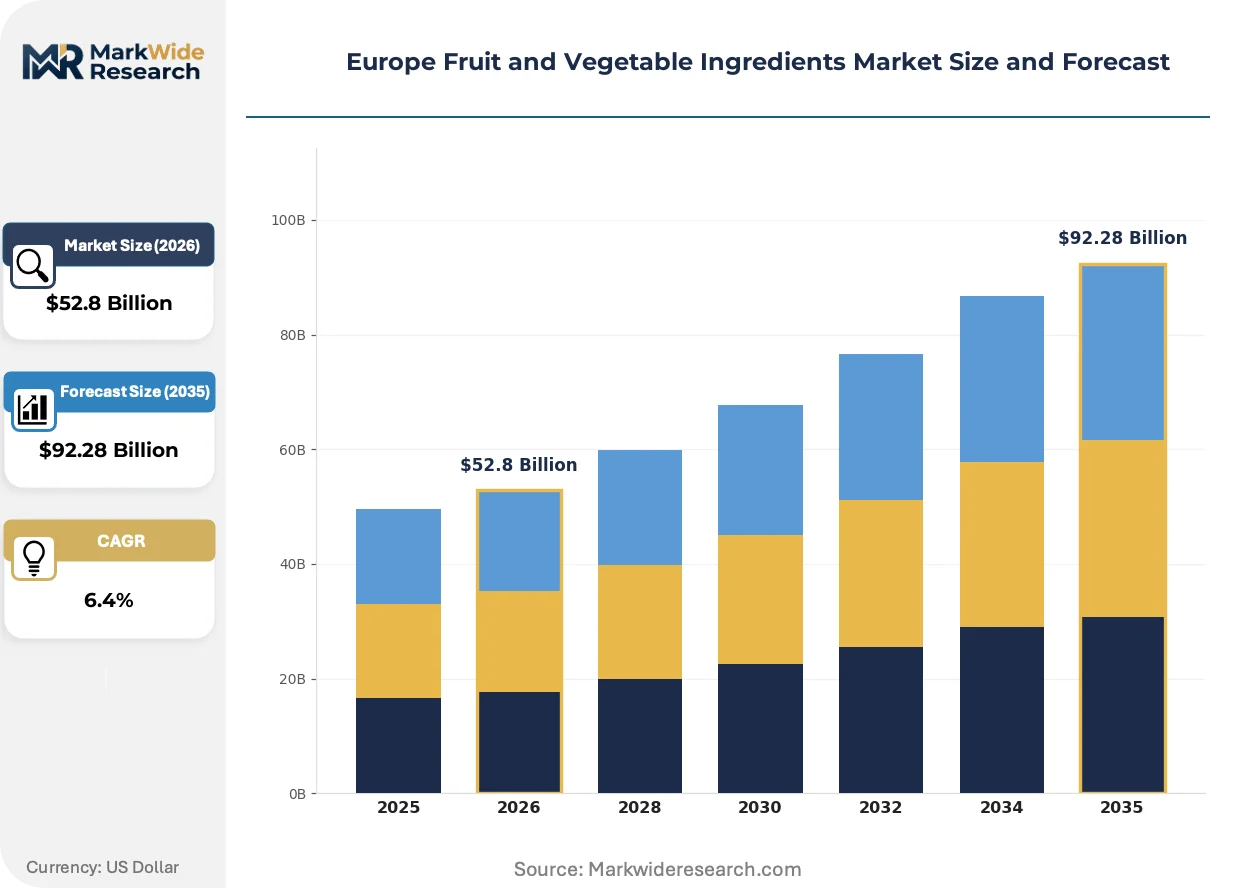
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Concentrates, Powders, Juices End Use: Food Processing, Beverage Manufacturing, Snacks, Bakery Products Form: Frozen, Dried, Liquid, Fresh Packaging Type: Bags, Bottles, Tubs, Pouches |
| Companies Covered | Archer Daniels Midland Company, Döhler Group SE, Kerry Group, Symrise AG, AGRANA Beteiligungs-AG, Tate & Lyle, SunOpta Inc, Olam International Limited, Sensient Technologies Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fruit and Vegetable Ingredients Market Shifts & Advancements
Processing technology convergence with sustainability verification systems is compressing batch-to-batch variability while expanding the addressable market for clean-label applications.
High-pressure processing technology is automating pasteurization workflows for sensitive fruit purees without thermal degradation of volatile aromatic compounds. German beverage compounders are deploying these systems at pilot scale ahead of broader industrial rollout. The technology is automating quality assurance labor while extending refrigerated shelf life parameters for premium juice applications.
EU Green Deal farm-to-fork pesticide reduction targets are mandating integrated pest management validation across contracted grower hectares. Processors must now document biological control agent usage and buffer zone compliance to maintain EFSA-approved supplier status. Baby food manufacturers face the steepest audit frequency increases as residue thresholds tighten for vulnerable consumer categories.
Direct contracting between ingredient processors and organized grower cooperatives is displacing spot-market procurement for strategic fruit categories. French and Italian beverage producers are locking multi-year supply agreements for specific apple varieties to secure color consistency and brix predictability. This consolidation concentrates volume leverage with processors while reducing price volatility exposure for cooperative members.
Europe Fruit and Vegetable Ingredients Market Segmentation
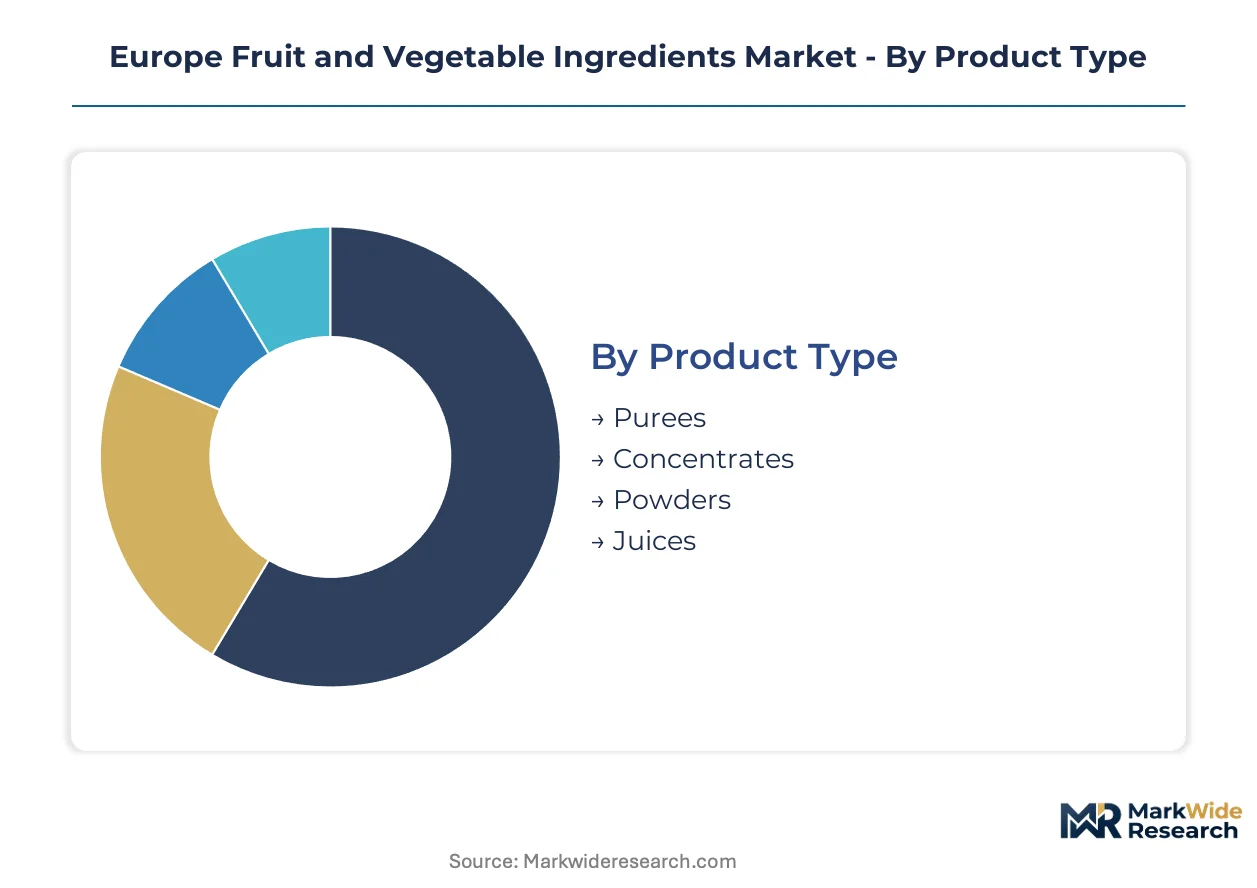
European processors configure ingredient specifications around thermal stability, brix standardization, and microbiological thresholds that vary sharply across infant nutrition, beverage, and bakery channels. Segmentation discipline separates commodity volume plays from premium positioning opportunities in clean-label and nutraceutical applications.
Product Type:
Reformulation cycles in German and French beverage manufacturing are accelerating specification upgrades from commodity juices toward concentrated and standardized inputs that reduce transport cost and water activity.
- Purees:Thermally stabilized fruit and vegetable mashes with controlled particle size distribution serve as texturizing bases for infant nutrition and dairy applications. German baby food manufacturers anchor procurement volumes here, pulled by EFSA microbiological thresholds that favor pasteurized, aseptically packed supply.
- Concentrates:Evaporated or membrane-filtered inputs standardized to specific brix levels function as flavor carriers and natural colorants. Beverage compounders in France and Spain concentrate demand for apple and red fruit concentrates as artificial colorant substitution accelerates under clean-label mandates.
- Powders:Spray-dried or drum-dried formats with sub-5% moisture content target nutraceutical and sports nutrition segments where shelf stability outweighs reconstitution cost.
- Juices:Single-strength or minimally processed liquid extracts retain importance in foodservice and private-label retail where per-unit cost sensitivity dominates specification.
Concentrates sit at the top of the volume ranking, with powders climbing the fastest.
End Use:
Customer procurement patterns diverge between multinational beverage and bakery chains demanding multi-year supply security and fragmented snack producers buying spot.
- Food Processing:Standardized fruit and vegetable inputs for prepared meals, sauces, and dairy applications require consistent viscosity and acid profiles. Central European ready-meal manufacturers drive specification toward aseptic purees with extended refrigerated shelf life.
- Beverage Manufacturing:Concentrated and compounded bases for juices, nectars, and functional drinks demand color stability and predictable brix. German industrial drink producers are expanding contract volumes for high-pressure processed purees that retain volatile aromatics without thermal degradation.
- Snacks:Dried fruit inclusions and vegetable powder coatings for bars and extruded products prioritize water activity control and particulate integrity.
- Bakery Products:Hydrated fruit pieces and concentrated fillings require structural retention through freeze-thaw cycles, concentrating demand in frozen and individually quick-frozen formats.
Beverage Manufacturing commands the largest revenue pool, with Snacks expanding most quickly.
Form:
Energy cost trajectories and cold chain reliability are reshaping format preferences across Eastern European processing corridors.
- Frozen:Individually quick-frozen fruit pieces and vegetable cuts retain cellular structure for bakery and foodservice applications. Polish and Hungarian processors dominate supply, though electricity price volatility compresses margin structures during peak demand periods.
- Dried:Dehydrated slices, dices, and powders with reduced water activity serve snack bar and cereal segments seeking ambient distribution without refrigeration dependency. Romanian dehydration capacity remains underdeveloped relative to orchard potential.
- Liquid:Aseptically packed concentrates and single-strength juices flow to beverage compounding and food manufacturing lines with pasteurization infrastructure.
- Fresh:Minimally processed chilled cuts retain limited industrial penetration outside premium foodservice and direct retail channels.
Frozen leads absolute volume, with Dried gaining share fastest.
Packaging Type:
Portion-control mandates and foodservice waste reduction targets are compressing demand toward flexible formats.
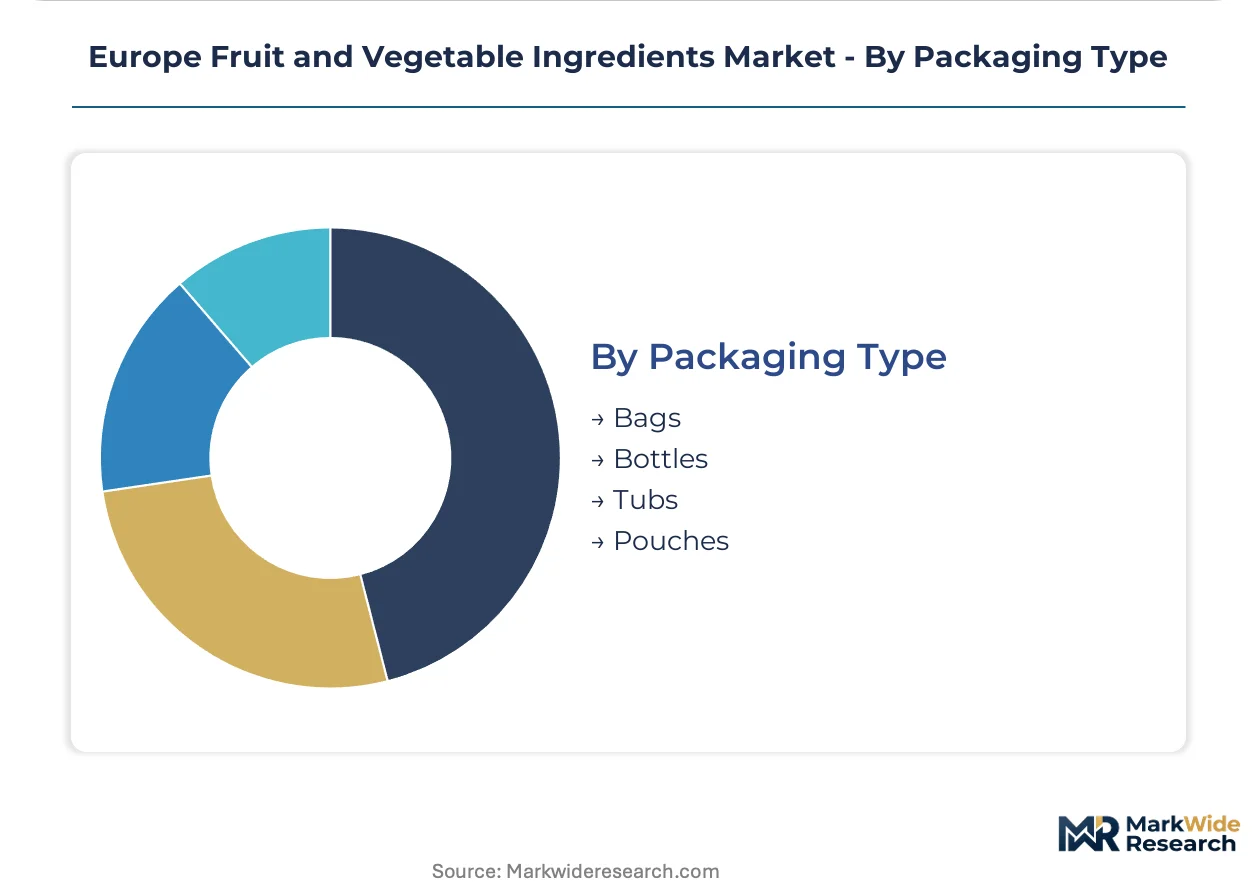
- Pouches:Single-serve and bulk bag-in-box configurations reduce headspace and enable precise portion dispensing. French beverage producers are standardizing on pouch concentrates for foodservice operators seeking waste metric improvements.
- Bags:Multi-layer laminated sacks for powders and dried pieces balance moisture barrier performance against unit cost in bulk ingredient distribution.
- Bottles:Rigid PET and glass containers retain importance in premium juice and foodservice concentrate segments where visibility and pour control matter.
- Tubs:Rigid plastic pails for frozen purees and concentrates serve industrial manufacturing lines with high-throughput emptying requirements.
Pouches now top the growth trajectory, with Bags holding the volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale fruit and vegetable ingredient processing first achieved commercial scale in Central European orchard belts during the post-war consolidation of cooperative agriculture. German and Austrian processors pioneered thermal stabilization techniques that standardized brix and acidity for industrial bakery and beverage lines. This technical foundation spread westward to France and northward to Poland as EU agricultural integration deepened procurement corridors.
Germany
Beverage compounding clusters in the Rhineland and Bavaria anchor continental procurement volumes for concentrated apple and berry bases. EFSA purity standards for infant nutrition pull premium pasteurized volumes into compliant supply chains serving baby food manufacturers. Munich and Hamburg processing corridors concentrate high-pressure processing pilot installations ahead of broader industrial rollout for sensitive aromatic retention.
France
Multi-year direct contracting between beverage producers and organized apple grower cooperatives in Normandy and the Loire Valley locks color consistency and brix predictability. EU Green Deal farm-to-fork pesticide reduction targets mandate integrated pest management validation across contracted hectares. Lyon and Paris basin compounders are standardizing single-serve pouch concentrates for foodservice operators seeking waste metric improvements.
Poland
Central European weather pattern disruption concentrates crop risk in Polish and Hungarian sourcing corridors for apple and berry inputs. Underdeveloped dehydration capacity relative to orchard potential offers backward integration opportunities for volume players. Warsaw and Łódź processing clusters dominate individually quick-frozen fruit piece supply, though electricity price volatility compresses margins during peak demand periods.
Italy
Mediterranean fruit variety specialization supports premium positioning in natural colorant and flavor compound segments. CSRD supply chain disclosure mandates create audit service demand for validated-origin ingredient suppliers serving northern European multinational accounts. Emilia-Romagna and Veneto processing belts concentrate tomato and stone fruit dehydration infrastructure with direct port access for Middle Eastern and Asian export.
Spain
Extended growing seasons and irrigation infrastructure in Murcia and Valencia support counter-seasonal supply security for northern European processors. ECHA REACH compliance documentation burdens favor larger processors with dedicated regulatory affairs capacity over smaller traders in the fragmented southern supplier base. Barcelona and Madrid corridors are expanding aseptic puree capacity for dairy and prepared meal applications requiring extended refrigerated shelf life.
Europe Fruit and Vegetable Ingredients Market Competitive Landscape
The competitive structure tilts toward diversified ingredient conglomerates with captive flavor-compounding capabilities. Tiered specialization separates turnkey solution providers from commodity concentrate traders and regional dehydration specialists. Strategic archetypes include integrated flavor houses bundling color systems, agricultural processors with cooperative supply lock-ins, and nutraceutical-focused powder specialists. Dominant competitive moves center on multi-year supply contracting with organized grower bases and pilot-scale adoption of non-thermal processing technologies.
Within the integrated solution tier, Döhler Group SE and Kerry Group exemplify archetypes combining fruit concentrate supply with adjacent formulation services. AGRANA Beteiligungs-AG anchors the cooperative-sourced specialization vector. Archer Daniels Midland Company and Tate & Lyle represent diversified agricultural conglomerates with ingredient processing as one vertical among broader commodity portfolios. These named entities occupy positions that illustrate the market's structural segmentation between flavor-compounding integrators and upstream agricultural processors.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Döhler Group SE |
| Kerry Group |
| Symrise AG |
| AGRANA Beteiligungs-AG |
| Tate & Lyle |
| SunOpta Inc |
| Olam International Limited |
| Sensient Technologies Corporation |
| Others |
Supply & Pricing Matrix
High-pressure processing adoption across German beverage corridors is compressing thermal degradation losses while concentrating procurement leverage among compounders with pilot-scale installations. This technology shift simultaneously raises capital barriers for smaller processors and rewards early movers with aromatic retention premiums that justify contract price elevation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified infant nutrition supply from industrial beverage inputs and commodity spot volumes. Price differentiation rests on residue testing intensity and organic certification status, with clean-label beverage manufacturers absorbing moderate premiums for validated-origin apple concentrates. Cost compression in frozen format tiers is intensifying because Polish and Hungarian electricity price volatility erodes cold chain margins. Snack bar producers exhibit highest price sensitivity due to water activity specification tolerance, while baby food manufacturers prioritize compliance over unit cost.
Supply Chain Analysis
EU Green Deal farm-to-fork domestic-content mandates are reshaping sourcing toward contracted grower hectares with integrated pest management validation. Supply concentrates in Poland, Hungary, and Romania for apple and berry inputs, with Italian dehydration infrastructure serving Mediterranean specialty varieties. Raw material dependencies center on orchard-grade fruit, natural colorant feedstocks, and aseptic packaging materials. Single-source vulnerability runs through Central European weather corridors where hail and frost events concentrate crop risk. Distribution runs through organized cooperative networks into processor consolidation points, then onward to compounder and manufacturer direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on dehydration technology deployment that converts electricity cost exposure into shelf-stable powder premiums, particularly in Romanian catchment zones with underutilized orchard capacity.
For Market Incumbents: Deepen backward integration into Polish and Romanian dehydration capacity to capture stranded orchard potential before capital inflows accelerate. Secure multi-year EFSA-compliant supply agreements with organized cooperatives to lock brix predictability against weather volatility. Prioritize high-pressure processing scale-up in German pilot corridors to defend aromatic retention premiums against emerging thermal technology substitutes. For New Entrants and Emerging Players: Non-thermal pasteurization equipment leasing models offer service-based entry into beverage compounding without captive processing capital. Target Romanian dehydration white space where orchard supply exceeds installed drying capacity by widest margin. Lead with blockchain traceability audit services for CSRD compliance, selling validated-origin documentation to northern European multinational accounts rather than commodity concentrate volume. For Investors and Strategic Acquirers: Valuations sit cheapest among regional dehydration specialists with cooperative supply lock-ins but limited downstream flavor-compounding capabilities. Five-to-ten year viability favors processors with demonstrated EFSA audit frequency management and established baby food channel relationships. Watch for inflection in corporate sustainability reporting mandate enforcement intensity as the signal for premium pricing power emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dehydration Capacity | Captures margin leakage from electricity price volatility in Polish frozen supply corridors. |
| High-Pressure Processing Scale-Up | Secures aromatic retention premiums for German beverage compounders ahead of industrial rollout. |
| Multi-Year Cooperative Supply Agreements | Locks brix predictability for French apple concentrate buyers under EU Green Deal pesticide targets. |
| CSRD Traceability Audit Services | Creates recurring revenue from Italian processors serving northern European multinational disclosure mandates. |
| Powder Format Capacity Expansion | Addresses Romanian orchard potential with shelf-stable output for snack bar and sports nutrition channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with ingredient processors, beverage compounder procurement leads, cooperative supply managers, and EFSA regulatory affairs specialists against secondary validation. Customs data, EU agricultural production statistics, processor SEC filings, and CSRD disclosure drafts anchored volume and trade flow estimates. Bottom-up orchard yield modeling and top-down end-use consumption surveys triangulated demand segmentation.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-energy-crisis margin restructuring. Segmentation dimensions spanned product type, end-use channel, form factor, and regional processing corridor. CAGRs derived from compound growth path modeling across infant nutrition, beverage, and bakery demand trajectories, with brix standardization efficiency and cold chain electricity cost curves as industry-specific forecast inputs.
The model holds under stable EU Green Deal enforcement trajectory and cooperative supply contract durability; deviation in EFSA purity threshold acceleration or Central European weather pattern disruption would shift volume and value estimates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Hemp Seed Peptide Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Plant Based Premix Market
Ingredients
Cheese Powder Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Hexane-Free Protein Market
Ingredients
Elecampane Root Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Home Baking Ingredients Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Fruit Pectin Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Anti-Aging Ingredients Market