
 Baobab Powder Market | 2026-2036
Baobab Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Baobab Powder Market Analysis
Functional beverage formulation is restructuring demand patterns across the baobab powder value chain. Nexira leverages its botanical extraction infrastructure to supply standardized polyphenol grades to European formulators. Aduna Ltd anchors its position through direct-source partnerships with harvester cooperatives in Senegal and Ghana. Mighty Baobab Limited specializes in small-batch organic certification for premium health-store channels.
Baobab powder consists of the dried, milled fruit pulp of Adansonia digitata, containing approximately 50% dietary fiber by weight and vitamin C levels exceeding 300 mg per 100 grams. The powder functions primarily as a natural texturizer, acidulant, and micronutrient fortificant in food matrices and supplement formulations. Organic baobab powder commands the dominant value share as clean-label procurement tightens across European and North American manufacturing. Food and beverage end use absorbs the largest volume throughput, though nutraceutical applications in capsule and tablet forms are expanding fastest as clinical validation of prebiotic effects accumulates.
EFSA Novel Food regulations govern import authorization and safety dossier requirements for baobab powder entering European commerce. FDA GRAS self-affirmation pathways shape US market entry timelines and label claim permissibility. Organic certification under USDA and EU organic frameworks directly determines pricing tiers and retail placement eligibility. Stakeholders must monitor evolving fiber-health claim regulations across multiple jurisdictions to anticipate reformulation cycles and positioning adjustments.
Market Dynamics
Clean-label procurement mandates from European food manufacturers are compressing certification timelines and reshaping supplier qualification protocols across the baobab powder value chain. EFSA Novel Food dossier requirements now function as the primary gatekeeper for market access, forcing harvester cooperatives to invest in traceability infrastructure ahead of commercial contracts.
Growth Catalysts
- EFSA Novel Food streamlining:Simplified safety dossier pathways for traditional African foods are accelerating import authorization timelines for Senegalese and Ghanaian harvester networks.
- Prebiotic clinical validation:Accumulating human trials on Adansonia digitata fiber fermentation profiles are expanding nutraceutical capsule and tablet applications.
- Functional beverage formulation:Antioxidant-rich smoothie and sports drink categories are absorbing premium organic grades as natural acidulant replacements.
Market Restraints
- Input cost volatility:Irregular Sahel rainfall patterns create year-to-year variation in wild-harvested fruit yields, destabilizing raw material pricing.
- Supply concentration risk:Over 80% of exportable organic powder originates from harvester cooperatives in Senegal, Mali, and Burkina Faso, creating single-origin vulnerability.
- Substitution threat:Moringa leaf powder and acerola extract compete directly for vitamin C fortification and antioxidant positioning in beverage applications.
Strategic Opportunities
- Underpenetrated North American retail:FDA GRAS self-affirmation pathways allow faster entry than EU Novel Food processes, opening specialty health-store channels.
- EU Green Deal alignment:Carbon footprint labeling requirements favor low-input wild-harvested ingredients over cultivated alternatives in clean-label scoring.
- Direct-to-consumer subscription models:E-commerce platforms enable harvester cooperatives to bypass conventional ingredient distributor markups.
Industry Challenges
- Organic certification timeline compression:EU organic and USDA organic audits require 18-24 month transition periods that delay first commercial shipments.
- Traceability system integration:Blockchain and GPS-mapping investments strain harvester cooperative balance sheets without advance purchase guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baobab Powder Market |
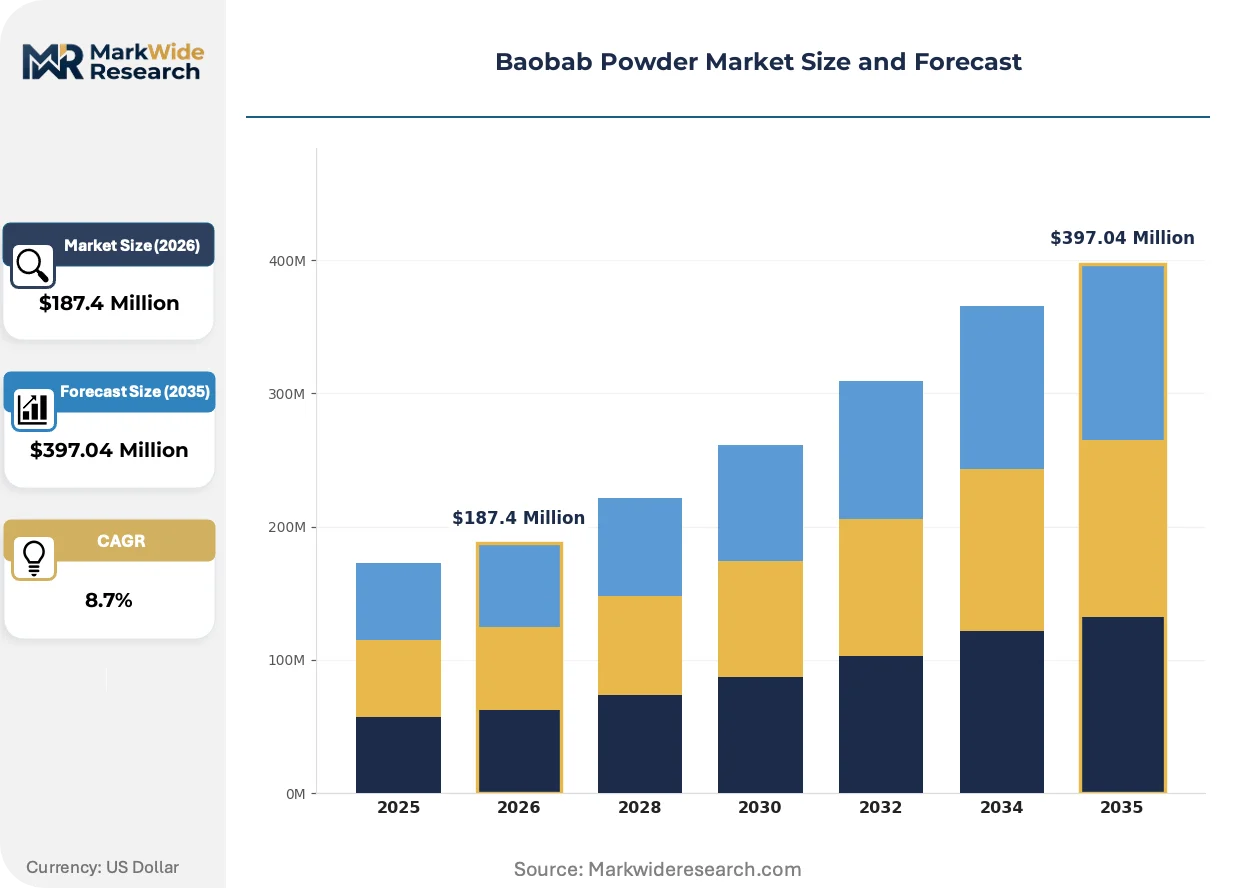
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
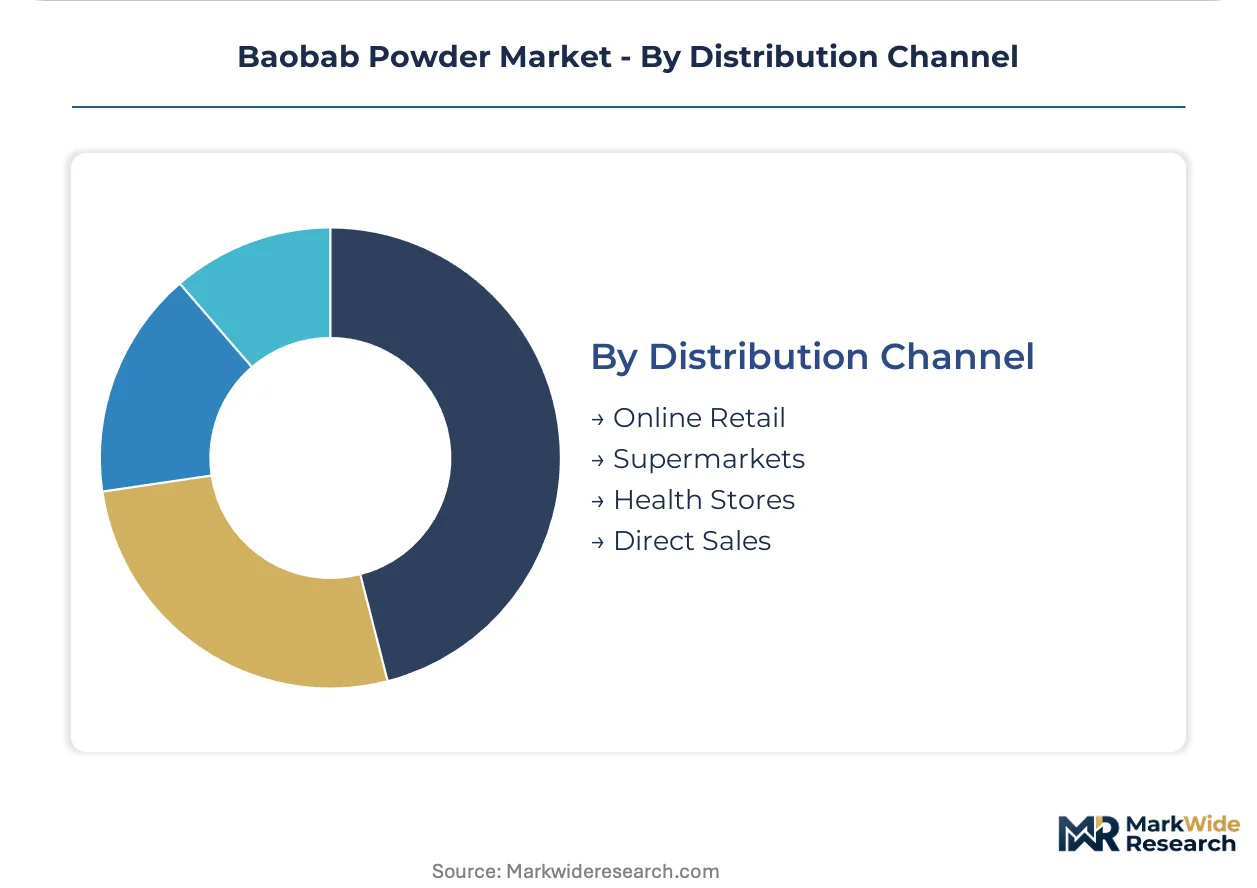
| Segmentation | Product Type: Organic Baobab Powder, Conventional Baobab Powder, Freeze-Dried Baobab Powder, Extracts End Use: Food & Beverage, Nutraceuticals, Cosmetics, Pharmaceuticals Form: Powder, Capsule, Tablet, Liquid Extract Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Nexira, Mighty Baobab Limited, Aduna Ltd, EcoProducts, Woodland Foods, Baobab Foods LLC, Afriplex Pty Ltd, Organic Africa, B'Ayoba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baobab Powder Market Emerging Trajectories
Formulation science and regulatory automation are converging to redefine how baobab powder enters finished goods. Three developments are compressing development cycles and reshaping competitive positioning.
Spray-drying technology adapted from dairy processing is unifying particle size distribution and moisture specifications across batch variations. European contract manufacturers are adopting these systems to meet beverage-grade texturizer requirements. The standardization is unifying quality tiers that previously separated food-service from retail-grade supply.
EU CSRD sustainability reporting mandates now require Scope 3 emissions disclosure from food manufacturers using African-sourced ingredients. Large European formulators are demanding GPS-mapped harvest polygons and transport carbon audits from suppliers. French and German procurement teams are restructuring supplier scorecards to prioritize documented low-carbon wild harvest over cultivated alternatives.
Health practitioner recommendation channels are displacing conventional retail discovery for baobab powder adoption. Functional medicine clinics and registered dietitians in Germany and the United Kingdom are directing patients toward prebiotic fiber supplementation. This professional referral loop is concentrating volume in practitioner-exclusive distribution networks rather than mass-market shelves.
Baobab Powder Market Segmentation
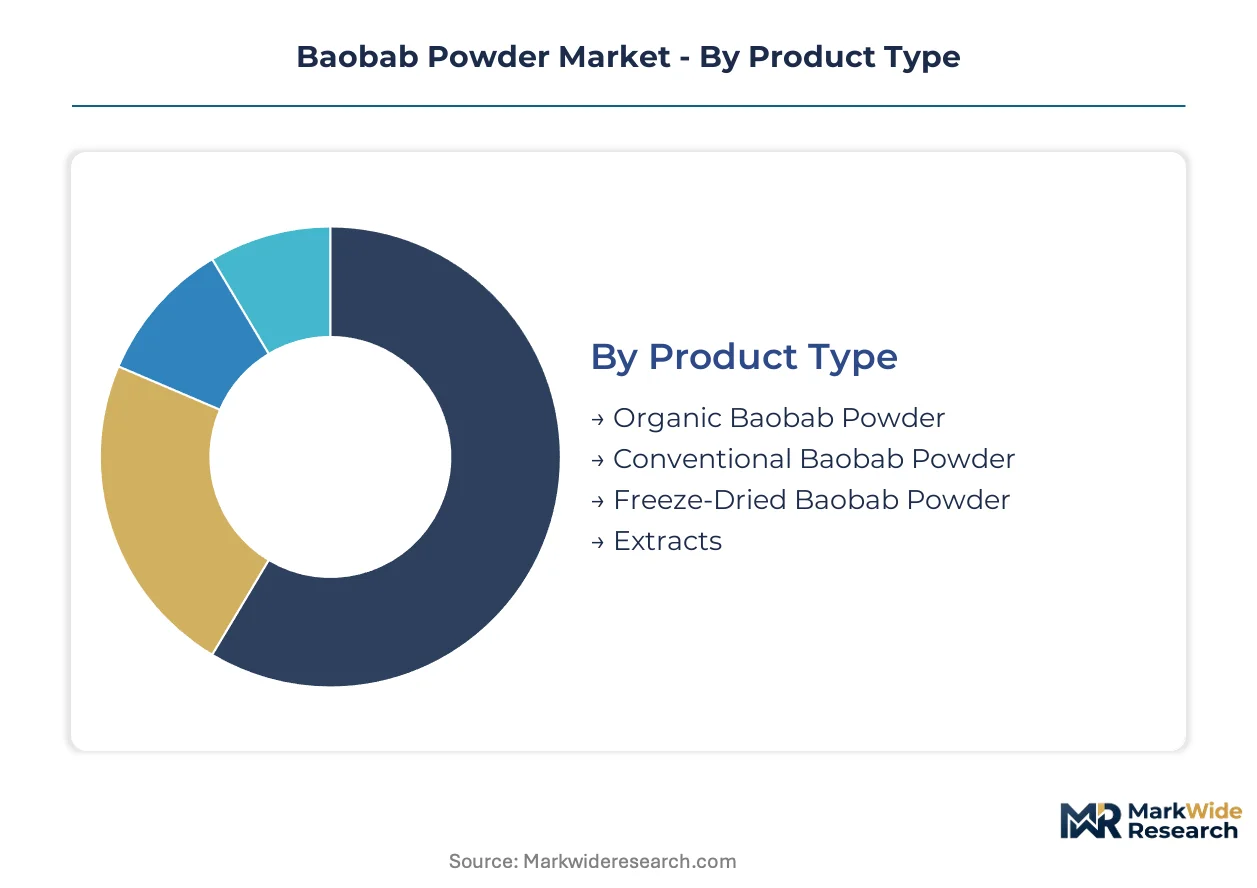
Segmentation in the baobab powder market reveals how regulatory certification tiers, formulation requirements, and channel economics partition commercial opportunity. Procurement teams navigate divergent compliance burdens and margin structures across product grades and end-use applications.
Product Type:
Organic certification under EU and USDA frameworks imposes the heaviest documentation burden, while conventional grades face lighter traceability requirements but compressed pricing power. EFSA Novel Food dossiers and FDA GRAS pathways apply variably across processing methods.
- Organic Baobab Powder:Wild-harvested pulp milled without synthetic inputs, commanding premium placement in clean-label formulations. German and French food manufacturers absorb the largest volumes as EU Green Deal carbon scoring favors low-input wild harvest over cultivated alternatives.
- Conventional Baobab Powder:Standard-processed pulp with conventional agricultural handling, serving cost-sensitive food-service and commodity ingredient channels. Price compression from moringa and acerola substitution limits expansion in antioxidant-positioned beverages.
- Freeze-Dried Baobab Powder:Low-temperature dehydration preserves heat-labile vitamin C and polyphenol activity for nutraceutical applications.
- Extracts:Standardized polyphenol or fiber concentrates for capsule and tablet formulations requiring precise active-content dosing.
Leading the category by volume: Organic Baobab Powder. Growing fastest: Extracts.
End Use:
Application-specific formulation standards reshape procurement specifications and supplier qualification protocols. Food-grade texturizer requirements diverge sharply from pharmaceutical-grade purity mandates.
- Food & Beverage:Natural acidulant and fiber fortification in smoothie bases, baked goods, and sports drinks. European functional beverage manufacturers drive demand concentration as antioxidant-rich positioning displaces synthetic alternatives.
- Nutraceuticals:Prebiotic fiber supplementation in capsule and tablet formats. Clinical validation of Adansonia digitata fermentation profiles is accelerating practitioner-channel distribution in Germany and the United Kingdom.
- Cosmetics:Antioxidant and exfoliant applications in natural skincare formulations.
- Pharmaceuticals:Excipient and active-ingredient roles requiring GMP-compliant manufacturing documentation.
Food & Beverage dominates current volume throughput. Nutraceuticals climb the fastest as professional recommendation channels expand.
Form:
Physical format determines shelf stability, dosing precision, and consumer convenience trade-offs. Powder specifications unify across beverage and food manufacturing, while unit-dose formats target supplement adherence.
- Powder:Bulk ingredient for industrial formulation and consumer kitchen use. Beverage-grade particle size standardization through spray-drying technology is compressing quality variation across Senegalese and Ghanaian supply origins.
- Capsule:Prebiotic fiber supplementation in unit-dose format for functional medicine protocols. German practitioner networks concentrate demand as registered dietitians direct patients toward gut-health interventions.
- Tablet:Compressed fiber delivery with excipient binding for swallowing convenience.
- Liquid Extract:Rapid-dissolution format for functional beverage ready-to-drink applications.
Powder commands the largest share by tonnage. Capsule formats expand most quickly on practitioner-channel momentum.
Distribution Channel:
Channel selection determines margin capture, brand control, and consumer education investment requirements. Direct models bypass distributor markups but demand logistics infrastructure.
- Online Retail:E-commerce platforms enabling harvester cooperatives to reach end consumers without conventional ingredient distributor intermediation. Subscription models from Senegalese source networks are testing price transparency against established brand premiums.
- Supermarkets:Mass-market placement requiring organic certification and clean-label packaging compliance. UK and French retail buyers prioritize EU organic and carbon-footprint labeling for shelf positioning.
- Health Stores:Premium specialty retail with practitioner-staffed consultation. Mighty Baobab Limited and comparable organic-certified suppliers target this channel for small-batch differentiation.
- Direct Sales:B2B ingredient supply to contract manufacturers and food processors with established formulation partnerships.
Supermarkets move the highest absolute volume. Online Retail gains share fastest on direct-source cooperative models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wild harvest operations in Senegal, Mali, and Burkina Faso supply the bulk of raw material, while European and North American markets absorb the processed powder. This production-consumption divide shapes logistics infrastructure and regulatory compliance investments across the value chain.
Germany
Functional beverage manufacturers in Bavaria and North Rhine-Westphalia drive organic baobab procurement for antioxidant-positioned formulations. EFSA Novel Food dossier requirements under EU regulations govern import authorization timelines for Senegalese suppliers. The Munich food-tech cluster hosts several contract manufacturers integrating spray-dried baobab into sports drink bases.
France
Clean-label procurement mandates from Paris-based food processors concentrate demand for certified organic grades. EU Green Deal carbon footprint labeling requirements favor low-input wild-harvested ingredients in sustainability scoring. The Lyon-Rhône-Alpes region anchors formulation R&D partnerships between African cooperatives and European distributors.
United Kingdom
Health practitioner networks in London and Greater Manchester direct patients toward prebiotic fiber supplementation, expanding nutraceutical applications. The Food Standards Agency maintains alignment with EFSA safety assessments for novel food ingredients. Direct-to-consumer subscription models from Senegalese source networks are testing price transparency against established brand premiums in UK e-commerce channels.
United States
FDA GRAS self-affirmation pathways enable faster market entry than EU processes, opening specialty health-store channels in California and New York. USDA organic certification determines retail placement eligibility in premium natural product chains. The Pacific Northwest hosts several functional beverage startups formulating with baobab as natural acidulant replacement.
Senegal
Harvester cooperatives in the Fatick and Kaffrine regions supply over 40% of exportable organic powder, creating supply concentration risk. The country's national food safety regulator coordinates with EU authorities on traceability documentation for Novel Food compliance. Dakar-based processing facilities are investing in blockchain mapping to meet French and German procurement requirements.
Baobab Powder Market Vendor Landscape
Top-tier vendors anchor premium organic certification tiers, while mid-scale operators compete on direct-source partnerships and harvester cooperative relationships. The vendor base stratifies across botanical extraction specialists, African-origin processors, and North American distribution intermediaries. Three archetypes dominate: European ingredient formulators with standardized polyphenol capabilities, African harvester cooperatives with organic wild-harvest access, and North American brand builders with practitioner-channel positioning. Competitive moves center on traceability infrastructure investment and direct-to-consumer channel development.
Among European botanical specialists, Nexira exemplifies the extraction-technology archetype with supply relationships across West African networks. Aduna Ltd and Mighty Baobab Limited occupy positions within the UK-based brand-builder tier, representing divergent strategies in cooperative partnership depth versus small-batch organic differentiation. These three entities illustrate how geographic origin and channel focus segment competitive positioning without overlapping operational models.
| Leading Market Players |
|---|
| Nexira |
| Mighty Baobab Limited |
| Aduna Ltd |
| EcoProducts |
| Woodland Foods |
| Baobab Foods LLC |
| Afriplex Pty Ltd |
| Organic Africa |
| B'Ayoba |
| Others |
Supply Flow & Price Mechanics
Wild-harvested fruit pulp from Senegal, Mali, and Burkina Faso flows through certification tiers that stratify pricing power downstream. EU organic and EFSA Novel Food compliance costs compress margins at harvester cooperatives while amplifying premiums for German and French food manufacturers commanding clean-label shelf placement.
Pricing Analysis
Margin tightening in conventional grades traces to moringa and acerola substitution in antioxidant-positioned beverages. Three-tier pricing structure across organic-certified, conventional, and extract-concentrate levels segments buyer archetypes, with food-service channels exhibiting highest price sensitivity and practitioner-network nutraceuticals showing lowest. Cost-down pressure on Senegalese harvester cooperatives accelerates because blockchain traceability investments strain balance sheets without advance purchase guarantees.
Supply Chain Analysis
EU Green Deal domestic-content mandates for carbon footprint labeling are reshaping sourcing toward GPS-mapped wild harvest polygons. Supply concentrates in Senegal, Mali, and Burkina Faso, with raw material dependencies on Sahel rainfall patterns, wild Adansonia digitata fruit yields, and organic certification audit capacity. Single-origin vulnerability from 80%-plus export concentration creates tariff exposure if EU trade preferences shift. Distribution runs through Dakar processing facilities to European ingredient distributors and North American health-store chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where harvester cooperatives and European formulators compete to capture traceability infrastructure and direct-to-consumer channel control.
For Market Incumbents: Deepen backward integration into Senegalese harvester cooperatives through advance purchase guarantees that secure organic certification pipeline. Invest in spray-drying standardization capacity to defend position against moringa substitution in beverage applications. Lock practitioner-channel distribution partnerships in Germany and the United Kingdom before clinical validation of prebiotic effects fully matures. For New Entrants and Emerging Players: Blockchain-enabled provenance tracking offers a technology-first wedge into premium organic tiers where incumbent traceability investments lag. Target underpenetrated North American health-store channels via FDA GRAS self-affirmation pathways that bypass EU Novel Food timelines. Pursue direct-to-consumer subscription models that bypass established distributor markups and test price transparency against brand premiums. For Investors and Strategic Acquirers: EFSA Novel Food authorization acceleration for traditional African foods is the leading indicator that regulatory moats are compressing, favoring early positions in harvester cooperative infrastructure. Long-term viability rests on carbon-negative wild harvest positioning aligned with EU CSRD Scope 3 disclosure requirements. Acquire vertically integrated processors with captive Senegalese supply and existing organic certification rather than pure-play distribution assets.| Strategic Initiative | Industry Significance |
|---|---|
| Harvester Cooperative Partnership | Captures organic certification pipeline and secures EFSA Novel Food traceability documentation for EU market access. |
| Spray-Drying Capacity Expansion | Unifies particle size distribution to meet beverage-grade texturizer specifications from German contract manufacturers. |
| Blockchain Traceability Deployment | Enables GPS-mapped harvest polygon disclosure required by French and German procurement teams under EU CSRD mandates. |
| Practitioner Channel Development | Concentrates volume in German functional medicine clinics and UK registered dietitian networks ahead of mass-market commoditization. |
| Direct-to-Consumer Subscription Launch | Bypasses conventional ingredient distributor markups for Senegalese source networks testing price transparency. |
Methodological Framework
Independent corroboration across harvester cooperative leadership, European food manufacturer procurement directors, and nutraceutical formulators underwrites the qualitative findings in this study. Primary fieldwork with Senegalese processing facility operators, German functional beverage R&D heads, and UK health practitioner network coordinators combined with secondary validation from EFSA Novel Food dossier records, EU organic certification databases, and customs trade data. Bottom-up volume estimates from harvester cooperative output figures triangulate against top-down demand modeling from European food and beverage production data.
Comparable-period anchoring to historical organic certification timelines and EFSA authorization cycles shaped the forecast window construction. Segmentation modeling spanned product type, end-use application, physical form, and distribution channel across the projection horizon. CAGRs derive from weighted average growth contributions by segment, with inputs including clinical trial publication rates on Adansonia digitata prebiotic effects and EU Green Deal carbon labeling implementation pace.
Several conditions sit outside the modeled scope, including extreme Sahel drought events disrupting wild harvest yields and abrupt EU trade preference renegotiations affecting Senegalese tariff access. Forecasts reflect assumptions around EFSA Novel Food streamlining continuity and practitioner-channel recommendation persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oyster Shell Powder Market
Ingredients
Tapioca Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Pea Starch Market
Ingredients
India Soy Protein Market
Ingredients
Specialty Starch Market
Ingredients
Desiccated Coconut Market
Ingredients
Fermented Ingredients Market
Ingredients
Wheat Starch Market
Ingredients
Pumpkin Seed Protein Market
Ingredients
Europe Amino Acid Market
Ingredients
Arachidonic Acid Market