
 Bean Pasta Market | 2026-2036
Bean Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Bean Pasta Market Intelligence
A capital-intensity divergence between extrusion technology investments and basic co-packing arrangements is reorganizing competitive tiers in bean pasta manufacturing. Banza LLC leverages in-house extrusion capabilities and direct-to-consumer infrastructure to sustain premium positioning. Pedon SpA anchors European supply through specialized legume processing scale in Italy. Explore Cuisine competes on organic certification breadth and international distribution reach.
Bean pasta comprises dried noodle and shaped formats manufactured from legume flours such as chickpea, lentil, black bean, or edamame, typically extruded at moisture levels below 12 percent and protein contents ranging from 14 to 25 grams per serving depending on source legume; the product serves as a gluten-free, high-protein substitute for conventional wheat pasta in retail and foodservice channels. Chickpea pasta occupies the dominant product type position due to neutral flavor compatibility with traditional sauces and broad consumer recognition. Online retail represents the fastest-expanding distribution channel as subscription models and direct brand engagement reduce shelf-space dependency. Health food stores retain concentrated margin pools through curated placement and dietitian endorsement programs.
FDA gluten-free labeling enforcement and USDA organic certification requirements govern product claims and facility audits for US-market participants, while EFSA novel food assessments and EU organic regulation shape import compliance for European distribution. The EU Green Deal agricultural transition targets and associated CAP legume cultivation incentives indirectly influence raw material availability and cost structures for European processors. Stakeholders must monitor evolving protein content claim thresholds and emerging front-of-pack labeling schemes that could redefine competitive positioning across retail channels.
Market Dynamics
Protein claim standardization across FDA and EFSA jurisdictions is compressing formulation flexibility and forcing manufacturers toward dual-certified production architectures. This regulatory convergence is reshaping capital allocation toward centralized extrusion facilities capable of serving multiple compliance regimes.
Growth Catalysts
- EU Green Deal legume cultivation incentives:The Common Agricultural Policy subsidizes domestic chickpea and lentil farming, reducing raw material import dependency for Italian and Spanish processors.
- Home cooking protein enrichment:Athletic households and diet-managed consumers are substituting wheat pasta with legume alternatives in weekly meal preparation, driving repeat purchase velocity through subscription channels.
- FDA gluten-free labeling enforcement:Strict facility segregation requirements for <20 ppm thresholds are creating competitive moats for certified manufacturers against uncertified private label entrants.
Market Restraints
- Chickpea price volatility:Pulse crop yields in Canada and Australia fluctuate with drought cycles, compressing processor margins during poor harvest seasons.
- Extrusion equipment concentration:Italian and German machinery suppliers control high-throughput legume pasta extrusion technology, creating capex bottlenecks for new entrants.
- Wheat pasta price anchoring:Conventional pasta's commodity pricing sets consumer reference points that constrain premium pricing power for bean alternatives in mass retail.
Strategic Opportunities
- Foodservice penetration:Hospital and corporate cafeteria nutrition programs are adopting high-protein pasta for therapeutic and performance dining applications.
- EFSA novel food streamlining:Simplified approval pathways for traditional legume varieties are accelerating European product line extensions beyond chickpea into mung bean and fava formats.
- Direct-to-consumer subscription models:Brand-owned ecommerce platforms bypass slotting fee barriers and capture first-party consumption data for flavor innovation.
Industry Challenges
- Dual certification complexity:Simultaneous USDA organic and gluten-free audits require dedicated quality personnel and extended facility downtime.
- Extrusion technician scarcity:Specialized knowledge of low-moisture legume dough rheology remains concentrated among veteran Italian equipment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bean Pasta Market |
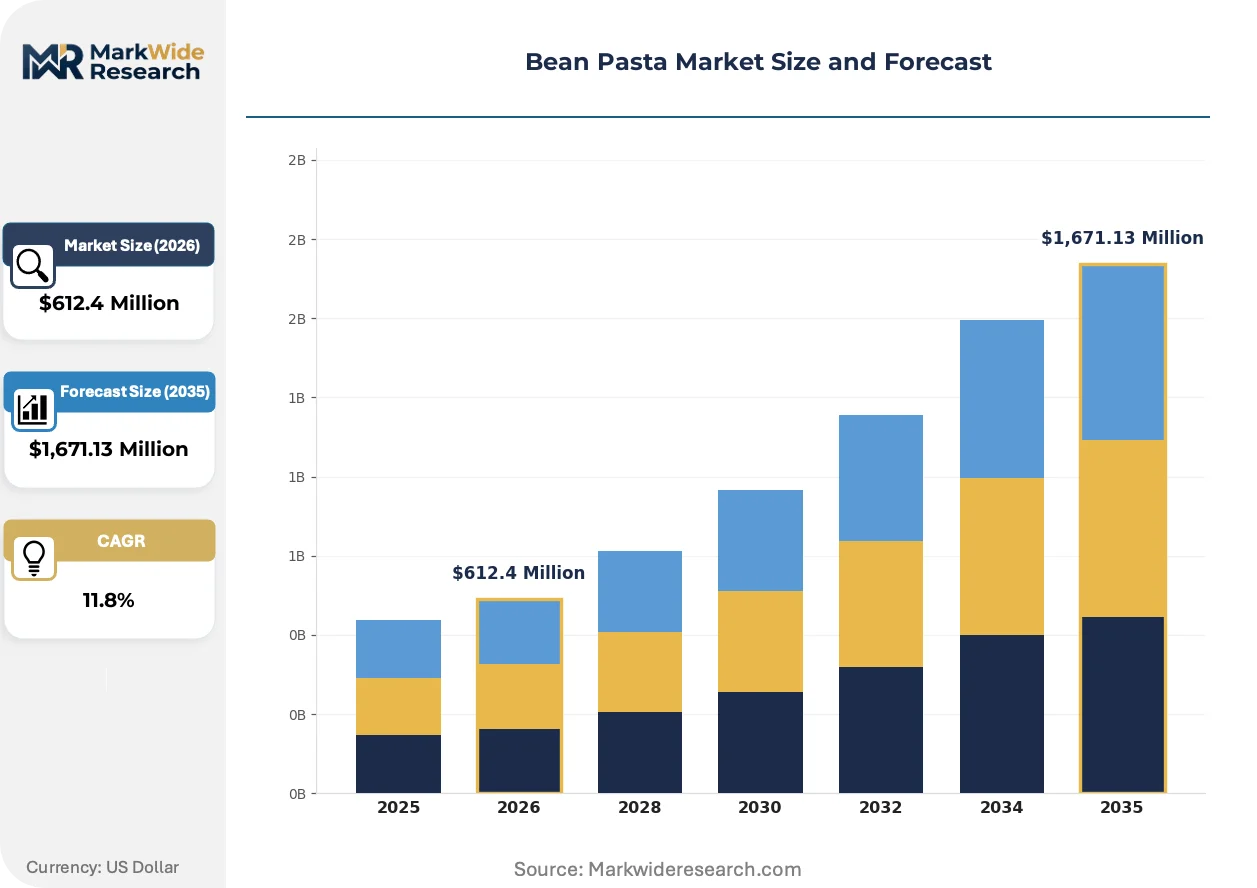
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,671.13 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chickpea Pasta, Black Bean Pasta, Lentil Pasta, Edamame Pasta Application: Home Cooking, Restaurants, Meal Kits, Health Food Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Health-Conscious Consumers, Vegetarians, Gluten-Free Dieters, Athletic Individuals |
| Companies Covered | Banza LLC, The Only Bean, LIVIVA Foods, Pedon SpA, NutriNoodle, Bellabondonza, Explore Cuisine, Tolerant Foods, Kazidomi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bean Pasta Market Strategic Shifts & Innovations
Extrusion technology advances and front-of-pack labeling mandates are converging to redefine product differentiation and manufacturing scale requirements across the bean pasta category.
Single-screw extrusion systems with precision temperature control are miniaturizing. Small-batch artisanal producers in Portland and Copenhagen are adopting compact extrusion units that previously required industrial-scale facilities. This equipment democratization is compressing minimum viable scale thresholds and enabling regional craft brands to achieve protein consistency rivaling mass manufacturers.
EFSA's evolving protein content claim thresholds are tightening. Manufacturers must now substantiate gram-per-serving declarations through standardized analytical methods, raising laboratory compliance costs. European retailers are responding by demanding third-party certificates before shelf placement, favoring processors with in-house testing capabilities.
Athletic consumers are consolidating purchases through specialized nutrition platforms. Subscription services targeting marathon runners and CrossFit practitioners are displacing conventional grocery discovery for high-protein pantry staples. This channel shift is most pronounced in California and Colorado, where direct brand relationships now drive trial for novel legume formats like edamame fusilli.
Bean Pasta Market Segmentation
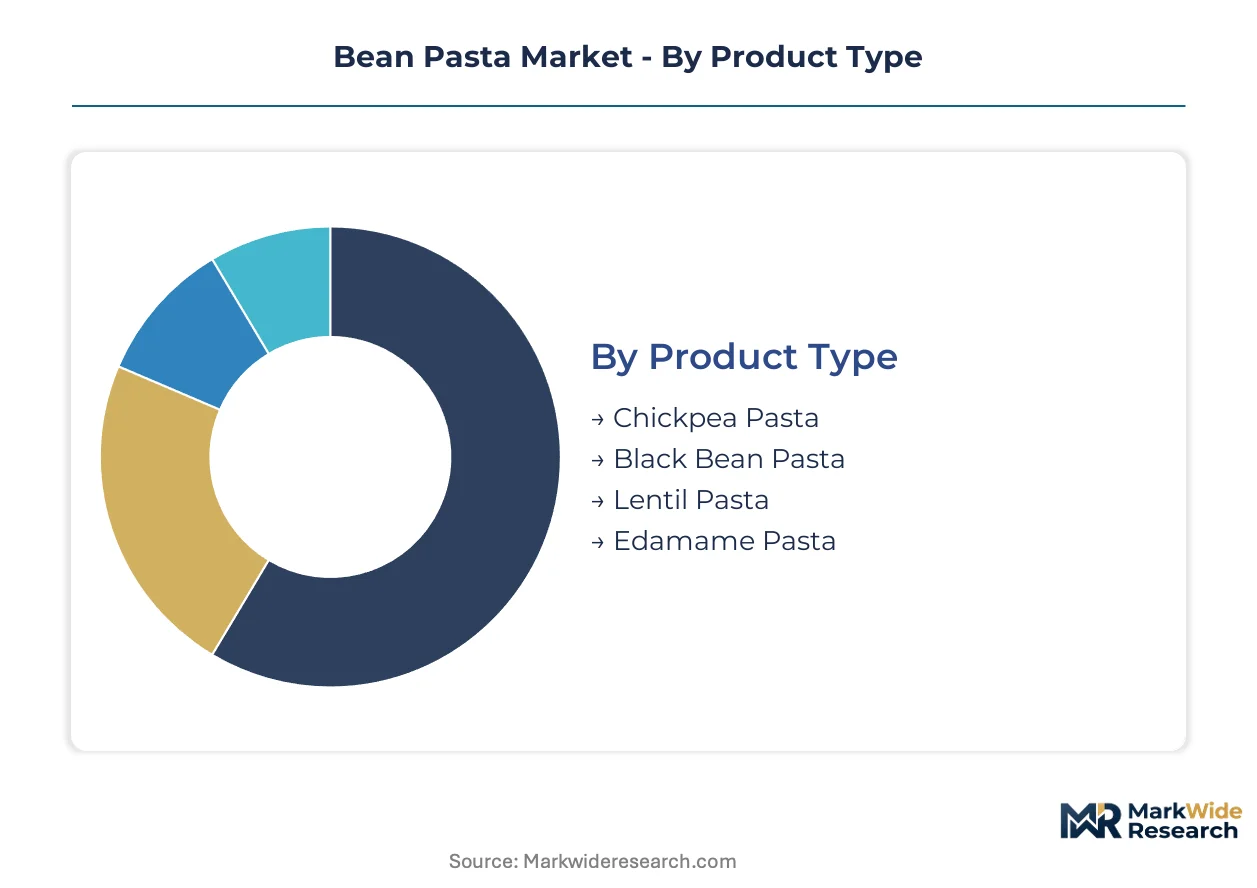
Bean pasta segmentation reflects divergent compliance burdens and channel economics across product formats and buyer profiles. Manufacturers must align extrusion capabilities and certification investments with specific segment requirements to capture margin pools effectively.
Product Type:
FDA gluten-free thresholds and USDA organic audits apply unevenly across legume bases, with chickpea and lentil varieties facing distinct supply chain verification demands.
- Chickpea Pasta:Neutral flavor profile enables broad sauce compatibility and mainstream retail placement. Italian processors leverage CAP-subsidized domestic chickpea cultivation to secure cost-advantaged supply for North American export. EFSA protein claim substantiation requirements favor established manufacturers with in-house analytical capabilities.
- Lentil Pasta:Higher protein density attracts athletic and therapeutic diet segments. Canadian red lentil supply volatility creates margin pressure during drought cycles, compressing processor economics relative to chickpea alternatives.
- Black Bean Pasta:Distinctive color and earthier taste profile limits mass-market penetration. Mexican and Brazilian raw material sourcing dominates supply configuration for North American production.
- Edamame Pasta:Asian-origin positioning commands premium pricing in coastal US markets. Japanese and Korean import dependency creates tariff exposure under evolving trade frameworks.
Chickpea pasta handles the majority of throughput; edamame pasta is gaining share fastest among premium-positioned entrants.
Application:
Volume concentration varies sharply between institutional procurement and direct-to-consumer subscription economics.
- Home Cooking:Weekly meal preparation drives repeat purchase velocity through brand-owned subscription platforms. Athletic households in California and Colorado consolidate pantry purchases through specialized nutrition services.
- Restaurants:Corporate cafeteria nutrition programs adopt high-protein pasta for performance dining contracts. Hospital therapeutic menus require dual certification and extended supplier qualification timelines.
- Meal Kits:Portion-controlled formats align with diet-managed consumer acquisition strategies. Supply chain complexity favors co-manufacturing partnerships over captive production.
- Health Food Stores:Curated placement and dietitian endorsement programs sustain margin premiums. Slotting fee structures disadvantage smaller regional brands.
Home cooking absorbs the largest volume base; meal kits are expanding most quickly as subscription models scale.
Distribution Channel:
Customer acquisition costs and data ownership rights diverge materially between third-party retail and direct channels.
- Online Retail:Subscription models bypass shelf-space dependency and capture first-party consumption data. Amazon and Thrive Market algorithms favor established brands with review velocity and inventory depth.
- Supermarkets:Mass retail placement requires slotting fee commitments and promotional spend coordination. Kroger and Albertsons category managers prioritize dual-certified suppliers with regional distribution density.
- Specialty Stores:Whole Foods and Sprouts emphasize organic certification breadth and local sourcing narratives. Smaller format count limits absolute volume potential.
- Direct Sales:Brand-owned ecommerce platforms eliminate intermediary margin extraction. Customer lifetime value metrics drive flavor innovation prioritization.
Supermarkets move the highest absolute tonnage; direct sales channels are climbing the fastest on margin contribution.
End User:
Protein claim sensitivity and certification awareness segment price tolerance and purchase frequency.
- Health-Conscious Consumers:Front-of-pack labeling responsiveness drives trial conversion. CrossFit and marathon training communities consolidate purchases through specialized nutrition platforms.
- Vegetarians:Complete protein positioning supports premium pricing relative to wheat alternatives. Meal planning applications influence brand discovery and loyalty.
- Gluten-Free Dieters:Celiac disease diagnosis and non-celiac sensitivity create distinct compliance requirements. FDA facility segregation standards govern supplier selection.
- Athletic Individuals:Gram-per-serving protein targets dominate purchase criteria. Strava and training platform integrations enable targeted digital acquisition.
Health-conscious consumers represent the broadest addressable base; athletic individuals are the steepest expansion trajectory on subscription attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across mature markets, with European consumers accepting steeper premiums for certified organic formats while North American buyers remain anchored to wheat pasta price benchmarks. Italian and Spanish processors exploit CAP subsidies to compress supply costs, whereas US manufacturers absorb higher chickpea import tariffs. Asian markets exhibit intermediate price sensitivity, with Japanese consumers prioritizing protein density claims over origin labeling.
United States
Athletic households in California and Colorado drive subscription-based repeat purchases through specialized nutrition platforms. FDA gluten-free labeling enforcement and facility segregation requirements create compliance moats against uncertified private label entrants. Chicago and Denver host emerging extrusion technology clusters where compact single-screw systems enable regional craft production.
Italy
CAP-subsidized domestic chickpea cultivation anchors cost-advantaged supply for North American export volumes. EFSA protein content claim substantiation requirements favor established manufacturers with in-house analytical laboratories. Emilia-Romagna concentrates specialized legume processing infrastructure, with Bologna-area facilities serving dual-certified production architectures.
Germany
Health food store chains in Berlin and Munich emphasize organic certification breadth and front-of-pack labeling transparency. EU Green Deal agricultural transition targets indirectly influence raw material availability through legume cultivation incentive structures. Bavaria hosts precision extrusion machinery suppliers controlling high-throughput equipment bottlenecks.
Canada
Red lentil supply volatility from Prairie Province harvest cycles creates margin pressure for protein-dense pasta processors. Health Canada gluten-free standards align with FDA thresholds, enabling cross-border certification efficiency. Saskatchewan pulse crop concentration determines regional processor cost structures during drought-affected seasons.
Australia
Chickpea yield fluctuations in Queensland and New South Wales generate raw material price instability for Asia-Pacific export contracts. TGA therapeutic food classifications influence hospital and institutional procurement specifications. Melbourne and Sydney specialty retailers curate placement through dietitian endorsement programs sustaining margin premiums.
Bean Pasta Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with in-house extrusion capabilities and direct-to-consumer infrastructure separating premium-positioned players from co-packing dependent entrants. The middle tier comprises regional craft brands leveraging compact equipment democratization to achieve protein consistency rivaling mass manufacturers. Two strategic archetypes dominate: vertically integrated processors controlling supply from legume sourcing through retail distribution, and certification-focused specialists optimizing for dual USDA organic and gluten-free compliance. Competitive moves concentrate on geographic expansion through EFSA novel food streamlining and capacity expansion in CAP-subsidized cultivation zones.
Within the integrated leader tier, Banza LLC and Pedon SpA exemplify divergent continental strategies, with the former anchoring North American direct-to-consumer infrastructure and the latter exploiting Italian agricultural policy support. Explore Cuisine occupies a position emphasizing organic certification breadth and international distribution reach. Among specialist entrants, Tolerant Foods and The Only Bean represent the compact-equipment craft segment, with geographic naming conventions suggesting regional concentration in North American metropolitan markets. These three archetypes—integrated leader, certification-focused internationalist, and craft specialist—structure competitive dynamics across price and compliance vectors.
| Leading Market Players |
|---|
| Banza LLC |
| The Only Bean |
| LIVIVA Foods |
| Pedon SpA |
| NutriNoodle |
| Bellabondonza |
| Explore Cuisine |
| Tolerant Foods |
| Kazidomi |
| Others |
Cost & Logistics Intelligence
FDA gluten-free facility segregation standards gate both supplier qualification and retail price differentiation, compressing uncertified processors into commodity tiers while certified manufacturers command shelf-space premiums through dual-label positioning.
Pricing Analysis
Subscription renewal revenue drives lifetime value for direct-to-consumer bean pasta brands. Three-tier pricing structure across premium organic, standard certified, and economy private-label levels stratifies the market, with protein density claims and USDA organic certification as primary differentiation levers. Cost compression in the standard tier is intensifying because wheat pasta price anchoring constrains pass-through of chickpea input volatility. Mass retail buyers exhibit highest price sensitivity, while athletic subscription customers tolerate premiums for gram-per-serving transparency.
Supply Chain Analysis
Canadian Prairie Province red lentil harvests and Australian Queensland chickpea yields create raw material chokepoints for protein-dense pasta processors. Production draws from Italy, Canada, and Australia for legume flour supply, with extrusion equipment dependencies resting on German and Italian machinery suppliers. Single-source vulnerability concentrates in high-throughput extrusion technology controlled by Bavaria-based equipment manufacturers. Distribution runs through brand-owned subscription platforms, Amazon fulfillment networks, and Kroger-Albertsons regional distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against wheat pasta price anchoring and emerging lentil-based fresh pasta substitutes that threaten shelf-stable differentiation.
For Market Incumbents: Secure CAP-subsidized Italian chickpea supply through long-term offtake agreements with Emilia-Romagna processors. Deepen backward integration into domestic legume processing to offset Canadian drought exposure. Reinforce dual-certification moats through dedicated quality personnel investment.
For New Entrants and Emerging Players: Lead with compact single-screw extrusion systems in Portland and Denver craft clusters to bypass industrial-scale capital barriers. Target meal kit partnerships as the most penetrable application segment. Pursue dietitian endorsement programs in health food stores as primary go-to-market channel.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational food conglomerates divesting non-core legume processing assets. Five-to-ten year viability hinges on subscription model scalability and EFSA novel food approval velocity. Watch EFSA protein claim threshold tightening as inflection signal favoring in-house analytical capability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Legume Processing | Captures CAP subsidy benefits and insulates margin from Prairie Province drought cycles. |
| Direct-to-Consumer Subscription Launch | Bypasses Kroger slotting fees and captures first-party consumption data for flavor innovation. |
| Dual Certification Investment | Creates FDA gluten-free and USDA organic compliance moats against uncertified private label entrants. |
| EFSA Novel Food Streamlining | Accelerates European product line extensions into mung bean and fava formats beyond chickpea. |
| Compact Extrusion Technology Adoption | Enables regional craft production in Denver and Portland with protein consistency rivaling mass manufacturers. |
Research Approach
A spread of perspectives from extrusion equipment operators, legume procurement managers at Italian processors, Amazon category specialists, Kroger shelf-space planners, and registered dietitians converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from FDA gluten-free facility audit records, USDA organic certification databases, EFSA novel food submission filings, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled span legume source type, application format, distribution channel structure, and end-user protein sensitivity tier across the projection horizon. CAGRs derived from historical volume trajectories and substitution elasticity parameters, with chickpea price volatility indices and CAP subsidy renewal schedules as industry-specific forecast inputs.
Underlying assumptions cover sustained FDA gluten-free enforcement intensity and EU Green Deal legume cultivation incentive continuity, with deviation risk concentrated in Canadian drought frequency and extrusion equipment supplier concentration. Practitioners should keep alternative scenarios live as EFSA protein claim thresholds and front-of-pack labeling mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Australia Soy Protein Market
Ingredients
Soy Lecithin Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Bean Ingredients Market
Ingredients
Corn Oil Cake Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
High Protein Flour Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
Edible Fiber Market
Ingredients
Textured Soy Flour Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Salt Content Reduction Ingredients Market
Ingredients
North America Potato Starch Market