
 US Frozen Dessert Market | 2026-2036
US Frozen Dessert Market Size, Share, and Industry Trends Forecast 2026-2036
US Frozen Dessert Market Intelligence
Clean-label sourcing pressure from major retail buyers is hardening formulation standards across the industry. Unilever leverages its North American R&D network to develop reduced-sugar ice cream platforms. Nestlé anchors its portfolio in functional ingredient innovation, while Blue Bell Creameries sustains regional manufacturing scale across the Southern states.
Frozen dessert denotes a category of sweet, frozen preparations manufactured through controlled crystallization of dairy or non-dairy bases, typically containing 10-16% milkfat for ice cream and stabilized through homogenization at 150-200 bar pressure. The primary commercial purpose centers on delivering portion-controlled indulgence with extended shelf stability through sub-zero distribution. Ice cream occupies the dominant margin pool given its volume scale and premium pricing latitude, while frozen yogurt competes fastest in health-positioned retail channels. Gelato and sorbet segments concentrate in specialty stores and café direct-to-consumer formats where flavor intensity commands price premiums.
FDA nutrition labeling mandates, USDA dairy grade standards, and state-level dairy plant inspection regimes collectively govern product composition claims and interstate commerce eligibility. These frameworks elevate compliance costs for smaller processors while creating barrier effects that favor scaled operators with dedicated regulatory affairs capacity. Stakeholders must monitor evolving added-sugar disclosure thresholds and plant-based labeling petitions that could recategorize non-dairy frozen dessert formulations.
Market Dynamics
FDA's updated Nutrition Facts labeling requirements for added sugars are forcing reformulation across portfolios, while supermarket chains simultaneously expand freezer aisle allocations for premium frozen yogurt. This dual pressure squeezes mid-tier processors lacking R&D scale.
Growth Catalysts
- Clean-label sourcing mandates:Major retail buyers are hardening formulation standards, compelling processors to eliminate artificial stabilizers and synthetic colorants from frozen dessert bases.
- Functional ingredient innovation:Probiotic cultures and protein fortification are expanding frozen yogurt's health-positioned appeal in metropolitan retail corridors.
- California dairy processing corridor concentration:Proximity to fluid milk supply and cold-chain infrastructure reduces logistics costs for scaled ice cream manufacturers.
Market Restraints
- Dairy input cost volatility:Butterfat and milk powder pricing swings compress margins for processors without forward-contracting capabilities.
- FDA compliance cost escalation:Added-sugar disclosure thresholds and plant-based labeling petitions elevate regulatory affairs spending disproportionately for smaller operators.
- Non-dairy frozen dessert substitution:Oat and coconut milk bases are capturing shelf space in premium channels, threatening traditional ice cream volume.
Strategic Opportunities
- Texas metropolitan retail corridors:Population inflow and limited incumbent presence create whitespace for regional frozen yogurt expansion.
- Café direct-to-consumer formats:Gelato and sorbet segments command price premiums through flavor intensity in specialty store channels.
- USDA dairy grade standards alignment:Premium grading certification enables processors to access institutional foodservice contracts with specification requirements.
Industry Challenges
- Homogenization pressure calibration:150-200 bar processing specifications require skilled maintenance technicians scarce in rural dairy plant locations.
- Sub-zero distribution infrastructure:Cold-chain integrity investments strain capital allocation for processors expanding beyond regional footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Frozen Dessert Market |
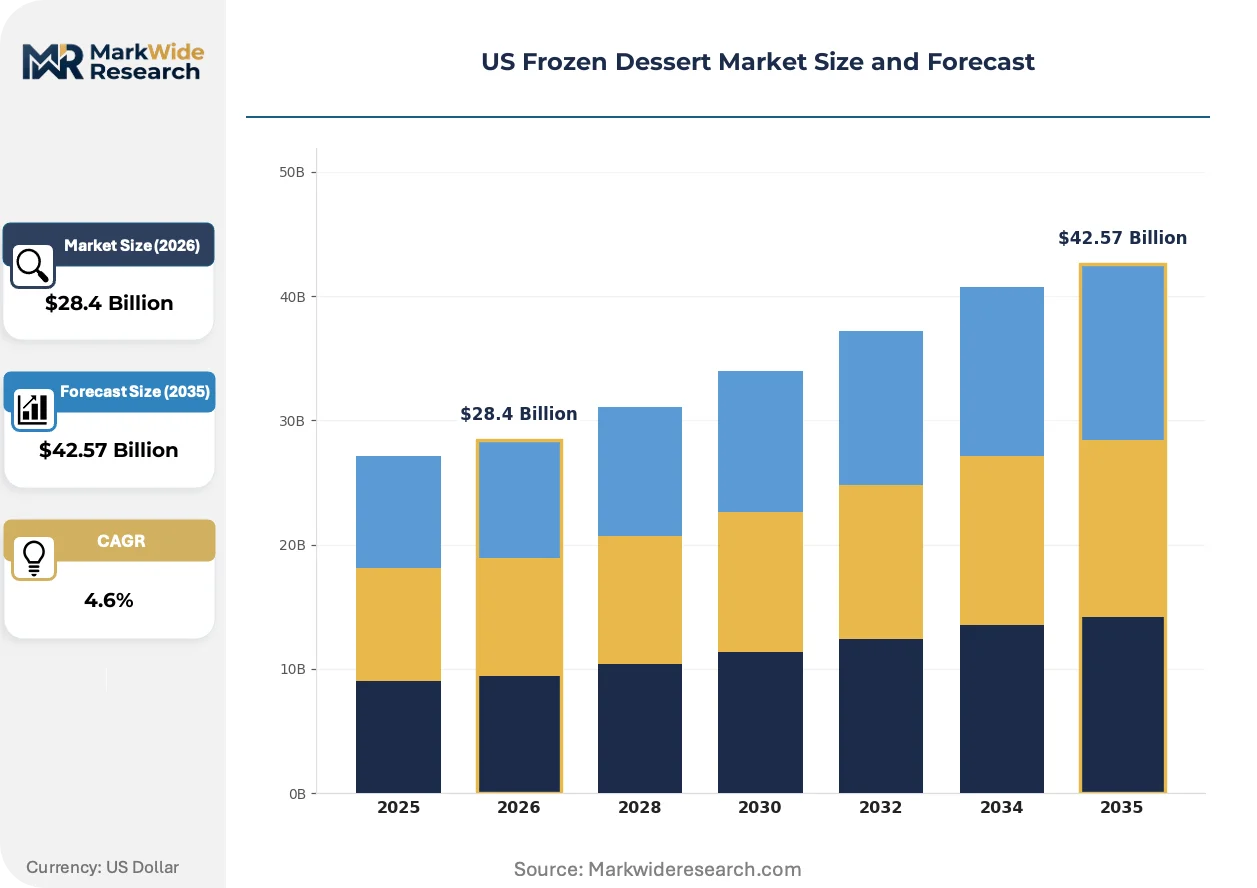
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $42.57 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream, Sorbet, Gelato, Frozen Yogurt Customer Type: Retail Consumers, Food Service, Restaurants, Cafés Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Flavor Profile: Chocolate, Vanilla, Strawberry, Mint, Others |
| Companies Covered | Froneri International Limited, Wells Enterprises, Inc., Unilever, Mars, Kraft Heinz, Nestlé, Blue Bell Creameries, Dairy Farmers of America, Inc., General Mills, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Frozen Dessert Market Strategic Shifts & Innovations
Controlled crystallization technologies and alternative base formulations are compressing traditional category boundaries between dairy and non-dairy frozen desserts. Processors must now engineer texture parity across fundamentally different fat structures.
High-pressure processing is unifying microbial safety assurance with clean-label positioning. Mid-scale frozen dessert manufacturers are adopting HPP systems to eliminate thermal pasteurization while extending shelf stability. This convergence is compressing the cost gap between artisan and industrial production methods.
FDA's added-sugar disclosure mandates are redrawing formulation roadmaps. Processors must now recalculate sweetness delivery through non-nutritive alternatives or reduced-sugar bases. Ice cream portfolios face the steepest reformulation burden given their historical reliance on sucrose for freezing-point depression and scoopability.
Health-positioned retail channels are fragmenting traditional supermarket dominance. Frozen yogurt and functional dessert buyers increasingly source through specialty grocers and direct subscription models. California and Texas metropolitan clusters exhibit the most pronounced channel diversification, with conventional freezer aisle traffic flattening in these markets.
US Frozen Dessert Market Segmentation
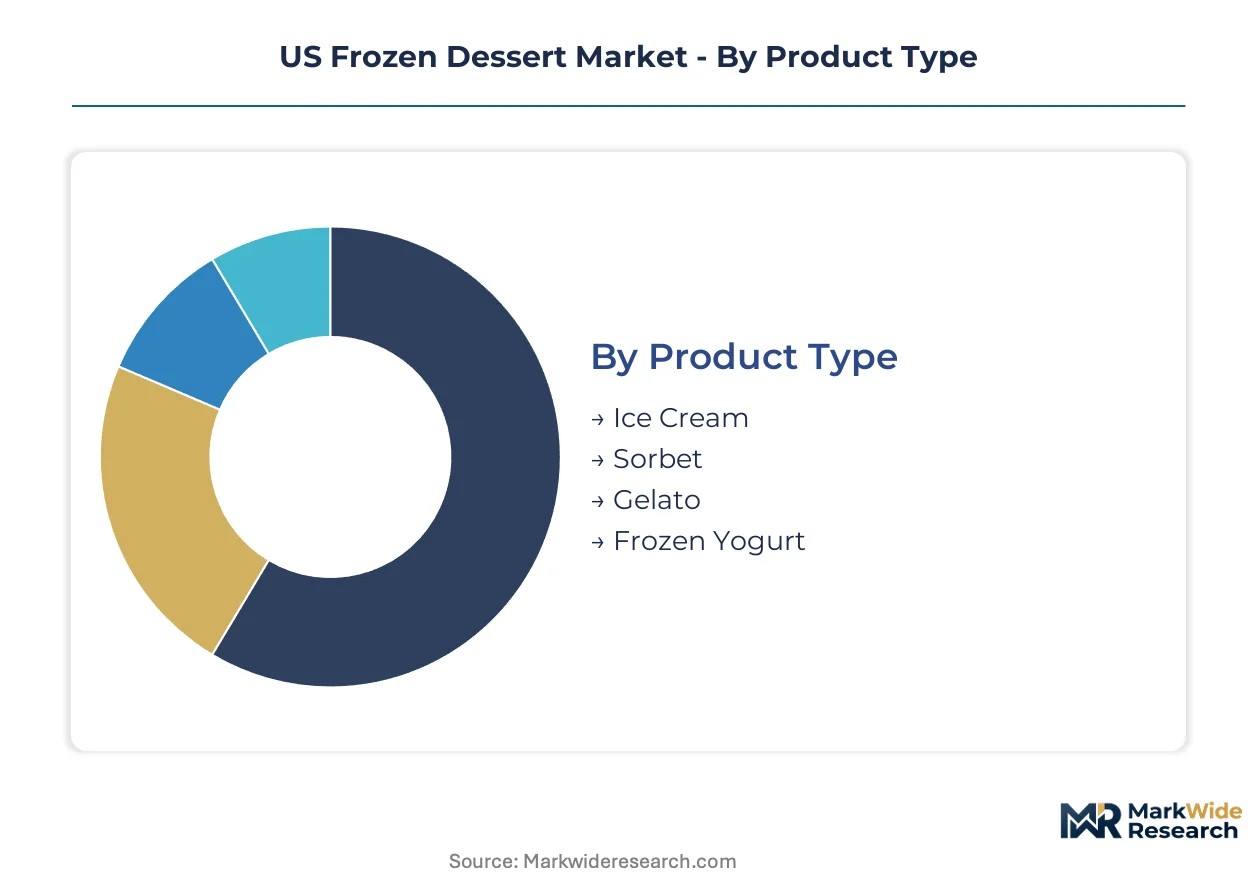
Frozen dessert processors segment portfolios across four intersecting dimensions that determine pricing latitude and channel access. Product composition and customer type together govern margin structure, while distribution reach and flavor innovation drive volume velocity in competing retail formats.
Product Type:
Volume concentration favors mass-market ice cream, but premium positioning accelerates fastest in health-oriented alternatives.
- Ice Cream:Standard formulations contain 10-16% milkfat stabilized through homogenization at 150-200 bar pressure. California's dairy processing corridor anchors scaled production for supermarket chains, though FDA's added-sugar disclosure mandates are forcing sucrose reduction across legacy portfolios.
- Frozen Yogurt:Probiotic cultures and protein fortification expand health-positioned appeal in Texas metropolitan retail corridors where incumbent presence remains limited. Clean-label sourcing pressure from major retail buyers is hardening formulation standards fastest in this segment.
- Sorbet:Fruit-based non-dairy formulations command price premiums through flavor intensity in specialty store and café direct-to-consumer channels.
- Gelato:Dense, low-overrun preparations concentrate in specialty stores where artisan positioning justifies higher per-unit pricing than standard ice cream.
Today's leader: Ice Cream. Tomorrow's challenger: Frozen Yogurt.
Customer Type:
Channel diversification fragments traditional supermarket dominance as health-positioned buyers migrate toward direct and specialty formats.
- Retail Consumers:Supermarket freezer aisle allocations for premium frozen yogurt are expanding, but subscription models and specialty grocer channels are capturing health-conscious households in California and Texas metropolitan clusters.
- Food Service:Institutional contracts require USDA dairy grade standards alignment, elevating compliance costs that favor scaled processors with dedicated regulatory affairs capacity.
- Restaurants:Menu placement of gelato and sorbet supports dessert course pricing in full-service formats where portion-controlled indulgence drives check average.
- Cafés:Direct-to-consumer formats concentrate gelato and sorbet segments where flavor intensity commands premiums unavailable in conventional retail.
Food Service locks in volume through contract specifications. Cafés capture margin through experiential positioning.
Distribution Channel:
Cold-chain infrastructure requirements strain capital allocation as processors expand beyond regional footprints into national distribution.
- Supermarkets:Expanded freezer aisle allocations for premium frozen yogurt compete with oat and coconut milk non-dairy alternatives capturing shelf space in premium channels.
- Convenience Stores:Impulse-oriented single-serve formats prioritize ice cream novelty items with extended shelf stability through sub-zero distribution.
- Online Retail:Direct subscription models fragment conventional freezer aisle traffic, particularly in California and Texas where channel diversification is most pronounced.
- Specialty Stores:Gelato and sorbet segments command price premiums through flavor intensity unavailable in mass-market formats.
Supermarkets defend volume share. Online Retail climbs fastest in customer acquisition economics.
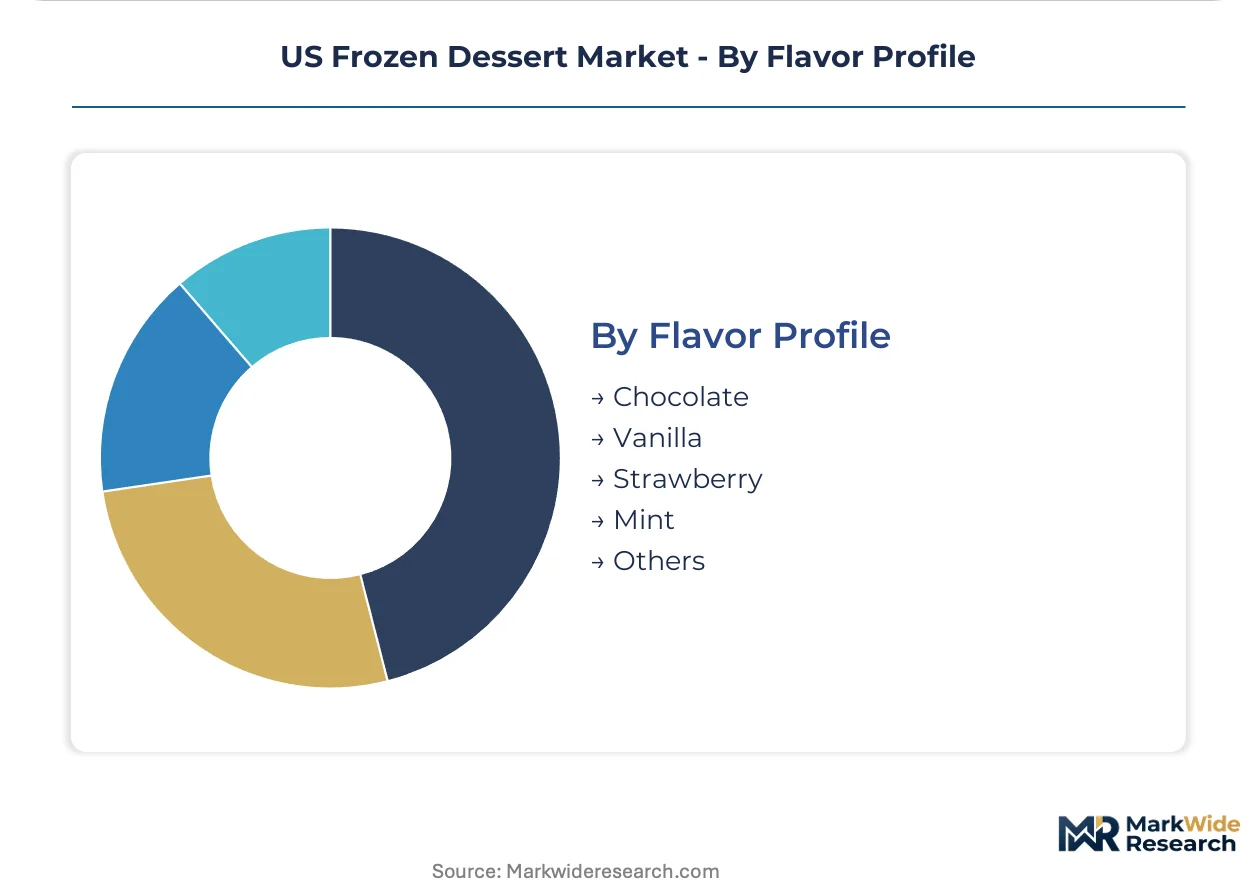
Flavor Profile:
Classic profiles anchor volume, but limited-edition and functional flavor extensions drive trial and premium pricing.
- Chocolate:Cocoa butter and chocolate liquor formulations face dairy input cost volatility from butterfat pricing swings, compressing margins for processors without forward-contracting capabilities.
- Vanilla:Madagascar and Tahitian bean sourcing concentrates clean-label sourcing pressure, with major retail buyers hardening formulation standards around artificial vanillin elimination.
- Strawberry:Fruit inclusion requires high-pressure processing adoption for microbial safety assurance without thermal degradation of flavor compounds.
- Mint:Peppermint oil and extract formulations compete in seasonal novelty rotations with limited-edition pipeline velocity.
- Others:Salted caramel, cookie dough, and functional ingredient extensions expand frozen yogurt's health-positioned appeal through protein fortification and probiotic cultures.
Chocolate and Vanilla lock in baseline volume. Others category gains share fastest through innovation cycle velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US frozen dessert industry traces its scaled manufacturing roots to the dairy-rich Midwest and Northeast corridors of the early twentieth century, where fluid milk access and rail distribution networks first enabled national ice cream brands. California's post-war agricultural expansion and Texas's metropolitan growth subsequently reoriented production gravity toward the Sun Belt.
California
California's dairy processing corridor anchors fluid milk supply for scaled ice cream manufacturing, with cold-chain infrastructure reducing logistics costs for national distribution. FDA's updated Nutrition Facts labeling requirements for added sugars are forcing portfolio reformulation among processors headquartered in the Central Valley. The Los Angeles-San Diego metropolitan cluster exhibits the most pronounced channel diversification, with conventional freezer aisle traffic flattening as specialty grocer and direct subscription models capture health-conscious households.
Texas
Texas metropolitan retail corridors concentrate demand growth for premium frozen yogurt, where population inflow and limited incumbent presence create whitespace for regional expansion. State-level dairy plant inspection regimes govern interstate commerce eligibility, elevating compliance costs that favor scaled operators with dedicated regulatory affairs capacity. The Dallas-Fort Worth and Houston metro areas drive fastest growth in health-positioned retail channels, with supermarket chains expanding freezer aisle allocations for probiotic-fortified formulations.
New York Metro
The New York metropolitan area sustains institutional foodservice demand through USDA dairy grade standards alignment, enabling processors to access contracts with specification requirements for premium grading certification. FDA compliance cost escalation for added-sugar disclosure thresholds disproportionately burdens smaller operators in this high-rent market. Brooklyn and Queens harbor specialty gelato and sorbet production for café direct-to-consumer formats where flavor intensity commands price premiums unavailable in mass-market channels.
Midwest
The Midwest dairy belt—spanning Wisconsin, Illinois, and Michigan—maintains regional manufacturing scale through proximity to butterfat and milk powder supply, though input cost volatility compresses margins for processors without forward-contracting capabilities. USDA dairy grade standards and interstate commerce frameworks collectively govern product composition claims for processors shipping across state lines. Chicago anchors distribution hub operations, with sub-zero distribution infrastructure investments straining capital allocation for operators expanding beyond regional footprints into national cold-chain networks.
Southeast
The Southeast corridor—centered on Florida and Georgia—exhibits growing demand for frozen dessert novelty items in convenience store impulse formats, prioritizing extended shelf stability through sub-zero distribution. State-level dairy plant inspection regimes vary across the region, creating compliance complexity for processors with multi-state manufacturing footprints. Atlanta and Miami metropolitan areas concentrate foodservice distribution for restaurant dessert course placement, where portion-controlled indulgence drives check average in full-service formats.
US Frozen Dessert Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation sophistication and clean-label positioning, with the market consolidating around scaled multinational portfolios and regional heritage brands. The competitive terrain splits between diversified consumer goods conglomerates with dedicated frozen dessert divisions and specialized creameries with geographic concentration in specific dairy corridors. Three archetypes dominate: multinational platform operators leveraging North American R&D networks, regional manufacturing specialists sustaining Southern or Midwestern production scale, and private-label suppliers serving retail buyer consolidation. Dominant competitive moves include portfolio reformulation to meet FDA added-sugar disclosure mandates and strategic freezer aisle allocation negotiations with supermarket chains.
Within the multinational platform tier, Unilever and Nestlé exemplify archetypes diverging across innovation vectors—Unilever anchoring reduced-sugar ice cream development through its North American R&D network, Nestlé concentrating functional ingredient innovation with probiotic cultures and protein fortification. Blue Bell Creameries occupies a position as the regional manufacturing specialist archetype, sustaining production scale across Southern states with heritage brand equity. Among diversified consumer goods operators, Mars and Kraft Heinz sit within portfolio adjacency strategies that treat frozen dessert as one indulgence category among multiple snacking platforms.
| Leading Market Players |
|---|
| Froneri International Limited |
| Wells Enterprises, Inc. |
| Unilever |
| Mars |
| Kraft Heinz |
| Nestlé |
| Blue Bell Creameries |
| Dairy Farmers of America, Inc. |
| General Mills |
| Others |
Cost & Logistics Intelligence
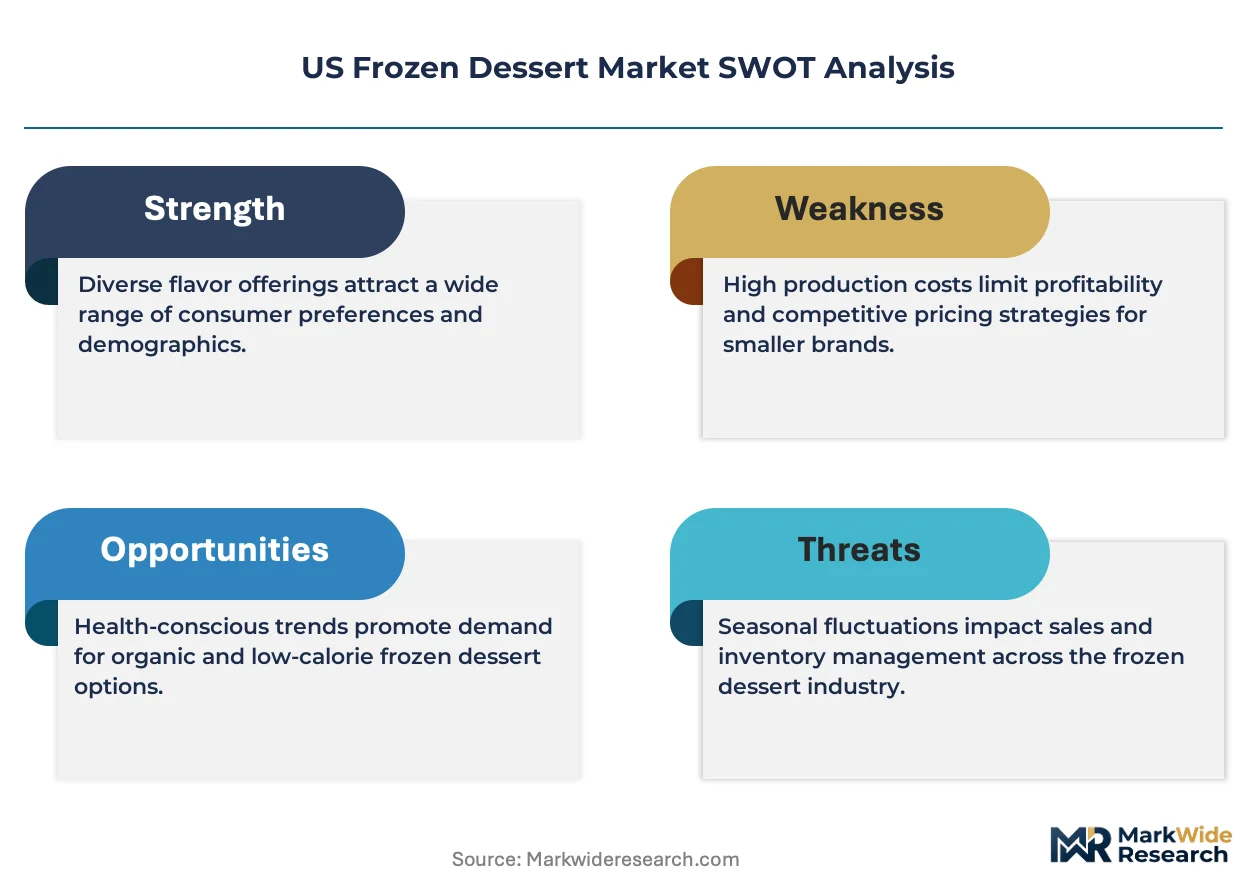
Clean-label sourcing mandates from major retail buyers are forcing processors to eliminate artificial stabilizers and synthetic colorants, compelling supply base consolidation around certified ingredient suppliers and compressing margins for mid-tier operators without scale purchasing power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA Grade A certified products from commercial grade and private-label tiers. Price differentiation rests on clean-label certification and regional brand heritage, with premium tiers commanding latitude through probiotic fortification claims. Cost compression in the standard tier is intensifying because butterfat and milk powder pricing swings compress margins for processors lacking forward-contracting capabilities. Foodservice buyers exhibit highest price sensitivity due to contract specification requirements, while café direct-to-consumer channels show lowest sensitivity where flavor intensity justifies per-scoop premiums.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised inventory create specialized cold-chain recovery networks serving foodservice redistribution channels. Geographic supply concentration centers on California's Central Valley dairy processing corridor, Wisconsin's butterfat production belt, and Texas metropolitan distribution hubs. Raw material dependencies draw from fluid milk supply, Madagascar and Tahitian vanilla bean imports, and cocoa butter sourcing. Single-source vulnerability in natural flavor extract imports from specific equatorial regions elevates procurement risk. Distribution runs through supermarket chain direct-store-delivery systems and third-party cold-chain logistics providers maintaining sub-zero integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's concentration of fluid milk supply and cold-chain infrastructure against Texas's limited incumbent presence and population inflow creates a geographic-arbitrage window for processors optimizing production location against demand growth corridors.
For Market Incumbents: Anchor defensive positioning through backward integration into fluid milk supply contracts in the Central Valley and certification investment for USDA dairy grade standards alignment. Oat and coconut milk non-dairy substitution threatens traditional ice cream volume, making channel control through exclusive supermarket freezer aisle allocation negotiations the critical lever for margin defense. For New Entrants and Emerging Players: Capture whitespace in Texas metropolitan retail corridors where population inflow and limited incumbent presence create expansion opportunity for probiotic-fortified frozen yogurt formats. Health-positioned retail channels in Dallas-Fort Worth and Houston represent the most penetrable geography. Direct-to-consumer subscription models offer the strongest go-to-market angle for customer acquisition economics. For Investors and Strategic Acquirers: Asymmetric upside sits with regional manufacturing specialists possessing heritage brand equity and Southern state production scale. Long-term viability over the five-to-ten year window favors processors with dedicated regulatory affairs capacity navigating FDA added-sugar disclosure mandates. Acquisition targets should concentrate on scaled operators with clean-label certification infrastructure. Plant-based labeling petition outcomes serve as the critical signal to watch for category recategorization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | Elimination of artificial stabilizers satisfies Walmart and Kroger sourcing mandates while opening premium channel access. |
| Probiotic Fortification Platform | Functional ingredient innovation captures health-positioned demand in Texas metropolitan retail corridors. |
| Backward Integration into Fluid Milk Supply | Captive supply of California Central Valley dairy reduces butterfat cost volatility exposure. |
| USDA Grade A Certification Investment | Premium grading qualification enables institutional foodservice contract access with specification requirements. |
| Direct-to-Consumer Subscription Launch | Channel diversification captures health-conscious households in Los Angeles-San Diego cluster beyond conventional retail. |
Research Approach
Direct dialogue with frozen dessert plant managers, supermarket category buyers, dairy procurement leads, and regulatory affairs directors combined with secondary validation from FDA filings, USDA dairy grade reports, Nielsen retail audit data, and customs import records. Bottom-up and top-down triangulation cross-validated volume estimates against production capacity disclosures and channel shipment data.
Bottom-up modeling anchored projections across product type, customer channel, distribution format, and flavor profile dimensions, while top-down macroeconomic drivers calibrated aggregate market expansion. CAGRs were derived through trend extrapolation of historical volume trajectories adjusted for regulatory inflection points and channel migration patterns. Forecast inputs incorporated FDA added-sugar disclosure implementation timelines and cold-chain infrastructure investment cycles.
Butterfat pricing volatility, plant-based labeling petition outcomes, and supermarket buyer consolidation are the dominant revision risks to modeled projections. Practitioners should monitor dairy futures contract spreads, FDA guidance document releases, and category buyer merger activity for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Frozen Meat Market