
 Europe Dairy Alternatives Market | 2026-2036
Europe Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dairy Alternatives Market Analysis
Supermarket dairy aisles across Europe is rewriting how consumers discover plant-based beverages, with chilled sections now commanding premium positioning formerly reserved for conventional milk. Danone S.A. leverages its refrigerated logistics network to dominate French and Benelux retail. Oatly Group AB anchors its growth through barista-grade formulations that secure placement in specialty coffee chains. Alpro competes aggressively on price in the private-label supply channel, sustaining volume across British and German supermarkets.
Europe dairy alternatives comprise non-beverage formulations derived from oats, almonds, soy, or coconut, processed through enzymatic hydrolysis and homogenization to achieve protein stability and mouthfeel parity with animal-derived dairy. These products serve commercial food manufacturing, foodservice recipe bases, and direct retail consumption where lactose intolerance, vegan preference, or environmental concern drives substitution. Oat milk leads liquid formulations due to neutral flavor and lower allergenicity, while yogurt forms capture expanding margin pools as cultured plant-based products achieve texture breakthroughs. Powder segments remain niche but sustain demand from food manufacturers seeking extended shelf stability for bakery and confectionery applications.
The EU Green Deal's Farm to Fork Strategy shapes product development timelines by mandating front-of-pack environmental scoring, while EFSA governs nutritional claim substantiation for calcium and vitamin fortification. REACH compliance adds formulation complexity for imported coconut and almond raw materials, particularly affecting suppliers sourcing from outside the European Economic Area. Stakeholders must monitor evolving EU-wide labeling harmonization proposals that could reset competitive advantage between established brands and private-label entrants.
Market Dynamics
EU Green Deal's Farm to Fork Strategy forces reformulation timelines as front-of-pack environmental scoring mandates compress product development cycles. Food manufacturers now redesign supply chains to capture lower-carbon oat and almond inputs ahead of labeling harmonization.
Growth Catalysts
- EFSA Nutritional Claim Pathways:Calcium and vitamin fortification approvals enable premium positioning for fortified oat beverages in German and French retail channels.
- Barista-Grade Formulation Demand:Specialty coffee chains across Italy and Spain expand plant-based milk contracts, pulling enzymatic hydrolysis capacity toward neutral-flavor oat concentrates.
- REACH Compliance Infrastructure:Established importers of coconut and almond raw materials leverage pre-registered substance dossiers to lock out new entrants from Southeast Asian supply sources.
Market Restraints
- Input Cost Volatility:Almond harvest fluctuations in California and Spain create margin pressure for European processors dependent on imported nut protein concentrates.
- Supply Concentration Risk:Enzymatic processing capacity clusters in Denmark and the Netherlands, creating bottlenecks for oat milk brands seeking toll manufacturing agreements.
- Technical Limitation:Cultured plant-based yogurt textures fail to match dairy mouthfeel at industrial scale, capping category expansion in refrigerated dessert segments.
Strategic Opportunities
- Underpenetrated Eastern European Retail:Polish and Romanian supermarket chains lack dedicated chilled plant-based aisles, offering first-mover shelf space advantages for oat beverage brands.
- CSRD Reporting Integration:Corporate sustainability disclosure mandates drive B2B demand for traceable oat and coconut ingredients in food manufacturing procurement.
- Powder Segment Innovation:Extended-shelf-stable formulations target bakery and confectionery manufacturers seeking to reduce refrigerated logistics costs across Nordic markets.
Industry Challenges
- Formulation Talent Scarcity:Protein stability expertise for enzymatic hydrolysis remains concentrated among Danish and Dutch food technology specialists, constraining R&D expansion.
- Certification Timeline Compression:Pending EU-wide labeling harmonization proposals force parallel track development for multiple front-of-pack scoring systems.
- Legacy Dairy Equipment Retrofit:Homogenization and UHT lines require stainless steel modifications to prevent cross-contamination in mixed dairy-plant facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dairy Alternatives Market |
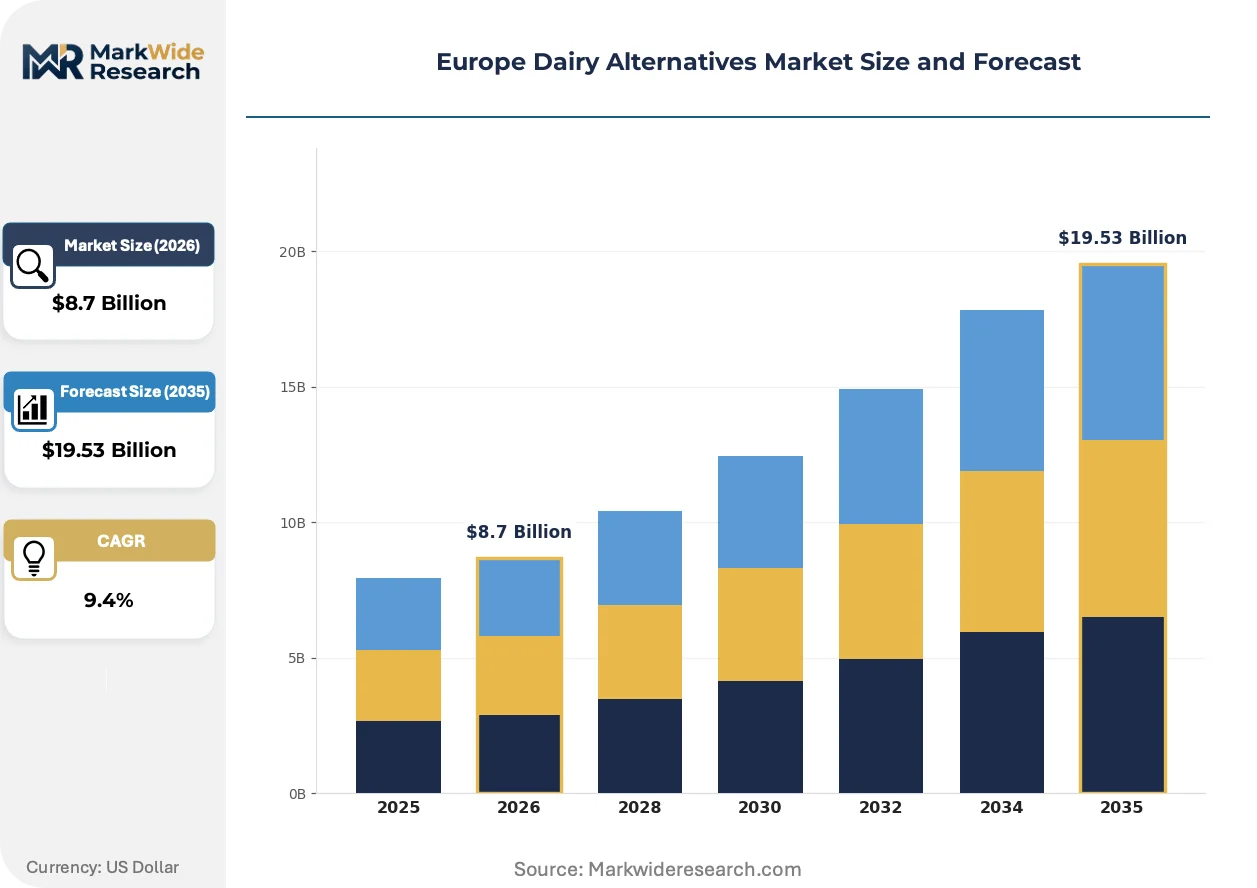
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Form: Liquid, Powder, Cream, Yogurt End User: Retail Consumers, Foodservice, Food Manufacturers, Health Stores Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Oatly Group AB, Danone S.A., Alpro, Blue Diamond Growers, The Hain Celestial Group Inc., Califia Farms LLC, Upfield Holdings BV, Ecotone, Granarolo S.p.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dairy Alternatives Market Emerging Trajectories
Formulation science is converging with sustainability metrics as enzymatic processing and carbon accounting tools merge in product development workflows. This fusion redefines competitive advantage away from flavor alone toward verified environmental performance.
Fermentation-derived protein concentrates are hybridizing with traditional plant bases to improve amino acid completeness and reduce off-flavors in neutral-taste applications. Specialty coffee roasters in Berlin and Amsterdam adopt these hybrid oat-ferment blends for latte art stability. The technology is compressing the performance gap between commodity oat milk and premium barista formulations.
EU Green Deal's Farm to Fork Strategy mandates front-of-pack environmental scoring by 2025, forcing reformulation priorities toward lower-carbon oat sourcing over almond. Food manufacturers in France and Benelux restructure procurement contracts to secure Swedish and Finnish oat supplies with verified carbon footprints. Dairy alternative brands with pre-established lifecycle assessment data capture shelf space ahead of compliance deadlines.
Foodservice procurement contracts now unbundle plant-based milk from traditional dairy supply agreements, enabling direct sourcing relationships with oat processors. Independent coffee chains in London and Copenhagen bypass broadline distributors to negotiate volume commitments with specialized oat beverage suppliers. This disintermediation concentrates purchasing power among mid-sized roaster networks seeking exclusive formulation partnerships.
Europe Dairy Alternatives Market Segmentation
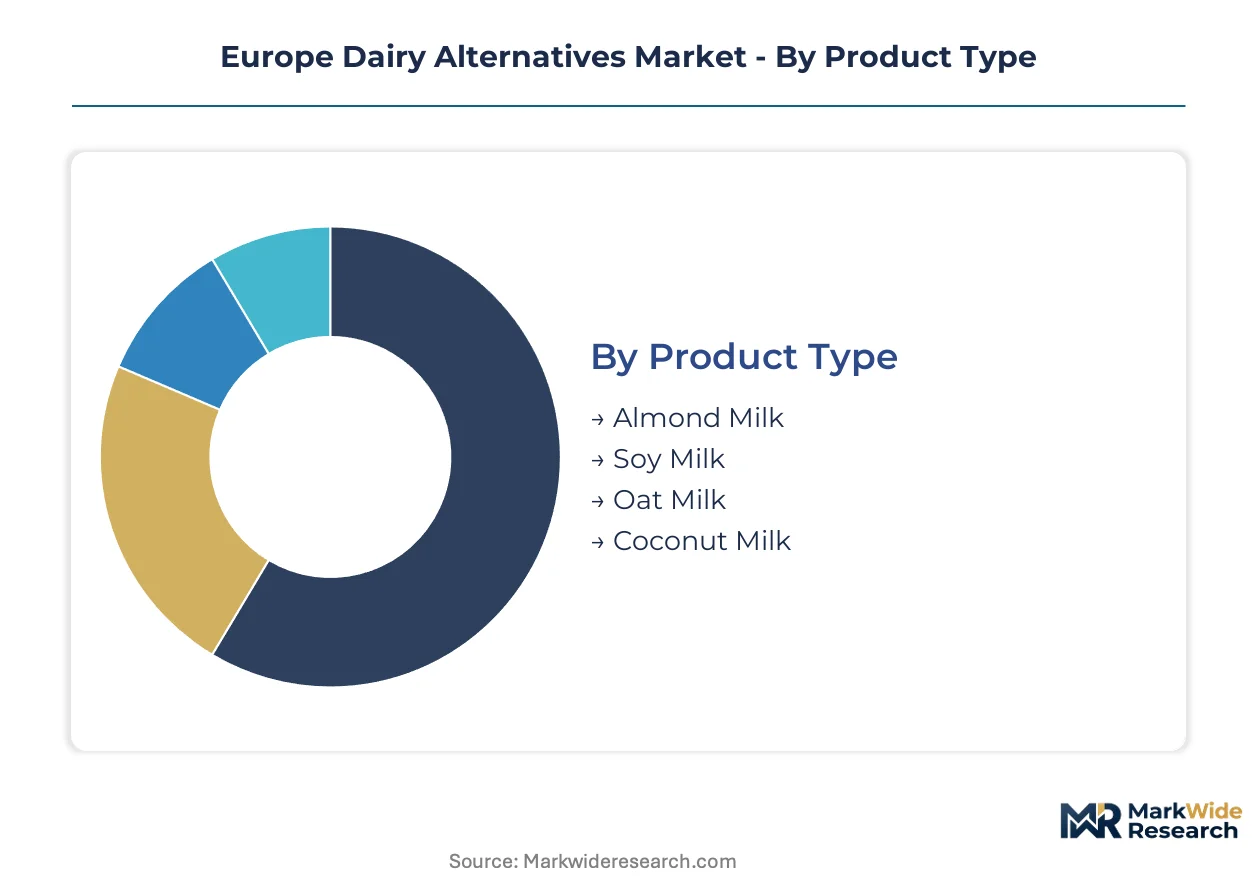
Product differentiation across Europe's dairy alternatives sector hinges on formulation stability and chilled distribution reach. Segmentation reveals where margin pools concentrate versus where volume scales fastest.
Product Type:
Oat milk commands the shortest innovation cycle as barista-grade specifications evolve quarterly, while coconut milk formulations turn over slowest due to entrenched tropical flavor preferences in Southern Europe.
- Oat Milk:Enzymatically hydrolyzed oat concentrates achieve neutral flavor profiles through beta-glucan stabilization. German and Dutch retailers dedicate expanding chilled shelf space to barista-grade variants as specialty coffee chains in Berlin and Amsterdam lock in exclusive supply contracts.
- Almond Milk:Blanched almond protein concentrates deliver lower caloric density but face supply volatility from California and Spanish harvest fluctuations. French retail channels favor almond for its established consumer recognition, though EFSA fortification claim timelines delay premium positioning.
- Soy Milk:Isoflavone-rich formulations retain cost leadership in Eastern European price-sensitive markets.
- Coconut Milk:Lauric acid profiles suit cooking applications in Italian and Spanish food manufacturing.
Oat milk anchors the volume base while oat milk gains share at the steepest rate.
Form:
Margin tiers separate formats by processing intensity and cold-chain dependency, with powders commanding logistics savings and refrigerated liquids capturing shelf-space premiums.
- Liquid:UHT and ESL processing lines dominate capital deployment as enzymatic hydrolysis capacity clusters in Denmark and the Netherlands. Chilled distribution networks in France and Benelux determine competitive access to retail placement.
- Yogurt:Cultured plant-based formulations require fermentation infrastructure and texture-modifying hydrocolloids. German consumers drive demand for spoonable formats as Alpro and Danone expand refrigerated dessert sections.
- Powder:Spray-dried oat and coconut bases target bakery and confectionery manufacturers seeking extended shelf stability.
- Cream:Higher-fat emulsions serve foodservice whipping applications in Nordic markets.
Liquid formats generate the revenue base while yogurt climbs fastest on texture breakthroughs.
End User:
Procurement sophistication varies sharply across buyer types, with food manufacturers demanding batch certification and retail consumers responding to front-of-pack environmental scoring.
- Foodservice:Coffee chains and institutional caterers unbundle plant-based milk from traditional dairy supply agreements. Independent roasters in London and Copenhagen negotiate direct volume commitments with specialized oat processors, bypassing broadline distributors.
- Food Manufacturers:Industrial buyers require REACH-compliant documentation and carbon footprint verification under CSRD procurement mandates. Swedish and Finnish oat suppliers with verified lifecycle data capture contract renewals from French and Benelux manufacturers.
- Retail Consumers:German supermarket shoppers prioritize EFSA-approved calcium fortification claims.
- Health Stores:Specialty channels in Austria and Switzerland emphasize organic certification tiers.
Foodservice anchors the volume base while food manufacturers expand most quickly on sustainability compliance.
Distribution Channel:
Channel concentration reflects cold-chain infrastructure maturity, with supermarkets controlling chilled placement and online platforms capturing subscription-driven repeat purchases.
- Supermarkets:Chilled dairy aisle repositioning in Germany and France grants premium eye-level placement to plant-based beverages. Danone leverages refrigerated logistics dominance to secure multi-brand facings across Carrefour and REWE networks.
- Online:Direct-to-consumer subscriptions concentrate in urban UK and German markets where pantry stocking preferences favor ambient-stable multi-packs. Oatly and Alpro deploy proprietary apps to capture first-party consumption data.
- Specialty Stores:Organic and vegan-focused retailers in Netherlands and Belgium curate premium-tier assortments.
- Wholesale:Foodservice distributors in Italy and Spain consolidate plant-based milk into broadline catalogs.
Supermarkets anchor the volume base while online gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites the Netherlands' central role in distributing enzymatically processed oat concentrates across the continent. Rail links from Danish processing clusters feed into this hub, enabling rapid replenishment of German and French retail channels.
Germany
REWE and Edeka supermarket chains command dedicated chilled aisle space for barista-grade oat beverages. The EU Green Deal's Farm to Fork Strategy mandates front-of-pack environmental scoring that favors lower-carbon Swedish oat supplies. Berlin's specialty coffee roasters negotiate direct volume commitments with toll processors, bypassing traditional distribution layers.
France
Carrefour's refrigerated logistics network secures premium eye-level placement for fortified plant-based yogurts. EFSA governs calcium and vitamin fortification claim substantiation, compressing product development timelines for cultured formulations. The Lyon-Toulouse corridor clusters enzymatic hydrolysis R&D facilities serving French and Benelux manufacturers.
United Kingdom
Tesco and Sainsbury's unbundle plant-based milk from traditional dairy supply agreements, enabling direct sourcing relationships. The country's departure from EU labeling harmonization creates parallel compliance tracks for domestic versus export-bound production. London's independent coffee chains anchor demand for neutral-flavor oat concentrates with latte art stability.
Netherlands
Alpro's private-label supply channel sustains volume across British and German supermarkets through aggressive price positioning. REACH compliance infrastructure for imported coconut and almond raw materials leverages pre-registered substance dossiers. The Amsterdam-Rotterdam port complex concentrates toll manufacturing capacity for enzymatic processing of oat and almond protein concentrates.
Italy
Specialty coffee chains across Milan and Rome expand plant-based milk contracts, pulling enzymatic hydrolysis capacity toward neutral-flavor formulations. Lauric acid profiles in coconut milk retain entrenched tropical flavor preferences in Southern European cooking applications. The Po Valley food manufacturing belt integrates spray-dried oat bases into bakery and confectionery supply chains.
Europe Dairy Alternatives Market Vendor Landscape
On the supply side, the industry is consolidating around refrigerated logistics dominance and enzymatic processing capacity concentration. Established players leverage pre-registered REACH substance dossiers to lock out new entrants from Southeast Asian supply sources. Three strategic archetypes define positioning: dairy conglomerates with cold-chain infrastructure, specialized oat processors with barista-grade formulation expertise, and private-label suppliers competing on price. Dominant competitive moves include backward integration into Swedish and Finnish oat sourcing with verified carbon footprints, and exclusive supply partnerships with specialty coffee roasters in Berlin and Amsterdam.
Within the specialized oat processing tier, Oatly Group AB exemplifies the barista-grade formulation archetype through its neutral-flavor concentrate technology. Danone S.A. occupies the dairy conglomerate position, leveraging refrigerated logistics networks to secure multi-brand facings across major retail chains. Alpro anchors the private-label supply channel, sustaining volume through aggressive price positioning in British and German supermarkets.
| Leading Market Players |
|---|
| Oatly Group AB |
| Danone S.A. |
| Alpro |
| Blue Diamond Growers |
| The Hain Celestial Group Inc. |
| Califia Farms LLC |
| Upfield Holdings BV |
| Ecotone |
| Granarolo S.p.A. |
| Others |
Supply Flow & Price Mechanics
Amsterdam-Rotterdam port complex capacity dynamics grant established oat processors substantial pricing power over new entrants seeking toll manufacturing agreements. Enzymatic hydrolysis infrastructure concentration in this hub compresses margins for brands without pre-negotiated capacity, while REACH-registered importers of coconut and almond raw materials extract premiums from buyers lacking compliant substance dossiers.
Pricing Analysis
Volume-discount tiering structures separate barista-grade oat concentrates from commodity UHT formulations, with specialty coffee chains in Berlin and Amsterdam locking annual contracts at 15-20% below spot rates. Price differentiation hinges on EFSA-approved fortification claims and verified carbon footprint certification under EU Green Deal scoring mandates. Pricing pressure stems from almond harvest volatility in California and Spain, which squeezes mid-tier processors dependent on imported nut protein. Private-label suppliers in British supermarkets exhibit highest price sensitivity, while fortified yogurt brands in French retail channels absorb premiums for calcium and vitamin positioning.
Supply Chain Analysis
Upstream feedstock flows concentrate on Swedish and Finnish oat cultivation regions, Spanish almond orchards, and Southeast Asian coconut plantations. Raw material dependencies include beta-glucan-stabilized oat concentrates, blanched almond protein isolates, and lauric acid-rich coconut cream. Single-source vulnerability clusters in Danish and Dutch enzymatic processing capacity, where toll manufacturing bottlenecks constrain oat milk brand expansion. Distribution runs through refrigerated logistics networks anchored by Danone's French cold-chain infrastructure and REWE's German retail replenishment systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where REACH compliance infrastructure and pre-registered substance dossiers create regulatory entrenchment that locks out new entrants from Southeast Asian supply sources.
For Market Incumbents: Insulate market position by deepening backward integration into Swedish oat sourcing with verified lifecycle assessment data ahead of EU-wide labeling harmonization. Expand enzymatic hydrolysis capacity in the Netherlands to capture toll manufacturing demand from mid-sized brands lacking in-house processing. Prioritize exclusive supply partnerships with specialty coffee roasters in Copenhagen and London to preempt competitor access to barista-grade formulation channels.
For New Entrants and Emerging Players: Eastern European retail underpenetration offers first-mover shelf space advantages, as Polish and Romanian supermarket chains lack dedicated chilled plant-based aisles. Target food manufacturing procurement contracts in the Po Valley bakery and confectionery belt, where spray-dried oat bases face limited domestic supply competition. Pursue direct-to-foodservice distribution models that bypass broadline distributors and capture margin from independent coffee chains seeking neutral-flavor oat concentrates.
For Investors and Strategic Acquirers: Carve-out targets emerge from dairy conglomerates seeking to divest non-core plant-based assets amid margin compression in conventional milk. Long-term viability favors specialized oat processors with captive enzymatic capacity and established barista-grade formulation expertise over private-label suppliers exposed to price erosion. Watch for CSRD reporting mandates accelerating B2B demand for traceable ingredients as the inflection signal indicating sustained contract renewal premiums for verified-carbon-footprint suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Oat Sourcing | Secures lower-carbon feedstock with verified lifecycle data ahead of EU Green Deal scoring mandates. |
| Barista-Grade Formulation Partnerships | Locks exclusive supply contracts with specialty coffee chains in Berlin, Amsterdam, and Copenhagen. |
| REACH Compliance Infrastructure Investment | Pre-registers substance dossiers to block new entrants from Southeast Asian coconut and almond sources. |
| Powder Segment Capacity Expansion | Targets bakery and confectionery manufacturers seeking extended shelf stability across Nordic markets. |
| Direct-to-Foodservice Distribution Launch | Bypasses broadline distributors to capture margin from independent roasters unbundling plant-based milk procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA guidance documents, EU Green Deal Farm to Fork Strategy implementation timelines, and REACH substance registration databases. Primary inputs drew from interviews with enzymatic processing plant managers, procurement leads at French and German food manufacturers, category buyers at REWE and Carrefour networks, and regulatory affairs specialists navigating front-of-pack environmental scoring mandates. Secondary validation incorporated customs trade data for oat and almond raw material flows, SEC filings of listed dairy alternative producers, and CSRD disclosure frameworks. Bottom-up segment sizing triangulated against top-down market value estimates.
Forecast inputs span product type segmentation across oat, almond, soy, and coconut formulations; form factors including liquid, yogurt, powder, and cream; end-user categories from foodservice operators to food manufacturers and retail consumers; and distribution channels through supermarkets, online platforms, specialty stores, and wholesale. CAGRs derive from historical growth pattern analysis adjusted for regulatory timeline impacts and supply capacity expansion schedules. Industry-specific inputs include enzymatic hydrolysis capacity utilization rates and EFSA fortification claim approval trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by specialized oat processors or accelerated private-label entry by retail chains would shift outcomes beyond modeled ranges. Almond harvest volatility in California and Spain, pending EU labeling harmonization proposals, and REACH enforcement intensity on imported raw materials constitute primary revision risks. Quarterly review of EFSA claim approval timelines, CSRD procurement mandate adoption rates, and toll manufacturing contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Dry Yogurt Market