
 AKD Emulsifier Market | 2026-2036
AKD Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
AKD Emulsifier Market Outlook
Food-grade specification upgrades is collapsing the gap between commodity and premium AKD emulsifier tiers, forcing reformulation investments across the supply base. BASF SE leverages its integrated alkylene oxide chain to sustain cost-advantaged feedstock access for high-purity grades. DuPont de Nemours, Inc. anchors its position through specialized fluorine-free barrier chemistry that competes directly with conventional AKD sizing in liquid packaging applications.
Alkyl ketene dimer emulsifiers are aqueous dispersions of wax-reactive sizing agents, typically stabilized at 15-30% solids content through cationic starch or synthetic polymer colloids, designed to impart hydrophobicity to cellulose fibers via esterification with hydroxyl groups during drying. Liquid emulsifiers dominate volume consumption in integrated paper mills where continuous processing technology enables inline dilution and minimal storage infrastructure. Powder emulsifiers occupy the fastest-expanding margin pool among regional converters and specialty paperboard manufacturers lacking bulk liquid handling systems.
EPA effluent guidelines for pulp and paper mills in the United States restrict AOX formation from sizing chemistries, while REACH registration requirements in Europe mandate full toxicological dossiers for AKD substances above one-tonne annual thresholds. China's SAMR enforces GB 4806 food contact material standards that limit extractables from paper packaging into fatty food simulants. Stakeholders must monitor regulatory divergence between jurisdictions on per- and polyfluoroalkyl substance restrictions, as these frameworks will determine whether AKD emulsifiers capture or surrender share in grease-resistant packaging applications.
Market Dynamics
Food-grade barrier coating specifications are collapsing the historical separation between commodity and premium AKD emulsifier tiers, forcing simultaneous investments in purification infrastructure and reformulation capabilities across the entire supply base.
Growth Catalysts
- REACH purity mandates:European chemical registration requirements for alkyl ketene dimer substances above one-tonne thresholds are accelerating demand for high-purity grades in liquid packaging board.
- Fluorine-free packaging conversion:Per- and polyfluoroalkyl substance restrictions across multiple jurisdictions are redirecting grease-resistant barrier demand toward AKD-based chemistries in food-contact applications.
- Specialty paperboard capacity expansion:Converters in Germany and Japan are scaling procurement of stabilized aqueous dispersions for inline sizing systems.
Market Restraints
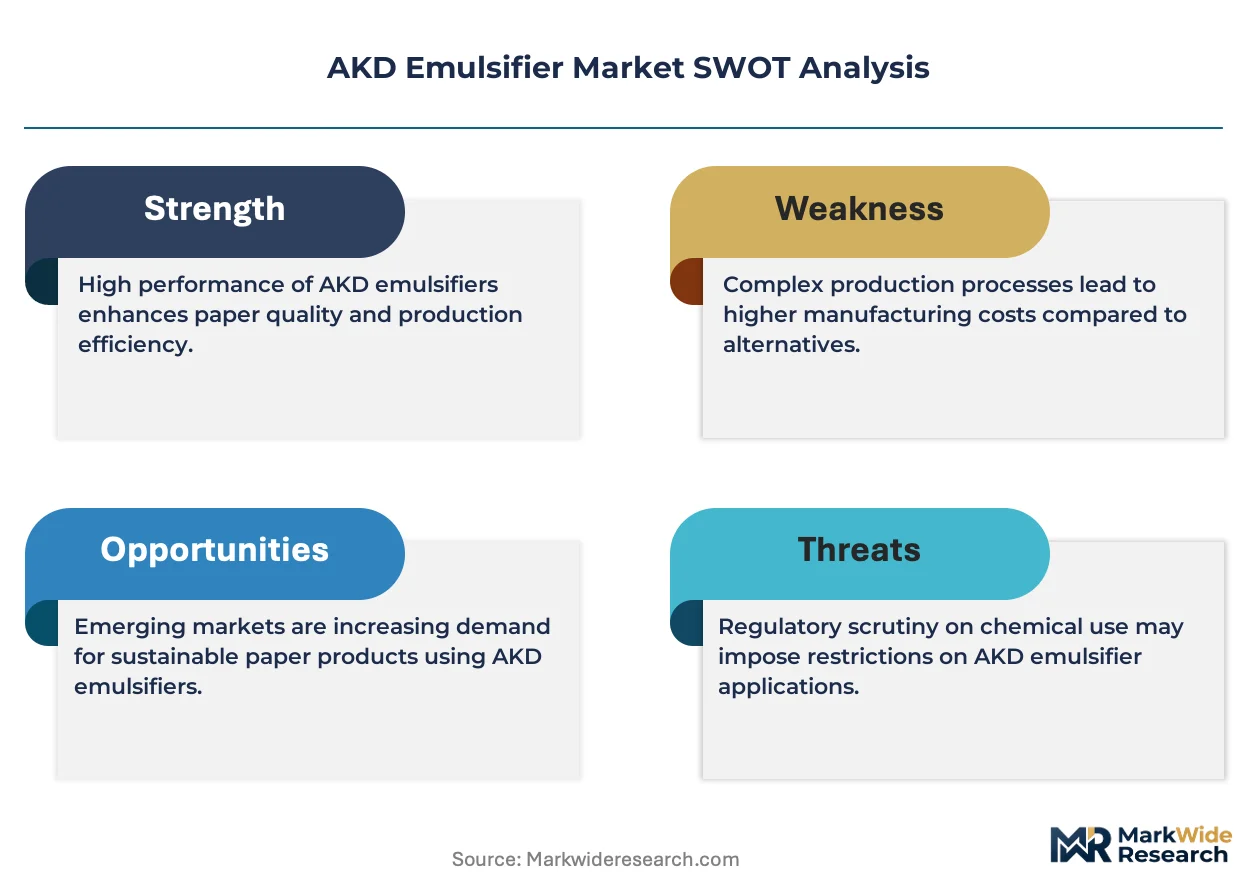
- Feedstock concentration:Integrated alkylene oxide chain control among a limited set of petrochemical producers creates supply vulnerability for high-purity AKD feedstocks.
- AOX formation limits:EPA effluent guidelines for pulp and paper mills in the United States restrict acceptable byproduct levels from sizing chemistries, constraining formulation flexibility.
- Fluoropolymer substitution competition:Specialized fluorine-free barrier chemistries from diversified materials suppliers compete directly with conventional AKD sizing in liquid packaging segments.
Strategic Opportunities
- GB 4806 compliance services:China's food contact material standards for extractable limits create advisory and certification revenue streams for testing laboratories and chemical suppliers.
- Powder emulsifier distribution:Regional converters lacking bulk liquid handling infrastructure represent an expanding margin pool for stabilized dry-form AKD products.
- Dual carbon alignment:China's national decarbonization targets and EU Green Deal industrial transitions favor bio-based feedstock pathways for ketene dimer production.
Industry Challenges
- Esterification process control:Achieving consistent hydrophobicity via cellulose fiber reaction during drying requires specialized technical expertise that remains scarce among regional paperboard manufacturers.
- Cross-jurisdictional dossier management:Divergent toxicological data requirements between REACH, EPA New Chemicals Program, and China's MEE create compliance timeline fragmentation for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AKD Emulsifier Market |
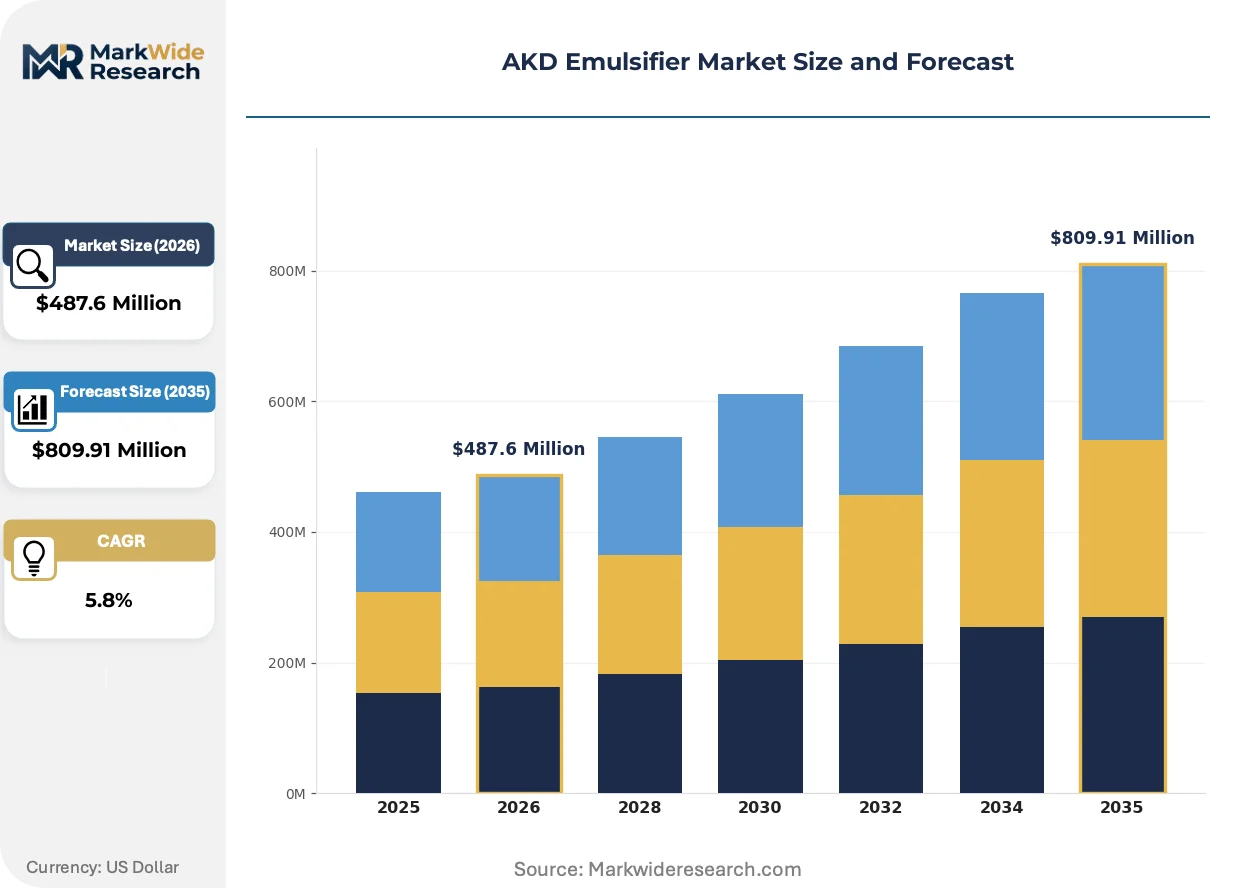
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Emulsifiers, Powder Emulsifiers, Granular Emulsifiers, Concentrated Emulsifiers Application: Paints, Coatings, Adhesives, Personal Care End User: Manufacturers, Distributors, Retailers, Consumers Technology: Batch Processing, Continuous Processing, High-Shear Mixing, Emulsification Techniques |
| Companies Covered | Trinseo PLC, Wacker Chemie AG, BASF SE, DuPont de Nemours, Inc., Synthomer PLC, Arkema Inc., The Lubrizol Corporation, Solenis LLC, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AKD Emulsifier Market Strategic Shifts
Reactive sizing chemistry is undergoing rapid specification stratification as regulatory thresholds tighten and end-use performance requirements diverge across packaging segments. Three developments are restructuring competitive positioning and investment priorities.
High-solids AKD emulsification technology is bifurcating the market between integrated mills with continuous dilution capabilities and regional converters dependent on pre-stabilized dispersions. Paperboard manufacturers in Japan are adopting 25-30% solids formulations for inline processing, while smaller German converters prioritize shelf-stable liquid concentrates. This technical divergence is compressing margins for mid-tier suppliers lacking formulation flexibility across both concentration ranges.
REACH registration dossiers for alkyl ketene dimer substances are mandating expanded toxicological testing above one-tonne annual volume thresholds, elevating compliance costs for specialty chemical suppliers. The industrial consequence is accelerated consolidation among European formulators unable to absorb full substance characterization expenses. Specialty packaging converters in Germany are responding by qualifying fewer approved suppliers and locking in multi-year procurement contracts.
Specification-driven vendor consolidation is concentrating procurement authority among technical buyers at major packaging converters, displacing traditional distributor-mediated purchasing for AKD emulsifiers. Direct supplier relationships now dominate volume contracting for food-grade barrier coatings in the United States and Japan. This channel compression is most visible in liquid packaging board segments where lot traceability and certificate-of-analysis documentation have become non-negotiable bid requirements.
AKD Emulsifier Market Segmentation
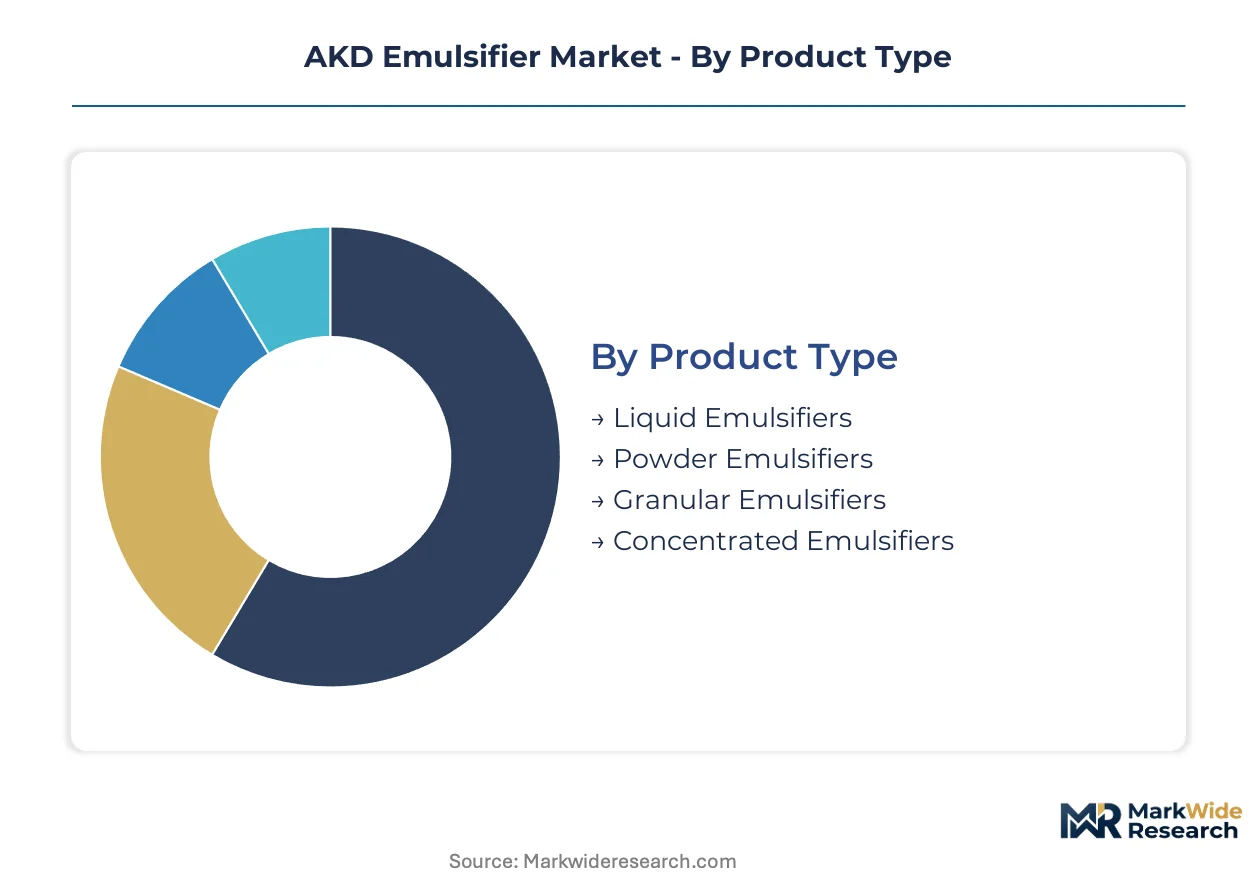
AKD emulsifier procurement patterns diverge sharply between integrated paper mills with captive sizing systems and regional converters dependent on third-party supply. Specification stratification across product forms and processing technologies is compressing margins for mid-tier suppliers lacking formulation flexibility. End-use concentration in food-contact packaging is collapsing historical tier separations between commodity and premium grades.
Product Type:
Liquid emulsifiers command the deepest margin pools due to continuous dilution capabilities and minimal storage infrastructure at integrated mills.
- Liquid Emulsifiers:Aqueous dispersions stabilized at 15-30% solids content through cationic starch or synthetic polymer colloids. Demand concentrates in Germany and Japan where specialty paperboard converters operate inline sizing systems for food-grade barrier coatings. REACH purity mandates and EPA AOX limits are forcing reformulation investments across the supply base.
- Powder Emulsifiers:Stabilized dry-form products designed for regional converters lacking bulk liquid handling infrastructure. Japanese specialty paperboard manufacturers are scaling procurement fastest as shelf-stable concentrates eliminate dilution complexity. This segment is closing the gap fastest on liquid forms among converters with limited technical staffing.
- Granular Emulsifiers:Free-flowing particulate formats for automated dosing systems in mid-scale coating operations.
- Concentrated Emulsifiers:High-solids formulations above 30% active content requiring precision dilution equipment.
The dominant share belongs to Liquid Emulsifiers, while Powder Emulsifiers is gaining share fastest among regional converters.
Application:
Food-contact packaging specifications are driving specification upgrades across all coating chemistries, with barrier performance requirements diverging by end-use exposure conditions.
- Paints:Industrial formulations requiring hydrophobic cellulosic substrates for exterior durability.
- Coatings:Food-grade barrier applications where GB 4806 extractable limits and FDA food contact notifications govern approval. German and Japanese converters are qualifying dual-compliant suppliers for liquid packaging board exports to China.
- Adhesives:Pressure-sensitive and laminating formulations leveraging AKD reactivity with hydroxyl-functional polymers.
- Personal Care:Cosmetic-grade emulsions requiring pharmaceutical-tier purity documentation and toxicological dossiers.
Coatings holds the dominant application share, with Personal Care climbing fastest on pharmaceutical-tier purity premiums.
End User:
Procurement authority is concentrating among technical buyers at major packaging converters, displacing distributor-mediated purchasing for food-grade barrier coatings.
- Manufacturers:Integrated paper mills with captive emulsification capacity and continuous processing technology. These buyers lock in multi-year contracts with full lot traceability and certificate-of-analysis documentation as non-negotiable requirements.
- Distributors:Channel intermediaries losing volume share as direct supplier relationships dominate food-grade contracting in the United States and Japan.
- Retailers:Private-label packaging converters with limited technical staffing dependent on pre-qualified supplier lists.
- Consumers:Artisan and specialty paper producers purchasing small-batch emulsifiers through chemical distributors.
Manufacturers retain the dominant procurement volume, while Retailers are expanding fastest on private-label food packaging conversion.
Technology:
Processing technology selection determines emulsion stability, solids content range, and capital intensity for formulators and end-users alike.
- Batch Processing:Flexible production suited to multi-product formulators serving diverse end-use specifications.
- Continuous Processing:Inline dilution systems enabling 25-30% solids formulations at integrated mills. Japanese paperboard manufacturers are adopting this technology fastest for food-grade barrier coating lines with minimal inventory buffers.
- High-Shear Mixing:Mechanical dispersion achieving sub-micron particle size distribution for premium coating applications.
- Emulsification Techniques:Chemical stabilization methods including cationic starch complexation and synthetic polymer colloid protection.
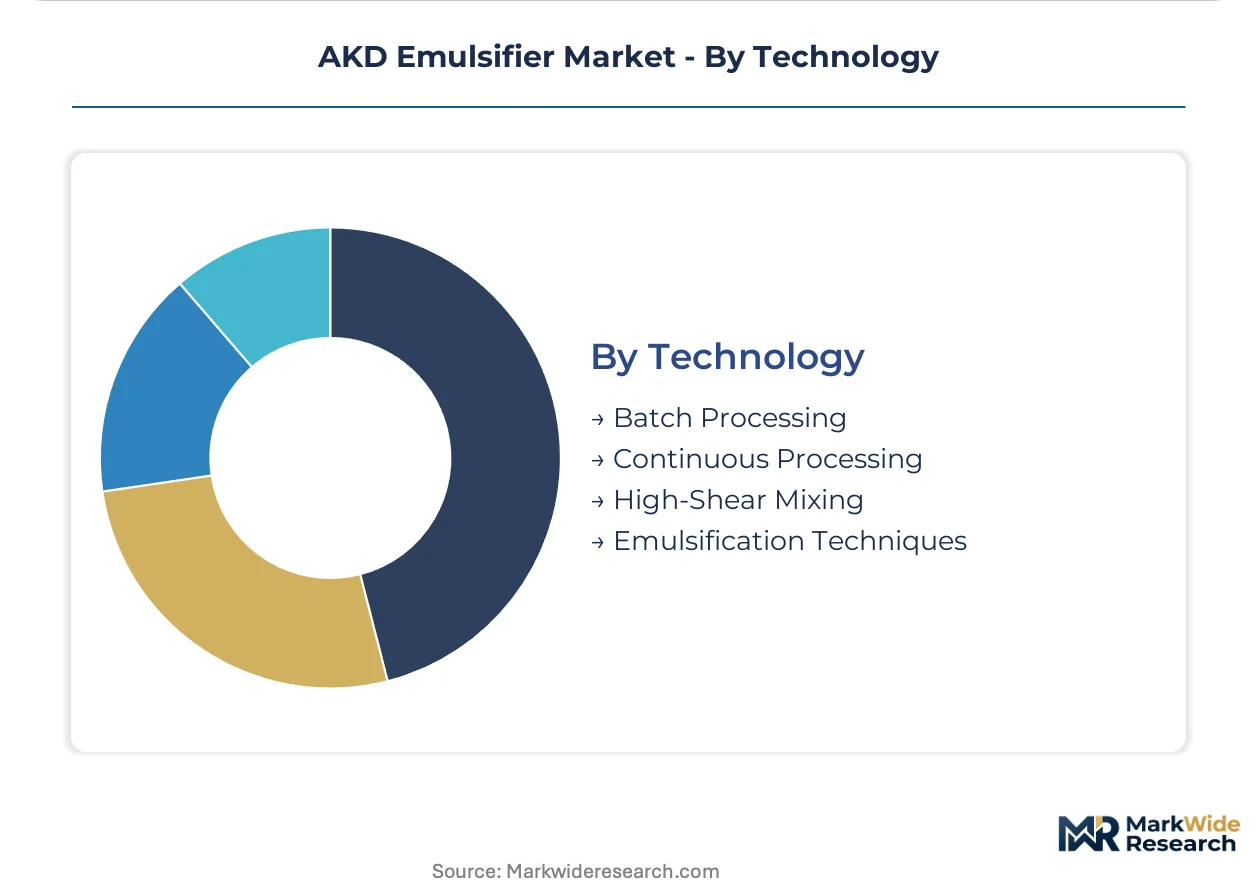
Continuous Processing dominates volume throughput, with High-Shear Mixing expanding most quickly on premium coating specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated alkylene oxide production concentrates in Germany, China, and the United States, creating feedstock access asymmetries that shape regional AKD emulsifier supply economics. Specialty paperboard demand clusters in Japan and Germany are accelerating qualification protocols for food-grade barrier coatings.
Germany
Specialty paperboard converters in Bavaria and North Rhine-Westphalia are scaling procurement of high-purity AKD emulsifiers for liquid packaging exports. ECHA REACH registration mandates full toxicological dossiers above one-tonne thresholds, elevating compliance costs for domestic formulators. The Hamburg industrial cluster hosts integrated chemical suppliers controlling captive alkylene oxide feedstock streams.
United States
EPA effluent guidelines restrict AOX formation from sizing chemistries in pulp and paper mills across the Southeast and Pacific Northwest. Integrated mills in Wisconsin and Georgia operate continuous dilution systems for 25-30% solids AKD formulations. FDA food contact notifications govern approval pathways for barrier coatings in dairy and beverage packaging applications.
China
SAMR enforcement of GB 4806 food contact material standards limits extractables from paper packaging into fatty food simulants. Specialty paperboard manufacturers in the Yangtze River Delta are qualifying dual-compliant suppliers for export markets. Dual carbon targets favor bio-based feedstock pathways for ketene dimer production in Shandong Province chemical parks.
Japan
METI industrial standards drive specification upgrades for fluorine-free barrier coatings in Tokyo and Osaka packaging corridors. Paperboard manufacturers in the Chubu region adopt high-shear mixing technology for premium coating applications. JIS certification requirements concentrate procurement authority among technical buyers at major converters.
AKD Emulsifier Market Competitive Environment
Concentration sits with integrated petrochemical conglomerates controlling upstream alkylene oxide supply chains. The vendor base spans three tiers: multinational chemical majors with captive feedstock access, regional formulators serving specialty packaging converters, and technology licensors supplying emulsification equipment and process know-how. Dominant competitive moves include backward integration into alkylene oxide production and strategic partnerships with paperboard manufacturers for co-development of food-grade barrier formulations.
Within the integrated chemical tier, BASF SE and DuPont de Nemours, Inc. exemplify divergent strategic positioning. BASF SE leverages its Ludwigshafen alkylene oxide complex to sustain cost-advantaged feedstock access for high-purity AKD grades. DuPont de Nemours, Inc. anchors its position through specialized fluorine-free barrier chemistry competing directly with conventional AKD sizing in liquid packaging segments. Wacker Chemie AG represents the technology-specialist archetype with Munich-based silicone and polymer expertise applicable to emulsion stabilization systems.
| Leading Market Players |
|---|
| Trinseo PLC |
| Wacker Chemie AG |
| BASF SE |
| DuPont de Nemours, Inc. |
| Synthomer PLC |
| Arkema Inc. |
| The Lubrizol Corporation |
| Solenis LLC |
| Celanese Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH registration dossiers gate both supplier qualification and price differentiation simultaneously, elevating compliance costs above one-tonne thresholds while compressing margins for formulators lacking integrated alkylene oxide access. Buyers in Germany and Japan now demand certificate-of-analysis documentation as non-negotiable bid requirements, forcing tier separation between certified premium grades and commodity alternatives.
Pricing Analysis
REACH dictates the pricing tier structure across the AKD emulsifier market, separating premium grades with full toxicological dossiers from commodity alternatives lacking registration completeness. Price differentiation rests on certification grade and volume scale, with multi-year contracts locking in favorable terms for major packaging converters. Cost compression in mid-tier formulations is intensifying because high-shear mixing technology investments concentrate margin capture among integrated mills. Regional converters lacking bulk liquid handling infrastructure exhibit highest price sensitivity, while Japanese specialty paperboard manufacturers demonstrate lowest sensitivity due to JIS certification requirements.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for alkylene oxide derivatives, pressuring landed cost structures for European formulators dependent on Asian ketene dimer intermediates. Geographic supply concentrates in Germany, China, and the United States, where integrated petrochemical complexes control captive feedstock streams. Raw material dependencies center on alkylene oxide, cationic starch stabilizers, and synthetic polymer colloids. Single-source vulnerability from concentrated alkylene oxide production creates structural risk. Distribution runs through direct supplier relationships with major converters, displacing traditional distributor channels for food-grade barrier coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical expertise in esterification process control remains scarce among regional paperboard manufacturers, creating capability gaps that determine competitive survival. Suppliers mastering both high-solids formulation and regulatory dossier management capture disproportionate margin pools.
For Market Incumbents: Secure backward integration into alkylene oxide production to defend feedstock cost positions against petrochemical supply volatility. Lock in multi-year procurement contracts with German and Japanese specialty converters before REACH dossier deadlines force supplier consolidation. Fluorine-free barrier chemistry from diversified materials suppliers threatens AKD share in liquid packaging segments; counter through co-development partnerships for food-grade coating specifications. For New Entrants and Emerging Players: GB 4806 compliance fast-tracks offer entry pathways into Chinese export supply chains serving Yangtze River Delta paperboard manufacturers. White-space concentrates in powder emulsifier distribution for regional converters lacking bulk liquid infrastructure across Southeast Asian packaging corridors. Target private-label food packaging retailers with shelf-stable concentrates eliminating dilution complexity. Go-to-market leverage rests on advisory services bundling certification documentation with product supply. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-purity AKD grades due to purification infrastructure investments and expanded toxicological testing requirements. Long-term viability favors integrated formulators with captive alkylene oxide access and established REACH registrations. Acquisition targets include regional European formulators facing compliance cost absorption challenges. Watch for fluoropolymer substitution acceleration in grease-resistant packaging as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive alkylene oxide supply secures cost-advantaged feedstock access for high-purity AKD grades. |
| REACH Dossier Completion | Full toxicological registration above one-tonne thresholds preserves market access in European liquid packaging board. |
| GB 4806 Compliance Certification | Dual-compliant supplier status unlocks Chinese food-contact export channels for German and Japanese converters. |
| Powder Emulsifier Distribution | Shelf-stable dry-form products capture expanding margin pools among regional converters lacking liquid handling infrastructure. |
| Fluorine-Free Barrier Co-Development | Partnerships with major packaging converters defend AKD positioning against fluoropolymer substitution in grease-resistant applications. |
Study Parameters
Initial hypotheses were tested against primary input from technical R&D directors at specialty chemical formulators, procurement leads at German and Japanese packaging converters, plant managers at integrated paper mills, and distribution channel partners, then refined through secondary validation. Sources included customs and trade data on alkylene oxide derivatives, ECHA REACH registration databases, SEC filings from petrochemical conglomerates, and industry association reports from Cefic and the American Chemistry Council. Bottom-up demand modeling across end-use segments triangulated against top-down supply capacity assessments.
Variance decomposition across product form, application specification, end-user procurement scale, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories calibrated to capacity expansion announcements and qualification timeline data. Industry-specific inputs included paperboard production forecasts for liquid packaging segments and fluoropolymer regulatory restriction timelines across multiple jurisdictions.
Underlying assumptions cover sustained REACH enforcement stringency, stable alkylene oxide feedstock availability, and continued fluorine-free packaging conversion momentum, with deviation risk concentrated in per- and polyfluoroalkyl substance regulatory divergence between jurisdictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market