
 Low Calorie Cream Cheese Market | 2026-2036
Low Calorie Cream Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Cream Cheese Market Foresight
FDA nutrition labeling modernization is consolidating the cost-of-entry calculus for low calorie cream cheese entrants, as reformulation and compliance investments now exceed what smaller regional dairies can absorb. Kraft Heinz Company leverages its refrigerated distribution network to sustain shelf-space dominance across mass retail channels. Arla Foods anchors its position through farm-to-dairy traceability systems that compete on provenance claims. Lactalis Group specializes in European-format spreadable variants, occupying premium positioning in specialty grocers.
Low calorie cream cheese denotes a dairy or dairy-alternative spread engineered with reduced fat content, typically achieved through partial milkfat replacement by yogurt, tofu, or almond milk bases, and stabilized for spreadability at refrigerated temperatures; its primary commercial purpose is to deliver flavor and mouthfeel parity with conventional cream cheese while aligning with calorie-controlled dietary protocols. Spreadable formats dominate household purchasing patterns due to breakfast and snacking versatility, whereas almond milk-based variants represent the fastest-growing ingredient segment as plant-forward formulations capture health-store and cafe channels. Cooking cream applications remain mature with thinner margin pools, while cheese slices targeted at food processors concentrate volume in wholesale distribution.
The FDA governs nutrition fact panel accuracy and health claim substantiation for U.S. products, while EFSA sets maximum residue limits and labeling thresholds across European markets, and FSSAI mandates fat-content disclosures and additive approvals for India-bound formulations; these frameworks collectively shape demand by determining which ingredient technologies achieve market access and which claims survive regulatory scrutiny. Stakeholders must monitor evolving plant-based identity standards as jurisdictions debate whether non-dairy formulations qualify for cheese nomenclature, a determination that will reshape competitive positioning and channel eligibility across multiple continents.
Market Dynamics
Quick-service restaurants across North America are accelerating reduced-fat cream cheese menu placements, while FDA nutrition labeling modernization forces simultaneous reformulation investments that favor scaled refrigerated distributors over regional dairies.
Growth Catalysts
- Plant-forward formulation technology:Almond milk-based stabilization systems achieve spreadability parity with conventional dairy bases, unlocking placement in health-store and cafe channels previously closed to reduced-fat alternatives.
- ESFA residue limit harmonization:Aligned maximum thresholds across European markets reduce cross-border formulation complexity, enabling single-SKU strategies for private-label health-food chains sourcing from consolidated dairy processors.
- German retail concentration:Discounter and organic-specialist chains actively tender for low-fat dairy alternatives, creating predictable offtake volumes that justify dedicated production lines.
Market Restraints
- Milkfat input volatility:Cream cheese production depends on fluid milk supply curves that track feed grain and energy costs, compressing margin predictability for reformulated SKUs with thinner unit economics.
- Mid-scale dairy consolidation:Regional processors in Wisconsin and Bavaria lack capital reserves for dual-track dairy and plant-based production infrastructure, ceding shelf space to integrated multinationals.
- Clean-label stabilization tradeoffs:Locust bean gum and carrageenan exclusion requirements under FDA scrutiny degrade freeze-thaw stability, limiting food-service applications requiring extended holding temperatures.
Strategic Opportunities
- Indian urban premium retail:FSSAI fat-content disclosure mandates create first-mover positioning for reformulated spreads in Mumbai and Bangalore modern trade formats targeting calorie-conscious professionals.
- Direct-to-cafe distribution:Specialty roaster chains bypass traditional wholesale distributors, sourcing customized bulk formats with specified mouthfeel profiles and shorter ingredient decks.
- EU Green Deal agricultural transition incentives:Farm-level methane reduction subsidies lower input costs for participating dairy cooperatives, creating certified low-carbon cream cheese feedstock pools.
Industry Challenges
- Cross-functional formulation talent scarcity:Protein chemistry and emulsion science expertise must converge with sensory evaluation capabilities, a combination concentrated in a handful of European and North American research clusters.
- Dual certification timeline compression:Simultaneous organic and plant-based identity standard approvals stretch quality assurance bandwidth, delaying seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Cream Cheese Market |
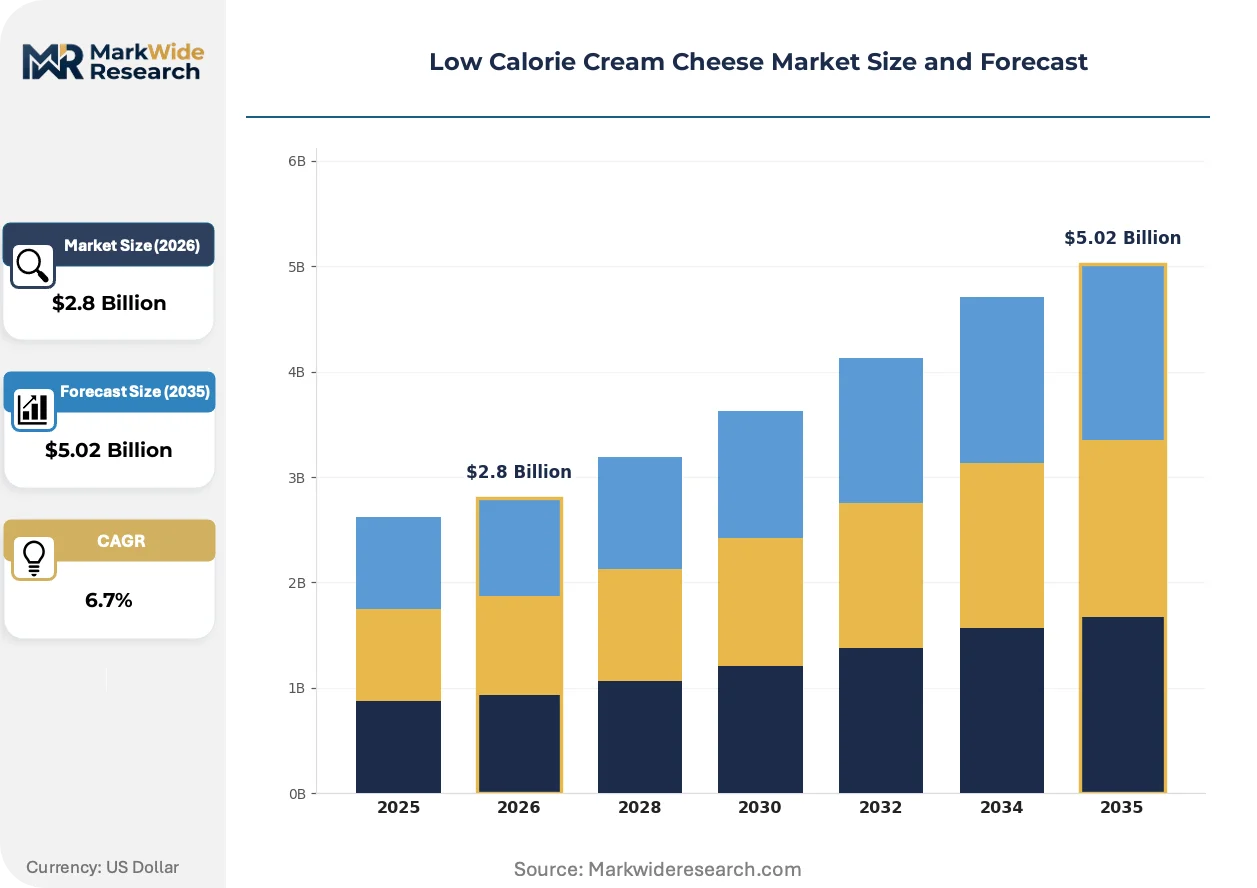
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreadable, Dips, Cooking Cream, Cheese Slices Ingredient Type: Cream, Tofu, Yogurt, Almond Milk End User: Restaurants, Households, Cafes, Food Processors Distribution Channel: Supermarkets, Online Retail, Health Stores, Wholesale |
| Companies Covered | Kraft Heinz Company, Arla Foods, Lactalis Group, Kite Hill, Miyoko’s Creamery, Danone, Royal FrieslandCampina, Fonterra Co-operative Group, Daiya Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Cream Cheese Market Shifts & Advancements
Reformulation science is converging with supply chain traceability demands, creating pressure for ingredient provenance verification and modular production architectures that can switch between dairy and alternative bases within single facilities.
Enzymatic fat-mimetic systems derived from modified starch and citrus fiber are modularizing texture engineering in reduced-fat cream cheese production. Mid-tier dairy processors in Denmark and the Netherlands adopt these systems to avoid capital-intensive homogenization equipment upgrades. The technology is modularizing competitive entry by decoupling mouthfeel achievement from legacy production scale.
REACH chemical registration requirements for novel emulsifiers are tightening disclosure thresholds for substances used at sub-percent inclusion rates. European formulators face reformulation cycles to substitute pending-registration ingredients with established alternatives. Specialty grocers in Germany and France are responding by accelerating clean-label certification timelines ahead of regulatory enforcement dates.
Food-service buyers are consolidating supplier relationships around full-category dairy and alternative spread portfolios rather than single-SKU procurement. Broadline distributors in the United States are displacing specialized dairy jobbers by bundling low-calorie cream cheese with complementary breakfast ingredients. This concentration is most visible in quick-service restaurant supply chains operating across Texas, California, and Illinois.
Low Calorie Cream Cheese Market Segmentation
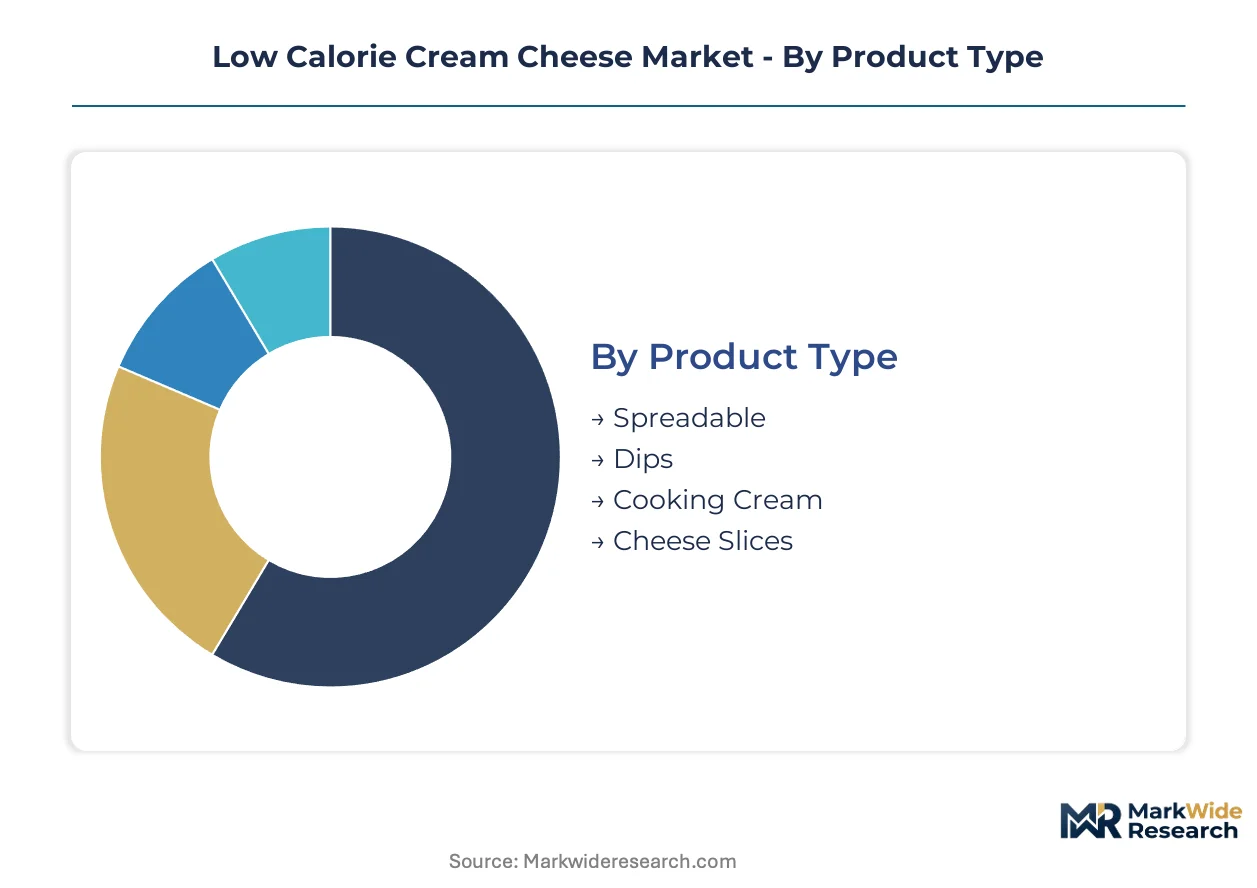
Low calorie cream cheese buyers prioritize texture parity and caloric transparency differently across consumption occasions. Spreadability requirements dominate household breakfast routines, while food-service procurement emphasizes holding stability and bulk economics. Ingredient provenance claims now override price sensitivity in health-store channels, fragmenting traditional mass-market segmentation logic.
Product Type:
Texture versatility drives purchase frequency more than flavor differentiation in reduced-fat spreads.
- Spreadable:Refrigerated tubs formulated for knife-spread consistency at 4°C dominate household breakfast and snacking occasions. German discounters and North American quick-service restaurants concentrate procurement volumes here, pressured by FDA nutrition labeling modernization toward cleaner stabilizer decks.
- Dips: Thicker-bodied preparations with extended acid stability suit party-size packaging and food-service holding cabinets. Demand clusters in US cafe chains seeking customizable flavor bases with shorter ingredient lists for front-of-house display.
- Cooking Cream: Lower-viscosity formulations designed for sauce incorporation and heat tolerance. Mature segment with thinner margins; volume concentrates in European wholesale distribution to ready-meal manufacturers.
- Cheese Slices: Individually wrapped portions targeting food processors and sandwich assembly lines. Melting behavior specifications dominate procurement criteria over caloric claims.
Spreadable leads on scale; Dips leads on momentum.
Ingredient Type:
Base material selection determines regulatory pathway and channel eligibility for reduced-fat positioning.
- Cream:Traditional dairy base with partial milkfat reduction through skim milk blending or enzymatic fat modification. Wisconsin and Bavarian processors retain cost advantages through captive fluid milk supply, though EFSA residue limit compliance adds cross-border complexity.
- Almond Milk: Plant-forward stabilization systems achieving spreadability parity through modified starch and citrus fiber emulsification. Fastest-climbing trajectory as health-store and specialty cafe channels expand placement; REACH chemical registration requirements for novel emulsifiers create European formulation headwinds.
- Tofu: Soy protein base with neutral flavor profile requiring masking agents. Niche positioning in vegetarian-specialist retail with limited food-service penetration due to freeze-thaw instability.
- Yogurt: Cultured dairy base leveraging existing fermentation infrastructure for tang-forward flavor profiles. Concentrated in Nordic private-label supply for breakfast-oriented consumption.
Cream anchors volume economics; Almond Milk captures channel expansion.
End User:
Procurement sophistication varies sharply between institutional buyers and household decision-makers.
- Restaurants:Quick-service chains across Texas, California, and Illinois drive reduced-fat menu placement through consolidated broadline distributor relationships. Specifications emphasize holding stability and SKU consolidation across full dairy portfolios.
- Households: Supermarket shoppers prioritizing breakfast versatility and refrigerated convenience. Spreadable formats dominate; clean-label claims increasingly influence switching behavior.
- Cafes: Specialty roaster chains bypassing traditional wholesale for direct sourcing of customized bulk formats with specified mouthfeel profiles. Shorter ingredient decks command premium positioning.
- Food Processors: Industrial buyers concentrating cheese slice volumes for sandwich manufacturing and prepared meal integration. Price elasticity exceeds sensitivity to caloric claims.
Restaurants concentrate purchasing power; Cafes reshape sourcing relationships.
Distribution Channel:
Channel selection determines margin structure and regulatory exposure for reformulated SKUs.
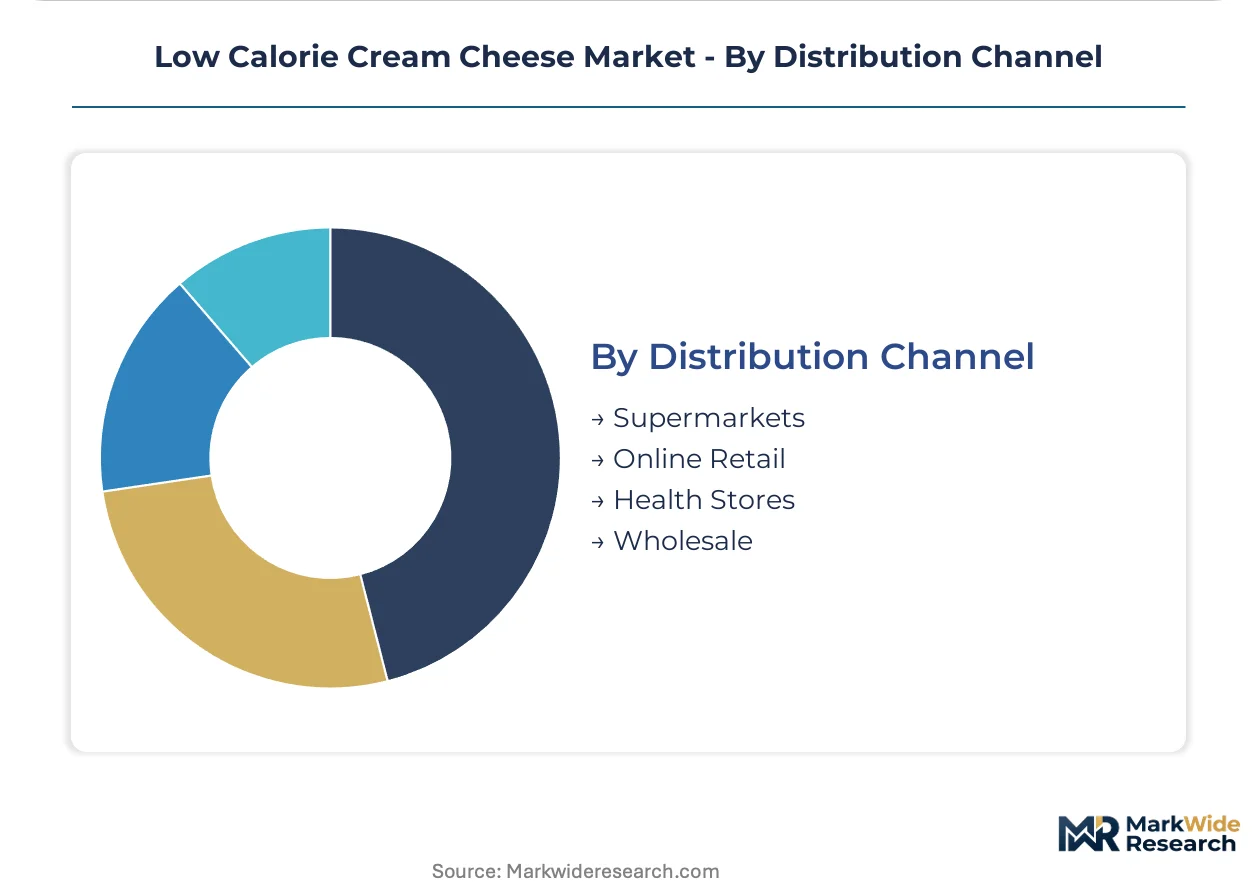
- Supermarkets:Mass retail shelf-space competition dominated by scaled refrigerated distributors with nationwide logistics networks. Kraft Heinz leverages infrastructure advantages for placement density.
- Health Stores: Curated assortment prioritizing plant-based identity certifications and farm-to-dairy traceability. German organic-specialist chains actively tender for low-fat alternatives, creating predictable offtake volumes.
- Online Retail: Direct-to-consumer growth constrained by cold-chain fulfillment economics. Subscription models emerging for premium almond milk-based variants in urban India.
- Wholesale: Broadline distribution bundling low-calorie cream cheese with complementary breakfast ingredients displaces specialized dairy jobbers. Volume concentrates in food-service supply chains.
Supermarkets control household penetration; Health Stores command premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cream cheese production originated in the United States during the late 19th century, with Philadelphia-brand spreadable formats establishing the category's commercial foundation. Modern low-calorie variants now distribute through refrigerated networks across five major national markets.
United States
Quick-service restaurant chains in Texas, California, and Illinois drive reduced-fat menu placements through consolidated broadline distributor relationships. FDA nutrition labeling modernization pressures reformulation toward cleaner stabilizer decks while expanding compliance costs. Wisconsin dairy cooperatives supply fluid milk feedstock to reformulation facilities in the Upper Midwest.
Germany
Discounter and organic-specialist retail chains actively tender for low-fat dairy alternatives, creating predictable offtake volumes that justify dedicated production lines. EFSA maximum residue limits shape cross-border formulation strategies for private-label health-food chains. Bavarian processors leverage captive fluid milk supply to retain cost advantages in spreadable format manufacturing.
India
FSSAI fat-content disclosure mandates create first-mover positioning for reformulated spreads in Mumbai and Bangalore modern trade formats targeting calorie-conscious professionals. Urban premium retail expansion concentrates demand in western and southern metropolitan corridors. Subscription models emerge for cold-chain delivery of almond milk-based variants to affluent households.
Netherlands
Mid-tier dairy processors adopt enzymatic fat-mimetic systems to avoid capital-intensive homogenization equipment upgrades. REACH chemical registration requirements for novel emulsifiers tighten disclosure thresholds for substances used at sub-percent inclusion rates. Rotterdam and Eindhoven research clusters concentrate protein chemistry and emulsion science expertise.
Denmark
Nordic private-label supply chains leverage existing fermentation infrastructure for cultured dairy base production with tang-forward flavor profiles. EU Green Deal agricultural transition subsidies lower input costs for participating dairy cooperatives through farm-level methane reduction incentives. Arla Foods anchors farm-to-dairy traceability systems that compete on provenance claims in health-store channels.
Low Calorie Cream Cheese Market Competitive Landscape
The competitive structure tilts toward multinational refrigerated distributors with legacy dairy infrastructure and specialized plant-based formulators with health-store channel access. Consolidated mass retail shelf-space competition favors scaled logistics networks, while fragmented specialty channels sustain niche positioning. Two strategic archetypes dominate: integrated multinationals leveraging backward integration into fluid milk supply, and agile alternative-protein specialists capturing cafe and health-store placement. Dominant competitive moves include portfolio diversification across dairy and plant-based bases, and geographic expansion through direct-to-cafe distribution relationships bypassing traditional wholesale.
Among North American and European incumbents, Kraft Heinz Company exemplifies the scale-driven archetype through refrigerated distribution network dominance, while Arla Foods occupies a position anchored in farm-to-dairy traceability systems. Lactalis Group represents the European-format specialization archetype through spreadable variant expertise in premium specialty grocer channels.
| Leading Market Players |
|---|
| Kraft Heinz Company |
| Arla Foods |
| Lactalis Group |
| Kite Hill |
| Miyoko's Creamery |
| Danone |
| Royal FrieslandCampina |
| Fonterra Co-operative Group |
| Daiya Foods |
| Others |
Supply & Pricing Matrix
Captive fluid milk supply in Wisconsin and Bavaria anchors both production positioning and pricing power for reformulated cream cheese variants, with FDA nutrition labeling modernization forcing simultaneous compliance investments that favor scaled operators over regional dairies lacking capital reserves for dual-track infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume scale. Premium almond milk-based variants command positioning through health-store channel access and shorter ingredient decks, while economy tiers face cost compression from milkfat input volatility tracking feed grain and energy curves. Quick-service restaurant procurement concentrates price sensitivity in bulk spreadable formats, whereas cafe direct-sourcing tolerates premium positioning for customized mouthfeel specifications.
Supply Chain Analysis
Direct-to-cafe distribution channels handle specialty roaster demand for customized bulk formats with specified stabilizer profiles and shorter ingredient decks. Raw material sourcing draws from fluid milk supply curves in Wisconsin and Bavaria, almond milk concentrate pools in California, and modified starch emulsification inputs from Danish and Dutch processors. Single-source vulnerability concentrates in locust bean gum and carrageenan alternatives facing FDA scrutiny, degrading freeze-thaw stability for food-service applications. Distribution runs through refrigerated networks dominated by scaled multinationals with nationwide logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low calorie cream cheese market functions as a stable compounder, with plant-forward formulation technology driving steady channel expansion into health-store and cafe segments previously closed to reduced-fat alternatives.
For Market Incumbents: Deploy portfolio diversification across dairy and plant-based bases to defend against almond milk-based specialist encroachment. Expand backward integration into fluid milk supply in Wisconsin and Bavaria to secure cost advantages as EFSA residue limit harmonization reshapes cross-border formulation complexity. Capture shelf-space dominance through refrigerated distribution network density in mass retail channels. For New Entrants and Emerging Players: Specialty roaster chains represent the most penetrable channel partner type for bypassing traditional wholesale distributor relationships. Target direct-to-cafe distribution in Texas, California, and Illinois quick-service restaurant corridors with customized bulk formats featuring specified mouthfeel profiles and clean-label stabilization systems. Leverage enzymatic fat-mimetic technology to avoid capital-intensive homogenization equipment requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale dairy processors in Wisconsin and Bavaria lack capital reserves for dual-track dairy and plant-based production infrastructure. Long-term viability favors acquisition targets with established health-store channel relationships and modular production architectures capable of switching between dairy and alternative bases. Monitor FDA plant-based identity standard rulings as the critical inflection signal for competitive positioning reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Spreads risk across dairy and almond milk bases as FDA debates plant-based cheese nomenclature. |
| Direct-to-Cafe Distribution | Bypasses broadline distributors to capture premium positioning through customized bulk format relationships. |
| Enzymatic Fat-Mimetic Adoption | Enables mid-tier processors to achieve spreadability parity without capital-intensive homogenization upgrades. |
| Clean-Label Reformulation | Addresses FDA scrutiny of locust bean gum and carrageenan while meeting health-store certification timelines. |
| Backward Integration | Secures captive fluid milk supply in Wisconsin and Bavaria to retain margin predictability amid input volatility. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at retailers, channel sales heads, and supply planners informed demand-side assumptions. Secondary validation drew from FDA filings, EFSA residue limit databases, FSSAI fat-content disclosure records, and Nielsen retail audit data. Triangulation across these sources anchored volume estimates against production capacity disclosures from Wisconsin and Bavarian dairy cooperatives.
Historical trendline analysis established baseline growth patterns across spreadable, dips, cooking cream, and cheese slice formats. The projection framework modeled segmentation dimensions including product type, ingredient base, end-user procurement sophistication, and distribution channel margin structure. CAGRs were derived through iterative reconciliation of bottom-up SKU-level buildups with top-down category spending trajectories. Key forecast inputs incorporated almond milk-based variant adoption curves and quick-service restaurant menu placement velocity across Texas, California, and Illinois.
Revisions become necessary when FDA plant-based identity standards, EFSA emulsifier registration timelines, or FSSAI enforcement intensities materialize differently than baseline assumptions. Forecasts reflect documented assumptions regarding clean-label stabilization technology maturation and health-store channel expansion velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Dairy-Free Evaporated Milk Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market