
 Pet Milk Market | 2026-2036
Pet Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Milk Market Outlook
Multi-source ingredient procurement is expanding across the pet milk supply chain as manufacturers seek resilience against dairy price volatility and regional supply disruptions. Pet-Ag, Inc. leverages decades of neonatal nutrition expertise to dominate veterinary channels for orphaned puppies and kittens. Grober Nutrition anchors its position through vertically integrated goat milk sourcing and species-specific formulation capabilities. Beaphar B.V. competes across European retail shelves with extended shelf-life liquid formats and pharmacy-grade nutritional supplements.
Pet milk denotes nutritionally formulated dairy or dairy-alternative products engineered for companion animal consumption, typically containing adjusted lactose levels, fortified vitamins, and protein profiles calibrated to canine, feline, or small mammal digestive physiology. Powdered milk formulations lead volume due to extended stability and lower logistics costs, while liquid milk commands premium positioning in refrigerated veterinary and specialty retail channels. Online retail is accelerating fastest among distribution channels as subscription models capture recurring replenishment demand, though pet stores retain margin concentration through personalized nutritional consultation.
FDA Center for Veterinary Medicine oversight and AAFCO model regulations shape ingredient safety thresholds and label claims across the United States, while EFSA and national EU feed hygiene regulations govern European market access and formulation standards. These frameworks elevate compliance costs for new entrants but simultaneously validate premium pricing for certified therapeutic and life-stage-specific products. Stakeholders must monitor evolving lactose-reduction technologies and plant-based protein integration as consumer preferences shift toward hypoallergenic and sustainability-positioned formulations.
Market Dynamics
FDA Center for Veterinary Medicine oversight and AAFCO nutritional guidelines are compressing formulation flexibility while elevating compliance costs, forcing manufacturers to consolidate R&D spending on cleaner-label, species-specific products.
Growth Catalysts
- AAFCO Model Regulations:Tightening nutritional standards in the United States validate premium pricing for certified therapeutic formulations and drive recurring veterinary channel purchases.
- Lactose-Reduction Enzyme Technology:Advances in enzymatic hydrolysis enable broader canine and feline tolerance profiles, expanding addressable pet populations beyond neonatal stages.
- Specialty Pet Retail Expansion:Veterinary clinics and premium pet stores are dedicating shelf space to refrigerated liquid formats, capturing household penetration through personalized nutritional consultation.
Market Restraints
- Dairy Input Volatility:Fluctuating goat and cow milk commodity prices squeeze margin structures for powder-dependent manufacturers without captive supply arrangements.
- Regulatory Fragmentation:Divergent EFSA feed hygiene standards and national EU implementations create multi-jurisdictional compliance burdens for cross-border formulation launches.
- Plant-Based Substitution:Oat and pea protein milk alternatives for companion animals are capturing sustainability-conscious households, pressuring traditional dairy-derived positioning.
Strategic Opportunities
- Subscription E-Commerce:Direct-to-consumer replenishment platforms are capturing recurring demand with personalized life-stage formulations and auto-ship convenience.
- Hypoallergenic Positioning:Novel protein sources including camelid and insect-derived bases address growing veterinary diagnoses of dairy sensitivity in companion animals.
- Sustainability Certification:Carbon-neutral production claims and regenerative agriculture sourcing align with EU Green Deal consumer preference shifts in premium segments.
Industry Challenges
- Formulation Scientist Scarcity:Veterinary nutrition PhD talent pools concentrate at incumbent manufacturers, constraining startup R&D velocity and species-specific innovation pipelines.
- Cold Chain Infrastructure:Liquid format distribution requires refrigerated logistics investments that fragment margin capture between manufacturers and third-party distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Milk Market |
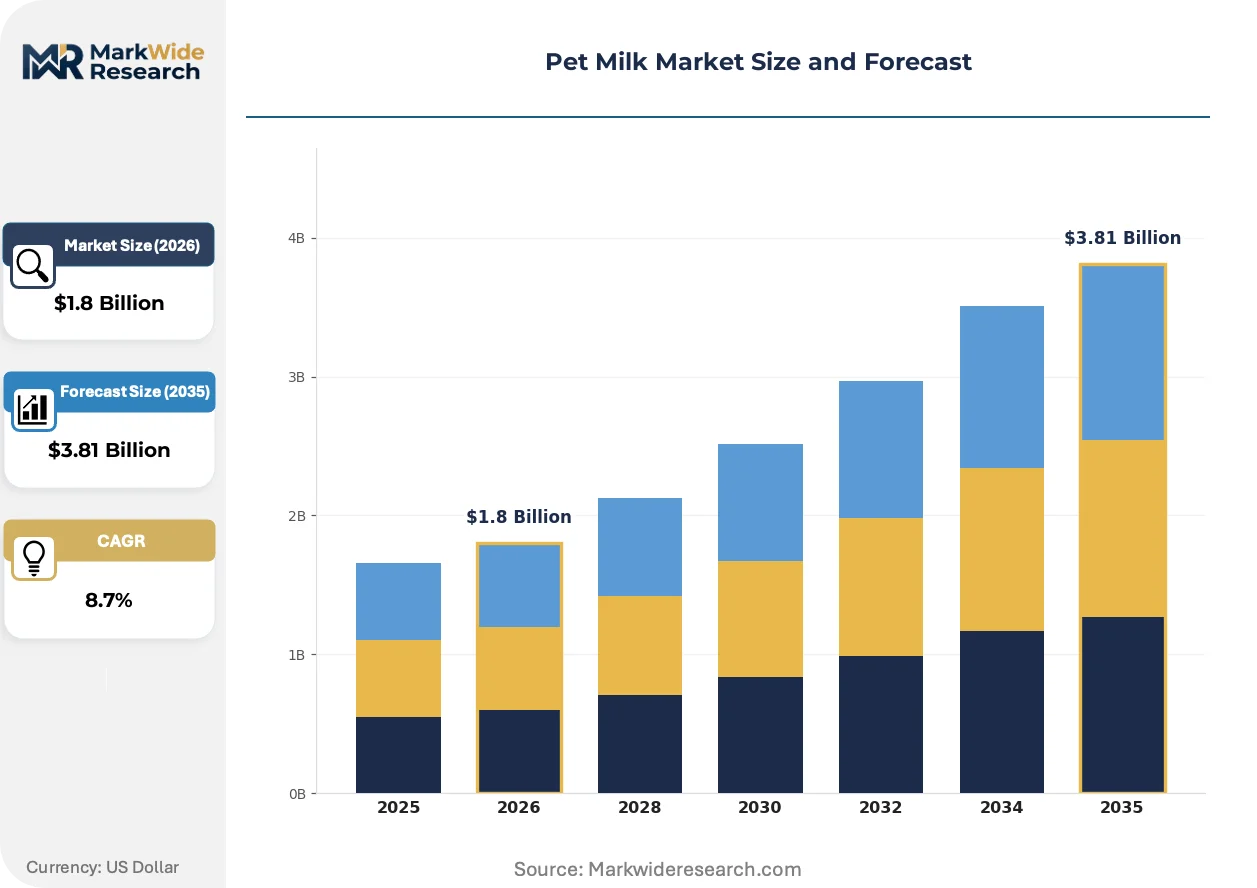
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Milk, Powdered Milk, Cream, Nutritional Supplements Packaging Type: Bottles, Tetra Packs, Pouches, Cans End User: Dogs, Cats, Small Animals, Others Distribution Channel: Online Retail, Pet Stores, Supermarkets, Veterinary Clinics |
| Companies Covered | Pet-Ag, Inc., Beaphar B.V., Grober Nutrition, Fetch For Pets LLC, Manna Pro Products LLC, Milk Specialties Global, Cargill, Incorporated, Royal Canin, Land O'Lakes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Milk Market Strategic Shifts
Enzymatic lactose hydrolysis and plant-protein integration are restructuring competitive positioning around digestive tolerance and sustainability claims, while distribution channels fragment between veterinary authority and direct consumer convenience.
Spray-dried goat milk protein concentrates with enhanced fat globule structures are overtaking conventional bovine-based neonatal formulas in veterinary orphan care protocols. Specialty breeders and emergency veterinary clinics are adopting these concentrates at accelerating rates for improved digestibility in compromised puppies and kittens. This shift is compressing incumbent bovine-sourced product lines and forcing reformulation investments across legacy portfolios.
EFSA feed hygiene regulation updates are mandating stricter microbiological thresholds for liquid pet milk shelf-life claims across European markets. Manufacturers must validate extended stability through accelerated testing protocols, elevating batch release timelines and quality control staffing. Small-format regional producers in France and Germany are responding by consolidating production at centralized EU facilities to achieve economies of compliance.
Pet owner purchasing is migrating from episodic retail visits toward algorithm-driven subscription replenishment with veterinary telehealth integration. Online platforms are displacing in-store consultation for routine nutritional decisions, though premium segments retain physical channel preference for therapeutic product selection. This behavioral divergence is most pronounced in United States metropolitan markets with high digital commerce penetration and established veterinary telemedicine infrastructure.
Pet Milk Market Segmentation
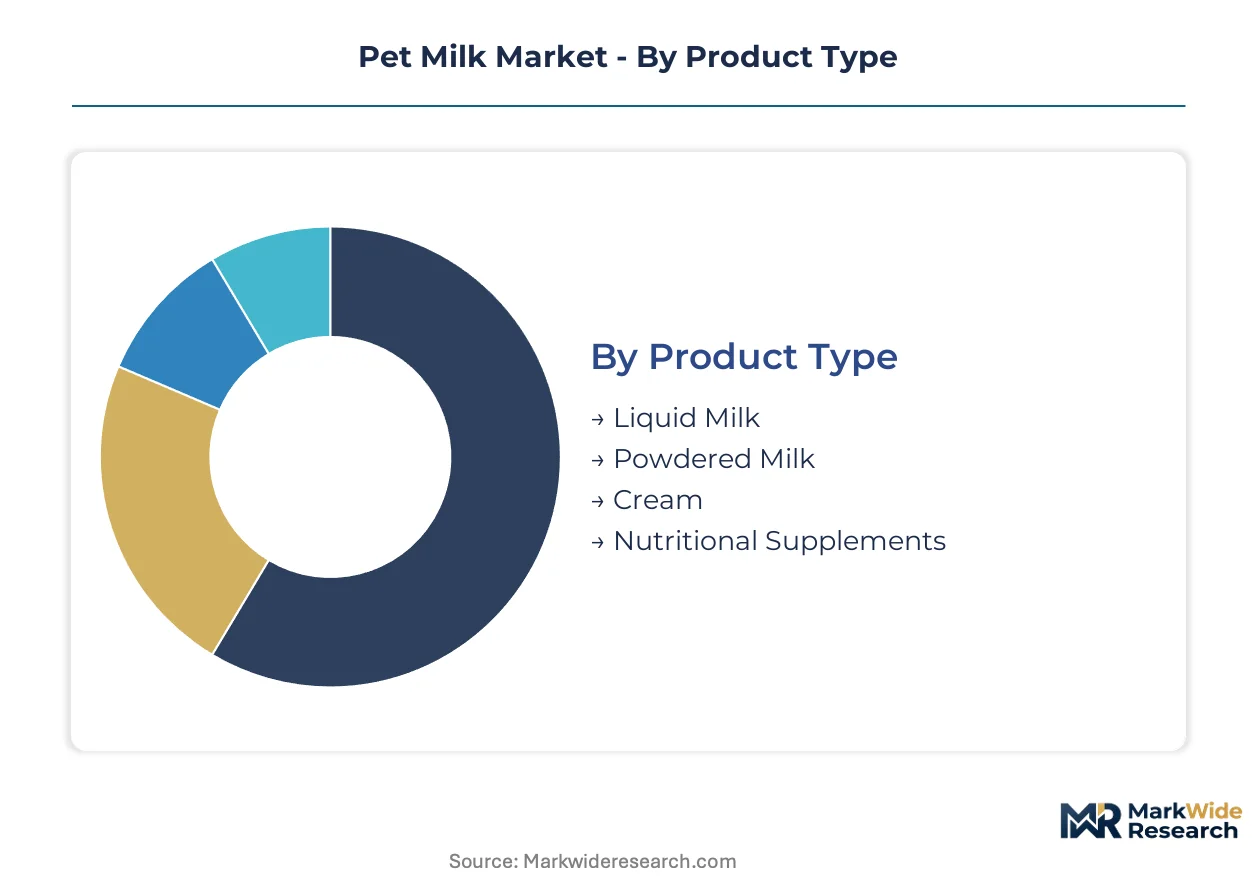
Pet milk segmentation reflects divergent supply chain economics and consumption occasions across formats and channels. Powdered formulations dominate manufacturing scale while liquid formats capture premium positioning through cold-chain investments. Species-specific nutritional calibration and packaging shelf-life requirements further fragment procurement patterns among breeders, veterinary clinics, and direct consumers.
Product Type:
Liquid milk integrates into refrigerated veterinary protocols and premium retail displays as a standalone consumption format, while powdered milk embeds into breeder supply chains and emergency nutrition kits as a shelf-stable input requiring reconstitution.
- Liquid Milk:Refrigerated dairy or dairy-alternative formulations with enzymatic lactose reduction for immediate feeding occasions. Demand concentrates in United States metropolitan veterinary clinics where orphaned neonatal care protocols specify temperature-controlled delivery. Cold-chain infrastructure investments limit manufacturer margin capture.
- Powdered Milk:Spray-dried protein concentrates with adjusted fat globule structures for extended stability. Breeders across Texas, Florida, and California kennel clusters drive recurring bulk procurement for whelping season preparation. Lower logistics costs enable private-label penetration.
- Cream:High-fat emulsion products for underweight or convalescing animals requiring caloric density.
- Nutritional Supplements:Fortified additive formats targeting specific life-stage deficiencies or therapeutic recovery protocols.
Powdered milk leads volumes today; liquid milk is gaining share fastest through veterinary channel expansion.
Packaging Type:
Packaging selection tracks distribution channel cost structures and shelf-life requirements, with rigid formats commanding veterinary authority and flexible formats capturing e-commerce logistics efficiency.
- Bottles:PET or glass containers with resealable closures for multi-feeding occasions. United States specialty pet retailers in California and New York metropolitan areas dedicate refrigerated display space to bottle formats. Premium positioning supports margin extraction through visible quality signaling.
- Tetra Packs:Aseptic carton technology enabling ambient distribution of liquid formulations. European Union manufacturers leverage this format for cross-border retail penetration under EFSA feed hygiene compliance. Extended shelf-life reduces retail write-off rates.
- Pouches:Flexible film structures for single-serve powder sachets or liquid portions. E-commerce subscription platforms favor pouches for dimensional weight optimization in last-mile delivery.
- Cans:Metal containment for high-volume institutional procurement by commercial breeding operations.
Bottles dominate veterinary and premium retail placement; Tetra Packs are expanding most quickly through European mass retail distribution.
End User:
Species-specific digestive physiology drives formulation divergence, with canine and feline segments requiring distinct protein profiles and lactose tolerance thresholds.
- Dogs:Formulations calibrated to canine gut microbiome and lower lactase persistence relative to neonatal cats. United States sporting dog breeders in South Carolina and Wisconsin drive seasonal demand spikes for performance nutrition. AAFCO nutritional adequacy claims validate premium pricing tiers.
- Cats:Higher protein concentration and taurine fortification requirements reflecting obligate carnivore metabolism. Veterinary clinics in Japan and United Kingdom urban centers prescribe therapeutic milk for post-surgical recovery. Feline formulations command per-unit price premiums over canine equivalents.
- Small Animals:Rabbits, ferrets, and exotic mammals requiring specialized fat and carbohydrate ratios.
- Others:Avian and reptile nutritional applications with highly specific formulation constraints.
Canine formulations anchor volume today; feline segments show steepest expansion trajectory through veterinary therapeutic positioning.
Distribution Channel:
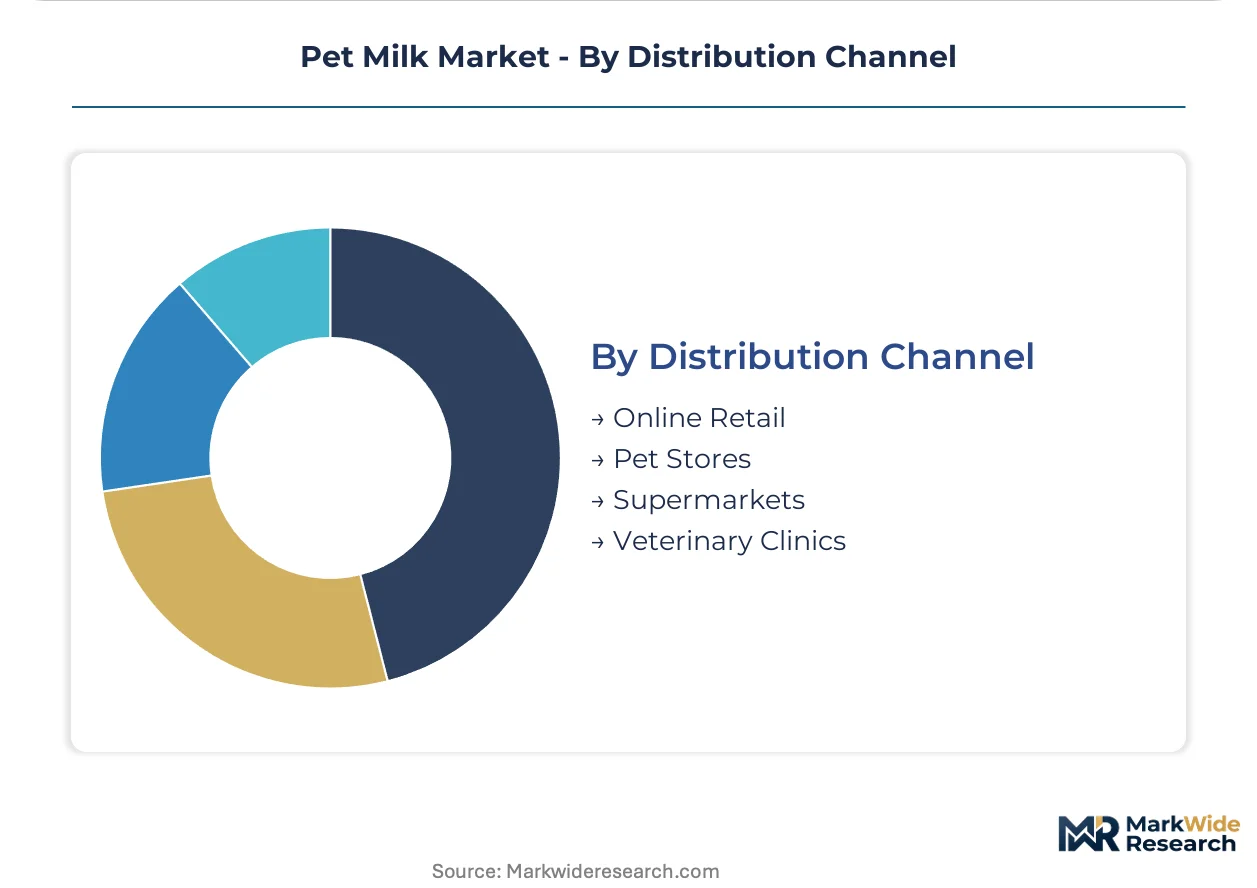
Channel selection determines margin capture and customer relationship depth, with physical retail retaining consultation value and digital platforms capturing replenishment automation.
- Online Retail:Direct-to-consumer platforms with subscription replenishment algorithms and veterinary telehealth integration. United States coastal metropolitan markets with established digital commerce infrastructure show highest penetration. Auto-ship models reduce customer acquisition cost through lifetime value extension.
- Pet Stores:Specialty retail with trained staff providing species-specific nutritional consultation. Independent retailers in Germany and France differentiate through personalized formulation matching. Margin concentration persists through premium product mix curation.
- Supermarkets:Mass retail placement for standard powdered formats with price-competitive positioning.
- Veterinary Clinics:Authority-driven therapeutic product recommendation with prescription-aligned dispensing.
Pet stores lead margin capture today; online retail is climbing the fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States veterinary clinics and specialty retailers anchor international demand for premium pet milk formulations, with metropolitan clusters in California, Texas, and Florida driving recurring procurement through established breeder networks and companion animal hospital systems.
United States
FDA Center for Veterinary Medicine oversight and AAFCO nutritional adequacy claims validate premium pricing tiers across therapeutic formulations. The South Carolina and Wisconsin sporting dog breeding corridors generate seasonal demand spikes for performance-calibrated products. Independent pet retailers in New York and Los Angeles metropolitan areas differentiate through personalized nutritional consultation and refrigerated liquid format curation.
Germany
EFSA feed hygiene regulations mandate stricter microbiological thresholds for liquid pet milk shelf-life claims, elevating batch release timelines and quality control staffing requirements. Small-format regional producers in Bavaria and North Rhine-Westphalia are consolidating production at centralized EU facilities to achieve economies of compliance. Frankfurt and Hamburg veterinary distributors are expanding refrigerated logistics networks for cross-border retail penetration.
Japan
Feline therapeutic milk prescriptions for post-surgical recovery are concentrating demand in Tokyo and Osaka urban veterinary clinics. METI guidelines on functional pet food claims shape formulation marketing boundaries and substantiation requirements. Yokohama-based specialty pet retailers are integrating telehealth consultation platforms with subscription replenishment models for premium nutrition segments.
United Kingdom
Veterinary telemedicine infrastructure in London and Manchester is accelerating online platform displacement of in-store consultation for routine nutritional decisions. The national feed hygiene regulator enforces compliance thresholds that elevate entry barriers for imported formulations. Scottish and Welsh breeder cooperatives are driving bulk powdered milk procurement for seasonal whelping preparation.
France
EU Green Deal consumer preference shifts are elevating demand for carbon-neutral production claims and regenerative agriculture sourcing in premium segments. ANSM oversight of veterinary nutritional supplements shapes label claim substantiation requirements for pharmacy-grade products. Lyon and Marseille metropolitan specialty retailers are dedicating expanded shelf space to aseptic Tetra Pack liquid formats with extended ambient distribution capability.
Pet Milk Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hypoallergenic and plant-based positioning as differentiation vectors. The vendor base stratifies across three maturity tiers: legacy neonatal nutrition specialists with decades of veterinary channel relationships, mid-scale regional formulators with captive dairy supply arrangements, and venture-backed entrants commercializing novel protein bases. Consolidation pressure is intensifying as compliance costs compress margin structures for sub-scale operators. Strategic moves concentrate on backward integration into goat milk sourcing and algorithm-driven direct-to-consumer subscription platforms.
Within the legacy specialist tier, Pet-Ag, Inc. and Grober Nutrition exemplify archetypal positioning through species-specific formulation depth and vertically integrated supply control. Beaphar B.V. occupies a distinct European retail-facing position with extended shelf-life liquid formats and pharmacy-grade nutritional supplement integration. These three anchors illustrate the competitive divergence between veterinary authority-driven and consumer convenience-driven channel strategies.
| Leading Market Players |
|---|
| Pet-Ag, Inc. |
| Beaphar B.V. |
| Grober Nutrition |
| Fetch For Pets LLC |
| Manna Pro Products LLC |
| Milk Specialties Global |
| Cargill, Incorporated |
| Royal Canin |
| Land O'Lakes |
| Others |
Value Chain & Pricing Dynamics
Backward integration into goat milk sourcing anchors competitive position and pricing power for established manufacturers, compressing margin exposure to dairy commodity swings while validating premium positioning for species-specific formulations. Captive supply arrangements in Wisconsin and California dairy corridors insulate incumbents from spot-market volatility that erodes private-label competitors.
Pricing Analysis
Input-cost pass-through from goat and cow milk commodities shapes tiered pricing across the market. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-certified therapeutic formulations from mass-market powders and private-label alternatives. Price differentiation rests on AAFCO nutritional adequacy certification and cold-chain delivery infrastructure. Pricing pressure stems from plant-based oat and pea protein substitutes capturing sustainability-conscious households. Mass-market supermarket buyers show highest price sensitivity; veterinary clinics demonstrate lowest sensitivity due to protocol-driven purchasing authority.
Supply Chain Analysis
Workforce availability constraints in Wisconsin and California processing facilities limit spray-drying capacity expansion for powdered formulations. Supply concentrates in United States dairy corridors, Netherlands ingredient technology hubs, and French aseptic packaging operations. Raw material flows draw from goat milk cooperatives, enzymatic lactose-reduction inputs, and pharmaceutical-grade vitamin premixes. Single-source vulnerability in goat milk procurement elevates risk during seasonal kidding cycles. Distribution runs through refrigerated veterinary distributors, ambient Tetra Pack retail networks, and algorithm-driven e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet milk market functions as a stable compounder, with recurring subscription replenishment and veterinary protocol adherence generating predictable revenue streams resistant to economic cyclicality.
For Market Incumbents: Extend formulation pipelines into hypoallergenic camelid and insect-derived protein bases before venture-backed entrants capture veterinary diagnostic momentum. Deepen captive goat milk supply through cooperative equity stakes in Wisconsin and California breeder networks. Invest in AAFCO therapeutic certification for liquid formats to defend margin position against refrigerated private-label encroachment.
For New Entrants and Emerging Players: Begin with algorithm-driven subscription platforms targeting United States coastal metropolitan markets where veterinary telehealth infrastructure enables remote nutritional consultation. White-space exists in carbon-neutral production claims for EU Green Deal-aligned premium segments. Pursue direct-to-consumer auto-ship models with personalized life-stage formulation matching as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional formulators with captive dairy supply arrangements because compliance cost escalation is consolidating sub-scale operators into acquisition-ready positions. Five-to-ten year viability hinges on backward integration depth and species-specific R&D capabilities. Target formulators with established veterinary channel relationships and spray-drying infrastructure. Watch FDA enforcement patterns around lactose-reduction label claims as the inflection indicator for regulatory-driven consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Goat Milk Sourcing | Captive supply from Wisconsin cooperatives insulates margin from commodity volatility. |
| AAFCO Therapeutic Certification Investment | FDA-recognized nutritional adequacy claims validate premium pricing in veterinary channels. |
| Subscription E-Commerce Platform Launch | Auto-ship algorithms with veterinary telehealth integration capture recurring replenishment demand. |
| Hypoallergenic Protein Base Development | Camelid and insect-derived formulations address growing veterinary dairy sensitivity diagnoses. |
| Carbon-Neutral Production Certification | EU Green Deal alignment opens premium positioning in French and German metropolitan retail. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary nutrition formulators, specialty pet retail category managers, dairy cooperative procurement leads, and cold-chain logistics operators with secondary validation. FDA Center for Veterinary Medicine guidance documents, AAFCO model regulations, EFSA feed hygiene standards, and customs trade data on dairy ingredient flows anchored the quantitative foundation. Bottom-up volume modeling across product formats and top-down value reconciliation triangulated market sizing.
Segment-weighting approaches distributed value across powdered and liquid formats, canine and feline species calibrations, and veterinary versus retail channel economics. Modeled dimensions included product type, packaging technology, end-user species, and distribution channel structure. CAGRs derived from historical trajectory analysis and adoption curve projection across the analysis window. Forecast inputs incorporated lactose-reduction enzyme diffusion rates and subscription e-commerce penetration patterns in United States metropolitan markets.
Several conditions sit outside the modeled scope, including abrupt FDA regulatory reinterpretations, catastrophic dairy disease outbreaks affecting goat supply, and rapid consumer preference shifts toward plant-based alternatives. Forecasts reflect documented assumptions about veterinary protocol stability and cold-chain infrastructure investment continuity. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
North America Almond Milk Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Dairy-Free Spreads Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market