
 Vegan Yogurts Market | 2026-2036
Vegan Yogurts Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Yogurts Market Analysis
The vegan yogurts category is pivoting between artisanal small-batch positioning and mass-market commodity pricing. Danone S.A. leverages its refrigerated distribution network to sustain shelf presence across conventional retail. Chobani, LLC anchors its portfolio with Greek-style plant-based textures that differentiate on protein parity. Oatly Group AB competes through barista-channel brand recognition that extends into home-refrigerated purchases.
Vegan yogurt denotes a fermented, spoonable food product manufactured from plant-derived milks such as coconut, almond, soy, or cashew, utilizing bacterial cultures at controlled temperatures to achieve target pH and viscosity. Its commercial purpose centers on delivering functional nutrition and sensory familiarity to consumers avoiding dairy for allergen, ethical, or environmental reasons. Coconut yogurt occupies the premium margin tier due to fat-body richness and clean-label positioning, while soy yogurt dominates manufacturing scale through established protein extraction infrastructure. Supermarkets capture the volume pool, though online retailers represent the fastest-growing distribution channel as direct-to-consumer cold-chain logistics mature.
The FDA governs allergen labeling and GRAS status for novel plant proteins entering US interstate commerce, while EFSA evaluates nutrition and health claims under EU Regulation 1924/2006, directly shaping permissible on-pack messaging. REACH compliance affects European manufacturers sourcing flavor compounds and stabilizers, raising formulation costs for imported ingredient sets. Stakeholders must monitor evolving protein-quality scoring methodologies and their influence on permissible comparative claims against dairy benchmarks.
Market Dynamics
Supermarket private-label programs are compressing brand premiums and forcing established dairy conglomerates to defend refrigerated shelf space through accelerated plant-based line extensions.
Growth Catalysts
- EU Green Deal cold-chain mandates:Refrigerated logistics providers are retrofitting fleets to comply with tightening F-Gas Regulation standards, expanding distribution capacity for plant-based perishables.
- Discounter fixture expansion:German retail chains have carved dedicated vegan dairy sections, normalizing plant-based yogurt placement alongside conventional dairy.
- Protein extraction infrastructure:Soy processing facilities in the Netherlands and Belgium achieve manufacturing scale that lowers unit costs for fermented plant-base production.
Market Restraints
- Coconut milk supply concentration:Southeast Asian harvest volatility creates input cost instability for premium-positioned coconut yogurt formulations.
- REACH compliance burden:European manufacturers face elevated formulation costs when sourcing stabilizers and flavor compounds from non-EU suppliers.
- Dairy sensory parity gap:Technical limitations in fat-body replication constrain mainstream dairy consumers from permanent switching.
Strategic Opportunities
- Direct-to-consumer cold-chain maturation:Specialized refrigerated last-mile logistics unlock subscription-based yogurt delivery models.
- Barista-channel brand extension:Oat milk recognition in coffee service environments creates pull-through demand for home-refrigerated yogurt purchases.
- EFSA protein-quality scoring evolution:Permissible comparative claims against dairy benchmarks open repositioning space for high-protein soy formulations.
Industry Challenges
- Fermentation microbiology talent scarcity:Plant-based culture development requires specialized food science expertise that outpaces current academic pipeline output.
- Multi-jurisdiction label compliance:Divergent FDA and EFSA allergen disclosure requirements force SKU fragmentation and inventory complexity.
- Cold-chain capex intensity:Refrigerated distribution network expansion demands capital allocation that strains mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Yogurts Market |
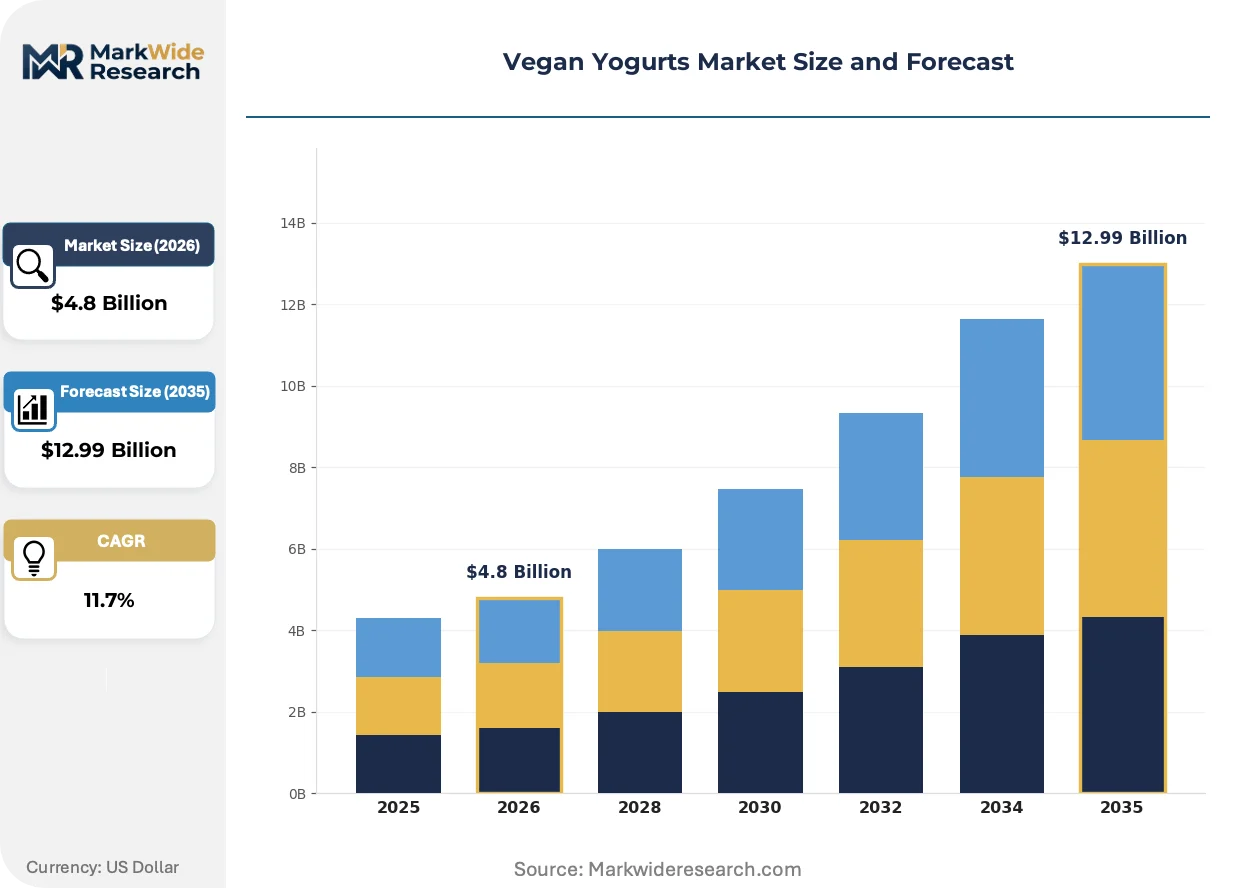
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Yogurt, Almond Yogurt, Soy Yogurt, Cashew Yogurt Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops Flavor: Vanilla, Strawberry, Blueberry, Mango Texture: Creamy, Smooth, Chunky, Whipped |
| Companies Covered | Danone S.A., General Mills, Inc., The Hain Celestial Group, Oatly Group AB, Chobani, LLC, Kite Hill, Califia Farms, Forager Project, COYO Pty Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Yogurts Market Emerging Trajectories
Fermentation technology advances and regulatory pressure on cold-chain emissions are restructuring how plant-based yogurt reaches refrigerated retail cases.
Precision fermentation for dairy-identical proteins is modularizing ingredient supply chains. Specialty ingredient suppliers now license biosynthesis platforms to regional dairy alternatives manufacturers. This technology compression enables smaller production facilities to achieve protein parity without capital-intensive extraction infrastructure.
REACH authorization requirements for novel stabilizer compounds are tightening formulation windows. European manufacturers must pre-register new hydrocolloid combinations before commercial deployment. The regulatory friction most affects coconut yogurt producers seeking clean-label positioning through reduced ingredient lists.
Subscription-based replenishment models are displacing conventional supermarket stock-up behavior. Direct-to-consumer brands bypass retail slotting fees through refrigerated home delivery. Germany and the Netherlands show highest penetration of this channel shift among urban households with dedicated cold storage capacity.
Vegan Yogurts Market Segmentation
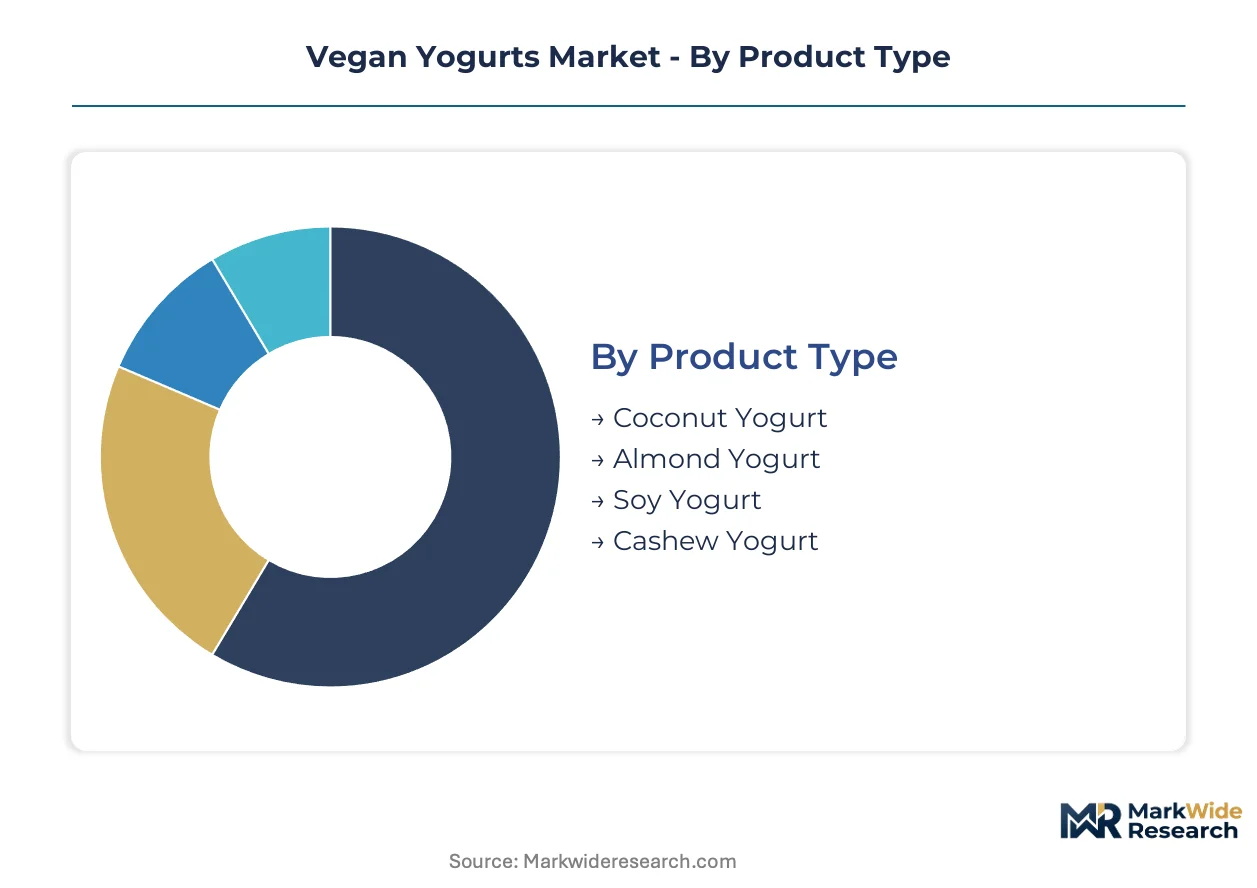
Vegan yogurt manufacturers segment offerings across four dimensions that shape formulation priorities, channel economics, and consumer targeting. Product type and distribution channel carry the heaviest strategic weight, while flavor and texture selections determine SKU proliferation and inventory complexity.
Product Type:
Buyers differentiate by protein source, fat-body characteristics, and clean-label positioning rather than price alone.
- Soy Yogurt:Fermented from isolated soy protein with established bacterial culture compatibility. Manufacturing scale concentrates in the Netherlands and Belgium, where extraction infrastructure lowers unit costs for mainstream retail penetration.
- Coconut Yogurt:Cultured from high-fat coconut cream delivering premium mouthfeel and minimal ingredient lists. Southeast Asian harvest volatility elevates input costs, constraining volume expansion despite margin attractiveness.
- Almond Yogurt:Lower protein content limits functional nutrition claims, though California almond processing networks support consistent supply.
- Cashew Yogurt:Artisanal positioning dominates as African and Indian cashew sourcing faces EFSA allergen disclosure complexity.
Volume sits with soy yogurt; growth tilts toward coconut yogurt.
Distribution Channel:
Channel selection determines cold-chain investment intensity and margin structure through the value chain.
- Supermarkets:Private-label programs compress brand premiums while securing refrigerated fixture space. German discounters have carved dedicated vegan dairy sections normalizing plant-based placement.
- Online Retailers:Direct-to-consumer cold-chain logistics mature fastest in Germany and the Netherlands, enabling subscription replenishment models that bypass slotting fees.
- Health Food Stores:Curated assortments favor coconut and cashew premium tiers with educated consumer bases.
- Specialty Shops:Limited refrigerated capacity restricts assortment breadth to fastest-turning SKUs.
Supermarkets dominate absolute volume; online retailers are expanding most quickly.
Flavor:
Flavor portfolio breadth correlates with manufacturing line flexibility and regional taste preference mapping.
- Vanilla:Base flavor enabling clean-label positioning with minimal stabilizer requirements for texture consistency.
- Strawberry:Highest penetration in European markets with established fruit preparation supply chains.
- Blueberry:North American preference concentration drives seasonal promotion calendars.
- Mango:Premium positioning leverages tropical associations though supply seasonality complicates year-round production.
Vanilla commands baseline volume; mango climbs the fastest on premium positioning.
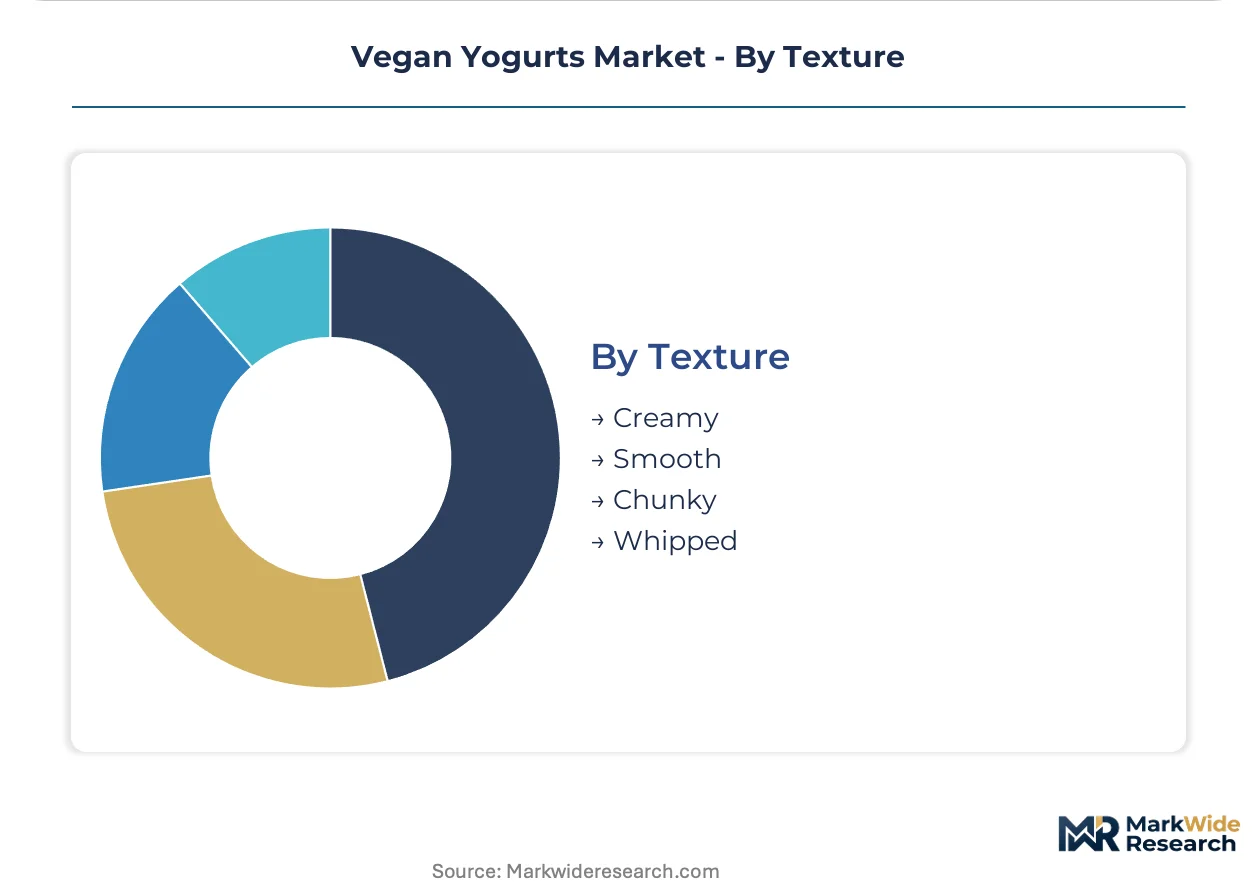
Texture:
Texture engineering separates commodity and premium tiers through fat-body replication and hydrocolloid stabilization.
- Creamy:Target pH and viscosity achieved through coconut fat or added vegetable oils for mainstream sensory acceptance.
- Smooth:Homogenization intensity and stabilizer selection determine pourability for drinking yogurt formats.
- Chunky:Fruit inclusions require modified fermentation protocols to prevent syneresis and maintain shelf stability.
- Whipped:Aeration technology adds processing steps that constrain production scale and elevate unit costs.
Creamy texture anchors mass-market volume; whipped formats gain share fastest in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Randstad corridor anchors European vegan yogurt manufacturing density, with Rotterdam's cold-chain infrastructure enabling refrigerated distribution across northwestern Europe. Plant-based fermentation facilities cluster near soy processing plants in the Netherlands and Belgium, while German retail innovation drives category normalization through dedicated fixture space.
Germany
Discounter chains Aldi and Lidl have carved dedicated vegan dairy sections, normalizing plant-based yogurt placement alongside conventional dairy. The EU Green Deal's F-Gas Regulation mandates fleet retrofitting for refrigerated logistics, expanding distribution capacity for plant-based perishables. Berlin and Hamburg host the densest concentrations of direct-to-consumer vegan yogurt startups leveraging subscription replenishment models.
United States
California almond processing networks support consistent supply for almond-based yogurt formulations, while barista-channel oat milk recognition creates pull-through demand for home-refrigerated purchases. FDA allergen labeling requirements and GRAS status evaluations shape permissible on-pack messaging for novel plant proteins. The Pacific Northwest and Northeast corridor show highest penetration of subscription-based yogurt delivery among urban households with dedicated cold storage capacity.
Netherlands
Soy processing facilities in the Netherlands achieve manufacturing scale that lowers unit costs for fermented plant-base production, supplying private-label programs across European supermarkets. REACH compliance affects manufacturers sourcing flavor compounds and stabilizers, raising formulation costs for imported ingredient sets. The Eindhoven region hosts precision fermentation technology providers licensing biosynthesis platforms to regional dairy alternatives manufacturers.
United Kingdom
Health food store chains favor coconut and cashew premium tiers with educated consumer bases in London and Southeast England. EFSA nutrition and health claims evaluations under EU Regulation 1924/2006 directly shape permissible comparative claims against dairy benchmarks. The Midlands and North England concentrate supermarket private-label manufacturing partnerships with established plant-based dairy suppliers.
France
Artisanal positioning dominates in Île-de-France and Provence-Alpes-Côte d'Azur, with small-batch coconut and cashew yogurt producers targeting premium retail channels. ANSM and CNIL oversight intersects with food labeling requirements, creating multi-layer compliance for direct-to-consumer brands. Lyon and the Auvergne-Rhône-Alpes region host dairy conglomerates accelerating plant-based line extensions to defend refrigerated shelf space.
Vegan Yogurts Market Vendor Landscape
Premium-margin players sit above commodity-margin players across protein source and texture sophistication tiers, with coconut-based formulations commanding higher unit economics than soy-based alternatives. The vendor base stratifies between multinational dairy conglomerates with refrigerated distribution networks, specialized plant-based pure-plays with barista-channel recognition, and regional artisanal producers with clean-label positioning. Three archetypes dominate: legacy dairy diversifiers leveraging existing cold-chain infrastructure, plant-native specialists building brand equity through coffee service environments, and craft fermenters targeting subscription-based replenishment. Competitive intensity centers on M&A activity consolidating regional brands and strategic partnerships securing soy protein extraction capacity.
Within the legacy dairy diversifier tier, Danone S.A. and General Mills, Inc. occupy positions anchored by refrigerated distribution networks that sustain shelf presence across conventional retail. Chobani, LLC exemplifies the Greek-style texture specialist archetype, differentiating on protein parity through plant-based line extensions. Oatly Group AB anchors the barista-channel extension strategy, converting coffee service brand recognition into home-refrigerated yogurt purchases.
| Leading Market Players |
|---|
| Danone S.A. |
| General Mills, Inc. |
| The Hain Celestial Group |
| Oatly Group AB |
| Chobani, LLC |
| Kite Hill |
| Califia Farms |
| Forager Project |
| COYO Pty Ltd |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating fleet retrofitting for refrigerated logistics providers, elevating capital barriers for mid-tier manufacturers while concentrating pricing power among legacy dairy conglomerates with existing cold-chain infrastructure.
Pricing Analysis
Value-based pricing anchored to sensory parity outcomes separates coconut yogurt formulations commanding premium positioning from soy-based commodity tiers. Three-tier pricing structure across premium, standard, and economy levels tracks protein source, fat-body replication fidelity, and clean-label ingredient count. Cost compression in the soy yogurt tier is intensifying because German discounter private-label programs compress brand premiums. Mainstream dairy switchers show highest price sensitivity, while health-motivated buyers in urban Netherlands and Germany markets tolerate elevated unit costs for minimal-ingredient coconut formulations.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised plant-based perishables remain underdeveloped, constraining inventory recovery and elevating working capital requirements for direct-to-consumer brands. Raw material sourcing draws from Southeast Asian coconut cream suppliers, Dutch and Belgian soy protein extraction facilities, and California almond processing networks. Single-source vulnerability concentrates in Thai and Indonesian coconut harvests exposed to climate volatility. Distribution runs through supermarket refrigerated fixtures dominating volume, with specialized cold-chain last-mile operators emerging fastest in German and Dutch urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
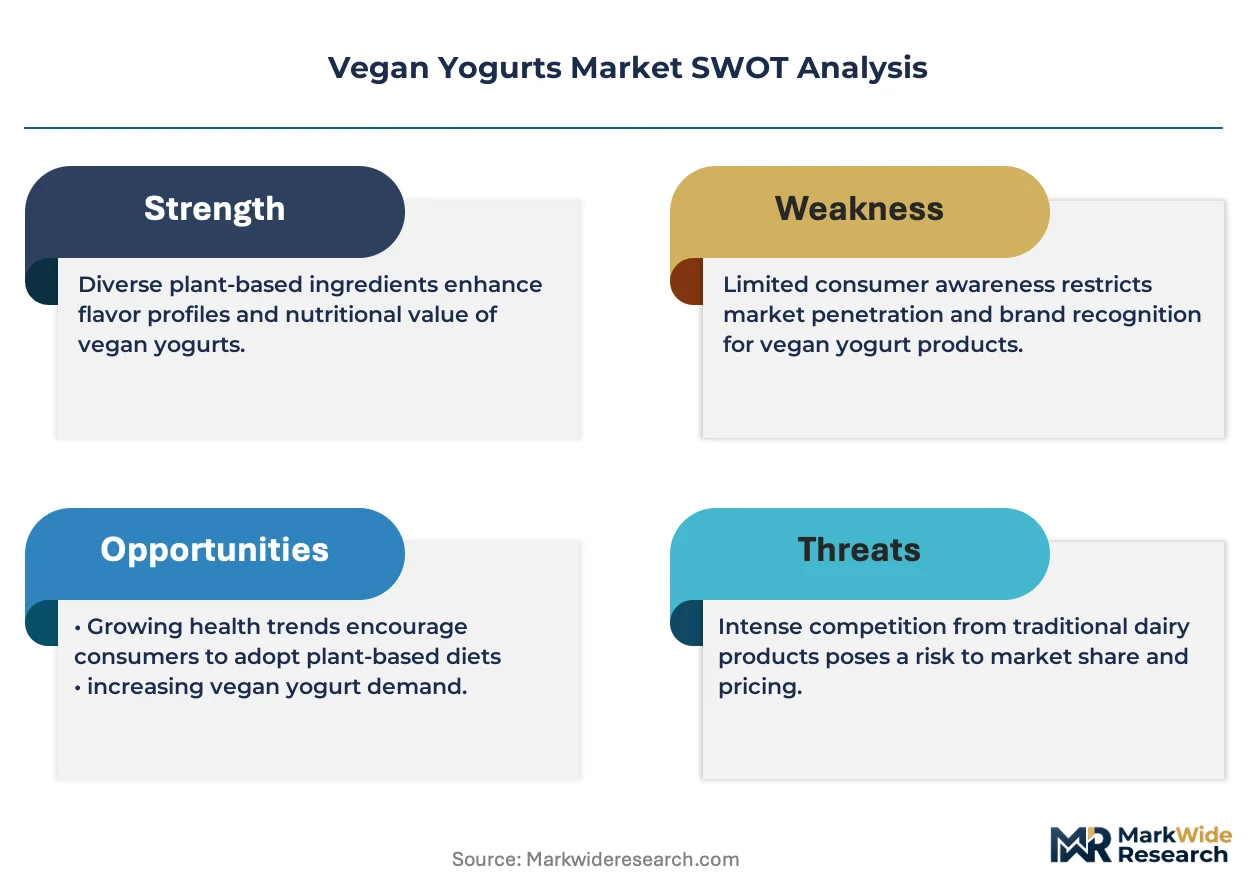
The vegan yogurts market reads as a cost-of-compliance story where REACH authorization requirements for novel stabilizer compounds create a barrier-to-entry moat for European manufacturers with pre-registered hydrocolloid portfolios.
For Market Incumbents: Anticipate accelerated private-label encroachment by securing captive soy protein extraction capacity in the Netherlands or Belgium. Defend refrigerated fixture space through precision fermentation partnerships that achieve dairy-identical protein parity without capital-intensive infrastructure buildout. For New Entrants and Emerging Players: Precision fermentation technology licenses offer a technology-first wedge into premium-tier positioning previously inaccessible to capital-constrained challengers. White-space targets cluster in subscription-based replenishment models bypassing German supermarket slotting fees, and in barista-channel brand extension converting coffee service recognition into home-refrigerated purchases. For Investors and Strategic Acquirers: EFSA protein-quality scoring methodology revisions are the leading indicator that permissible comparative claims against dairy benchmarks will reposition high-protein soy formulations for accelerated adoption. Long-term viability favors acquiring regional artisanal fermenters with clean-label positioning and established direct-to-consumer cold-chain relationships, monitoring REACH compliance cost escalation as the signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Biosynthesis platform licensing enables smaller facilities to achieve protein parity without extraction infrastructure. |
| Direct-to-Consumer Cold-Chain Buildout | Specialized refrigerated last-mile logistics unlock subscription replenishment models bypassing retail slotting fees. |
| Private-Label Defense Program | Accelerated plant-based line extensions secure supermarket fixture space against discounter compression. |
| EFSA Claims Authorization Investment | Pre-submission nutrition and health claims evaluations shape permissible on-pack messaging against dairy benchmarks. |
| Soy Protein Extraction Integration | Backward integration into Dutch or Belgian processing infrastructure locks in manufacturing scale advantages. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant-based dairy R&D directors, supermarket category buyers, refrigerated logistics operators, and precision fermentation technology providers. EFSA guidance documents, FDA GRAS notifications, EU cold-chain emissions compliance databases, and retail audit data from Nielsen and Circana furnished quantitative benchmarks. Bottom-up volume modeling triangulated against top-down market sizing from trade association aggregates.
Data-stream reconciliation across shipment volumes, production capacity disclosures, and channel inventory turns generated consistent baseline estimates. Segmentation dimensions modeled include protein source, distribution channel, texture sophistication tier, and regional regulatory cluster. CAGRs were derived from fitted trend projections accounting for private-label penetration curves and cold-chain infrastructure buildout rates across the analysis window. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and EFSA protein-quality scoring evolution scenarios.
Several conditions sit outside the modeled scope, including precision fermentation regulatory approval pathways for novel dairy-identical proteins and potential REACH authorization rejections for hydrocolloid stabilizer combinations. Forecasts reflect assumptions about sustained discounter fixture expansion and stable Southeast Asian coconut supply. Practitioners should monitor EFSA comparative claims rulings and Thai harvest yield reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Germany Dairy Alternatives Market