
 Instant Starches Market | 2026-2036
Instant Starches Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Starches Market Analytics
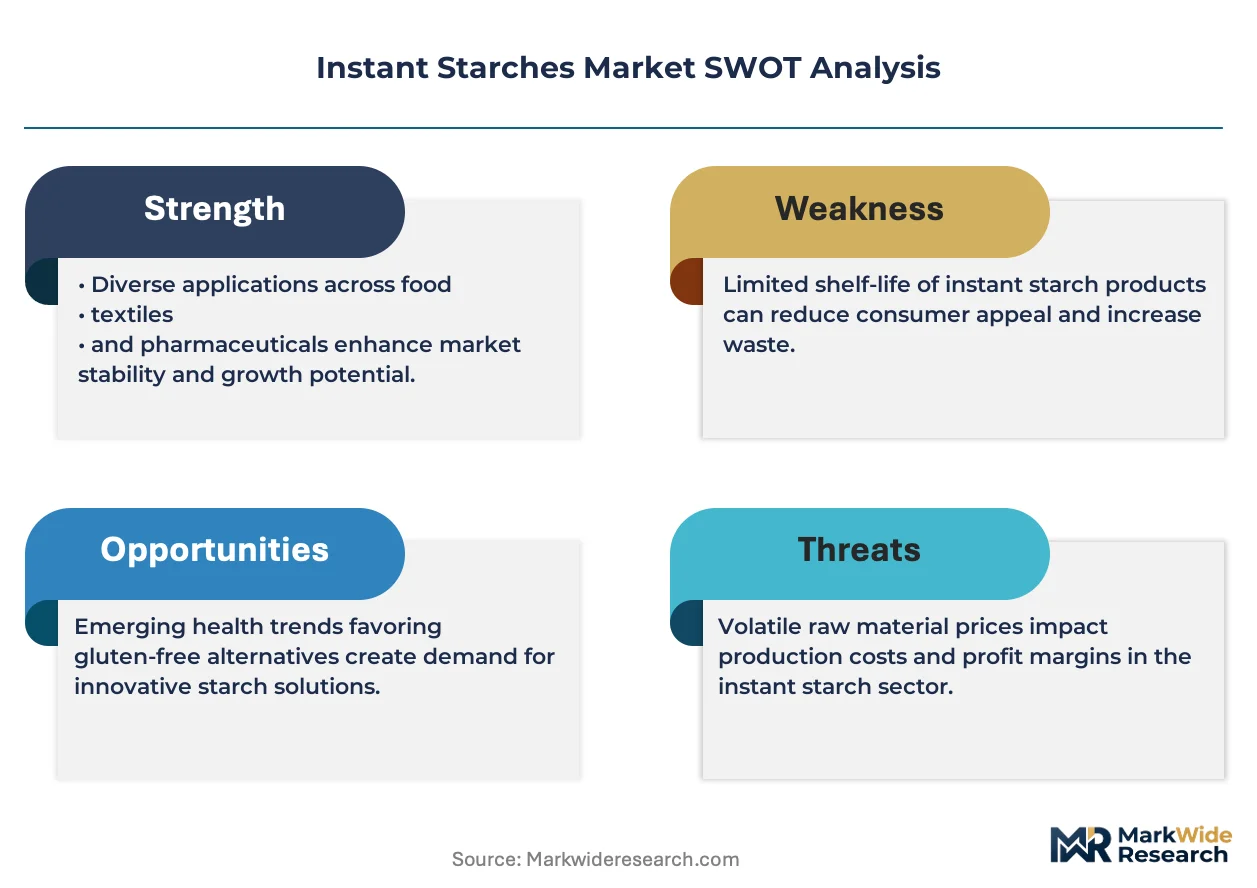
EU REACH chemical registration requirements is broadening the cost-of-entry calculus for instant starch suppliers seeking European market access. Cargill, Incorporated leverages its integrated corn processing network to sustain cost advantages across modified starch grades. Ingredion, Inc. anchors its position through deep R&D intensity in clean-label texturizing solutions. Tate & Lyle PLC differentiates via specialty pre-gelatinized starches tailored to pharmaceutical binding applications.
Instant starches comprise physically or chemically treated carbohydrate polymers derived from corn, potato, tapioca, or wheat, processed to achieve cold-water solubility, rapid viscosity development, or specific gel strength measured in Bloom grams. These functional ingredients serve as thickeners, binders, stabilizers, and fat replacers across formulated food systems, oral dosage forms, and industrial adhesives. Modified starch commands the largest value share due to its engineered performance in retort-stable sauces and UHT-processed dairy analogues. Pre-gelatinized starch represents the fastest-expanding category as bakery and snack manufacturers adopt no-cook processing lines to reduce energy input and cycle times.
FDA Food Safety Modernization Act protocols, EU REACH chemical registration frameworks, and ISO 22000 food safety management standards collectively govern ingredient purity, allergen labeling, and supply chain traceability for instant starch producers. These regulatory layers elevate testing burdens but simultaneously create competitive moats for certified suppliers capable of documenting batch-level provenance. Stakeholders must monitor evolving clean-label definitions and bioengineered disclosure mandates to anticipate reformulation requirements and secure preferred supplier status with multinational food processors.
Market Dynamics
Clean-label reformulation mandates from major food processors are compressing synthetic additive demand while expanding modified starch volumes across retort-stable and UHT-processed applications. This structural shift elevates supplier qualification burdens and concentrates procurement among certified producers capable of batch-level traceability documentation.
Growth Catalysts
- FSMA traceability protocols:The FDA's updated Food Safety Modernization Act requirements for processed ingredients are forcing large-scale food manufacturers to source from certified instant starch suppliers with documented supply chain provenance.
- No-cook processing adoption:Bakery and snack manufacturers deploying energy-reduced production lines are pulling pre-gelatinized starch volumes to eliminate cooking cycles and reduce thermal input costs.
- Pharmaceutical binding specifications:Oral dosage form producers in the United States are specifying specialty pre-gelatinized starches for tablet binding applications to replace synthetic polymer excipients.
Market Restraints
- Corn input volatility:Feedstock price swings for maize directly compress margin structures across modified starch grades, exposing non-integrated processors to raw material cost spikes.
- REACH registration burdens:EU chemical registration requirements for modified starch variants impose documentation costs that exclude smaller suppliers from European market access.
- Clean-label definitional drift:Evolving consumer and retailer interpretations of "natural" create reformulation uncertainty, forcing redundant product development cycles without stable specification targets.
Strategic Opportunities
- Pharmaceutical excipient expansion:Controlled-release tablet applications in the United States present white space for high-purity pre-gelatinized starch grades with documented Bloom gram specifications.
- Bioengineered disclosure preparation:Anticipated USDA bioengineered ingredient labeling mandates create first-mover advantage for suppliers with verified non-GMO corn sourcing and segregated handling infrastructure.
- Industrial adhesive diversification:Corrugated board and paper laminating operations are testing cold-water soluble starch adhesives to replace petroleum-derived synthetic binders in packaging applications.
Industry Challenges
- ISO 22000 certification timelines:Food safety management system audits require 12-18 month implementation periods, delaying supplier qualification with multinational processors.
- Retrofitting legacy spray-dryers:Pre-gelatinized starch production demands capital-intensive equipment upgrades for hydration control and particle size distribution precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Starches Market |
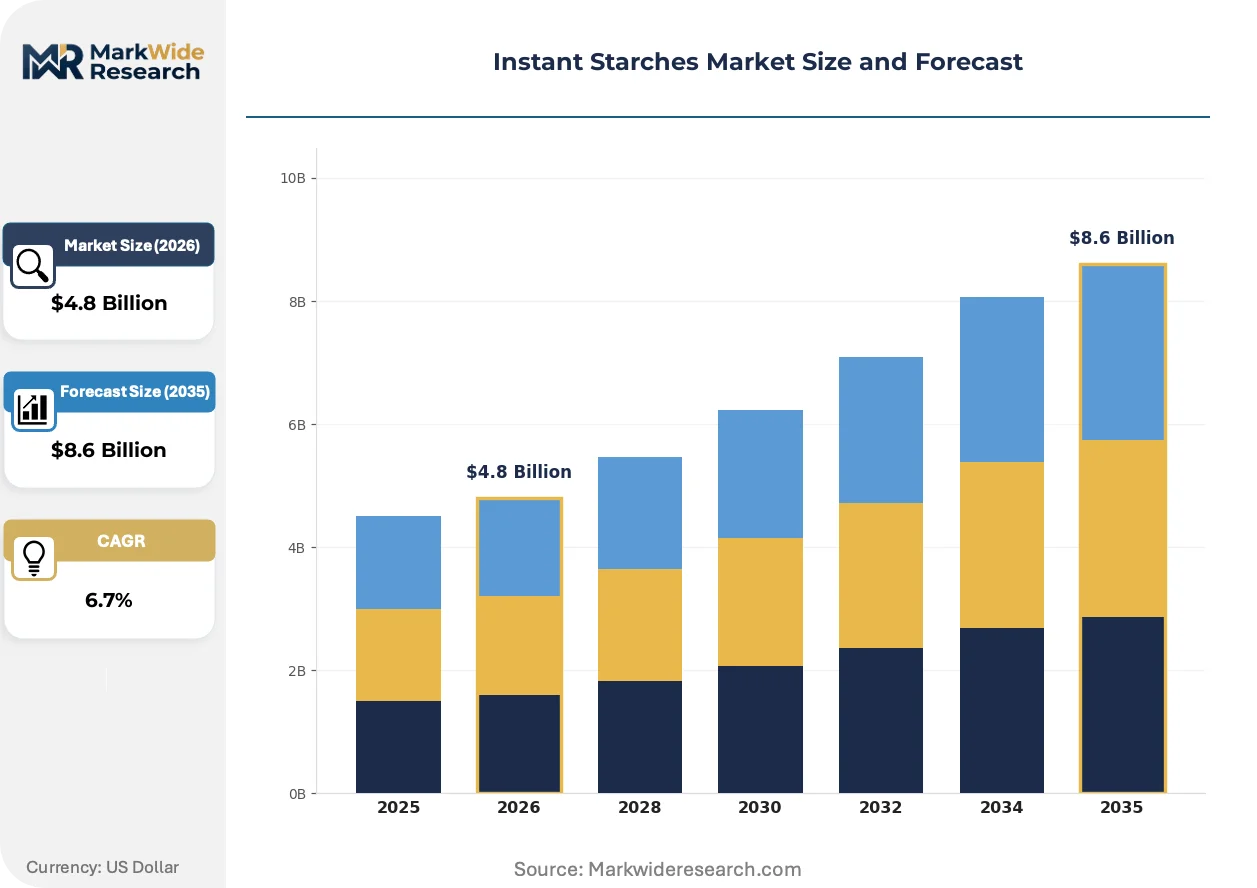
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Pre-gelatinized Starch, Instant Flour Application: Food & Beverage, Pharmaceuticals, Cosmetics, Paper Manufacturing End User: Food Processors, Bakeries, Confectioneries, Pharmaceutical Companies Packaging Type: Bags, Drums, Bulk Containers, Sachets |
| Companies Covered | Cargill, Incorporated, Ingredion, Inc., Tate & Lyle PLC, Archer Daniels Midland Company, Roquette Frères, Avebe U.A., Grain Processing Corporation, Emsland Group, Global Bio-Chem Technology Group Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Starches Market Evolving Landscape
Physical modification technologies are displacing chemical derivatization across instant starch production, driven by clean-label specifications and energy efficiency targets. This shift compresses traditional processing margins while opening premium positioning for enzymatically treated variants.
Enzymatic hydrolysis systems are integrating into modified starch production lines to achieve targeted viscosity profiles without chemical cross-linking agents. Mid-sized sauce and dressing manufacturers in the United States are adopting these enzymatically treated starches at accelerating rates. The technology is integrating cold-water solubility with clean-label positioning, enabling suppliers to capture price premiums from synthetic additive replacement mandates.
EU REACH chemical registration frameworks are tightening substance documentation requirements for imported modified starches entering European food and pharmaceutical channels. Industrial consequence includes mandatory safety data sheet revisions and extended supplier audit protocols. Pre-gelatinized starch grades destined for pharmaceutical binding applications face the most intensive scrutiny, with importers establishing dedicated regulatory affairs functions to manage ECHA compliance.
Direct procurement contracts between instant starch processors and large-scale food manufacturers are consolidating purchasing volumes and compressing distributor margins. Foodservice and industrial channels are being disrupted by captive supply agreements that bypass traditional ingredient distribution networks. This concentration is most visible across the United States, where multinational processors are qualifying single-source modified starch suppliers for multi-year retort sauce contracts.
Instant Starches Market Segmentation
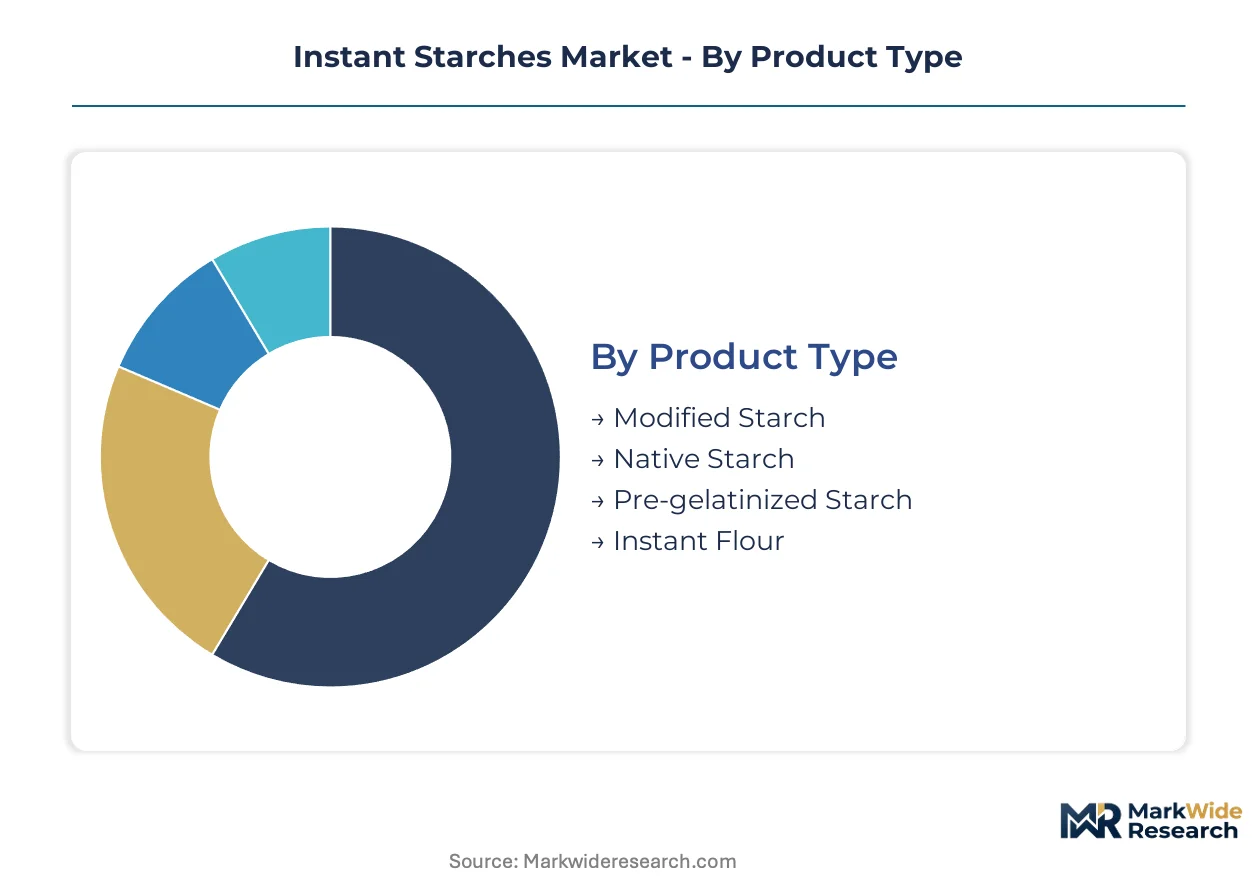
Instant starches serve divergent performance requirements across food, pharmaceutical, and industrial channels. Segmentation reveals where capital deployment, formulation expertise, and regulatory compliance create sustainable competitive position.
Product Type:
Capital intensity varies sharply across production technologies, with chemical modification and pre-gelatinization requiring the heaviest equipment investment.
- Modified Starch:Chemically or physically altered carbohydrate polymers engineered for specific viscosity, stability, or freeze-thaw resistance. Food processors in the United States specify these grades for retort-stable sauces and UHT-processed dairy analogues where synthetic additive replacement is mandated. FDA Food Safety Modernization Act traceability requirements concentrate procurement among certified suppliers with documented batch provenance.
- Pre-gelatinized Starch:Starch granules subjected to controlled hydration and thermal treatment, then dried to achieve cold-water solubility without cooking. Bakery and snack manufacturers deploy these variants on no-cook processing lines to eliminate thermal cycles and reduce energy input costs. The category is gaining share fastest from clean-label reformulation mandates.
- Native Starch:Unmodified carbohydrate polymers extracted directly from corn, potato, tapioca, or wheat sources, retaining natural granule structure and gelatinization temperature.
- Instant Flour:Pre-cooked wheat or alternative grain flours processed for rapid hydration and reduced lumping in reconstituted applications.
Most installed capacity flows through Modified Starch. Expansion is steepest in Pre-gelatinized Starch.
Application:
Margin structures diverge by end-use, with pharmaceutical and cosmetic channels commanding premium pricing against commoditized paper manufacturing volumes.
- Food & Beverage:Largest demand channel spanning sauces, dressings, dairy analogues, and convenience meal systems. Clean-label specifications from multinational processors are displacing synthetic thickeners and stabilizers.
- Pharmaceuticals:Oral dosage form applications including tablet binding, disintegration control, and controlled-release matrix systems. United States pharmaceutical companies specify high-purity pre-gelatinized grades with documented Bloom gram specifications to replace synthetic polymer excipients.
- Cosmetics:Skin and hair care formulations utilizing starch-derived texturizers and oil-absorbing powders.
- Paper Manufacturing:Surface sizing and coating applications for printability and stiffness enhancement in corrugated and specialty paper grades.
Volume concentrates in Food & Beverage. Value expansion runs highest in Pharmaceuticals.
End User:
Procurement sophistication separates large-scale food processors with captive supply agreements from fragmented bakery and confectionery operators purchasing through distribution.
- Food Processors:Multinational manufacturers of retort sauces, UHT dairy analogues, and convenience meals. These buyers qualify single-source suppliers for multi-year contracts with batch-level traceability documentation.
- Pharmaceutical Companies:Dosage form producers specifying excipient grades with ISO 22000 certification and REACH-compliant documentation for European market access.
- Bakeries:Regional and national operators adopting pre-gelatinized starches for no-cook processing lines.
- Confectioneries:Candy and chocolate manufacturers utilizing modified starches for texture control and fat replacement.
Contract concentration is tightest with Food Processors. Qualification velocity is fastest among Pharmaceutical Companies.
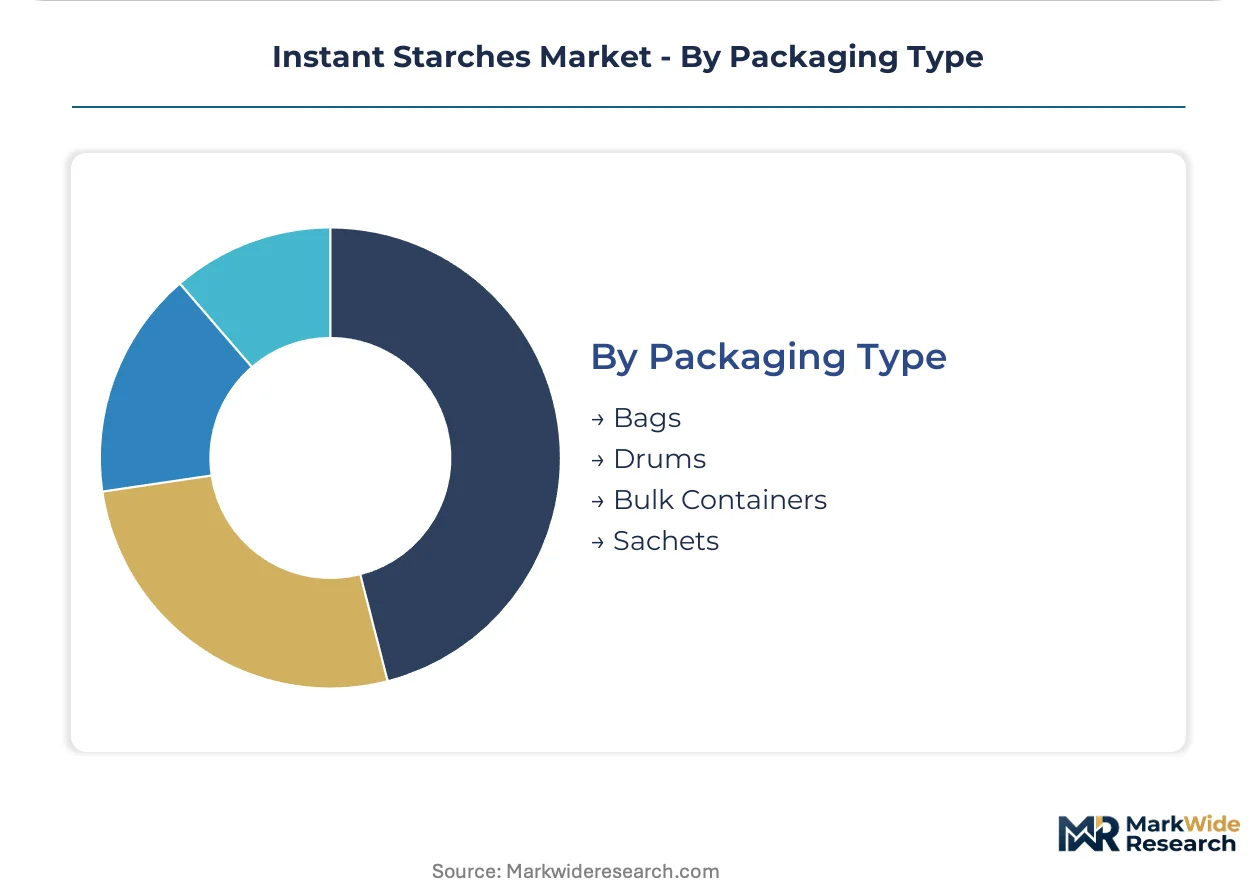
Packaging Type:
Handling economics and contamination risk shape packaging selection, with bulk formats dominating high-volume food processing and unitized packaging serving fragmented channels.
- Bulk Containers:Tanker and tote formats for just-in-time delivery to large-scale food processors with dedicated handling infrastructure.
- Drums:Standardized steel or fiber containers for pharmaceutical and cosmetic manufacturers with controlled-environment receiving.
- Bags:Multi-wall paper or woven polypropylene for mid-scale bakeries and confectioneries.
- Sachets:Pre-measured unit doses for foodservice and small-batch pharmaceutical compounding.
Throughput runs highest through Bulk Containers. Format innovation concentrates in Sachets for foodservice convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and formulation chemists cluster in the United States, Germany, and Japan, anchoring demand concentration for instant starches across three distinct regulatory environments.
United States
Large-scale food processors in the Midwest and Southeast are reformulating retort-stable sauces and UHT dairy analogues to reduce synthetic additive dependence. FDA Food Safety Modernization Act traceability protocols are forcing manufacturers to source from certified suppliers with documented batch-level provenance. The Chicago-Minneapolis corridor hosts the densest concentration of modified starch procurement teams qualifying single-source suppliers for multi-year contracts.
Germany
Specialty pre-gelatinized starch demand from pharmaceutical tablet binding applications is expanding in the Rhine-Ruhr and Bavarian industrial zones. ECHA REACH registration requirements for modified starch variants impose documentation costs that concentrate market access among established suppliers with dedicated regulatory affairs functions. Frankfurt's pharmaceutical excipient cluster is driving specification intensity for Bloom gram documentation.
China
Bakery and snack manufacturers in the Yangtze River Delta are deploying no-cook processing lines to eliminate thermal cycles and reduce energy input costs. SAMR food safety standards and evolving clean-label interpretations are creating reformulation uncertainty without stable specification targets. Shanghai's food technology parks are piloting enzymatically treated starch variants for cold-water solubility applications.
India
Mid-scale confectionery and convenience food producers in Maharashtra and Gujarat are adopting pre-gelatinized starches for texture control and fat replacement. FSSAI allergen labeling mandates and supply chain traceability requirements are elevating testing burdens for imported modified starch grades. The Mumbai-Pune industrial corridor is emerging as a qualification hub for ISO 22000-certified suppliers.
Brazil
Paper manufacturing and corrugated board operations in São Paulo state are testing cold-water soluble starch adhesives to replace petroleum-derived synthetic binders. ANVISA pharmaceutical excipient regulations are tightening purity documentation for pre-gelatinized grades entering oral dosage form channels. The Campinas-Sorocaba axis is consolidating industrial starch handling infrastructure for just-in-time delivery.
Instant Starches Market Competitive Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive corn processing networks. Three tiers separate multinational ingredient suppliers with global distribution infrastructure from regional specialists focused on pharmaceutical-grade certification and industrial adhesive applications. Dominant competitive moves include backward integration into maize sourcing to compress feedstock volatility and strategic partnerships with large-scale food processors for captive supply agreements.
Within the integrated agribusiness tier, Cargill, Incorporated and Ingredion, Inc. represent archetypal positions anchored by North American corn processing density. Tate & Lyle PLC occupies a specialty positioning exemplifying the pharmaceutical-grade pre-gelatinized starch vector. These three entities collectively illustrate how regulatory compliance infrastructure—REACH documentation, FDA FSMA traceability, ISO 22000 certification—functions as a competitive moat excluding smaller suppliers from multinational procurement channels.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Ingredion, Inc. |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Roquette Frères |
| Avebe U.A. |
| Grain Processing Corporation |
| Emsland Group |
| Global Bio-Chem Technology Group Company Limited |
| Others |
Value Network & Pricing Analysis
Captive corn processing networks at Cargill and Ingredion anchor supply positions while compressing feedstock volatility exposure. This backward integration into maize sourcing grants pricing power over non-integrated processors facing spot market corn swings. FDA Food Safety Modernization Act traceability mandates further concentrate procurement leverage among certified suppliers with documented batch provenance.
Pricing Analysis
Bundled certification-plus-documentation services command premiums over unbundled commodity grades. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates premium pre-gelatinized starches with Bloom gram specifications from standard modified grades. Cost compression in industrial-grade segments is intensifying because paper manufacturing buyers prioritize volume scale over performance specifications. Pharmaceutical companies exhibit least price sensitivity due to excipient purity requirements, while corrugated board operators demonstrate highest sensitivity to per-ton delivered costs.
Supply Chain Analysis
Freight cost differentials between bulk tanker and bagged formats reshape regional competitiveness for instant starch suppliers. Production concentrates in the United States, Germany, and China where corn wet-milling infrastructure and pharmaceutical excipient clusters coexist. Supply chains draw from maize, potato, and tapioca feedstocks with enzyme and chemical modifier dependencies. Single-source vulnerability runs through specialized pre-gelatinized spray-dryer capacity. Distribution runs through direct procurement contracts with multinational food processors, bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instant starches constitute a late-cycle quality story as clean-label reformulation mandates shift demand toward certified, traceable grades with documented performance specifications. Pharmaceutical binding applications in the United States exemplify this premium specification drift.
For Market Incumbents: Hedge against enzymatic hydrolysis technology displacement by accelerating physical modification R&D investment. Consolidate supplier qualification advantages through ISO 22000 certification expansion into emerging pharmaceutical clusters. Defensive positioning requires backward integration into non-GMO corn sourcing infrastructure ahead of anticipated USDA bioengineered disclosure mandates. For New Entrants and Emerging Players: Mid-scale bakery operators in India and Brazil represent an underserved buyer archetype seeking pre-gelatinized starches without multinational minimum order requirements. White-space targets include sachet-format foodservice distribution and pharmaceutical compounding channels. A regional toll-processing partnership with existing spray-dryer operators enables market entry without capital-intensive equipment deployment. For Investors and Strategic Acquirers: Roll-up economics work for regional ISO 22000-certified specialists because multinational processor procurement consolidation is compressing distributor margins and creating captive supply gaps. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. The signal to watch is ECHA REACH registration completion rates among mid-tier European suppliers as a proxy for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Non-GMO Corn Sourcing | Segregated handling infrastructure secures preferred supplier status ahead of USDA bioengineered labeling mandates. |
| Pharmaceutical Excipient Certification Investment | Bloom gram documentation and ECHA REACH compliance open premium pricing in oral dosage form channels. |
| Spray-Dryer Capacity Expansion | Controlled hydration and particle size precision enable pre-gelatinized starch production for no-cook processing lines. |
| Direct Procurement Contract Consolidation | Multi-year captive supply agreements with multinational food processors bypass traditional distribution networks. |
| Enzymatic Hydrolysis Technology Adoption | Physical modification systems achieve clean-label positioning without chemical cross-linking agent dependencies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged plant managers at corn wet-milling facilities, procurement leads at multinational food processors, pharmaceutical excipient specification chemists, and distribution channel partners handling bulk starch logistics. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, ECHA REACH substance registrations, ISO 22000 certification databases, and customs trade flows for modified starch HS codes. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Segment-weighting approaches distributed value across product type, application, and end-user dimensions. The analytical framework modeled modified starch, pre-gelatinized starch, native starch, and instant flour categories against food and beverage, pharmaceutical, cosmetic, and paper manufacturing channels. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules across the projection horizon. Forecast inputs incorporated clean-label reformulation velocity, no-cook processing line adoption rates, and pharmaceutical excipient specification intensity.
Underlying measurement precision varies by segment; pharmaceutical-grade pre-gelatinized starches carry tighter precision than industrial adhesive applications due to documented Bloom gram standardization. Forecasts reflect assumptions regarding regulatory timeline adherence and feedstock price stability that could revise materially with corn market volatility or ECHA documentation requirement changes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Protein Market
Ingredients
Mirepoix Market
Ingredients
North America Soy Protein Market
Ingredients
Yeast Peptide Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Citrus Fiber Market
Ingredients
Glucuronolactone Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Agar Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Yeast Autolysates Market
Ingredients
Carotenes Market
Ingredients
South America Lipid Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Cottonseed Oil Market