
 On-The-Go Yoghurt Market | 2026-2036
On-The-Go Yoghurt Market Size, Share, and Industry Trends Forecast 2026-2036
On-The-Go Yoghurt Market Analytics
The on-the-go yoghurt category is rebalancing between premium functional formulations with added protein and probiotics versus commodity single-serve cups competing on price. Chobani leverages its Greek yoghurt heritage to dominate the high-protein drinkable segment. Danone sustains European market presence through specialized organic and plant-based lines. Nestlé competes across multiple price tiers with global manufacturing scale.
On-the-go yoghurt denotes fermented dairy or plant-based products formulated for single-serve portability, typically requiring refrigeration below 8°C and achieving shelf lives of 21–45 days through controlled pH and aseptic filling processes. Drinkable yoghurt leads volume due to bottle-format compatibility with vending machines and transit consumption. Yoghurt parfaits command margin concentration through layered granola inclusion and premium positioning. Pouch packaging among children shows fastest structural expansion as squeeze formats reduce spillage and enable unsupervised consumption.
The FDA governs labelling standards for live and active cultures in the United States, while the USDA oversees school nutrition program eligibility that shapes institutional demand. The EU's CE marking and EFSA health claim authorizations determine which functional benefits brands may communicate across member states. Stakeholders must monitor evolving extended-shelf-life technologies and refrigeration-free distribution trials that could redraw competitive boundaries.
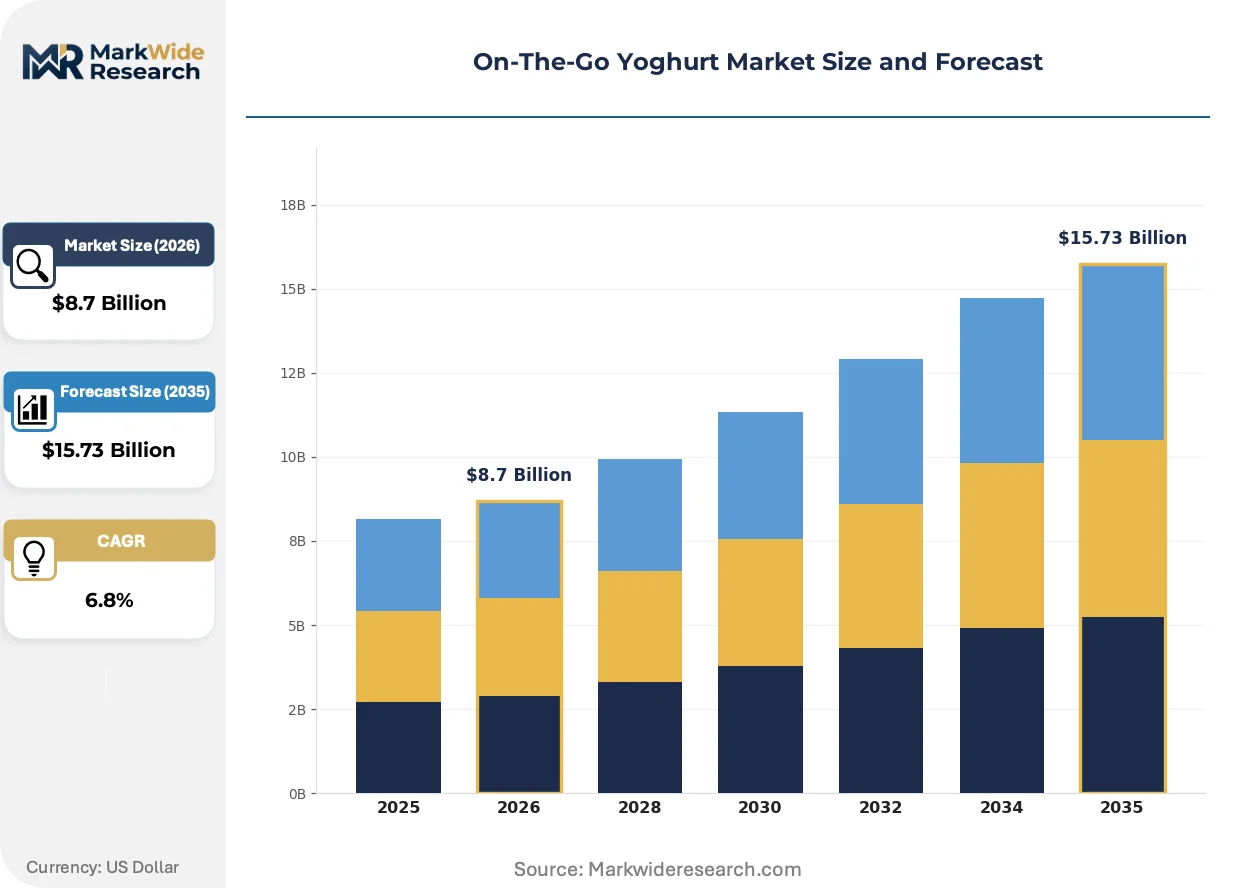
Market Dynamics
Refrigeration logistics consolidation is reshaping competitive boundaries in on-the-go yoghurt, as the EU's F-Gas Regulation phases down hydrofluorocarbon coolants and forces cold-chain operators toward alternative systems. This regulatory pressure cascades through distribution economics, favoring manufacturers with scale to absorb retrofit costs and penalizing regional players dependent on third-party logistics.
Growth Catalysts
- Urban Transit Infrastructure:Expanded metro and commuter rail networks in the United States, Germany, and Japan create captive consumption moments where drinkable formats outperform spoonable alternatives.
- EFSA Health Claim Pathways:Approved probiotic and protein claims enable functional positioning that commands shelf-space premiums in European retail.
- Aseptic Filling Advances:Extended-shelf-life technologies stretch distribution radii without cold-chain dependency, opening rural and institutional channels previously uneconomical to serve.
Market Restraints
- Dairy Input Volatility:Milk powder and whey protein concentrate prices fluctuate with New Zealand and EU dairy auction cycles, compressing margin predictability for contract manufacturers.
- Cold-Chain Concentration:Third-party refrigerated logistics in the United States concentrates among four national providers, creating bottleneck risk during peak summer demand.
- Plant-Based Substitution:Oat and almond milk drinkables capture shelf-space and trial budgets from traditional dairy yoghurt in urban coastal markets.
Strategic Opportunities
- Indian Convenience Retail:Modern trade expansion in Mumbai, Bangalore, and Delhi creates first-mover advantage for chilled single-serve formats as cold-chain infrastructure penetrates tier-1 cities.
- School Nutrition Mandates:USDA school breakfast program eligibility criteria favor portable dairy proteins, creating institutional volume anchors for compliant suppliers.
- Smart Vending Convergence:Refrigerated vending machines with cashless payment and telemetry integration enable placement in transit hubs, gyms, and corporate campuses without retail labor.
Industry Challenges
- Thermal Packaging Engineering:Developing insulated pouches that maintain sub-8°C temperatures for 4+ hours in ambient conditions requires materials science capabilities scarce among mid-tier converters.
- Multi-Jurisdiction Label Compliance:Simultaneous FDA, EFSA, and FSSAI live-culture disclosure requirements force SKU proliferation and inventory segmentation.
- Refrigeration Technician Shortage:Cold-chain fleet maintenance depends on EPA Section 608 certified technicians, with pipeline constraints lengthening equipment downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-The-Go Yoghurt Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drinkable Yoghurt, Yoghurt Tubes, Yoghurt Smoothies, Yoghurt Parfaits End User: Adults, Children, Athletes, Health Enthusiasts Flavor: Strawberry, Blueberry, Peach, Vanilla Packaging Type: Plastic Cups, Pouches, Bottles, Tetra Packs |
| Companies Covered | Chobani, Danone, Nestlé, Materne North America, Alpro UK, Origin Food Group, Yoplait (General Mills), Müller, Sprout Organic Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-The-Go Yoghurt Market Evolving Landscape
Active packaging and formulation science are compressing the traditional trade-off between shelf stability and live-culture efficacy. These advances enable new distribution geometries that bypass conventional cold-chain constraints.
High-pressure processing is modularizing the link between production scale and market reach. Mid-size dairy processors in Wisconsin and Bavaria adopt HPP lines to achieve 45-60 day shelf lives without terminal heat treatment. This technology is modularizing regional production networks, allowing smaller plants to serve distant markets previously requiring central manufacturing and overnight refrigerated trucking.
The EU's F-Gas Regulation is accelerating refrigerant transition timelines across European cold-chain assets. Operators face mandated phase-down quotas for hydrofluorocarbons, forcing capital deployment into CO2 transcritical systems or ammonia-based alternatives. German and Dutch logistics providers lead retrofit adoption, while southern European operators lag, creating divergence in per-unit distribution costs.
Commuter consumption patterns are fragmenting traditional daypart segmentation. Urban professionals in London, New York, and Tokyo consume drinkable yoghurt during evening transit as satiety management, displacing some snack-bar occasions. Convenience retailers respond with chilled grab-and-go placement at platform exits and building lobbies, capturing impulse selection outside conventional grocery trips.
On-The-Go Yoghurt Market Segmentation
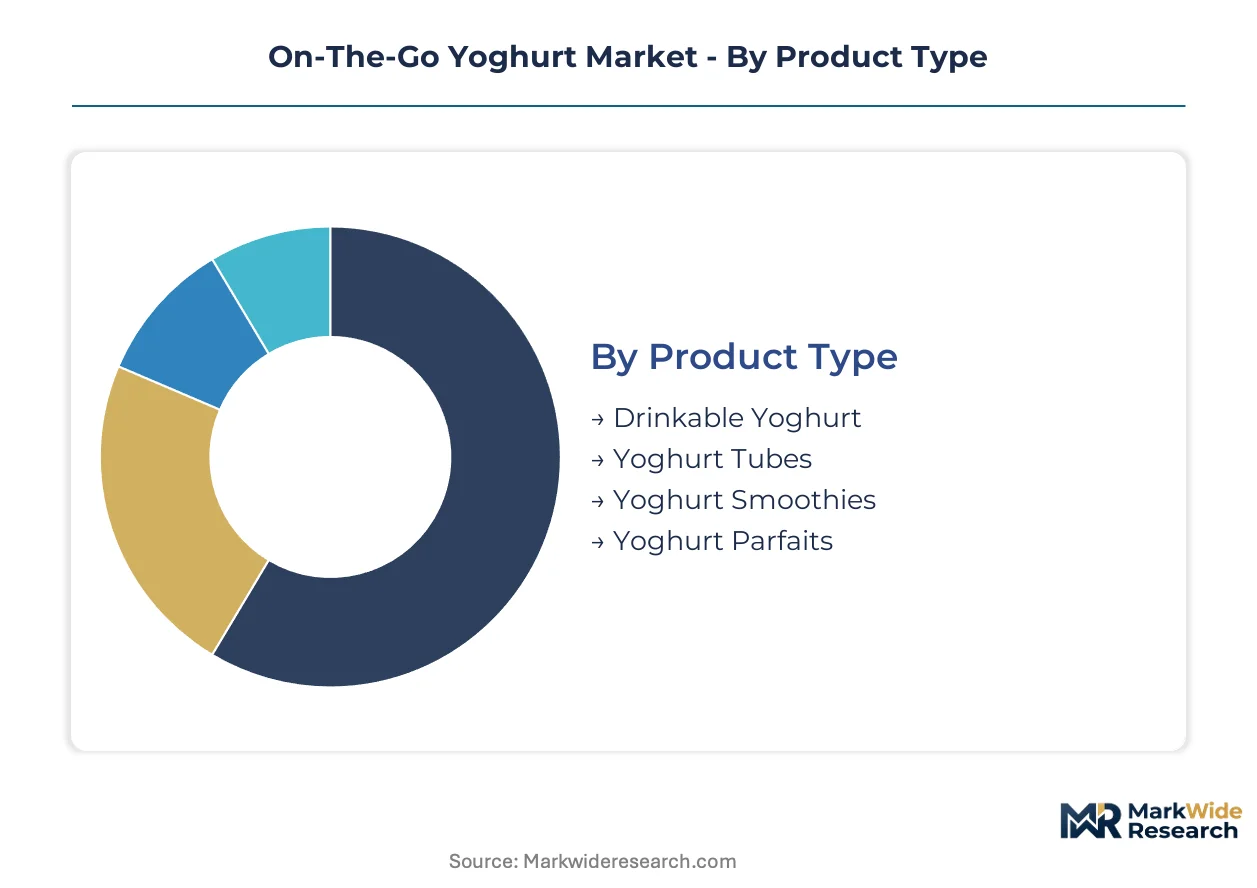
Segmentation in on-the-go yoghurt reveals distinct consumption physics across formats, users, and channels. Product architecture, portion sizing, and thermal requirements vary sharply between commuter transit consumption and institutional school feeding programs.
Product Type:
Format selection hinges on consumption velocity and spillage tolerance during motion.
- Drinkable Yoghurt:Fluid viscosity optimized for direct-from-bottle consumption without utensils. Demand concentrates in United States and German commuter rail corridors where platform vending placement captures impulse selection during evening transit.
- Yoghurt Tubes:Squeeze-format semi-solid packaged in laminated foil laminates. Children represent the core buyer cohort; unsupervised consumption in Japanese and British school environments drives repeat purchase frequency through portion control and reduced mess.
- Yoghurt Smoothies:Fruit-puree blended formulations with higher suspended solids. Health enthusiasts in coastal United States markets favor these for meal-replacement occasions.
- Yoghurt Parfaits:Layered granola and fruit inclusions in transparent cup formats. Premium positioning in French and Italian convenience retail commands margin concentration through visual appetite appeal.
Volume sits with Drinkable Yoghurt; growth tilts toward Yoghurt Tubes.
End User:
Buyer physiology and purchase authority reshape formulation priorities and channel access.
- Adults:Satiety-seeking professionals prioritizing protein density and low glycemic load. German and Japanese urban corridors show highest per-capita trial rates for functional fortified variants.
- Children:Palate-calibrated sweetness levels with parental oversight on ingredient simplicity. USDA school nutrition program eligibility criteria in the United States create institutional volume anchors for compliant suppliers.
- Athletes:Recovery-oriented protein concentrations exceeding standard dairy bases. Post-gym consumption in United States metropolitan clusters favors bottle formats with electrolyte fortification.
- Health Enthusiasts:Probiotic colony-forming unit claims and organic certification premiums. EFSA health claim authorizations in European markets enable functional positioning that commands shelf-space premiums.
Children drive absolute unit volume; Athletes deliver steepest expansion trajectory through sports-channel distribution.
Flavor:
Flavor selection signals market maturity and local agricultural input availability.
- Strawberry:Universal palate acceptance with year-round concentrate supply stability. Dominates introductory trial purchases across all geographies.
- Blueberry:Antioxidant health halo supporting premium pricing in United States and Canadian markets. Pacific Northwest cultivation clusters provide regional supply proximity.
- Peach:Mediterranean and Southern European preference concentration. Italian and Spanish retail buyers favor for summer seasonal programming.
- Vanilla:Neutral base for protein fortification and mix-in customization. Institutional foodservice specifications in United States school channels default to this profile for batch consistency.
Strawberry anchors baseline production; Blueberry gains share fastest through functional health positioning.
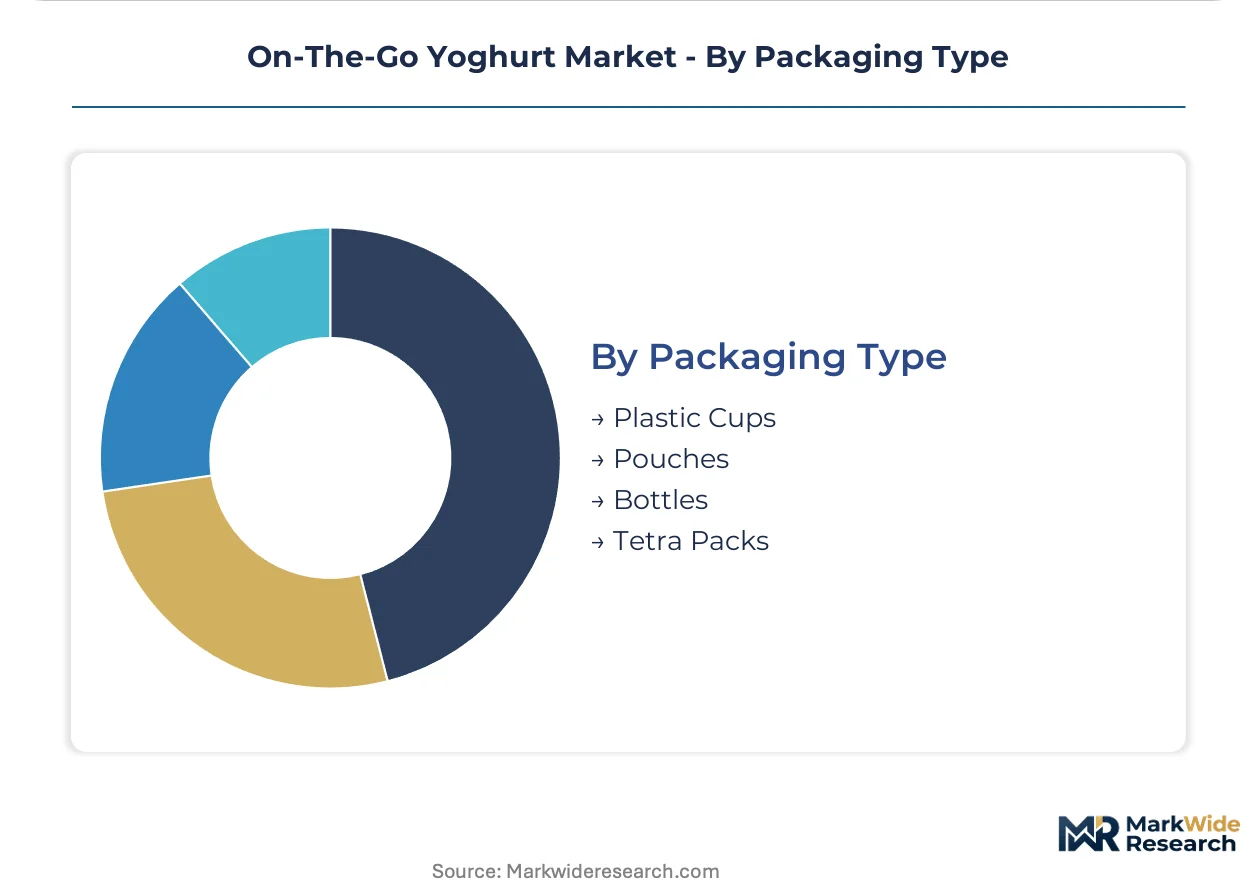
Packaging Type:
Material-engineering decisions determine cold-chain compliance duration and retail placement flexibility.
- Plastic Cups:Thermoformed polystyrene or PET with lidding film for spoonable formats. Standard for Yoghurt Parfaits requiring structural rigidity for granola layering.
- Pouches:Multilayer laminated films with spout fitments. Squeeze functionality reduces spillage in children's unsupervised consumption; fastest-growing format in Indian and Brazilian modern trade expansion.
- Bottles:HDPE or PET with tamper-evident closures. Vending machine compatibility and single-handed opening dominate United States and Japanese transit-hub placement.
- Tetra Packs:Aseptic carton formats with extended ambient shelf stability. Rural distribution in China and Southeast Asia bypasses refrigeration infrastructure constraints.
Bottles hold installed base; Pouches climb the fastest through child-targeted format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City anchors commuter-format demand through subway-platform vending placement and grab-and-go convenience density unmatched elsewhere. Transit-hub consumption moments concentrate in Manhattan, Brooklyn, and Queens corridors where drinkable bottles capture impulse selection during evening rush.
United States
Convenience-store penetration and school nutrition program eligibility drive institutional volume. The USDA oversees breakfast program compliance that shapes supplier qualification. Chicago and Los Angeles metropolitan clusters show parallel transit-hub vending expansion alongside New York.
Germany
Urban rail corridors in Berlin, Munich, and Hamburg create captive consumption for drinkable formats. The EU's F-Gas Regulation forces cold-chain operators toward CO2 transcritical refrigeration systems. Bavarian dairy processors adopt high-pressure processing lines to extend distribution radii without terminal heat treatment.
Japan
Evening transit consumption displaces snack-bar occasions among Tokyo and Osaka professionals. METI standards govern functional food labeling for probiotic claims. Kanto region convenience retailers deploy chilled placement at platform exits and building lobbies.
India
Modern trade expansion in Mumbai, Bangalore, and Delhi creates first-mover advantage for chilled single-serve formats. FSSAI live-culture disclosure requirements shape SKU development for multinational entrants. Tier-1 city cold-chain infrastructure penetration enables pouch-format growth among school-age children.
United Kingdom
Commuter rail networks in London and Manchester support drinkable yoghurt trial among urban professionals. EFSA health claim authorizations determine functional benefit communication permitted across member states. British school environments drive repeat purchase frequency for squeeze-format tubes through unsupervised consumption acceptance.
On-The-Go Yoghurt Market Competitive Landscape
Premium-margin players sit above commodity-margin players across protein fortification and probiotic certification tiers. The vendor base stratifies between Greek yoghurt heritage specialists, diversified dairy conglomerates, and plant-based challengers. Three archetypes dominate: functional formulation leaders leveraging live-culture efficacy claims, global scale operators optimizing manufacturing footprint across price tiers, and organic specialists capturing parental preference in children's segments. Competitive moves concentrate on aseptic filling technology licensing and cold-chain partnership consolidation.
Within the functional formulation tier, Chobani occupies a position exemplifying Greek yoghurt heritage translation into drinkable formats. Danone and Nestlé represent scale-driven archetypes spanning multiple price tiers and geographic markets. These three entities anchor the competitive structure through divergent strategic postures: heritage-based premium positioning, European organic and plant-based specialization, and global manufacturing footprint optimization.
| Leading Market Players |
|---|
| Chobani |
| Danone |
| Nestlé |
| Materne North America |
| Alpro UK |
| Origin Food Group |
| Yoplait (General Mills) |
| Müller |
| Sprout Organic Foods |
| Others |
Value Network & Pricing Analysis
USDA school nutrition program eligibility mandates for portable dairy proteins concentrate procurement authority among qualified suppliers, forcing contract manufacturers to absorb live-culture certification costs and compressing margin structures for non-compliant regional players.
Pricing Analysis
Live-culture efficacy claims anchor value-based pricing tiers across the on-the-go yoghurt category. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized probiotic formulations from commodity single-serve cups. Pricing pressure stems from plant-based oat and almond milk drinkables capturing trial budgets in coastal urban markets. Institutional foodservice buyers in United States school channels exhibit highest price sensitivity; health enthusiasts seeking organic certification show lowest.
Supply Chain Analysis
Dual-sourcing requirements for aseptic filling equipment and cold-chain logistics partners mandate multi-supplier qualification among tier-1 dairy processors. Milk powder and whey protein concentrate supply concentrates in New Zealand, the European Union, and the United States. Raw material dependencies include dairy solids, probiotic cultures, and multilayer laminated films. Single-source vulnerability in third-party refrigerated logistics creates bottleneck risk during peak summer demand. Distribution runs through national cold-chain providers and convenience retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's F-Gas Regulation functions as a cost-of-compliance moat, favoring manufacturers with capital reserves to retrofit refrigeration assets while marginalizing regional players dependent on aging hydrofluorocarbon systems.
For Market Incumbents: Extend cold-chain partnership consolidation to lock in capacity ahead of refrigerant transition deadlines. Acquire CO2 transcritical system capabilities to neutralize plant-based challengers. Secure aseptic filling technology licenses to stretch distribution radii without terminal heat treatment. For New Entrants and Emerging Players: Rural Indian school-age children represent an underserved buyer archetype with limited cold-chain penetration. Target tier-1 city modern trade expansion in Mumbai and Bangalore through pouch-format innovation. Pursue FSSAI live-culture disclosure compliance as the go-to-market anchor for multinational credibility. For Investors and Strategic Acquirers: The window for entry favors mid-tier dairy processors with installed high-pressure processing lines and regional brand recognition. Long-term viability hinges on backward integration into dairy solids supply and captive aseptic filling capacity. Watch EFSA health claim authorization timelines as the inflection signal for functional premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Technology Licensing | Enables 45-60 day shelf lives without cold-chain dependency, opening rural channels. |
| Cold-Chain Partnership Consolidation | Secures capacity with EPA Section 608 certified technicians amid technician shortage. |
| Refrigeration Asset Retrofit | EU F-Gas Regulation compliance creates barrier-to-entry moat for compliant operators. |
| Smart Vending Convergence | Cashless payment and telemetry integration enable transit-hub placement without retail labor. |
| Plant-Based Line Extension | Captures trial budgets from oat and almond milk drinkables in urban coastal markets. |
Research Methodology
Independent corroboration across brand managers at multinational dairy conglomerates, category buyers at United States convenience retail chains, and supply planners at cold-chain logistics providers underwrites the qualitative findings. Secondary validation draws from FDA live-culture labeling standards, EFSA health claim authorization databases, USDA school nutrition program specifications, and Nielsen retail audit data. Bottom-up volume modeling triangulates against top-down macroeconomic anchors.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation dimensions include product format, end-user physiology, flavor profile, and packaging material engineering. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points. Forecast inputs incorporate F-Gas Regulation phase-down timelines and extended-shelf-life technology adoption curves.
Revisions become necessary when EFSA probiotic claim authorizations accelerate, USDA school nutrition program criteria shift, or refrigeration technician pipeline constraints deepen. Forecasts reflect documented assumptions on cold-chain infrastructure penetration rates. A model refresh is warranted upon material change in aseptic filling technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Dairy-Free Evaporated Milk Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Dairy-Free Ice Creams Market