
 Japan Dairy Alternatives Market | 2026-2036
Japan Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Dairy Alternatives Market Insights
Asset-light contract manufacturing and third-party leasing of UHT processing lines is narrowing the capital barrier for new entrants in Japan's dairy alternatives sector. Kikkoman Corporation leverages its century-old soy processing infrastructure to dominate liquid soy milk supply. MARUSAN-AI CO., LTD. anchors the powdered segment through dedicated health food channels. SAPPORO HOLDINGS LTD. competes by extending its beverage distribution network into ready-to-drink oat and almond formats.
Japan dairy alternatives comprise plant-derived beverages and ingredients formulated to replicate the functional properties—emulsification, foaming, nutritional density—of conventional dairy, typically achieving protein equivalence through soy isolate or oat base concentrations of 8-12%. The primary commercial purpose spans direct consumption, barista applications, and industrial food manufacturing where thermal stability and neutral flavor profiles prove critical. Soy milk retains the largest volume position across retail and foodservice channels, though oat milk claims the fastest trajectory among cafés seeking foam-optimized formulations. Powdered products command margin premiums in health food stores where shelf stability and shipping economics favor concentrated formats over liquid cartons.
METI's Food Industry Vision and the Consumer Affairs Agency's labeling standards for plant-based claims shape product development timelines and marketing permissible language in Japan. JIS standards for food machinery and MHLW food additive regulations govern processing equipment specifications and permitted fortifications such as calcium and vitamin D. PMDA oversight of functional food claims further constrains how brands position digestive or cardiovascular benefits. Stakeholders must monitor evolving enforcement on "milk" terminology restrictions and the pace of domestic oat cultivation subsidies that could redraw raw material sourcing economics.
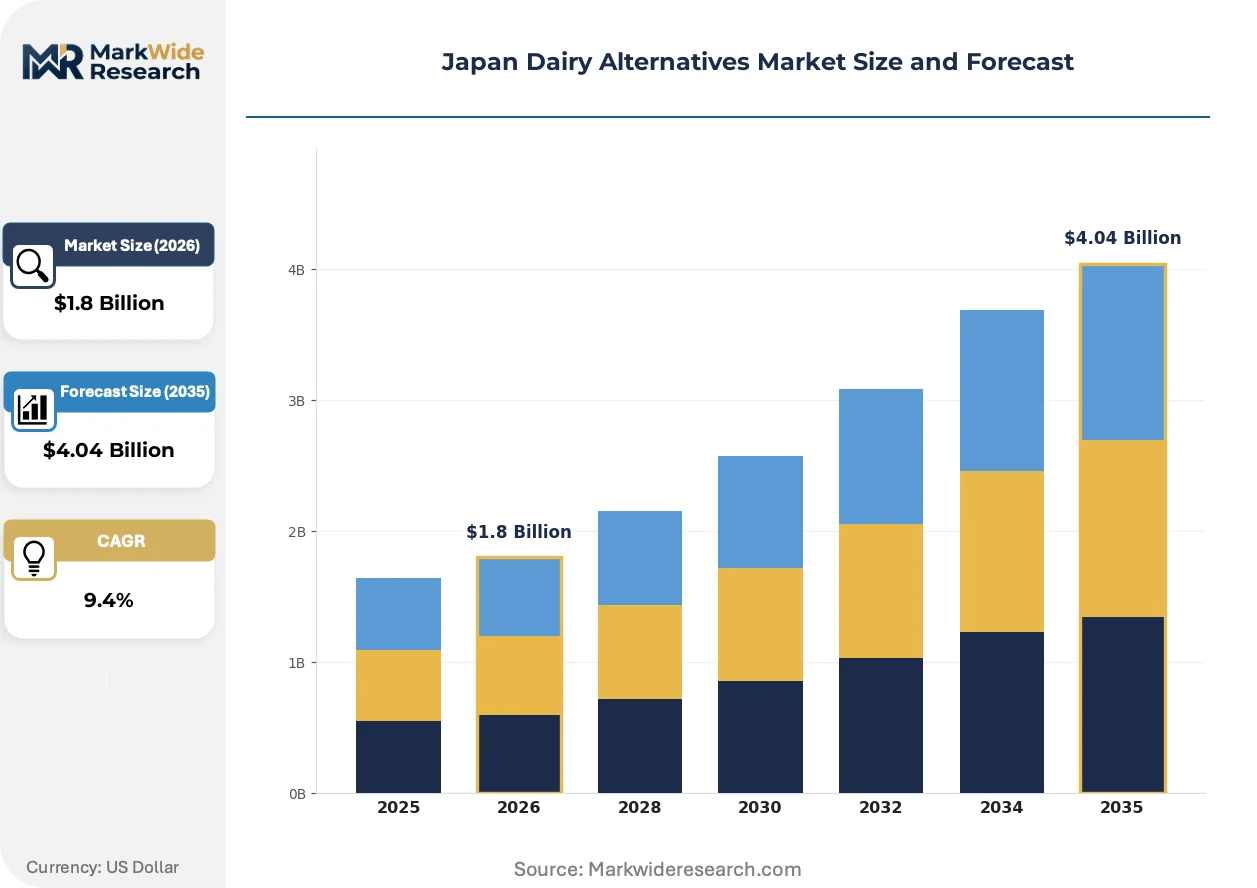
Market Dynamics
Japan's dairy alternatives sector is restructuring around METI's domestic oat cultivation subsidies and the Consumer Affairs Agency's tightening enforcement on "milk" terminology claims, which together are compressing import dependency and forcing label reformulation cycles.
Growth Catalysts
- Domestic oat cultivation incentives:METI's subsidy framework for northern Hokkaido farmers is accelerating local supply chain formation and reducing yen-denominated raw material exposure.
- Foodservice foam-performance specifications:Tokyo's specialty café corridor demands barista-grade oat formulations with stable microfoam structures, pulling investment toward enzymatic processing upgrades.
- JIS food machinery standards harmonization:Revised equipment certification timelines are streamlining UHT line deployment for contract manufacturers entering the segment.
Market Restraints
- Import concentration in oat base supply:Swedish and Finnish oat processors control premium raw material flows, exposing Japanese formulators to Baltic shipping disruptions and euro volatility.
- Soy isolate price anchoring:Global oilseed crush economics tie domestic soy milk margins to Argentine and Brazilian commodity swings beyond local policy control.
- PMDA functional claim constraints:The pharmaceutical regulator's narrow interpretation of digestive health evidence blocks protein positioning that European competitors exploit freely.
Strategic Opportunities
- Osaka-Kobe manufacturing belt expansion:Idle beverage capacity in Hyogo Prefecture offers asset-light entry points for oat milk production without greenfield capex.
- Convenience store chilled set innovation:Lawson and 7-Eleven Japan are testing dedicated plant-based dairy bays, creating shelf-space leverage unavailable in traditional retail.
- Cross-category fermentation convergence:Koji-cultured oat bases combining traditional brewing science with modern dairy replication open distinct positioning against Western imports.
Industry Challenges
- Enzymatic processing talent scarcity:Japanese universities produce limited specialists in cereal lipid modification, forcing employers to recruit from European food technology programs.
- Dual-label compliance complexity:Simultaneous satisfaction of JIS machinery standards and MHLW additive regulations extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Dairy Alternatives Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk End User: Residential Consumers, Food Industry, Cafés, Restaurants Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Direct Sales Form: Liquid, Powdered, Concentrate, Ready-to-Drink |
| Companies Covered | Kikkoman Corporation, MARUSAN-AI CO., LTD., SAPPORO HOLDINGS LTD., Otsuka Holdings Co., Ltd., Yakult Honsha Co., Ltd., Alpro, Kikkoman Soy Foods Co. Ltd., Tsukuba Dairy Products Co. Ltd., Asahi Group Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Dairy Alternatives Market Trends and Innovations
Formulation science and regulatory interpretation are diverging from Western templates as Japanese developers prioritize umami-compatible flavor profiles and domestic ingredient sourcing over direct milk replication.
Enzymatic lipid hydrolysis is migrating from laboratory-scale trials to industrial oat base production. Specialty café chains in Tokyo's Shibuya and Shinjuku wards specify hydrolyzed oat formulations for latte art stability. This enzymatic shift is compressing the performance gap between imported European bases and domestically processed alternatives.
METI's Food Industry Vision implementation guidelines now require explicit carbon footprint disclosures for plant-based products sold through government procurement channels. Food manufacturers serving school lunch and hospital nutrition contracts must submit scope-three emissions data. Institutional buyers in Osaka Prefecture are prioritizing domestic-processed soy milk to satisfy these disclosure thresholds.
Foodservice procurement is consolidating around specification-grade supply contracts rather than spot purchasing. Major hotel chains and airline caterers now demand batch-level protein consistency certificates. This certification-driven procurement is most visible in Tokyo's metropolitan foodservice corridor, where contract manufacturers with in-house analytics laboratories capture preferential vendor status.
Japan Dairy Alternatives Market Segmentation
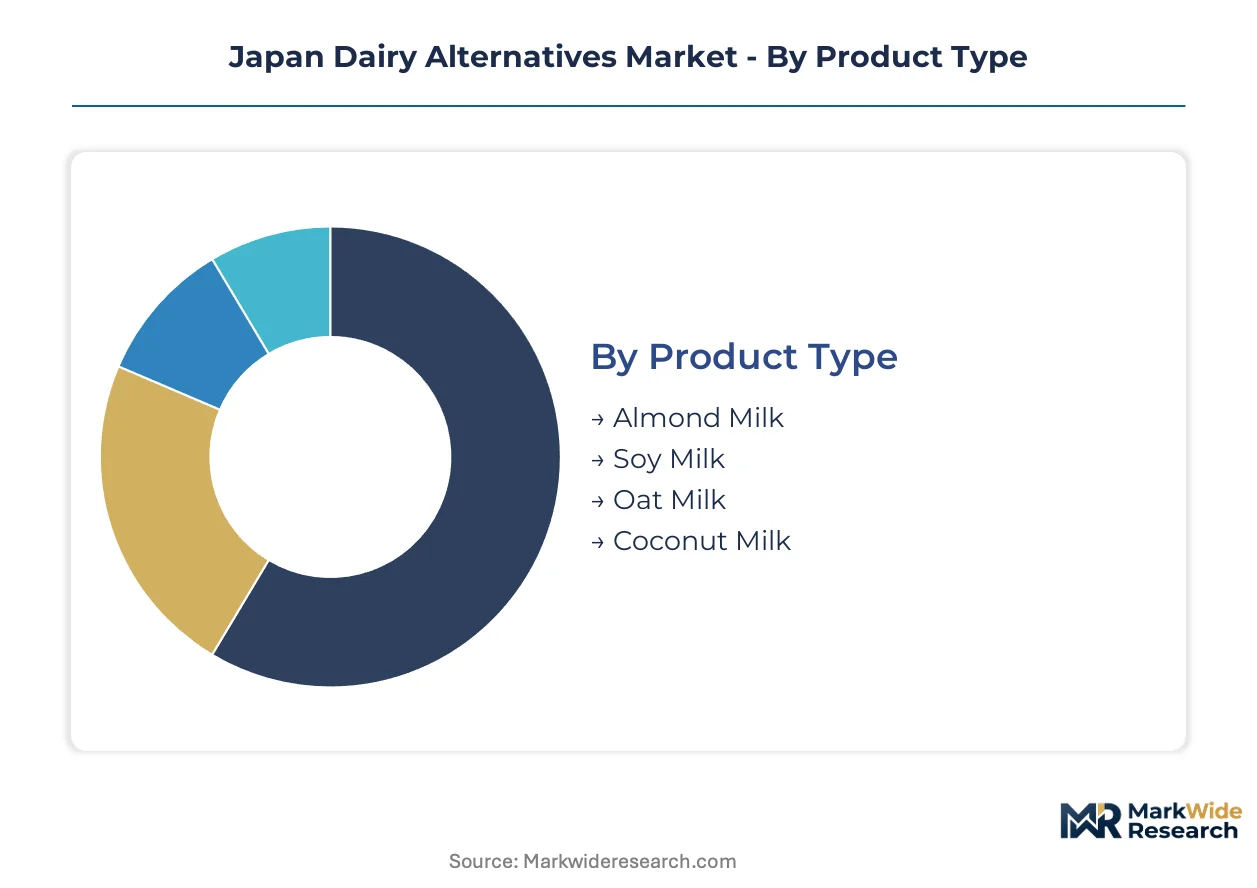
Japan's dairy alternatives sector fragments across four intersecting dimensions that determine formulation priorities, channel economics, and regulatory exposure. Each segmentation axis carries distinct margin profiles and capital requirements that shape competitive positioning.
Product Type:
Use-case spectrum spans direct consumption, barista applications, and industrial food manufacturing where thermal stability and foam performance dictate procurement decisions.
- Soy Milk:Formulated from soy isolate achieving protein equivalence to conventional dairy through 8-12% concentration. Tokyo's metropolitan foodservice corridor and Osaka's manufacturing belt anchor demand, with METI's domestic processing incentives reinforcing local supply chain formation.
- Oat Milk:Enzymatically hydrolyzed bases deliver stable microfoam structures critical for latte art specifications. Specialty cafés in Shibuya and Shinjuku wards drive specification-grade procurement, pulling investment toward enzymatic processing upgrades.
- Almond Milk:Lower protein content positions this segment toward health-conscious residential consumers seeking neutral flavor profiles for direct consumption.
- Coconut Milk:Higher fat concentration suits Southeast Asian cuisine applications and dessert manufacturing in Japan's food industry channel.
The dominant share belongs to soy milk, while oat milk is closing the gap fastest.
End User:
Volume concentration maps to Japan's urban consumption corridors and institutional procurement hubs.
- Residential Consumers:Supermarket and online retail channels serve household demand for daily consumption and nutritional fortification.
- Food Industry:Industrial manufacturers in Osaka's manufacturing belt require batch-level protein consistency certificates for bakery and confectionery applications.
- Cafés:Tokyo's specialty café corridor demands barista-grade formulations with certified foam stability, driving enzymatic processing adoption.
- Restaurants:Hotel chains and airline caterers consolidate procurement around specification-grade supply contracts with in-house analytics requirements.
Food industry buyers command the largest procurement volumes, though café channel specifications are expanding most quickly.
Distribution Channel:
Channel economics reflect cold chain infrastructure maturity and shelf-space allocation power across Japan's retail landscape.
- Supermarkets:Major chains dominate liquid carton volume with dedicated chilled dairy alternative bays.
- Online Retail:Powdered and concentrate formats leverage shipping economics and subscription models for residential penetration.
- Health Food Stores:Premium positioning for fortified and organic variants with margin advantages on concentrated formats.
- Direct Sales:Institutional contracts for school lunch and hospital nutrition programs requiring METI-mandated carbon footprint disclosures.
Supermarkets retain volume leadership, while online retail is gaining share fastest through powdered product subscriptions.
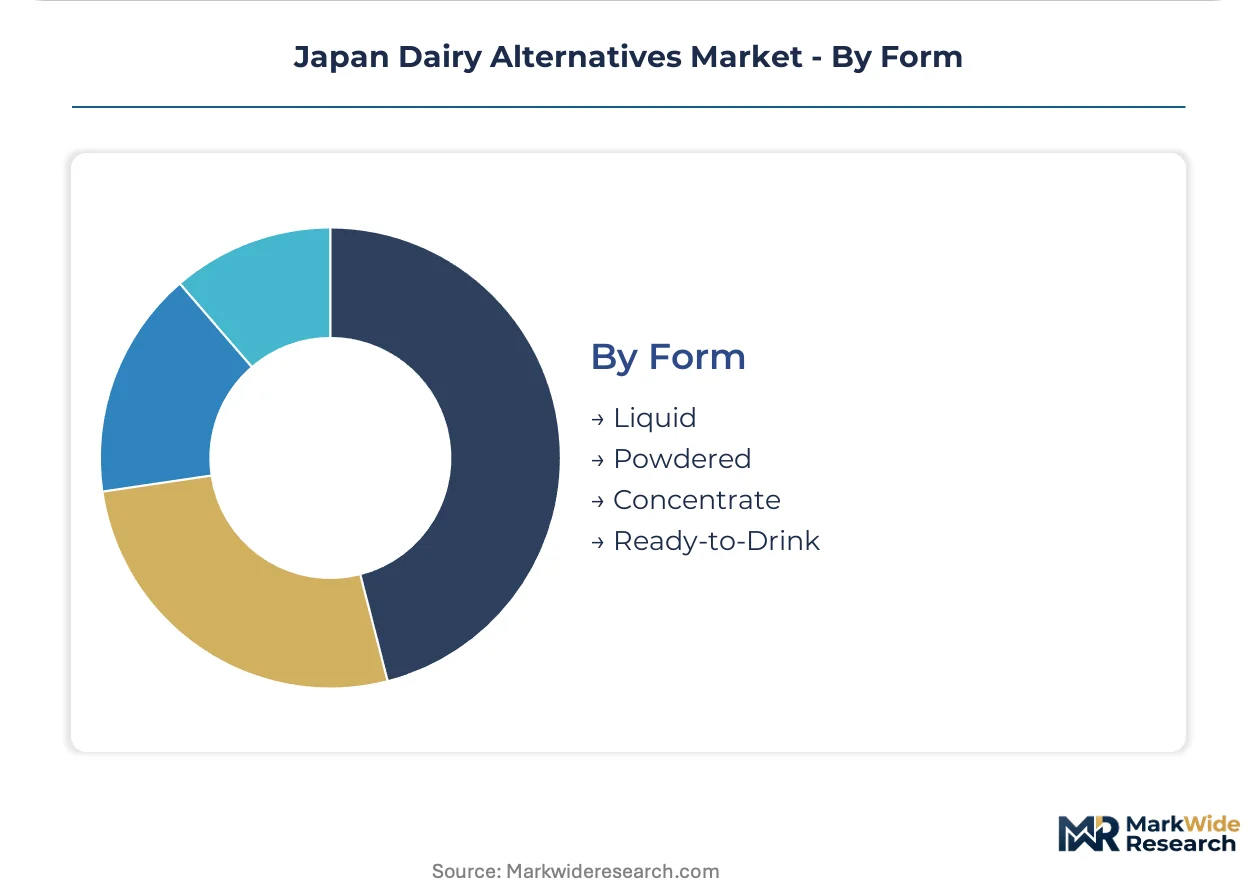
Form:
Form factor selection trades shelf stability, shipping economics, and end-use reconstitution requirements.
- Liquid:UHT-processed cartons serve retail and foodservice channels requiring immediate consumption readiness.
- Powdered:Concentrated formats command margin premiums in health food stores where shelf stability favors long-distance distribution.
- Concentrate:Industrial food manufacturers in Osaka Prefecture source bulk concentrate for in-house formulation and cost optimization.
- Ready-to-Drink:Convenience store chilled sets in Lawson and 7-Eleven Japan create shelf-space leverage for on-the-go consumption.
Liquid formats hold the dominant position, though powdered alternatives are climbing the fastest through health food channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty café chains and institutional foodservice buyers concentrate procurement decisions in Japan's major metropolitan corridors, with METI's domestic processing incentives redirecting supply chain investment toward northern cultivation zones and western manufacturing belts.
Kanto/Tokyo
Tokyo's Shibuya and Shinjuku specialty café corridors drive specification-grade oat milk procurement with certified foam stability requirements. METI's Food Industry Vision implementation guidelines mandate carbon footprint disclosures for institutional contracts. Contract manufacturers with in-house analytics laboratories capture preferential vendor status from major hotel chains and airline caterers.
Kansai/Osaka
Osaka's manufacturing belt anchors industrial food manufacturing demand where batch-level protein consistency certificates prove critical for bakery and confectionery applications. The Consumer Affairs Agency's tightening enforcement on "milk" terminology claims forces label reformulation cycles. Idle beverage capacity in Hyogo Prefecture offers asset-light entry points for oat milk production.
Chubu/Nagoya
Nagoya's food processing machinery cluster supplies JIS-certified UHT processing equipment to contract manufacturers entering the dairy alternatives segment. Revised equipment certification timelines streamline deployment. Regional formulators serve institutional buyers in Aichi Prefecture's hospital nutrition and school lunch programs.
Hokkaido
Hokkaido's northern agricultural belt hosts METI's subsidy framework for domestic oat cultivation, accelerating local supply chain formation. Farmers reduce yen-denominated raw material exposure through subsidized crop transitions. Primary processing facilities in Sapporo and Asahikawa handle initial oat base preparation before shipment to western formulation plants.
Kyushu
Fukuoka's metropolitan foodservice corridor replicates Tokyo's barista-grade specification demands at smaller scale. Regional distributors leverage proximity to Southeast Asian shipping routes for coconut milk ingredient sourcing. Local health food retail chains test powdered soy milk subscription models for residential penetration.
Japan Dairy Alternatives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Japan's dairy alternatives sector, producing a tiered structure where beverage distribution networks clash with dedicated soy processing heritage. The market fragments across three strategic archetypes: legacy soy sauce brewers leveraging fermentation infrastructure, diversified beverage conglomerates extending distribution reach, and health food specialists commanding premium shelf positions. Dominant competitive moves include enzymatic processing capability acquisition and specification-grade supply contract consolidation with institutional buyers.
Among legacy soy processing specialists, Kikkoman Corporation and MARUSAN-AI CO., LTD. exemplify divergent positioning strategies within the domestic supply base. Kikkoman leverages century-old infrastructure to anchor liquid soy milk supply, while MARUSAN-AI occupies the powdered segment through dedicated health food channels. SAPPORO HOLDINGS LTD. represents the beverage conglomerate archetype, competing through distribution network extension into ready-to-drink formats.
| Leading Market Players |
|---|
| Kikkoman Corporation |
| MARUSAN-AI CO., LTD. |
| SAPPORO HOLDINGS LTD. |
| Otsuka Holdings Co., Ltd. |
| Yakult Honsha Co., Ltd. |
| Alpro |
| Kikkoman Soy Foods Co. Ltd. |
| Tsukuba Dairy Products Co. Ltd. |
| Asahi Group Holdings |
| Others |
Pricing and Supply Chain Analysis
Import concentration in Swedish and Finnish oat base supply determines both pricing tier spreads and supply chain shape across Japan's dairy alternatives sector. Yen-euro volatility and Baltic shipping disruptions compress margins for formulators lacking long-term offtake agreements, while METI's domestic cultivation subsidies redraw raw material economics for subsidized competitors.
Pricing Analysis
Cost-plus contracts with Argentine and Brazilian soy commodity indexation dominate procurement for soy milk formulators. Three-tier pricing structure across premium, standard, and economy levels separates health food store fortified variants from supermarket private-label cartons and industrial concentrate bulk sales. Pricing pressure stems from global oilseed crush volatility and euro-denominated oat base imports. Food industry buyers in Osaka's manufacturing belt exhibit highest price sensitivity due to volume scale and specification tolerance, while Tokyo's specialty café corridor accepts foam-performance premiums.
Supply Chain Analysis
Contract manufacturing concentration rests with idle beverage processors in Hyogo Prefecture and dedicated health food co-packers serving MARUSAN-AI's powdered segment. Raw material flows draw from Hokkaido's subsidized oat cultivation belt, Swedish and Finnish premium oat processors, and Argentine soy crushing facilities. Single-source vulnerability concentrates in Baltic Sea shipping lanes for enzymatically hydrolyzed oat bases. Distribution runs through chilled retail sets at Lawson and 7-Eleven Japan, institutional procurement channels for hospital nutrition contracts, and health food store networks for powdered subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
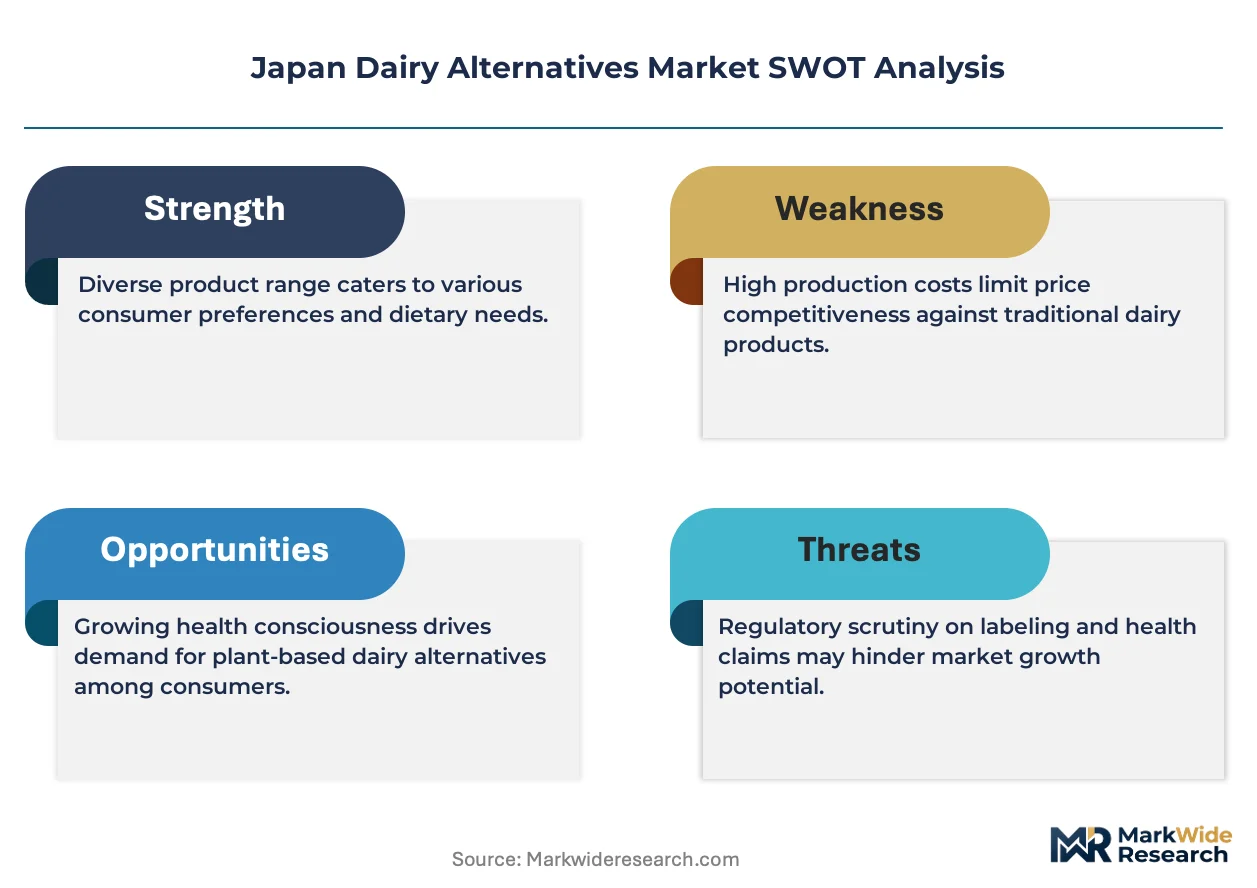
Japan's dairy alternatives sector presents a defensive-moat story anchored in regulatory entrenchment. METI's domestic processing incentives and PMDA's functional claim constraints create switching costs that favor established formulators with compliance infrastructure.
For Market Incumbents: Build specification-grade supply contract moats by consolidating batch-level protein consistency certification capabilities. Secure enzymatic processing talent through European recruitment pipelines and anchor UHT line capacity in Osaka-Kobe manufacturing belt idle facilities. Threat substitution from koji-cultured oat bases demands accelerated R&D investment in traditional fermentation science applications.
For New Entrants and Emerging Players: Kyushu's underpenetrated health food subscription channel offers white-space entry with lower competitive density than Tokyo's café corridor. Target Fukuoka's metropolitan foodservice corridor for barista-grade specification contracts at reduced customer acquisition cost. Deploy asset-light contract manufacturing through third-party UHT line leasing to bypass greenfield capital requirements.
For Investors and Strategic Acquirers: PMDA's evolving enforcement on "milk" terminology claims reshapes the acquisition landscape toward compliance-capable formulators with in-house regulatory affairs infrastructure. Long-term viability favors targets with domestic oat supply chain integration and institutional procurement relationships. Monitor METI subsidy expansion announcements as inflection indicators for raw material sourcing economics shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Oat Cultivation Integration | METI subsidies reduce yen-denominated raw material exposure for Hokkaido-based processors. |
| Enzymatic Processing Capability Acquisition | European food technology recruitment closes foam-performance gaps against Swedish and Finnish imports. |
| Specification-Grade Supply Contract Consolidation | Batch-level protein consistency certificates capture preferential vendor status from Tokyo hotel chains. |
| Koji-Cultured Oat Base Development | Traditional brewing science applications create distinct positioning against Western enzymatic formulations. |
| Convenience Store Chilled Set Expansion | Lawson and 7-Eleven Japan dedicated plant-based bays unlock shelf-space leverage unavailable in traditional retail. |
Research Methodology
Desk research of METI policy documentation, JIS machinery standards filings, and MHLW food additive regulations preceded structured interviews with plant protein R&D directors, contract manufacturing operations managers, and institutional procurement officers at hospital nutrition programs. Secondary validation drew from customs trade data for oat and soy isolate imports, Consumer Affairs Agency labeling enforcement records, and PMDA functional food claim decisions. Primary fieldwork with Tokyo specialty café chain buyers and Osaka industrial food manufacturers informed demand-side segmentation. Bottom-up volume modeling triangulated against top-down market sizing from channel shipment data.
Assumptions held METI's domestic oat cultivation subsidy framework and PMDA's narrow digestive health evidence interpretation fixed across the projection horizon. Segmentation dimensions modeled include product type, end user category, distribution channel, and form factor. CAGRs derived from weighted average of historical volume trajectories and policy-driven inflection scenarios. Industry-specific forecast inputs incorporated enzymatic processing adoption curves and carbon footprint disclosure mandate compliance timelines for institutional contracts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by European oat base exporters or domestic koji fermentation specialists would shift outcomes. Quarterly review of METI subsidy allocation announcements, Baltic shipping lane disruption indices, and PMDA functional claim enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
North America Almond Milk Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Germany Dairy Alternatives Market