
 Dry Cream Substitute Market | 2026-2036
Dry Cream Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Cream Substitute Market Foresight
Enzymatic interesterification of plant lipids is narrowing the functional gap between dairy cream and vegetable-based substitutes. Cargill leverages its integrated oilseed processing network to secure consistent feedstock supply for cream alternative production. Puratos anchors its competitive position through specialized fermentation-derived lipid technologies tailored to European bakery applications. ADM competes across multiple geographies with in-house enzymatic modification capabilities that reduce reliance on external ingredient suppliers.
Dry cream substitutes are spray-dried or roller-dried emulsions composed of hydrogenated or interesterified vegetable oils, carbohydrate carriers, and emulsifying salts, engineered to replicate the mouthfeel, whipping capacity, and thermal stability of dairy cream in food manufacturing. Non-dairy creamers occupy the largest volume share within product type segmentation, driven by instant beverage and vending channel demand, while coconut cream variants command premium positioning in clean-label bakery and confectionery formulations. Application segmentation shows beverages as the mature baseline category, with sauces and confectionery representing faster-growing margin pools where fat functionality requirements are more technically demanding.
FDA standards for dairy alternative labeling, EFSA novel food assessments for emerging plant lipid sources, and EU REACH compliance for emulsifier chemistries collectively shape product development timelines and market access conditions for dry cream substitute manufacturers. Food service operators and industrial buyers must evaluate supplier capabilities against evolving regulatory frameworks while monitoring enzymatic processing innovations that could reset cost-performance benchmarks across substitute categories.
Market Dynamics
Enzymatic lipid modification is compressing the functional performance gap between dairy cream and vegetable-based substitutes, forcing incumbent suppliers to accelerate R&D timelines or cede share to biotechnology-enabled entrants.
Growth Catalysts
- Clean-label bakery demand:Industrial bakers in Germany and France are reformulating recipes to eliminate dairy allergens, creating pull-through for coconut and oat-based cream powders that carry shorter ingredient lists.
- FDA labeling clarity:Updated standards for dairy alternative nomenclature reduce consumer confusion and enable clearer shelf positioning for non-dairy creamers in US retail channels.
- EFSA novel food pathways:Streamlined safety assessments for emerging plant lipid sources accelerate time-to-market for fermented and algal-derived fat technologies.
Market Restraints
- Palm oil price volatility:Hydrogenated palm kernel oil remains the dominant feedstock for economy-grade substitutes, exposing margins to Malaysian and Indonesian supply disruptions.
- Supply concentration in Southeast Asia:Over 60% of interesterified lipid feedstock originates from a narrow corridor of Malaysian refiners, creating single-source vulnerability for European manufacturers.
- Whipping stability ceiling:Current enzymatic modification cannot yet replicate the overrun and foam structure of high-fat dairy cream in artisan confectionery applications.
Strategic Opportunities
- India industrial bakery expansion:FSSAI harmonization with Codex standards opens formulation pathways for multinational suppliers to serve organized retail bakery chains in Mumbai and Bangalore.
- Precision fermentation lipids:Convergence of synthetic biology and enzymatic processing enables custom-tailored fat profiles that outperform commodity vegetable oils on melting point and oxidative stability.
- Direct-to-foodservice distribution:Bypassing traditional ingredient distributors, manufacturers are building captive sales forces to serve coffee chain operators and contract caterers with just-in-time replenishment.
Industry Challenges
- Enzyme engineering talent scarcity:Formulation chemists with expertise in lipase-catalyzed interesterification command premium compensation, constraining mid-tier manufacturers' R&D bandwidth.
- EU REACH emulsifier re-registration:Sodium stearoyl lactylate and other core emulsifying salts face extended toxicological review timelines, delaying product reformulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Cream Substitute Market |
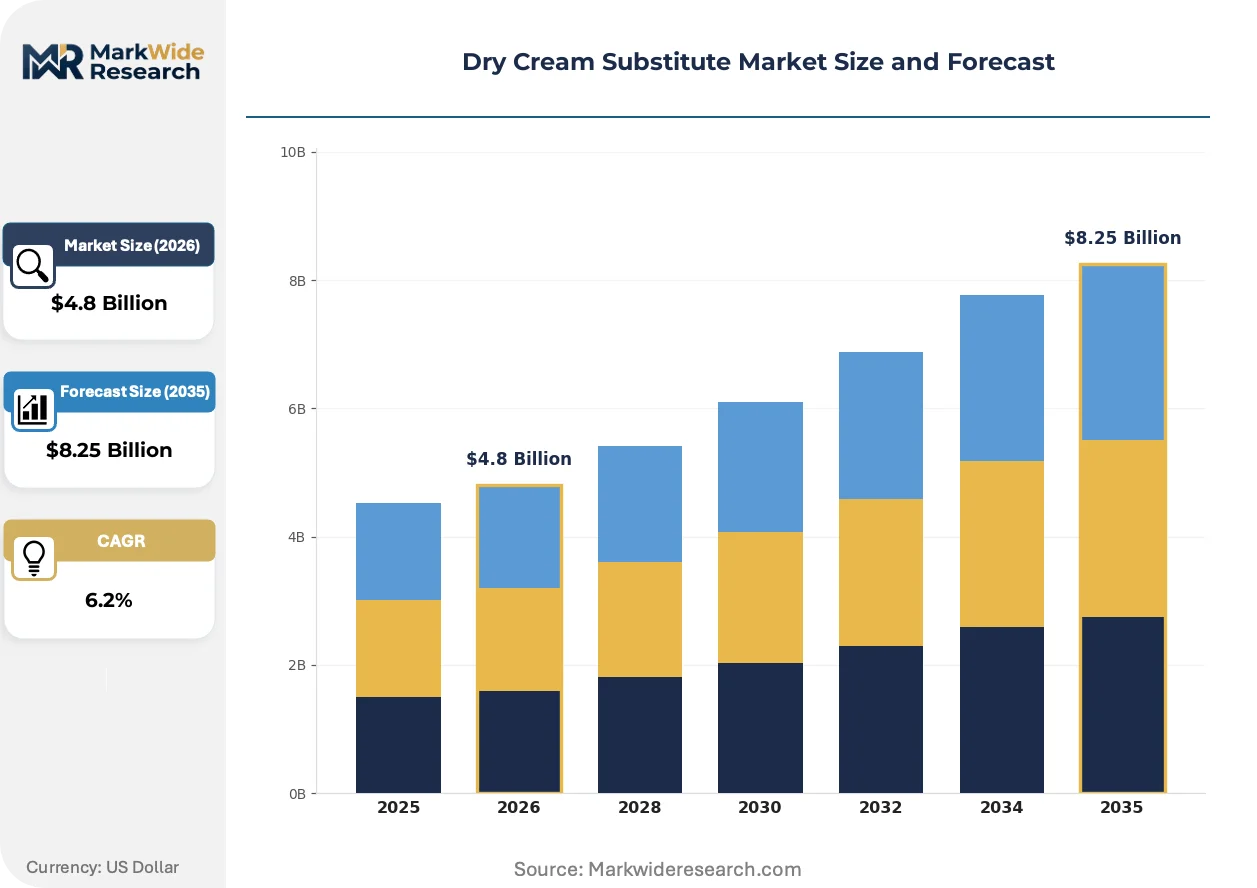
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Dairy Creamers, Milk Powder, Coconut Cream, Soy Cream Application: Beverages, Bakery Products, Confectionery, Sauces End User: Food Service, Retail Consumers, Manufacturers, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Rich's Products, Monarch Foods, Puratos, Barry Callebaut, Cargill, ADM, Ingredion, Tate & Lyle, SternLife, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Cream Substitute Market Shifts & Advancements
Biotechnology-enabled fat synthesis and regulatory pressure on carbon-intensive processing are converging to redefine how cream substitutes achieve functional parity with dairy. These forces are compressing development cycles and redrawing competitive boundaries.
Precision fermentation-derived lipids are hybridizing with conventional plant oil processing, enabling manufacturers to engineer specific fatty acid chain lengths and melting behaviors previously unattainable through agricultural sourcing alone. Specialty confectionery producers in Belgium and Switzerland are piloting these ingredients for ganache and praline fillings. This convergence is hybridizing the traditional divide between commodity vegetable oils and high-value dairy fats, forcing price realignment across premium substitute tiers.
EU F-Gas Regulation phase-down schedules are pressuring spray-drying operations to abandon hydrofluorocarbon-based refrigeration, accelerating capital deployment in ammonia and CO2-based drying systems. Industrial cream powder facilities in the Netherlands and Denmark face retrofit deadlines that compress project timelines. Bakery ingredient divisions with captive drying capacity are securing competitive advantage through early compliance, while toll processors risk capacity constraints.
Foodservice operators are consolidating supplier relationships around full-line dairy alternative portfolios, displacing single-category vendors who cannot bundle creamers with milk and cheese substitutes. Coffee chain procurement teams in Italy and Spain now mandate integrated plant-based ingredient sourcing. This concentration is most visible in Southern European markets where vending and automated beverage equipment penetration drives volume scale requirements.
Dry Cream Substitute Market Segmentation
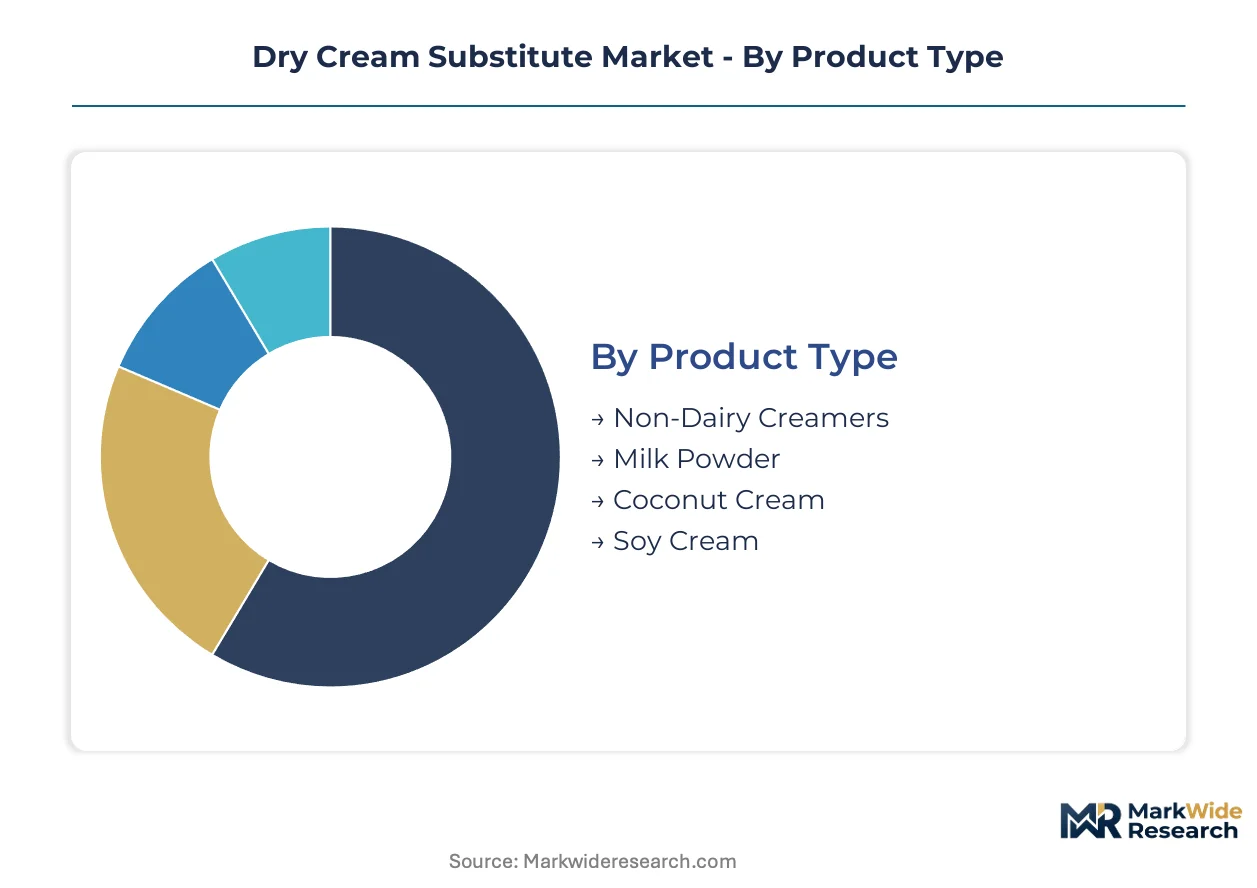
Segmentation in dry cream substitutes reveals how formulation requirements diverge across temperature stability, whipping performance, and clean-label positioning. Manufacturers configure production lines around these splits to capture margin pools in beverage vending versus artisan bakery channels.
Product Type:
After-sales formulation support intensity varies sharply across product types, with industrial buyers demanding ongoing technical assistance for whipping stability optimization and emulsion troubleshooting.
- Non-Dairy Creamers:Spray-dried emulsions of hydrogenated vegetable oils, glucose syrup solids, and sodium caseinate engineered for instant solubility in hot beverages. Coffee chain procurement teams in Italy and Spain concentrate volume here, driven by vending equipment compatibility requirements and bulk dispensing economics.
- Coconut Cream:Dehydrated coconut milk powders with 60-70% fat content, prized for clean-label positioning and dairy-allergen avoidance. Industrial bakers in Germany and France are scaling procurement of this segment, pulled by reformulation mandates for shorter ingredient declarations and EU allergen labeling compliance.
- Milk Powder:Standardized dairy-derived powders with defined protein and fat specifications for reconstitution applications. Food manufacturers in Belgium specify this grade for consistent hydration performance in sauce applications.
- Soy Cream:Defatted soy flour and lecithin-based emulsions offering cost-competitive alternatives for economy-tier bakery formulations. Procurement teams at contract caterers in the Netherlands evaluate this segment for institutional baking programs.
Non-Dairy Creamers holds the largest share; momentum sits with Coconut Cream.
Application:
Cost tier stratification separates commodity beverage applications from premium confectionery segments where fat functionality commands price premiums.
- Beverages:The mature baseline category encompassing instant coffee, tea, and vending machine formulations. Volume concentrates in automated dispensing channels where powder flowability and rapid dissolution are non-negotiable specifications.
- Confectionery:Ganache, praline, and filling applications demanding precise melting profiles and oxidative stability. Specialty producers in Switzerland and Belgium are piloting precision fermentation-derived lipids here, expanding most quickly as enzymatic modification narrows the performance gap with dairy cream.
- Bakery Products:Cake, pastry, and laminated dough applications requiring emulsion stability through freeze-thaw cycles. Industrial bakeries in Mumbai and Bangalore are scaling organized retail supply chains for this segment following FSSAI harmonization with Codex standards.
- Sauces:Cream-based soup and ready-meal applications where thermal stability prevents fat separation during retort processing. Food manufacturers in Denmark specify high-performance emulsifier systems for this segment.
Beverages anchors volume scale; Confectionery captures the steepest expansion trajectory.
End User:
Customer type determines packaging configuration, with food service operators demanding bulk tote formats and retail channels requiring single-serve sachets.
- Food Service:Coffee chains, contract caterers, and institutional kitchens purchasing 10-25kg bulk formats with just-in-time replenishment requirements. Direct distribution models are displacing traditional ingredient distributors for this segment.
- Manufacturers:Industrial bakeries, confectionery producers, and sauce compounders integrating cream powders into intermediate formulations. Procurement teams here evaluate supplier capabilities against EFSA novel food assessments and EU REACH emulsifier compliance.
- Retail Consumers:Household purchasers of 200-500g retail formats for home baking and beverage preparation. Shelf positioning clarity improved following FDA updated labeling requirements for dairy alternatives.
- Catering Services:Event and hospitality operators requiring portion-controlled formats with extended ambient storage stability. Volume clusters in Southern European markets where automated beverage penetration drives equipment-specific procurement.
Manufacturers represents the largest addressable base; Food Service is climbing the fastest on direct distribution adoption.
Distribution Channel:
Supply concentration in Southeast Asian lipid feedstock sources shapes channel economics, with wholesale distributors managing currency exposure and inventory risk for European manufacturers.
- Wholesale:Ingredient distributors serving industrial buyers with consolidated procurement of emulsifiers, oils, and cream powders. Over 60% of interesterified lipid feedstock flows through Malaysian refiners into this channel, creating single-source vulnerability.
- Online Retail:Direct-to-manufacturer platforms and B2B marketplaces enabling small-batch procurement for R&D and trial formulations. Specialty confectionery producers in Belgium leverage this channel for precision fermentation lipid samples.
- Supermarkets:Mass retail distribution for consumer-format cream powders and non-dairy creamers. Shelf positioning benefits from FDA labeling clarity reducing consumer confusion.
- Specialty Stores:Gourmet and professional kitchen supply channels targeting artisan bakers and premium foodservice operators. Clean-label coconut cream variants command premium positioning here.
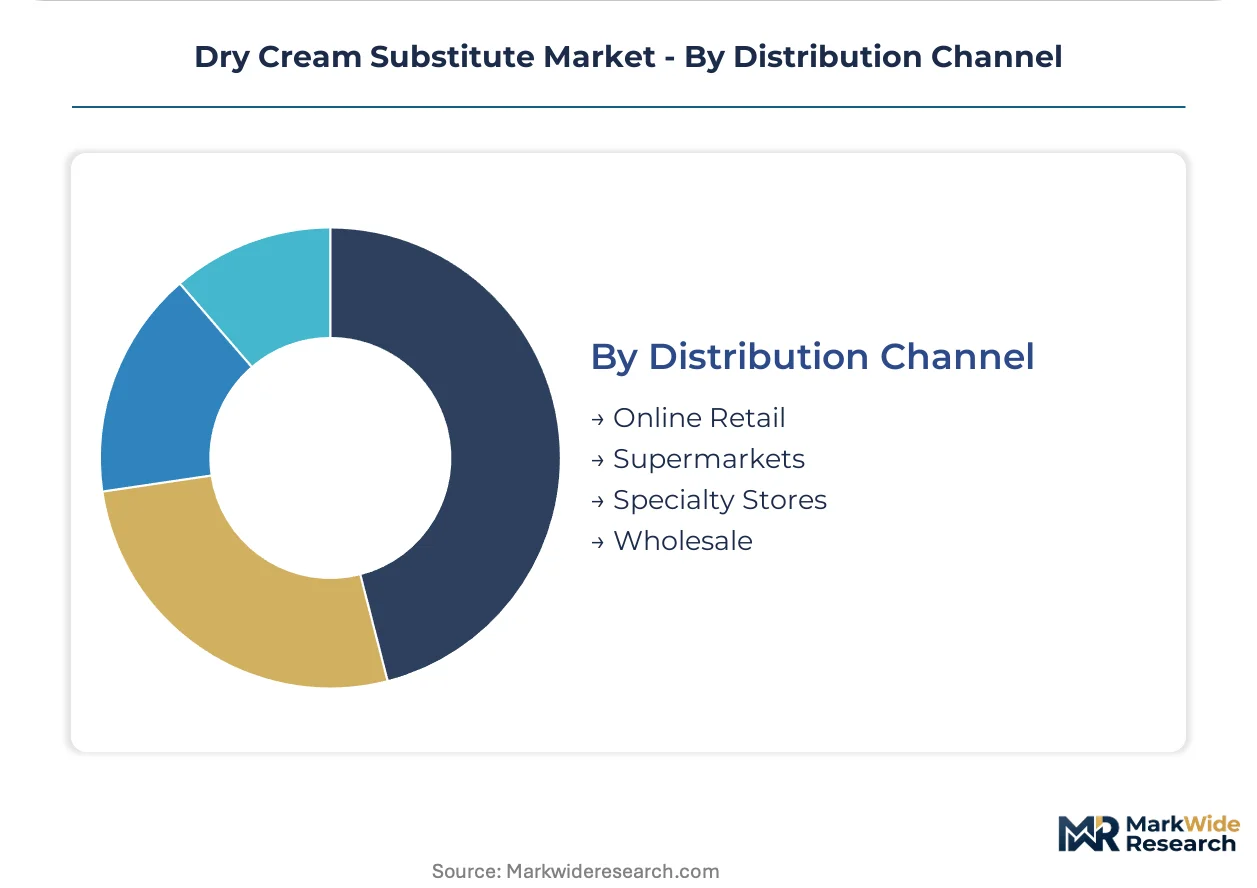
Wholesale dominates volume throughput; Online Retail is gaining share fastest on biotechnology ingredient sampling demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian refiners export over 60% of global interesterified lipid feedstock to European manufacturers, creating a trade-flow corridor that shapes supply security calculations for industrial bakeries and confectionery producers across the continent.
Germany
Industrial bakeries in Munich and Hamburg are scaling procurement of coconut cream powders for clean-label reformulations. EFSA novel food assessments for emerging plant lipid sources accelerate ingredient approvals for domestic manufacturers. The Baden-Württemberg confectionery cluster is piloting precision fermentation-derived lipids for premium praline applications.
United States
Coffee chain operators in Chicago and Seattle are consolidating supplier relationships around full-line dairy alternative portfolios. FDA updated labeling requirements for dairy alternatives reduce consumer confusion and enable clearer shelf positioning. Food manufacturers in Wisconsin specify high-performance emulsifier systems for sauce applications requiring thermal stability.
Belgium
Specialty confectionery producers in Brussels and Antwerp are sampling precision fermentation lipids for ganache formulations. EU REACH compliance for emulsifier chemistries shapes product development timelines for domestic compounders. The Flanders industrial corridor hosts pilot facilities testing enzymatic lipid modification for artisan chocolate fillings.
India
Organized retail bakery chains in Mumbai and Bangalore are expanding procurement of non-dairy cream powders following FSSAI harmonization with Codex standards. The national food regulator's streamlined safety protocols reduce import barriers for multinational suppliers. Gujarat-based industrial bakeries are reformulating recipes to eliminate dairy allergens for export-compliant production.
Netherlands
Spray-drying facilities in Rotterdam and Utrecht face EU F-Gas Regulation retrofit deadlines for ammonia-based refrigeration systems. Industrial cream powder manufacturers with captive drying capacity secure competitive advantage through early compliance. Contract caterers in Amsterdam evaluate soy cream segments for institutional baking programs.
Dry Cream Substitute Market Competitive Landscape
On the supply side, the industry is consolidating around integrated oilseed processors and specialized fermentation technology providers. Three strategic archetypes dominate: multinational agribusiness conglomerates with enzymatic modification capabilities, European bakery ingredient specialists with proprietary lipid technologies, and biotechnology-enabled entrants commercializing precision fermentation fats. Dominant competitive moves include backward integration into captive oilseed crushing capacity and direct-to-foodservice distribution model deployment.
Within the integrated processing tier, Cargill and ADM exemplify supply chain control strategies through in-house enzymatic modification capabilities. Puratos anchors the European specialist archetype through fermentation-derived lipid technologies tailored to regional bakery applications. These three companies represent contrasting pathways to functional parity with dairy cream: agricultural commodity leverage, biotechnology-enabled synthesis, and application-specific formulation expertise.
| Leading Market Players |
|---|
| Rich's Products |
| Monarch Foods |
| Puratos |
| Barry Callebaut |
| Cargill |
| ADM |
| Ingredion |
| Tate & Lyle |
| SternLife |
| Others |
Supply & Pricing Matrix
The Rotterdam-Malaysian container corridor shapes cost dynamics across substitute tiers, with freight rate volatility amplifying the spread between economy hydrogenated palm formulations and premium enzymatically-modified alternatives procured by Belgian confectionery houses.
Pricing Analysis
Next-generation precision fermentation lipids command substantial premia over current enzymatic interesterification grades, while legacy hydrogenated palm formulations face sustained cost compression. Three-tier pricing structure across premium fermentation-derived, standard enzymatically-modified, and economy hydrogenated levels separates artisan confectionery buyers from industrial beverage manufacturers. Pricing pressure stems from Malaysian refinery concentration and palm kernel oil volatility, squeezing mid-tier suppliers unable to backward integrate into captive crushing. Foodservice operators purchasing bulk non-dairy creamers exhibit highest price sensitivity; specialty ganache producers in Switzerland demonstrate lowest sensitivity due to performance-locked formulations.
Supply Chain Analysis
EU REACH re-registration protocols for emulsifier chemistries restrict cross-border flows of sodium stearoyl lactylate and related modifying salts, compelling European compounders to qualify alternative suppliers. Geographic supply concentration centers on Malaysia, Indonesia, and the Netherlands for interesterified lipid feedstock and spray-drying infrastructure. Raw material dependencies encompass hydrogenated palm kernel oil, coconut milk solids, and fermentation-derived lipid precursors. Single-source vulnerability from Malaysian refinery dominance creates structural risk for German industrial bakeries. Distribution runs through wholesale ingredient distributors managing currency exposure for European manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic processing platforms are converging with precision fermentation infrastructure, creating interoperability demands that favor suppliers with hybrid manufacturing capabilities across both technological pathways.
For Market Incumbents: Entrench supply security through backward integration into Southeast Asian oilseed crushing or captive fermentation capacity in European biotech corridors. Biotechnology-enabled entrants threaten margin pools in premium confectionery segments; defend by accelerating EFSA novel food dossier submissions for proprietary lipid modifications.
For New Entrants and Emerging Players: Build out precision fermentation lipid production targeting the Belgian-Swiss confectionery axis where enzymatic performance gaps persist. Direct-to-foodservice distribution models offer the most penetrable channel, bypassing consolidated wholesale distributors serving established coffee chains.
For Investors and Strategic Acquirers: EU F-Gas Regulation retrofit deadlines reshape the acquisition landscape toward spray-drying facilities with early ammonia-based refrigeration compliance. Long-term viability favors targets with captive drying infrastructure and enzymatic modification capabilities. Watch for FSSAI harmonization completion in India as inflection signal for organized retail bakery expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill and ADM secure Malaysian and Indonesian feedstock supply against palm price volatility. |
| Precision Fermentation Lipid Commercialization | Puratos and biotechnology entrants engineer custom fat profiles for Belgian praline applications. |
| Direct-to-Foodservice Distribution Buildout | Manufacturers bypass wholesale distributors to serve Italian coffee chains with just-in-time replenishment. |
| EU F-Gas Regulation Compliance Retrofit | Dutch and Danish spray-drying facilities secure competitive advantage through early ammonia system deployment. |
| EFSA Novel Food Dossier Acceleration | Streamlined safety assessments enable faster time-to-market for fermented and algal-derived fat technologies. |
Research Methodology
Initial hypotheses were tested against primary input from bakery R&D directors, confectionery procurement managers, foodservice chain operators, and emulsifier technology specialists and refined through secondary validation against EFSA novel food assessments, FDA labeling guidance documents, EU REACH registration databases, and Malaysian Palm Oil Board trade statistics. Bottom-up volume modeling triangulated with top-down value estimates across product type, application, and end-user segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions encompassing formulation technology tier, thermal stability specification, clean-label positioning, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis and substitution rate modeling. Industry-specific forecast inputs incorporated enzymatic processing adoption curves and precision fermentation capacity buildout timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by biotechnology-enabled entrants or accelerated EU emulsifier re-registration timelines would shift outcomes. Material shifts in Malaysian palm oil export policy or FSSAI regulatory harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dairy-Free Spreads Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
Lactose-Free Milk Market