
 Almond-Based Spreads Market | 2026-2036
Almond-Based Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Almond-Based Spreads Market Outlook
Asset-light contract manufacturing and co-packing arrangements is reconfiguring competitive entry barriers for emerging almond spread brands. The Hershey Company leverages its cocoa-butter processing infrastructure to cross-utilize equipment for nut-butter production. Mayver's anchors its position through single-origin sourcing transparency and clean-label positioning in Australian retail channels. BetterBody Foods competes on price-accessible organic formulations distributed through mass-market grocery networks.
Almond-based spreads are emulsified or ground preparations containing minimum almond content thresholds, typically processed through dry-roasting at controlled temperatures followed by stone-grinding or high-shear milling to achieve target particle size distribution below 20 microns for mouthfeel stability. Their primary commercial purpose centers on delivering plant-based protein and unsaturated fat profiles as sandwich spreads, baking ingredients, or smoothie additives in health-conscious foodservice and retail applications. Creamy variants dominate household penetration due to spreadability consistency, while crunchy formats command margin premiums in specialty shops where texture differentiation drives basket values. Organic certification segments extract higher per-unit economics but face supply volatility from California drought cycles affecting almond orchard yields.
The FDA's Food Safety Modernization Act preventive controls for human food govern almond processing facility sanitation and allergen cross-contact protocols, directly elevating compliance costs for smaller spread manufacturers. California's Almond Board mandates pasteurization requirements that shape raw versus roasted product positioning across state lines. USDA organic certification and EU REACH chemical residue standards further filter which suppliers can access dual-market distribution. Stakeholders must monitor water-right adjudications in California's Central Valley, as sustained irrigation restrictions threaten to reshape where almond milling and spread production concentrate geographically.
Market Dynamics
California's Central Valley irrigation restrictions are forcing almond processors to relocate milling capacity or secure alternative water rights, fundamentally restructuring where spread production concentrates geographically.
Growth Catalysts
- EU Green Deal deforestation-free mandates:European manufacturers are accelerating supply chain audits to meet mandatory due diligence requirements, creating certified premium demand tiers.
- Stone-grinding equipment advances:High-shear milling below 20-micron particle size distribution is improving mouthfeel stability in clean-label formulations.
- Bakery and cafe plant-based menu expansion:Foodservice operators are increasing bulk procurement of almond spreads as sandwich and pastry ingredients.
Market Restraints
- California drought cycle volatility:Sustained irrigation restrictions threaten organic almond orchard yields and concentrate supply risk in a single geography.
- FDA Food Safety Modernization Act compliance costs:Preventive controls for human food elevate facility sanitation and allergen cross-contact protocols, disproportionately burdening smaller manufacturers.
- Peanut butter price competition:Lower-cost legume-based spreads maintain household pantry dominance in mass-market grocery channels.
Strategic Opportunities
- Australian single-origin sourcing transparency:Clean-label positioning through verified origin documentation commands retail premium in Asia-Pacific export markets.
- Contract manufacturing and co-packing arrangements:Asset-light production models reduce capital barriers for emerging brand entry.
- USDA organic certification dual-market access:Combined US-EU organic standards enable streamlined export qualification for compliant processors.
Industry Challenges
- Water-right adjudication timeline uncertainty:California's Central Valley irrigation restriction rulings create capacity planning paralysis for orchard-dependent processors.
- Allergen cross-contact protocol validation:FDA-mandated sanitation verification extends production changeover cycles and compresses batch economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond-Based Spreads Market |
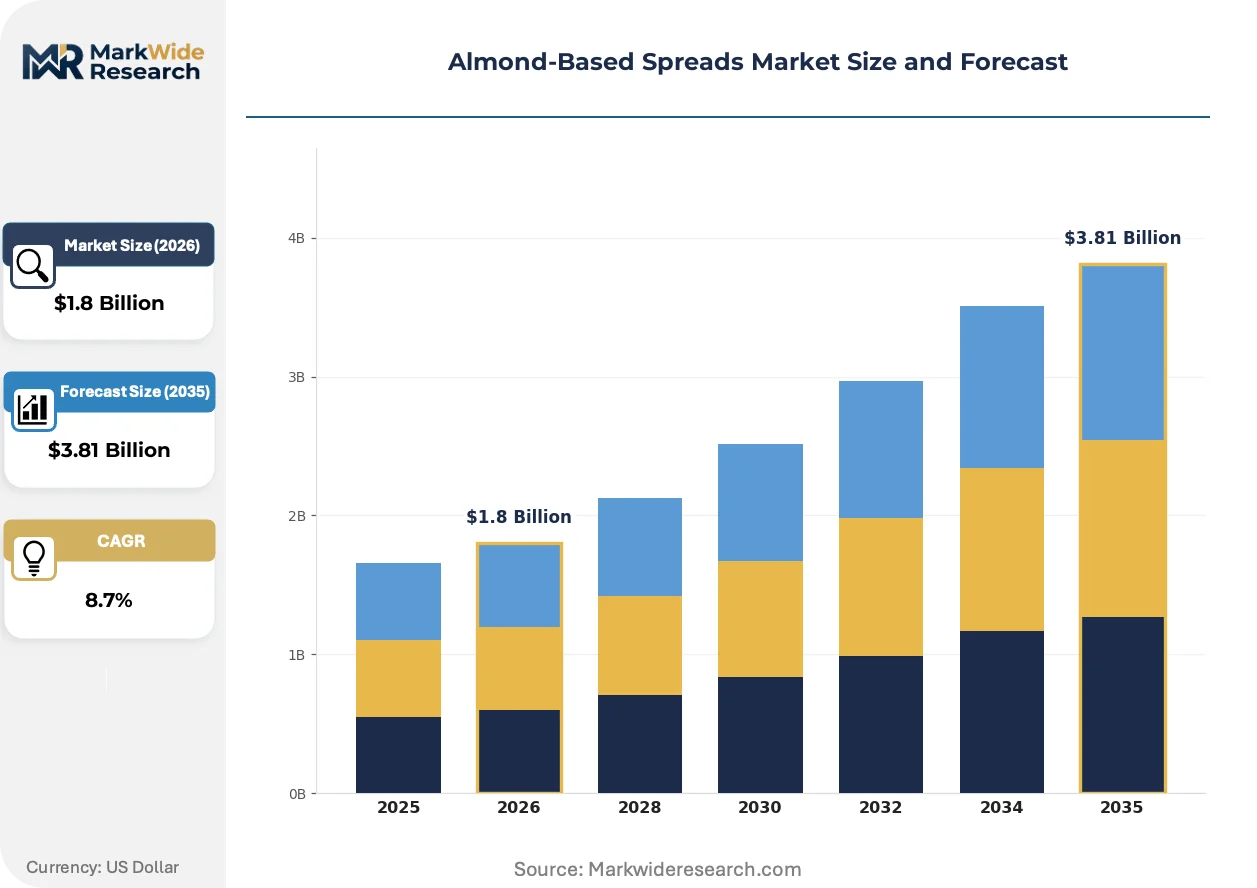
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crunchy, Creamy, Organic, Flavored Packaging Type: Jars, Pouches, Tubs, Sachets Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops End User: Households, Restaurants, Cafes, Bakeries |
| Companies Covered | The Hershey Company, My Raw Joy, Ingenuity Brands, Natural World, SHS Group, Mayver's, BetterBody Foods, Melrose Laboratories Pty Ltd, ImmaculateBites (India) Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond-Based Spreads Market Strategic Shifts
Equipment cross-utilization and regulatory compliance automation are compressing production economics while clean-label positioning is fragmenting premium tiers across retail channels.
High-shear milling technology is hybridizing with traditional stone-grinding processes to achieve sub-20-micron particle size distribution at commercial throughput rates. Mid-scale processors are adopting hybrid systems to balance mouthfeel quality with batch volume requirements. This equipment convergence is enabling smaller facilities to match multinational texture consistency standards without dedicated capital expenditure.
EU REACH chemical residue standards are tightening maximum allowable limits on processing aids and surface sanitizers used in nut-butter facilities. European manufacturers are reformulating production protocols to eliminate quaternary ammonium compounds from equipment cleaning cycles. Organic-certified spreads face the steepest compliance burden as dual USDA-EU organic verification requires parallel residue documentation.
Bulk foodservice procurement is consolidating purchasing authority among national bakery and cafe chains with standardized plant-based menu specifications. Distributors are responding with private-label almond spread programs that displace branded SKUs in institutional channels. This buyer concentration is most pronounced in California and Texas where regional cafe chains anchor multi-location supply agreements.
Almond-Based Spreads Market Segmentation
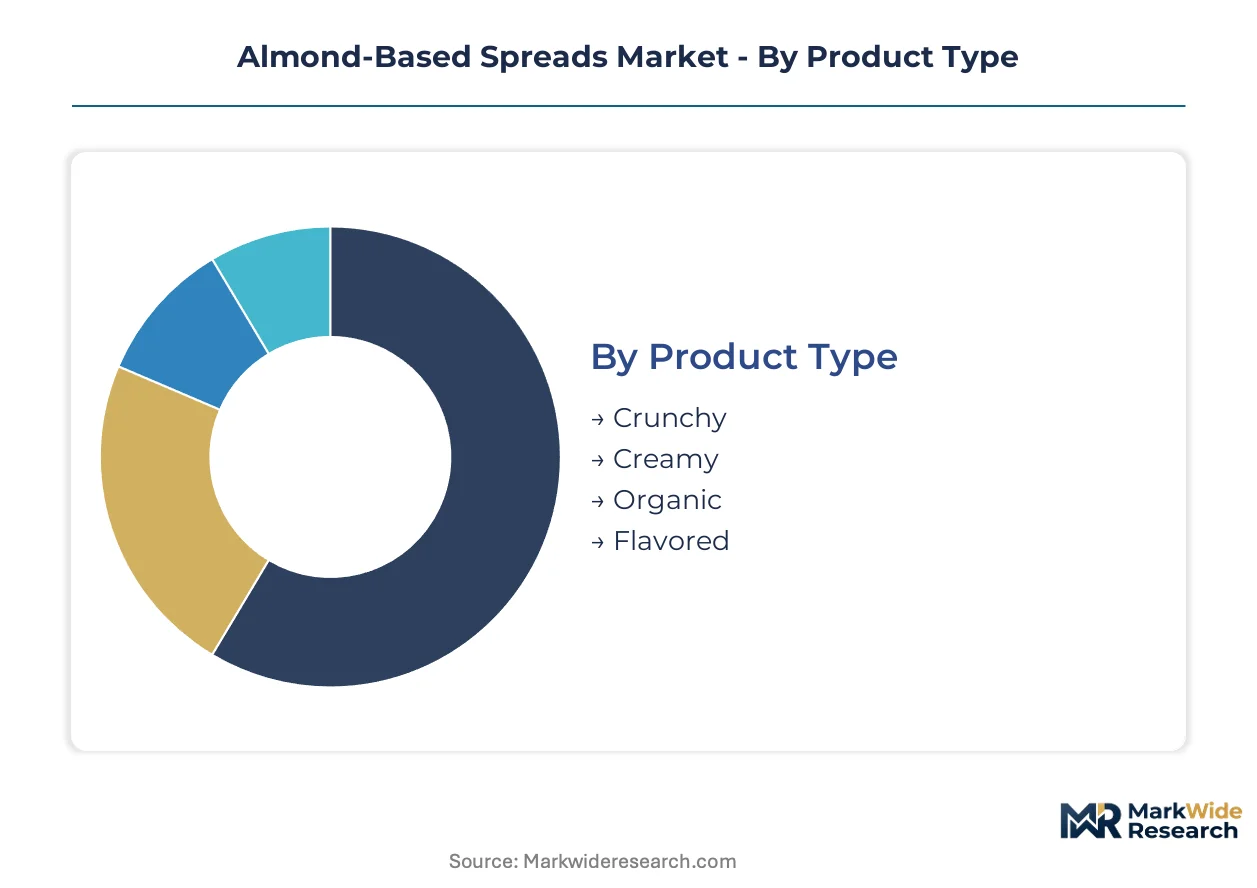
Almond-based spreads fragment across four distinct category axes, each shaping procurement patterns and margin structures differently. Product texture and certification status drive household pantry decisions, while packaging format and channel access determine foodservice penetration rates.
Product Type:
Mature formats anchor volume, while emerging certifications and flavor innovations capture premium expansion.
- Creamy:Stone-ground to sub-20-micron particle size distribution for consistent spreadability across bread and pastry applications. Household penetration concentrates in California and Texas where mass-market grocery chains stock private-label variants; peanut butter price competition constrains absolute margin capture despite volume leadership.
- Organic:Dual USDA-EU certified supply chains command retail premiums but face yield volatility from Central Valley irrigation restrictions. Demand clusters in specialty shops across Germany and France where EU Green Deal deforestation-free mandates filter conventional supply; drought cycles threaten orchard-dependent processors with supply interruption.
- Crunchy:Textured inclusions of almond fragments differentiate specialty retail positioning. Australian single-origin sourcing commands basket value premiums in Asia-Pacific export markets.
- Flavored:Cocoa, honey, and spice infusions target café smoothie and bakery ingredient channels. Innovation cycles accelerate in foodservice procurement programs.
Creamy handles the majority of throughput; Organic is expanding most quickly on share as clean-label positioning hardens across retail tiers.
Packaging Type:
Cost tier stratification separates institutional bulk from premium single-serve convenience formats.
- Jars:Standard glass and PET containers dominate household retail shelf presence with resealability for extended pantry storage. Mass-market grocery networks in the United States and United Kingdom anchor procurement volumes.
- Pouches:Flexible film structures reduce freight cube and enable squeeze-dispense functionality for foodservice speed-of-service requirements. National bakery chains in California and Texas are consolidating purchasing authority around pouch formats for back-of-house efficiency.
- Tubs:Wide-mouth plastic containers target bulk foodservice and bakery ingredient applications. Distributor private-label programs displace branded SKUs in institutional channels.
- Sachets:Single-serve portions command airline, hospitality, and grab-and-go retail premiums. Portion control aligns with EU REACH chemical residue documentation requirements for sealed-unit traceability.
Jars handle the majority of throughput; Pouches are gaining share fastest as foodservice procurement consolidates.
Distribution Channel:
Customer type concentration splits between price-sensitive mass retail and relationship-driven specialty access.
- Supermarkets:Mass-market grocery networks anchor volume through private-label and price-accessible organic formulations. BetterBody Foods competes through this channel with national distribution scale.
- Online Retail:Direct-to-consumer and marketplace platforms enable emerging brand entry without shelf-slotting capital. Subscription models concentrate in health-conscious demographic clusters.
- Health Food Stores:Clean-label positioning and single-origin transparency command retail premiums. Mayver's anchors Australian positioning through verified origin documentation in this channel.
- Specialty Shops:Curated assortments with texture differentiation and small-batch provenance drive basket values. Crunchy formats extract margin premiums where mouthfeel storytelling supports price architecture.
Supermarkets handle the majority of throughput; Online Retail is climbing the fastest on share as asset-light brand entry accelerates.
End User:
Application maturity separates established household consumption from emerging foodservice ingredient demand.
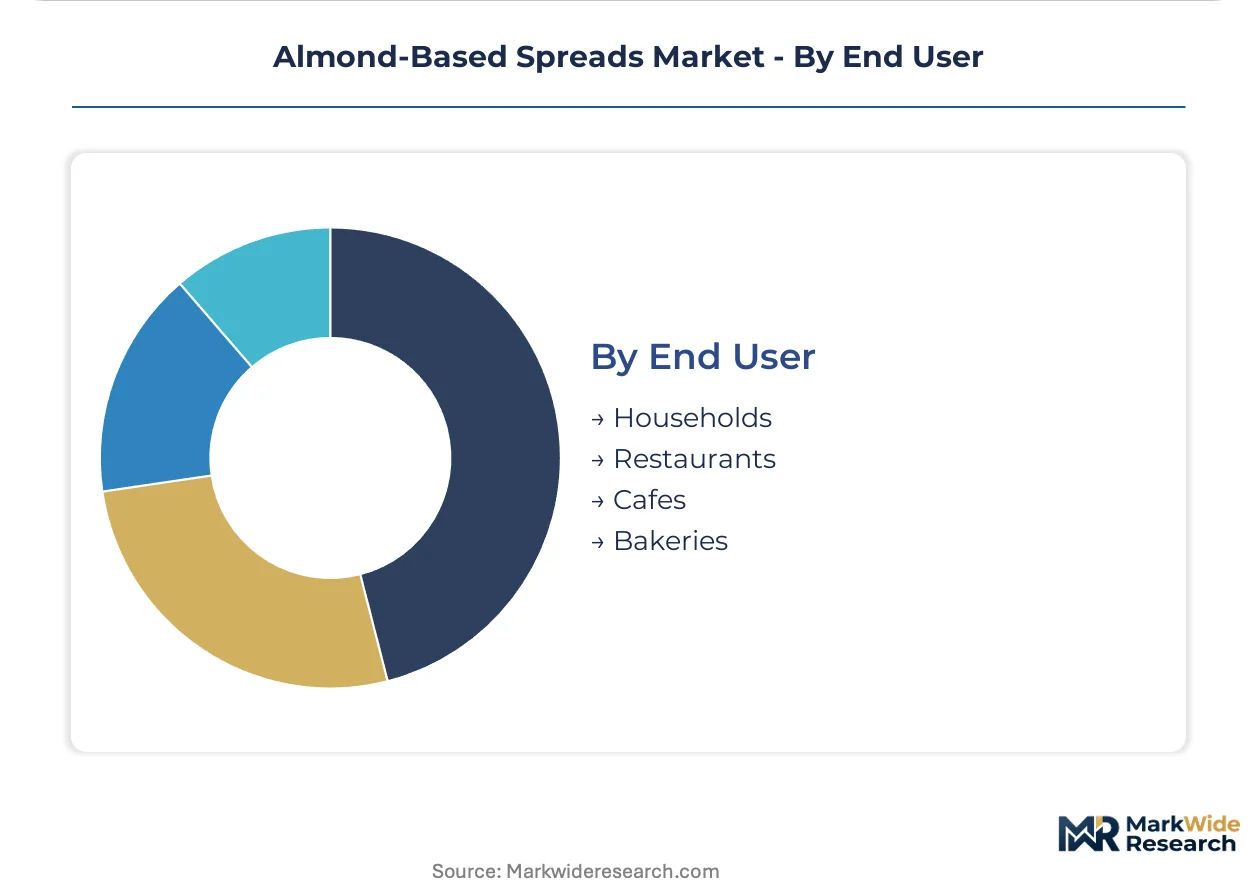
- Households:Sandwich spread and smoothie additive consumption anchors recurring purchase frequency. Creamy texture preferences dominate pantry stocking decisions in mass-market channels.
- Restaurants:Plant-based menu expansion drives bulk procurement for sauce bases and dessert components. Standardized specifications enable distributor private-label displacement of branded SKUs.
- Cafes:National chains in California and Texas anchor multi-location supply agreements with consolidated purchasing authority. Bakery and pastry ingredient applications concentrate procurement volume.
- Bakeries:Ingredient-grade specifications for emulsified fillings and toppings require sub-20-micron particle size consistency. Hybrid stone-grinding and high-shear milling equipment investments enable smaller facilities to match multinational texture standards.
Households handle the majority of throughput; Bakeries are on the steepest expansion trajectory as plant-based ingredient substitution accelerates in commercial baking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in California's Central Valley exceeds Australian single-origin premiums by a significant margin, while EU Green Deal compliance costs compress margins for European processors sourcing from deforestation-risk jurisdictions.
United States
Bakery and cafe chains in California and Texas are consolidating multi-location supply agreements for bulk almond spread procurement. The FDA's Food Safety Modernization Act preventive controls elevate facility sanitation costs for domestic processors. Fresno County and the broader Central Valley anchor North American milling capacity, though irrigation restriction rulings are forcing capacity relocation decisions.
Germany
Specialty retail channels across Bavaria and Baden-Württemberg command premium positioning for organic-certified spreads with dual USDA-EU verification. ECHA's REACH chemical residue standards are tightening maximum allowable limits on quaternary ammonium compounds in equipment cleaning cycles. Hamburg's food processing cluster is reformulating production protocols to eliminate non-compliant sanitizers from nut-butter facilities.
Australia
Clean-label positioning through verified single-origin sourcing documentation drives Asia-Pacific export demand from Melbourne and Sydney health food retail networks. The TGA's food standards code governs allergen labeling and cross-contact protocols for domestic manufacturers. Victoria's almond processing facilities are expanding stone-grinding capacity to meet sub-20-micron particle size specifications for premium texture consistency.
France
EU Green Deal deforestation-free supply chain mandates are accelerating due diligence audits for Paris and Lyon-based distributors sourcing from high-risk jurisdictions. EFSA residue monitoring programs filter which suppliers qualify for organic retail placement. The Île-de-France region's specialty foodservice procurement is consolidating purchasing authority around certified premium tiers with full traceability documentation.
United Kingdom
Mass-market grocery networks in Greater London and the Southeast are expanding private-label almond spread programs to displace branded SKUs. The Food Standards Agency enforces allergen cross-contact protocols aligned with EU REACH standards post-Brexit. Manchester's food manufacturing corridor is investing in hybrid stone-grinding and high-shear milling equipment to match multinational texture standards at mid-scale throughput.
Almond-Based Spreads Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient-grade positioning. The vendor base clusters around three functional tiers: multinational food conglomerates with cross-utilized processing infrastructure, mid-scale organic specialists with single-origin transparency positioning, and contract manufacturers offering asset-light production entry for emerging brands. Consolidation pressure concentrates among bakery and cafe procurement channels where distributor private-label programs displace branded volume. Competitive moves center on equipment cross-utilization for capital efficiency and co-packing arrangements to lower entry barriers for clean-label entrants.
Within the multinational conglomerate tier, The Hershey Company exemplifies platform-scale leverage through cocoa-butter processing infrastructure repurposed for nut-butter production. Mayver's and BetterBody Foods occupy distinct positioning archetypes: the former anchors Australian single-origin transparency through verified origin documentation, while the latter competes on price-accessible organic formulations distributed through mass-market grocery networks. These three entities represent the dominant competitive vectors—cross-utilized infrastructure, clean-label provenance, and price-accessible certification—shaping margin capture across retail tiers.
| Leading Market Players |
|---|
| The Hershey Company |
| My Raw Joy |
| Ingenuity Brands |
| Natural World |
| SHS Group |
| Mayver's |
| BetterBody Foods |
| Melrose Laboratories Pty Ltd |
| ImmaculateBites (India) Private Limited |
| Others |
Value Chain & Pricing Dynamics
Los Angeles-Long Beach port congestion surcharges ripple through California almond spread supply chains, amplifying cost differentials between Central Valley processors and Australian single-origin exporters while compressing margins for organic-certified tiers dependent on dual-market distribution.
Pricing Analysis
Configured-to-order premiums for stone-ground sub-20-micron specifications command substantial markups over standard creamy formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and texture consistency. Cost compression in mass-market grocery channels intensifies as private-label programs displace branded SKUs. Foodservice buyers exhibit lowest price sensitivity due to menu specification lock-in, while household consumers in Texas and California demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for distributor relationships with national bakery chains. Supply concentrates in the United States, Australia, and Spain for raw almond sourcing. Processing draws from California Central Valley milling clusters, Victorian stone-grinding facilities, and Hamburg equipment manufacturing. Single-source vulnerability runs through Central Valley irrigation-dependent orchards. Distribution runs through foodservice distributors, mass-market grocery networks, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is accelerating as national cafe chains consolidate multi-location procurement authority, fragmenting supplier negotiation leverage across smaller regional accounts.
For Market Incumbents: Pre-empt private-label displacement by securing exclusive co-packing arrangements with distributor networks. Invest in hybrid stone-grinding and high-shear milling capacity to match multinational texture standards without dedicated capital expenditure. FDA Food Safety Modernization Act compliance automation represents the priority defensive lever against smaller competitors. For New Entrants and Emerging Players: Establish a beachhead in Australian single-origin transparency positioning for Asia-Pacific export markets. Target foodservice pouch format procurement where consolidated purchasing authority has not yet locked in supply agreements. Clean-label subscription models offer the most penetrable go-to-market angle for direct-to-consumer entry. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational food conglomerates seeking to divest non-core nut-butter processing infrastructure. Long-term viability hinges on water-right security in sourcing geographies and dual USDA-EU organic certification capability. Watch California Central Valley adjudication rulings as the critical inflection signal for capacity relocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packing Partnership Expansion | Asset-light production models reduce capital barriers for emerging clean-label brands entering mass-market channels. |
| Hybrid Equipment Investment | Stone-grinding and high-shear milling convergence enables mid-scale processors to match multinational texture standards. |
| Dual Organic Certification | Combined USDA-EU verification streamlines export qualification for compliant processors targeting transatlantic distribution. |
| Foodservice Pouch Format Rollout | Squeeze-dispense functionality aligns with national bakery chain back-of-house efficiency requirements. |
| Single-Origin Provenance Documentation | Verified origin transparency commands retail premiums in Asia-Pacific health food store networks. |
Study Parameters
Initial hypotheses were tested against primary input from almond processing facility managers, foodservice procurement directors at national bakery chains, organic certification auditors, and mass-market grocery category buyers and refined through secondary validation against FDA enforcement data, USDA organic certification records, EU REACH compliance filings, and California water-right adjudication documents. Bottom-up volume estimates from processor capacity utilization were triangulated with top-down demand projections from retail audit data.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product texture, certification status, packaging format, and distribution channel. CAGRs were derived from weighted capacity expansion timelines and substitution elasticity parameters. Forecast inputs incorporated California drought cycle frequency, EU Green Deal deforestation-free compliance adoption curves, and foodservice menu specification standardization rates.
Stress conditions across Central Valley irrigation restriction severity, EU chemical residue limit tightening, and almond orchard yield volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and supply chain relocation feasibility. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Foie Gras Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Free-From Food Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Low Calorie Chocolate Desserts Market