
 Asia-Pacific Non-Dairy Milk Market | 2026-2036
Asia-Pacific Non-Dairy Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Non-Dairy Milk Market Insights
China's GB standards for plant-based beverages is shifting the cost-of-entry calculus for new entrants by mandating minimum protein thresholds and clearer allergen disclosures. Hebei Yangyuan Zhihui Beverage Co. Ltd leverages its deep distribution network across northern China to sustain volume leadership in walnut and almond-based lines. Vitasoy International Holdings Ltd anchors its competitive position through decades of soy milk manufacturing expertise and entrenched retail relationships across Greater China. Oatly Group AB competes by positioning its barista-edition formulations as the default dairy alternative in premium coffee chains throughout Shanghai, Seoul, and Sydney.
Non-dairy milk denotes aqueous emulsions extracted from oilseeds, grains, or nuts, typically containing 2-8% plant solids, homogenized to prevent phase separation and fortified with calcium, vitamin D, and B12 to approximate dairy nutritional profiles. The primary commercial purpose is to serve consumers with lactose malabsorption, milk protein allergy, or ethical dietary restrictions while delivering functional properties for beverage and food manufacturing applications. Soy milk retains the largest installed production base and lowest unit economics across the Asia-Pacific, though oat milk claims the fastest trajectory as coffee culture proliferation drives on-premise adoption. Supermarkets dominate distribution volume, yet online retail captures disproportionate growth in subscription-based repeat purchases where health stores curate premium positioning for organic and clean-label variants.
FSSAI in India enforces compositional standards for vegan milk alternatives while Australia's FSANZ governs nutrition content claims and health star ratings on plant-based labels. Japan's Ministry of Health, Labour and Welfare maintains distinct allergen labeling requirements that shape formulation choices for multinational suppliers entering those markets. Stakeholders must monitor how divergent protein fortification rules and emerging carbon footprint disclosure obligations across Chinese, Indian, and Australian jurisdictions will reshape sourcing strategies and product architecture.
Market Dynamics
China's GB standards for plant-based beverages are compressing formulation margins while elevating protein fortification requirements, forcing manufacturers to reconfigure supply chains around higher-cost raw material sourcing.
Growth Catalysts
- Lactose intolerance prevalence:Urban populations in Shanghai and Mumbai exhibit elevated malabsorption rates, creating concentrated demand pockets for enzymatically neutral alternatives.
- FSSAI vegan standards:India's compositional regulations legitimize category positioning on retail shelves, accelerating mainstream acceptance beyond niche health channels.
- Enzymatic hydrolysis advances:Improved oat processing yields reduce viscosity barriers, enabling barista-grade foam stability previously achievable only with dairy.
Market Restraints
- Almond water intensity:California drought exposure transmits price volatility through Asia-Pacific supply chains, compressing margin structures for nut-based formulations.
- GB protein thresholds:China's minimum protein mandates exclude lower-fortification products from formal classification, eliminating economy-tier positioning strategies.
- Dairy residual taste:Consumer sensory testing reveals persistent preference gaps in tea applications, limiting complete substitution in traditional beverage contexts.
Strategic Opportunities
- Tier-two China expansion:Chengdu and Hangzhou retail penetration remains underdeveloped relative to saturation in Beijing and Shanghai corridors.
- Subscription channel development:Direct-to-consumer platforms capture recurring purchase patterns with higher lifetime value than conventional supermarket transactions.
- Carbon labeling alignment:Australia's emerging disclosure obligations reward regionally sourced oat and soy inputs with verified footprint credentials.
Industry Challenges
- Formulation talent scarcity:Food science professionals with plant protein stabilization expertise command premium compensation, constraining R&D scaling.
- Allergen line segregation:Manufacturing facilities require dedicated processing zones to satisfy Japan's Ministry of Health, Labour and Welfare labeling standards.
- Fortification stability testing:Calcium and vitamin D degradation curves demand extended shelf-life validation protocols, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Non-Dairy Milk Market |
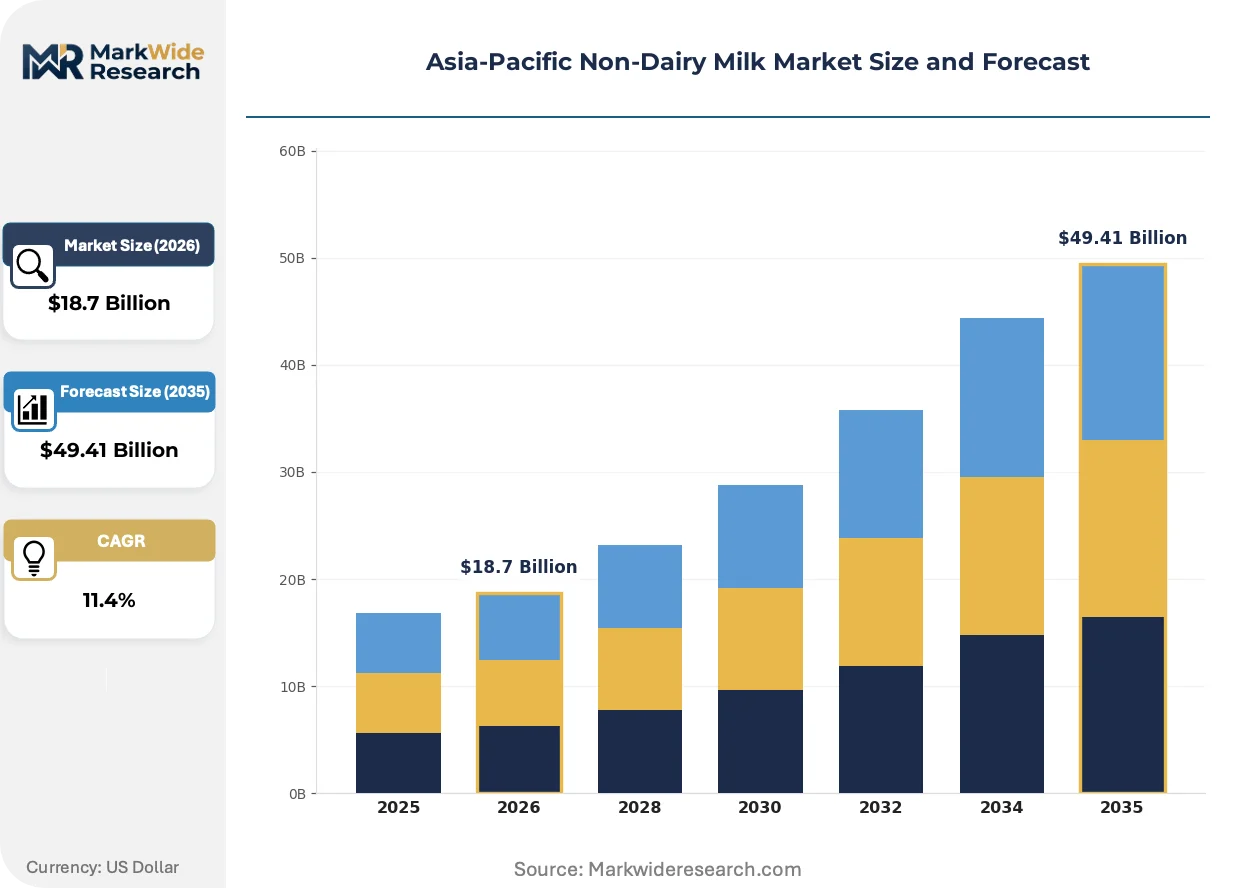
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Packaging Type: Carton, Bottle, Pouch, Can End User: Households, Cafes, Restaurants, Food Manufacturers Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores |
| Companies Covered | Hebei Yangyuan Zhihui Beverage Co. Ltd, Nestlé SA, Kikkoman Corporation, PureHarvest, Freedom Foods Group Ltd, Vitasoy International Holdings Ltd, Oatly Group AB, Sanitarium Health and Wellbeing Company, Coconut Palm Group Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Non-Dairy Milk Market Trends and Innovations
Enzymatic processing breakthroughs and regulatory disclosure mandates are compressing traditional formulation advantages while elevating transparency as a competitive differentiator across Asia-Pacific retail channels.
High-pressure processing is overtaking conventional heat treatment in premium oat milk manufacturing. Specialty coffee chains in Seoul and Sydney specify HPP-treated barista editions for superior foam microstructure and extended refrigerated stability. This technology is overtaking legacy UHT methods in the premium tier, compressing price positioning for standard shelf-stable alternatives.
China's GB standards for plant-based beverages mandate minimum protein content and additive disclosure thresholds that reshape product architecture decisions. Manufacturers must reformulate or exit formal classification, concentrating volume among suppliers with captive fortification capabilities. Soy and oat categories face the steepest compliance curves given their divergent base protein levels.
Health store curation is displacing mass-market discovery as the primary category entry point for organic and clean-label variants. Subscription platforms in Australia's metropolitan corridors now originate trial purchases that convert to supermarket repeat buying. This channel rotation is most visible in Melbourne and Sydney, where dedicated non-dairy sections expand faster than conventional dairy adjacencies.
Asia-Pacific Non-Dairy Milk Market Segmentation
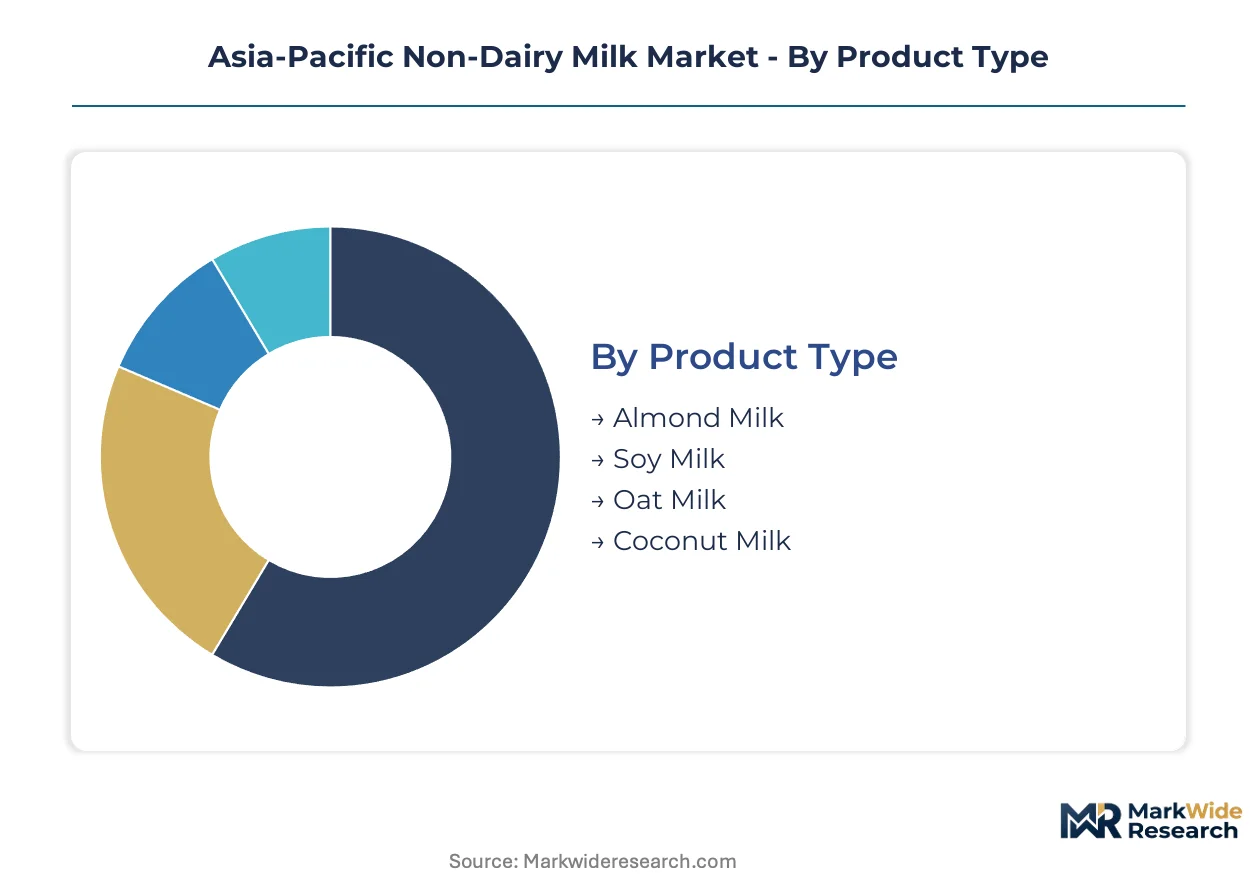
Non-dairy milk segmentation in Asia-Pacific reflects divergent procurement priorities across foodservice operators and retail consumers. Category boundaries shift as enzymatic processing advances and China's GB standards compress formulation economics.
Product Type:
Buyers differentiate primarily by protein fortification economics and foam functionality for barista applications.
- Soy Milk:Retains the lowest unit production costs and deepest installed manufacturing base across the region. Volume concentrates in northern China's retail corridors and India's metropolitan wholesale channels where FSSAI compositional standards validate mainstream positioning.
- Oat Milk:Enzymatic hydrolysis yields now deliver dairy-comparable foam stability for specialty coffee chains. Demand clusters in Seoul, Shanghai, and Sydney where premium on-premise consumption drives fastest category expansion.
- Almond Milk:California drought exposure transmits raw material volatility through Asia-Pacific supply chains.
- Coconut Milk:Traditional base for Southeast Asian food manufacturing applications with established regional sourcing networks.
Volume sits with soy milk; growth tilts toward oat milk.
Packaging Type:
Channel economics and shelf-life requirements separate institutional buyers from household procurement patterns.
- Carton:Dominates supermarket and health store distribution with aseptic barrier properties supporting extended ambient stability. Adoption concentrates in Australia's subscription channels and China's tier-one retail where Melbourne and Sydney health stores curate premium positioning.
- Bottle:Refrigerated distribution infrastructure favors high-turnover urban corridors. Demand concentrates in Seoul and Tokyo convenience retail where cold-chain density supports shorter shelf-life formats.
- Pouch:Flexible format reduces freight cube for e-commerce fulfillment in India's direct-to-consumer expansion.
- Can:Metal barrier suits food manufacturing bulk procurement with tolerance for warehouse temperature variation.
Carton claims installed volume leadership; bottle formats gain share fastest in cold-chain mature corridors.
End User:
Application specifications diverge sharply between beverage service functionality and ingredient processing requirements.
- Cafes:Barista-grade foam stability and neutral flavor profiles command premium positioning. Procurement concentrates in Shanghai, Seoul, and Sydney specialty coffee chains where Oatly's barista edition established category default status.
- Food Manufacturers:Bulk viscosity control and protein content standardization drive specification decisions. Demand clusters in China's processed food corridors where GB protein thresholds mandate reformulation compliance.
- Households:Repeat purchase patterns favor subscription platforms with curated organic variants in Australia's metropolitan markets.
- Restaurants:Menu flexibility requirements favor multi-format suppliers with regional distribution reach.
Food manufacturers anchor volume scale; cafes drive premium tier expansion.
Distribution Channel:
Discovery mechanics and replenishment frequency separate trial-oriented platforms from loyalty-driven subscription models.
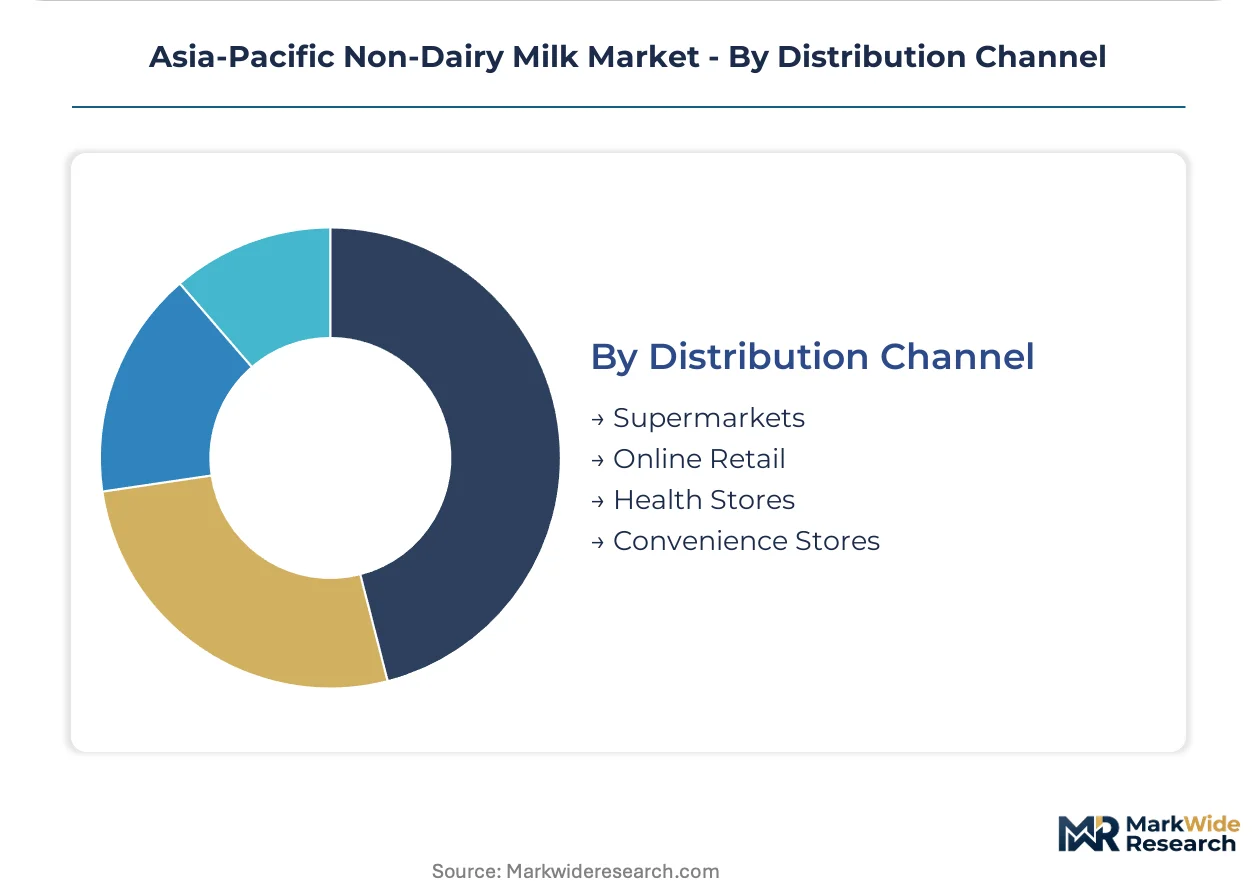
- Supermarkets:Category management and shelf-space allocation determine mainstream visibility. Volume concentrates in China's tier-one cities and India's metropolitan corridors where Hebei Yangyuan Zhihui and Vitasoy maintain entrenched retail relationships.
- Online Retail:Subscription algorithms capture recurring purchase patterns with higher lifetime value than conventional transactions. Growth concentrates in Melbourne, Sydney, and Seoul where platform curation displaces mass-market discovery.
- Health Stores:Clean-label and organic variants find differentiated positioning outside conventional dairy adjacencies.
- Convenience Stores:Impulse availability and single-serve formats suit urban commuter corridors.
Supermarkets retain volume concentration; online retail climbs the fastest in subscription-mature markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives and duty exemptions are drawing coconut milk processors and plant-based beverage formulators to establish southern coastal manufacturing nodes. India's Special Economic Zones in Gujarat and Maharashtra offer comparable fiscal advantages for FSSAI-compliant production facilities. Australia's designated food innovation precincts concentrate enzymatic processing R&D in Victoria and New South Wales.
China
GB standards for plant-based beverages mandate minimum protein thresholds and additive disclosure that eliminate economy-tier positioning. SAMR enforcement compresses formulation margins while elevating fortification requirements. Volume concentrates in Beijing, Shanghai, and Guangzhou where Hebei Yangyuan Zhihui and Vitasoy maintain entrenched retail relationships across tier-one corridors.
India
FSSAI compositional standards for vegan milk alternatives legitimize mainstream shelf placement beyond health channels. Urban lactose intolerance prevalence in Mumbai and Delhi-NCR drives concentrated demand for soy and almond variants. Maharashtra and Gujarat industrial zones host emerging domestic processors scaling to meet subscription channel growth in metropolitan markets.
Japan
METI guidance on functional food claims shapes premium positioning for vitamin-fortified oat and soy lines. The Ministry of Health, Labour and Welfare maintains stringent allergen labeling requirements that dictate manufacturing facility segregation protocols. Kanto region processors around Tokyo supply convenience retail and foodservice channels with shorter shelf-life refrigerated formats.
Australia
FSANZ nutrition content claims and emerging carbon footprint disclosure obligations reward regionally sourced oat inputs with verified credentials. Melbourne and Sydney health stores curate premium organic variants that convert to supermarket repeat purchasing. Victoria's food innovation precincts anchor enzymatic hydrolysis R&D for barista-grade foam stability applications.
South Korea
MFDS fortification standards and specialty coffee chain procurement specifications drive premium oat milk adoption in Seoul. Daegu-Gyeongbuk manufacturing clusters supply HPP-treated barista editions for domestic consumption and regional export. Convenience retail density in the capital supports high-turnover refrigerated distribution infrastructure.
Asia-Pacific Non-Dairy Milk Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across protein fortification tiers and channel positioning. The vendor base stratifies into three functional layers: legacy beverage conglomerates with dairy-alternative portfolios, regional soy and nut milk specialists with captive distribution, and oat-focused entrants scaling through coffee chain partnerships. Consolidation pressure operates most intensely in China's tier-one cities where GB compliance costs favor scale. Dominant competitive moves include backward integration into raw material sourcing and geographic expansion through distributor acquisition.
Within the regional specialist tier, Hebei Yangyuan Zhihui Beverage Co. Ltd and Vitasoy International Holdings Ltd exemplify entrenched distribution archetypes with decades of retail relationship depth across Greater China. Oatly Group AB occupies a position representing the coffee-channel-first expansion model that prioritizes barista-grade functionality over mass-market penetration. Nestlé SA represents the diversified conglomerate archetype leveraging cross-category manufacturing infrastructure to absorb fortification compliance costs.
| Leading Market Players |
|---|
| Hebei Yangyuan Zhihui Beverage Co. Ltd |
| Nestlé SA |
| Kikkoman Corporation |
| PureHarvest |
| Freedom Foods Group Ltd |
| Vitasoy International Holdings Ltd |
| Oatly Group AB |
| Sanitarium Health and Wellbeing Company |
| Coconut Palm Group Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
California almond futures and Australian oat spot indices transmit volatility through Asia-Pacific formulation economics, compressing margin structures for nut-dependent suppliers while rewarding regional oat processors with shorter procurement lead times. GB protein fortification mandates in China and FSSAI compositional standards in India reshape cost curves by eliminating sub-threshold products from formal classification, concentrating pricing power among scaled fortifiers.
Pricing Analysis
Short-lead-time premiums for HPP-treated barista editions command shelf-space positioning in Seoul and Sydney specialty coffee chains, while spot inventory discounts concentrate in India's pouch-format direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates enzymatically processed oat lines from UHT-stable soy bases and unfortified commodity alternatives. Price differentiation hinges on certification grade and volume scale, with organic and carbon-verified variants capturing sustained premiums. Cost compression in economy-tier soy milk is intensifying because GB threshold compliance excludes marginal producers. Food manufacturers exhibit highest price sensitivity due to bulk procurement scale, while cafe operators prioritize foam functionality over per-unit cost.
Supply Chain Analysis
Food science talent shortages in Victoria and New South Wales constrain enzymatic hydrolysis scale-up, forcing manufacturers to compete for plant protein stabilization expertise across Australia's innovation precincts. Manufacturing gravity centers on China's northern provinces, India's Maharashtra-Gujarat corridor, and South Korea's Daegu-Gyeongbuk clusters, each feeding distinct regulatory compliance requirements. Raw material sourcing draws from Australian oat fields, Canadian prairie grains, and Southeast Asian coconut plantations. Single-source vulnerability in California almond supply exposes margin compression during drought cycles. Distribution runs through supermarket-owned logistics in China's tier-one cities, subscription-platform fulfillment in Australian metros, and cold-chain convenience retail in Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's GB standards for plant-based beverages erect a cost-of-compliance barrier that eliminates sub-scale formulators, creating durable moats for incumbents with captive fortification infrastructure and SAMR-validated production protocols.
For Market Incumbents: Cement category leadership by acquiring distributor networks in Chengdu and Hangzhou before tier-two saturation accelerates, and by investing in backward integration into Australian oat sourcing to secure carbon-verified supply against emerging FSANZ disclosure mandates. The threat of oat-focused entrants scaling through coffee chain partnerships demands preemptive barista-grade capacity expansion. Certification investment in dual organic-carbon credentials is the priority lever for premium-tier defense. For New Entrants and Emerging Players: Subscription-platform routes into Melbourne and Sydney health stores offer the most penetrable white-space entry, converting curated trial to supermarket repeat purchase before incumbent shelf-space consolidation hardens. India's direct-to-consumer pouch segment remains underdeveloped relative to China's saturation, presenting viable scale opportunity for FSSAI-compliant domestic processors. Go-to-market execution should prioritize influencer-curated discovery algorithms over conventional trade marketing. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap oat processors with stranded HPP capacity in South Korea and Victoria, where specialty coffee demand temporarily outran manufacturing scale. Long-term viability over the coming decade rests on regulatory compliance architecture rather than brand equity alone, given GB and FSSAI threshold convergence. Acquisition targets should demonstrate validated fortification stability testing protocols. The signal to watch is carbon disclosure mandate acceleration across Australian and Chinese jurisdictions, which would revalue regionally sourced supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Sourcing | Captive Australian supply secures FSANZ carbon disclosure compliance ahead of regulatory activation. |
| HPP Manufacturing Scale-Up | High-pressure processing capacity in Daegu-Gyeongbuk meets Seoul cafe chain procurement specifications. |
| Subscription Platform Partnership | Melbourne and Sydney algorithmic curation displaces mass-market discovery for organic variants. |
| GB Compliance Certification Investment | SAMR-validated protein fortification protocols eliminate economy-tier competition from formal classification. |
| Tier-Two China Distribution Acquisition | Chengdu and Hangzhou retail penetration remains underdeveloped relative to Beijing-Shanghai saturation. |
Research Methodology
Multi-period observation of GB standard enforcement patterns, FSSAI registration trajectories, and specialty coffee chain procurement specifications anchored the trend analysis, supplemented by interviews with plant-based beverage R&D directors, retail category buyers in Shanghai and Sydney, food manufacturing procurement leads, and regulatory affairs specialists at SAMR and FSSAI. Secondary validation drew from customs trade records, FSANZ nutrition claim filings, SEC disclosures by listed processors, and enzymatic processing patent filings. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segment-weighting across product type, packaging format, end-use application, and distribution channel shaped the analytical framework, with protein fortification tier and foam functionality grade as industry-specific dimensions. CAGRs were derived from installed capacity trajectories and per-capita consumption elasticity models. Forecast inputs incorporated cold-chain infrastructure buildout rates in tier-two Chinese cities and subscription platform penetration curves in Australian metropolitan markets.
The model holds under stable regulatory enforcement intensity and intact specialty coffee demand growth; deviation in GB threshold revision timing or California drought severity would shift volume projections. Forecasts reflect documented assumptions about enzymatic hydrolysis yield improvement curves and health store channel expansion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Banana Milk Market