
 Camel Milk Products Market | 2026-2036
Camel Milk Products Market Size, Share, and Industry Trends Forecast 2026-2036
Camel Milk Products Market Intelligence
Market Context
Health enthusiasts are unwinding the historical dominance of traditional retail consumers in camel milk product procurement. Emirates Industry for Camel Milk and Products leverages its integrated farm-to-shelf infrastructure across the UAE to anchor premium positioning in fresh and fermented segments. Camelicious competes through specialized pharmaceutical-grade powder lines that target clinical nutrition channels. Desert Farms Inc. navigates North American regulatory complexity by sustaining direct-to-consumer subscription models that bypass conventional retail gatekeepers.
Technical Definition and Segment Structure
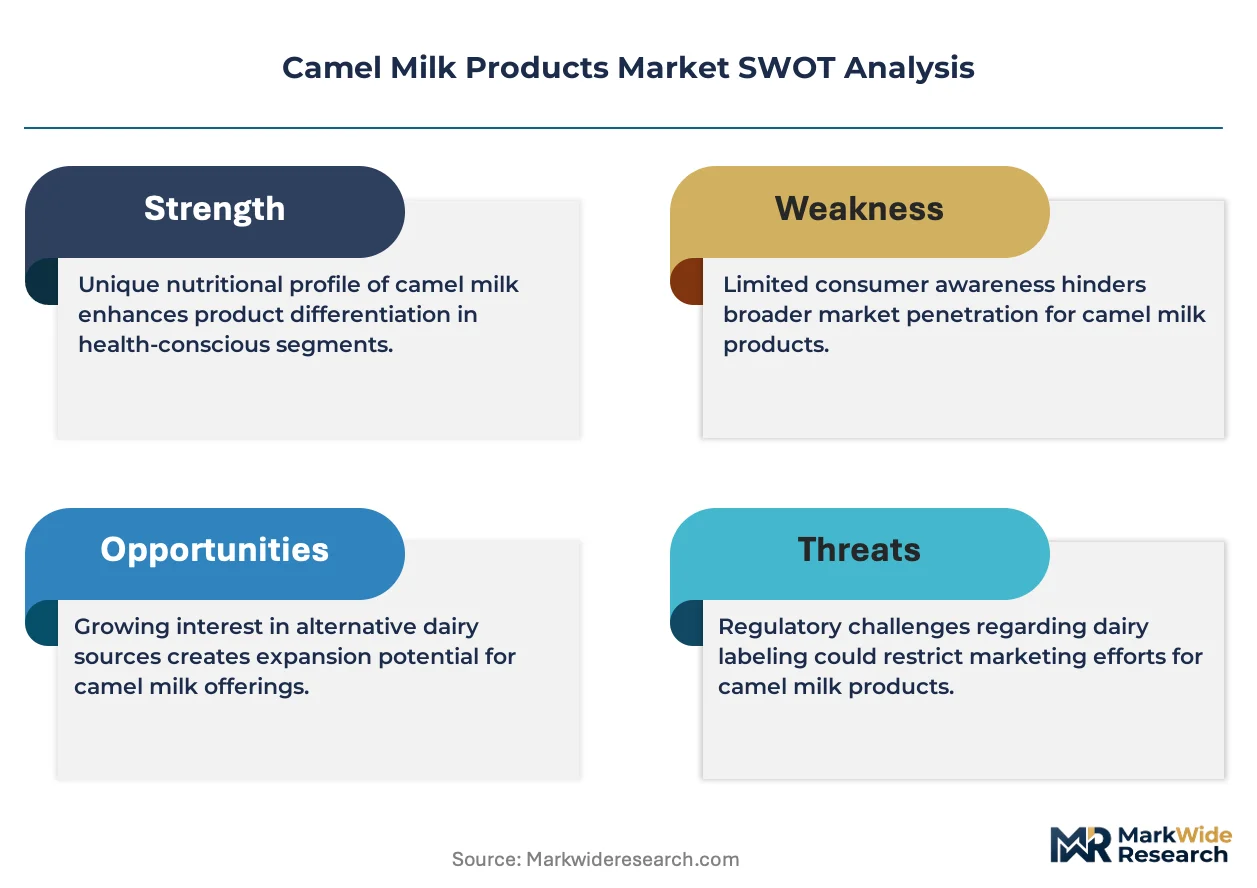
Camel milk products encompass dairy derivatives sourced from Camelus dromedarius and Camelus bactrianus species, characterized by lower lactose content, elevated insulin-like protein fractions, and vitamin C concentrations approximately threefold higher than bovine milk, serving functional nutrition, pharmaceutical excipient, and gourmet food applications. Powder formulations lead product type revenue contribution due to extended shelf stability and freight efficiency, while yogurt segments exhibit the fastest trajectory as probiotic positioning gains traction among digestive-health-focused buyers. Distribution through health stores captures disproportionate margin pools compared with supermarket channels, reflecting premium pricing power and educated consumer self-selection.
Regulatory Framework and Outlook
The UAE's Ministry of Climate Change and Environment, India's FSSAI, and the European Food Safety Authority collectively shape market access through divergent novel food approval pathways, hygiene mandates, and labeling requirements that dictate cross-border shipment viability. EFSA's persistent evaluation of camel milk protein allergenicity constrains European launch timelines for new entrants. Stakeholders must monitor harmonization momentum between Gulf standards bodies and Codex Alimentarius frameworks to anticipate export eligibility shifts.
Market Dynamics
The camel milk products market pivots on the tension between heritage supply chains rooted in Bedouin pastoral traditions and industrial-scale dairy infrastructure demanding standardized volume, quality certification, and cold-chain reliability for export eligibility.
Growth Catalysts
- Lactose-intolerant consumer migration:Functional nutrition buyers in North America and Europe are displacing conventional dairy with camel milk powders, drawn by insulin-like protein fractions and reduced allergenicity profiles.
- FSSAI novel food pathway clarification:India's evolving standards for camel milk derivatives are compressing registration timelines, enabling faster commercialization of fermented products and infant nutrition formulations.
- Lyophilization technology maturation:Spray-drying and freeze-drying equipment suppliers are delivering pharmaceutical-grade powder consistency, extending shelf stability from weeks to years and unlocking freight economics for distant markets.
Market Restraints
- Raw milk supply concentration:Over 80% of global camel milk production concentrates across Somalia, Saudi Arabia, and the UAE, exposing processors to climate volatility and pastoral labor shortages.
- EFSA novel food evaluation timelines:European protein allergenicity studies extend approval cycles to 18-24 months, freezing out small entrants lacking capital reserves for prolonged regulatory incubation.
- Bovine dairy price compression:Industrial cow milk oversupply in Europe and Oceania creates persistent substitution pressure at the mass-market tier, constraining camel milk to premium positioning.
Strategic Opportunities
- Clinical nutrition channel penetration:Hospital and long-term care facilities in Germany and France are piloting camel milk protocols for diabetic and immunocompromised patients, creating reimbursable prescription pathways.
- Probiotic yogurt line extensions:Digestive health positioning aligns with gut microbiome research momentum, enabling margin capture in pharmacy and health store channels distinct from commodity dairy.
- UAE-Saudi Codex harmonization:Gulf standards bodies are aligning with international food safety frameworks, anticipating mutual recognition agreements that would streamline cross-border shipment certification.
Industry Challenges
- Veterinary and dairy science talent scarcity:Camel husbandry expertise resides primarily in nomadic communities, while industrial dairy operations require veterinarians trained in camelid physiology and mastitis management protocols.
- Batch-to-batch protein standardization:Seasonal forage variation and hydration cycles create compositional inconsistency that pharmaceutical and infant nutrition buyers reject without costly blending and testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camel Milk Products Market |
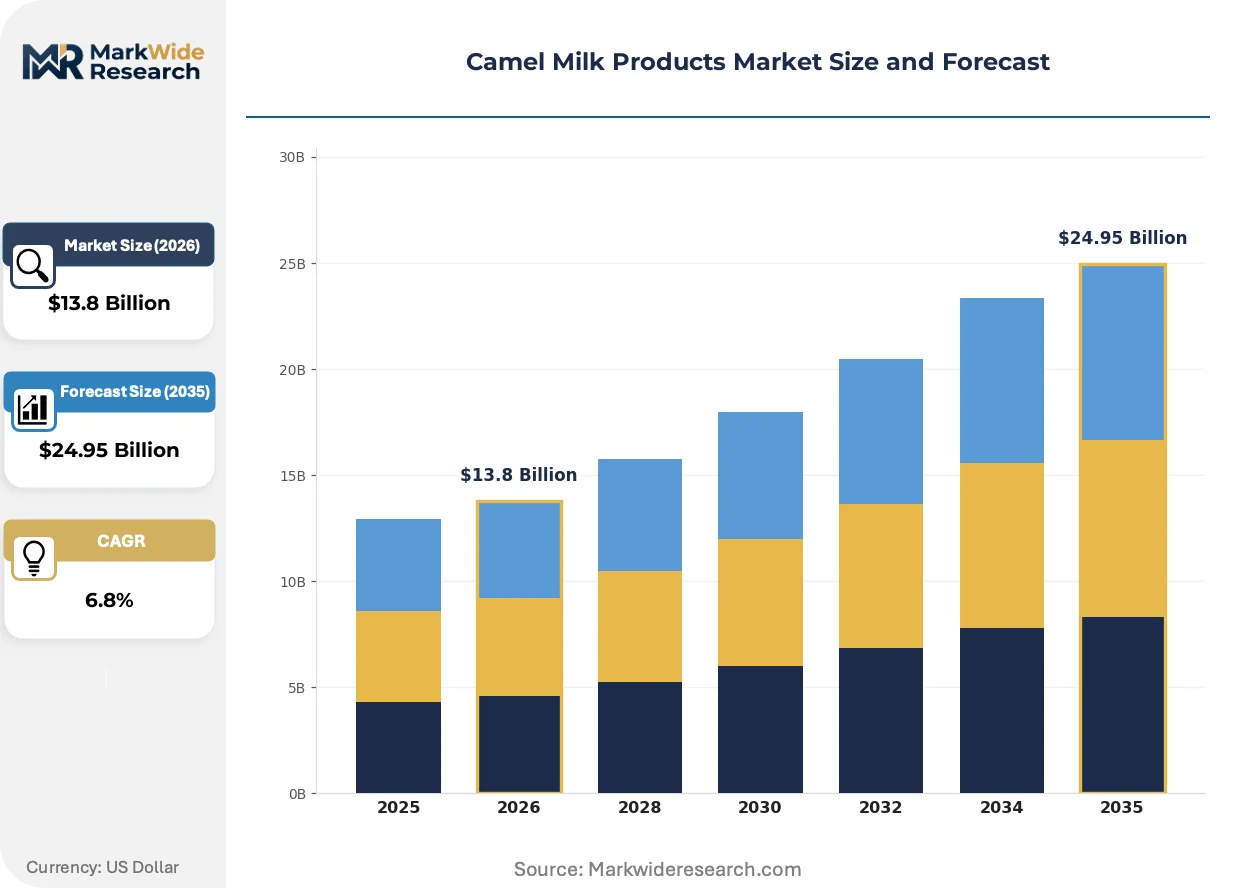
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Cheese, Yogurt, Ice Cream End User: Retail Consumers, Health Enthusiasts, Restaurants, Food Manufacturers Distribution Channel: Online Stores, Supermarkets, Health Stores, Specialty Shops Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Emirates Industry for Camel Milk and Products, QCamel, Camelicious, Camel Dairy Farm Smits, Gujarat Cooperative Milk Marketing Federation Ltd., Aadvik Foods and Products Pvt. Ltd., Desert Farms Inc., Dandaragan Camel Dairies Pty Ltd., Al Ain Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camel Milk Products Market Strategic Shifts & Innovations
Processing technology and regulatory science are converging to transform camel milk from a regional staple into a globally tradable functional ingredient, with preservation methods and certification protocols determining competitive access.
Lyophilization equipment is miniaturizing from industrial-scale spray towers to modular units deployable at collection points, enabling herder cooperatives in Rajasthan and Rajasthan to produce export-grade powder without centralized factory infrastructure. Smallholder dairy associations in India are piloting solar-powered mobile units, compressing spoilage losses and capturing value previously ceded to middlemen. This distributed processing architecture is fragmenting supply chain control and lowering capital barriers for new market entrants.
EFSA's ongoing evaluation of camel milk protein immunogenicity is reshaping European launch strategies, forcing applicants to commission dedicated clinical studies rather than relying on compositional equivalence arguments. The regulatory burden falls heaviest on powdered infant formula aspirants, who must demonstrate amino acid bioavailability parity with bovine benchmarks. German and Dutch dairy conglomerates are responding by acquiring Gulf-based processors with existing novel food dossiers, bypassing de novo approval timelines.
Subscription-based direct-to-consumer channels are displacing traditional retail gatekeepers in North American markets, with buyers self-selecting through online health platforms and bypassing supermarket slotting fees that erode margins. This channel shift concentrates customer data ownership with brands and enables personalized formulation offerings based on metabolic profiling. California and Texas health-conscious demographics are driving volume, with recurring purchase patterns stabilizing revenue forecasting for vertically integrated suppliers.
Camel Milk Products Market Segmentation
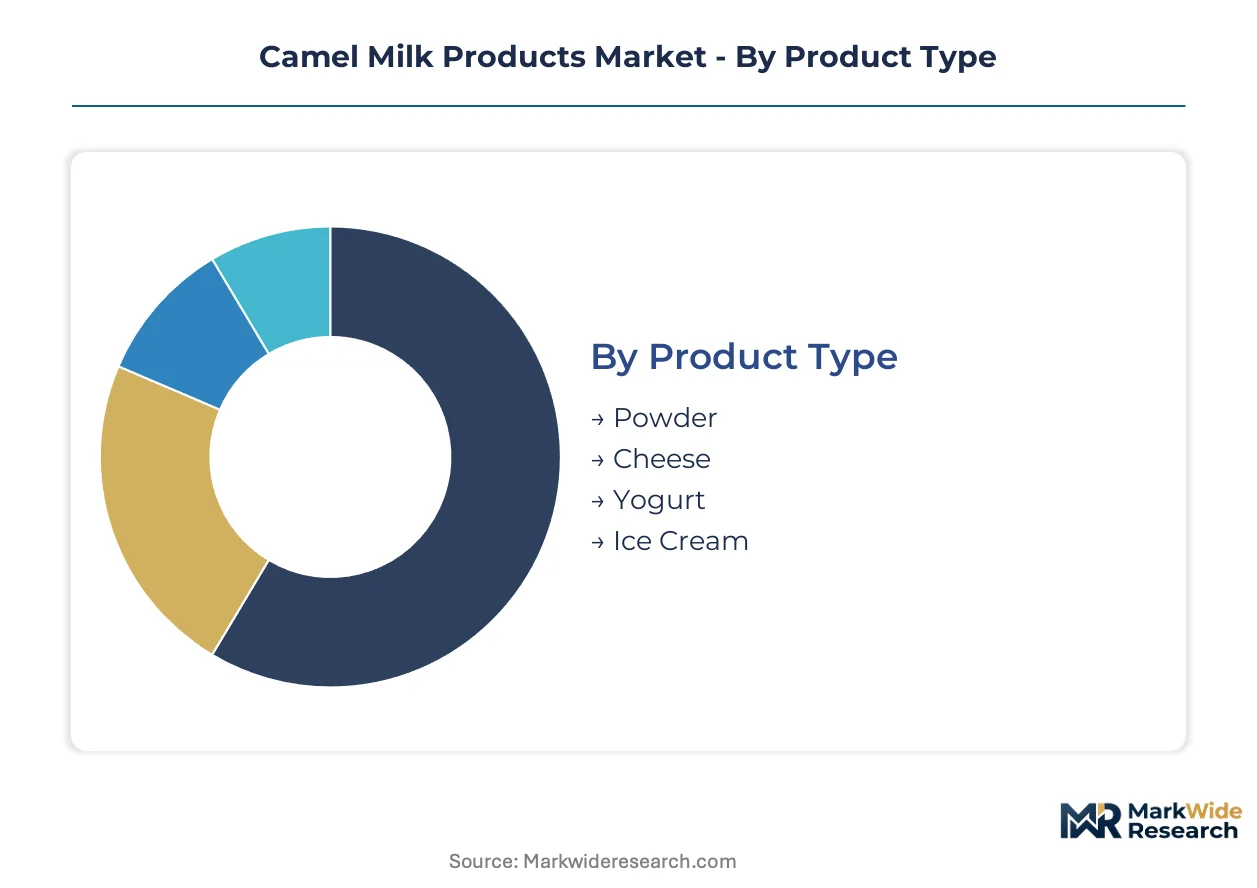
Camel milk product segmentation reveals divergent commercial logics across preservation formats, buyer sophistication levels, and channel access tiers. Powder formulations dominate export economics while fresh derivatives anchor domestic consumption patterns in producer countries.
Product Type:
Domestic markets across the UAE and Saudi Arabia favor fresh and fermented derivatives, whereas powder and freeze-dried formats drive cross-border shipment volumes to Europe and North America.
- Powder:Spray-dried and lyophilized concentrates achieve pharmaceutical-grade protein stability with shelf lives extending to 24 months. German and Dutch clinical nutrition channels are absorbing bulk powder shipments for diabetic patient protocols, constrained only by EFSA novel food dossier completion timelines.
- Yogurt:Fermented derivatives with live probiotic cultures are capturing digestive-health positioning in pharmacy and health store channels. French and Italian buyers are driving volume for gut microbiome-focused SKUs, bypassing commodity dairy price compression through premium functional claims.
- Cheese:Soft and aged varieties from UAE processors serve gourmet foodservice in London and Paris.
- Ice Cream:Premium dessert positioning targets lactose-intolerant consumers in California and Texas metro areas.
Powder commands the established base. The steepest expansion runs through yogurt.
End User:
Cost tier stratification separates mass-market retail from specialized clinical and foodservice procurement with divergent price elasticity and certification requirements.
- Health Enthusiasts:Functionally literate buyers self-select through online platforms and subscription models, prioritizing insulin-like protein content and reduced allergenicity profiles over price. California and Texas demographics are stabilizing recurring revenue for direct-to-consumer brands.
- Food Manufacturers:Industrial buyers in Germany and France integrate camel milk powder into infant formula and clinical nutrition blends, demanding batch-to-batch protein standardization and amino acid bioavailability documentation that raises supplier compliance costs.
- Retail Consumers:Supermarket shoppers in Gulf states treat fresh camel milk as heritage staple rather than functional purchase.
- Restaurants:Dubai and Riyadh fine-dining establishments feature camel milk derivatives as regional authenticity markers.
Health enthusiasts anchor premium pricing power. Food manufacturers are scaling fastest as novel food approvals mature.
Distribution Channel:
Channel selection determines margin capture, with health stores and online platforms preserving pricing power that supermarket slotting fees erode.
- Health Stores:Educated consumer self-selection enables 40-60% price premiums over conventional retail. German pharmacy chains and French parapharmacies are piloting dedicated camel milk sections for diabetic and immunocompromised patient segments.
- Online Stores:Direct-to-consumer subscriptions concentrate customer data ownership and enable personalized formulation based on metabolic profiling. North American platforms are displacing traditional retail gatekeepers by bypassing slotting fees and capturing full margin pools.
- Supermarkets:Gulf Cooperation Council chains dominate fresh milk volume with heritage brand recognition.
- Specialty Shops:Gourmet retailers in London and Paris curate artisanal cheese and ice cream selections.
Health stores defend the highest per-unit economics. Online channels are expanding most quickly through subscription retention models.
Packaging Type:
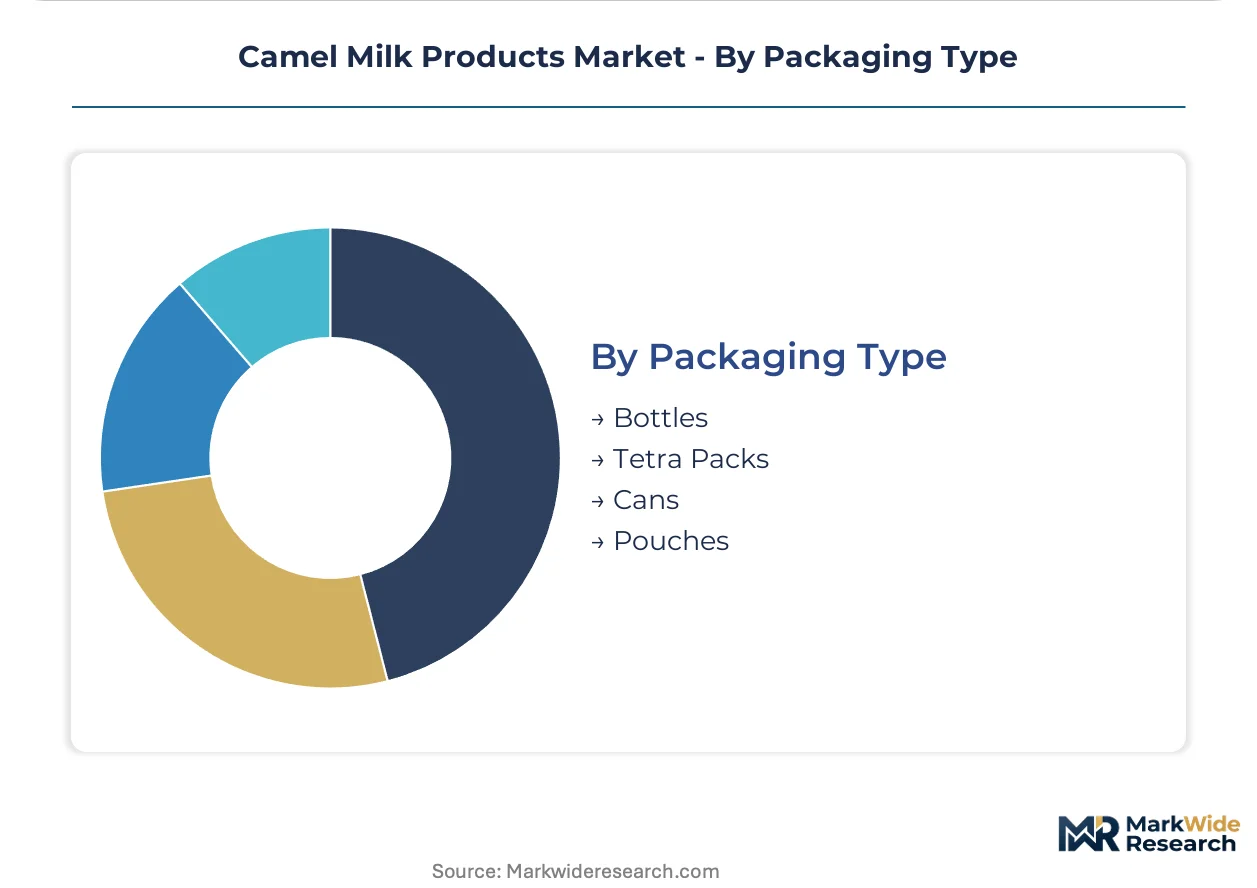
Packaging selection tracks product perishability and distribution distance, with shelf-stable formats enabling export eligibility that fresh packaging cannot support.
- Tetra Packs:Aseptic carton technology extends fresh milk shelf life to 6-9 months without refrigeration, unlocking supermarket distribution in European markets where cold-chain infrastructure gaps persist. UAE processors are prioritizing Tetra Pak lines for German and Dutch retail entry.
- Pouches:Flexible film packaging reduces freight weight and storage cube for powder shipments to North American direct-to-consumer channels. Rajasthan cooperatives are adopting pouch formats for solar-powered mobile processing units.
- Bottles:HDPE and glass containers dominate Gulf domestic fresh milk consumption with daily delivery logistics.
- Cans:Metal packaging serves military and institutional procurement with extreme durability requirements.
Tetra Packs hold the incumbent position for export-ready fresh derivatives. Pouches are climbing the fastest as distributed processing fragments supply chain control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port cold-chain infrastructure underwrites the UAE's role as the primary export gateway for camel milk derivatives bound for European and North American markets.
United Arab Emirates
Diabetic patient protocols in German clinics and heritage consumption in domestic households drive dual demand streams. MOCCAE hygiene mandates and novel food export certifications dictate cross-border shipment eligibility. Dubai's Al Ain industrial corridor hosts integrated farm-to-shelf operations processing fresh and fermented derivatives for Gulf retail and pharmaceutical-grade powders for export.
Saudi Arabia
Bedouin pastoral traditions sustain fresh milk consumption while Riyadh's health-conscious demographics adopt powder formats for functional nutrition. SFDA standards alignment with Codex Alimentarius frameworks is compressing registration timelines for fermented product exports. The Qassim region concentrates camel husbandry operations with modern dairy infrastructure bridging nomadic supply and industrial processing.
Germany
Clinical nutrition channels in Munich and Hamburg hospitals are piloting camel milk protocols for immunocompromised patients, creating reimbursable prescription pathways. BfR novel food evaluations and EFSA protein allergenicity studies extend approval cycles for new entrants. Bavaria's dairy technology cluster hosts lyophilization equipment suppliers serving Gulf processors seeking European market access.
India
Rajasthan's herder cooperatives and Gujarat's dairy federations are expanding powder production for domestic lactose-intolerant consumers and export markets. FSSAI novel food pathway clarification for camel milk derivatives is enabling faster commercialization of fermented products. The Kutch region hosts solar-powered mobile processing units capturing value previously lost to spoilage and middlemen.
United States
California and Texas health-conscious demographics are stabilizing recurring revenue for direct-to-consumer subscription brands bypassing retail gatekeepers. FDA novel food consultations and state-level dairy licensing create regulatory complexity that favors vertically integrated suppliers with compliance infrastructure. The Dallas-Fort Worth metro anchors distribution logistics for powder shipments reaching health store channels nationwide.
Camel Milk Products Market Key Industry Players
Listed leaders compete with private specialists across regulatory compliance capabilities and cold-chain infrastructure ownership. The vendor base fragments across Gulf-based integrated processors with heritage supply relationships, European clinical nutrition specialists with EFSA dossier expertise, and North American direct-to-consumer platforms with subscription retention models. Three archetypes dominate: farm-to-shelf integrators controlling raw milk supply, pharmaceutical-grade powder specialists targeting hospital channels, and digital-native brands bypassing retail slotting fees. Capacity expansion in lyophilization equipment and strategic partnerships for Codex harmonization represent the dominant competitive moves.
Within the integrated processor tier, Emirates Industry for Camel Milk and Products and Al Ain Farms exemplify Gulf-based operators with captive supply from desert husbandry operations and domestic retail distribution. Among specialty powder exporters, Camelicious occupies a position representing pharmaceutical-grade production capabilities targeting European clinical nutrition channels. At the direct-to-consumer vector, Desert Farms Inc. anchors North American subscription-based distribution, bypassing conventional retail infrastructure through health platform customer acquisition.
| Leading Market Players |
|---|
| Emirates Industry for Camel Milk and Products |
| QCamel |
| Camelicious |
| Camel Dairy Farm Smits |
| Gujarat Cooperative Milk Marketing Federation Ltd. |
| Aadvik Foods and Products Pvt. Ltd. |
| Desert Farms Inc. |
| Dandaragan Camel Dairies Pty Ltd. |
| Al Ain Farms |
| Others |
Cost & Logistics Intelligence
Industrial-scale lyophilization capacity in the UAE and Saudi Arabia generates cost advantages that compress price floors for pharmaceutical-grade powders while preserving premium tiers for small-batch artisanal producers. This scale concentration simultaneously anchors supply chain control among Gulf-based integrators and limits price competition at the quality-certified tier.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement contracts from direct-to-consumer subscription pricing. Three-tier pricing stratifies across pharmaceutical-grade powders, premium functional foods, and heritage fresh milk segments. Price differentiation hinges on EFSA novel food certification status and cold-chain reliability documentation. Pricing pressure stems from bovine dairy oversupply in European mass-market tiers, though clinical nutrition channels retain inelastic demand. Food manufacturers exhibit highest price sensitivity due to batch standardization requirements, while health enthusiasts absorb premiums for insulin-like protein content transparency.
Supply Chain Analysis
Jebel Ali Port container availability and Red Sea trade lane congestion intermittently elevate inbound logistics costs for European-bound shipments. Raw milk supply draws from Somalia, Saudi Arabia, and the UAE, with over 80% of global production concentrated across these three markets. Processing depends on imported lyophilization equipment from Germany and the Netherlands, plus aseptic packaging materials from Tetra Pak's European facilities. Single-source vulnerability concentrates in Gulf-based cold-chain infrastructure for export eligibility. Distribution runs through direct-to-consumer platforms in North America and pharmacy chains in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camel milk products occupy an early-cycle expansion phase, with FSSAI pathway clarification in India and EFSA dossier maturation in Europe accelerating legitimate market entry beyond heritage consumption bases.
For Market Incumbents: Secure captive supply agreements with Rajasthan herder cooperatives and Qassim pastoral associations before novel food approvals trigger feedstock competition. Invest in batch-to-batch protein standardization infrastructure to defend pharmaceutical-grade positioning against Dutch and German dairy conglomerates acquiring Gulf processors. Prioritize Codex Alimentarius harmonization advocacy through UAE-Saudi standards body alignment. For New Entrants and Emerging Players: Differentiate on probiotic yogurt formulations targeting French and Italian pharmacy channels, where digestive health positioning escapes commodity dairy price compression. Target California and Texas direct-to-consumer subscriptions with metabolic profiling personalization. Penetrate through online health platforms bypassing supermarket slotting fees that erode margins for vertically integrated incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription brands with vertically integrated supply chains. Long-term viability favors processors with existing EFSA novel food dossiers and captive raw milk supply from established husbandry operations. Watch for EFSA protein allergenicity study completion as inflection signal for European clinical nutrition channel scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | UAE processors deploying German-sourced equipment capture pharmaceutical-grade powder export eligibility. |
| Novel Food Dossier Acquisition | European dairy conglomerates bypass 18-24 month EFSA timelines by acquiring Gulf-based processors with existing approvals. |
| Direct-to-Consumer Platform Launch | Subscription models in California and Texas concentrate customer data ownership and stabilize revenue forecasting. |
| Probiotic Line Extension | French and Italian pharmacy channels absorb gut microbiome-positioned SKUs at 40-60% premiums over retail. |
| Solar-Powered Mobile Processing Deployment | Rajasthan cooperatives reduce spoilage losses and capture value previously ceded to middlemen through distributed architecture. |
Research Approach
Operator-level perspectives from camel dairy farm managers, lyophilization equipment suppliers, FSSAI regulatory affairs specialists, and German hospital procurement committees anchored the qualitative base. Primary interviews with Emirates Industry for Camel Milk and Products processing directors and Camelicious export managers combined with secondary validation from EFSA novel food register entries, FSSAI notification databases, UAE Ministry of Climate Change and Environment hygiene mandates, and Gulf customs trade records. Bottom-up volume modeling from herder cooperative production data triangulated against top-down consumption estimates from pharmacy channel audits and direct-to-consumer platform analytics.
Sensitivity analysis across regulatory approval timelines, raw milk supply volatility, and lyophilization equipment lead times informed scenario-weighted outputs over the projection horizon. Segmentation dimensions modeled include preservation format, buyer sophistication tier, distribution channel margin structure, and regional regulatory cluster. CAGRs derived from historical volume trajectories in Gulf domestic markets and penetration rate assumptions for European clinical nutrition channels. Industry-specific inputs incorporated FSSAI registration completion rates and EFSA protein allergenicity study progression status.
The analysis sits within stated boundaries; outcomes outside EFSA novel food approval progression, FSSAI pathway stability, or Gulf cold-chain infrastructure expansion would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization momentum and herder cooperative processing adoption. Recalibration cycles align with material shifts in EFSA evaluation timelines, Codex Alimentarius alignment progress, and solar-powered mobile unit deployment scale in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
On-The-Go Yoghurt Market