
 Coconut Milk Market | 2026-2036
Coconut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Milk Market Intelligence
A shift from multi-source ingredient procurement to dedicated supplier partnerships is consolidating supply chains around major processors. This trend favors companies with extensive agricultural networks and processing scale. Danone S.A. leverages its global distribution to push plant-based dairy alternatives into mainstream retail channels. Meanwhile, Theppadungporn Coconut Co., Ltd. specializes in branded coconut products, controlling quality from plantation to packaging.
Coconut milk is a stable oil-in-water emulsion derived from grating and pressing mature coconut flesh. Its quality is often defined by fat content, which distinguishes light coconut milk from richer regular and creamed versions. The product serves as a foundational ingredient in culinary dishes and as a base for dairy-free beverages. Organic coconut milk represents a fast-growing product type, while Tetra Pak packaging leads the ready-to-drink beverage segment due to its shelf-stability benefits.
In the United States, the FDA's food labeling regulations govern allergen declarations and nutritional information for coconut milk products. Concurrently, European Union food safety laws, overseen by bodies like the EFSA, set strict limits on contaminants and approve food additives. Stakeholders must now focus on securing certified supply chains to meet evolving consumer expectations for transparency and sustainability.
Market Dynamics
The market's central dynamic is the consumer-led transition towards plant-based diets, particularly in developed economies. This shift, combined with a strong preference for clean-label and minimally processed foods, places coconut milk at the intersection of health and convenience trends.
Growth Catalysts
- UHT Processing Innovation:Ultra-High Temperature processing extends shelf life, enabling broader distribution of ready-to-drink beverages and reducing spoilage costs for food service operators.
- Plant-Based Diet Adoption:The consumer shift to plant-based diets, especially in the United States, positions coconut milk as a key ingredient in dairy-free yogurts and beverages.
- Organic Certification Demand:Consumer preference for certified organic products supports a premium segment, linking the certification to sustainable farming and clean-label attributes.
Market Restraints
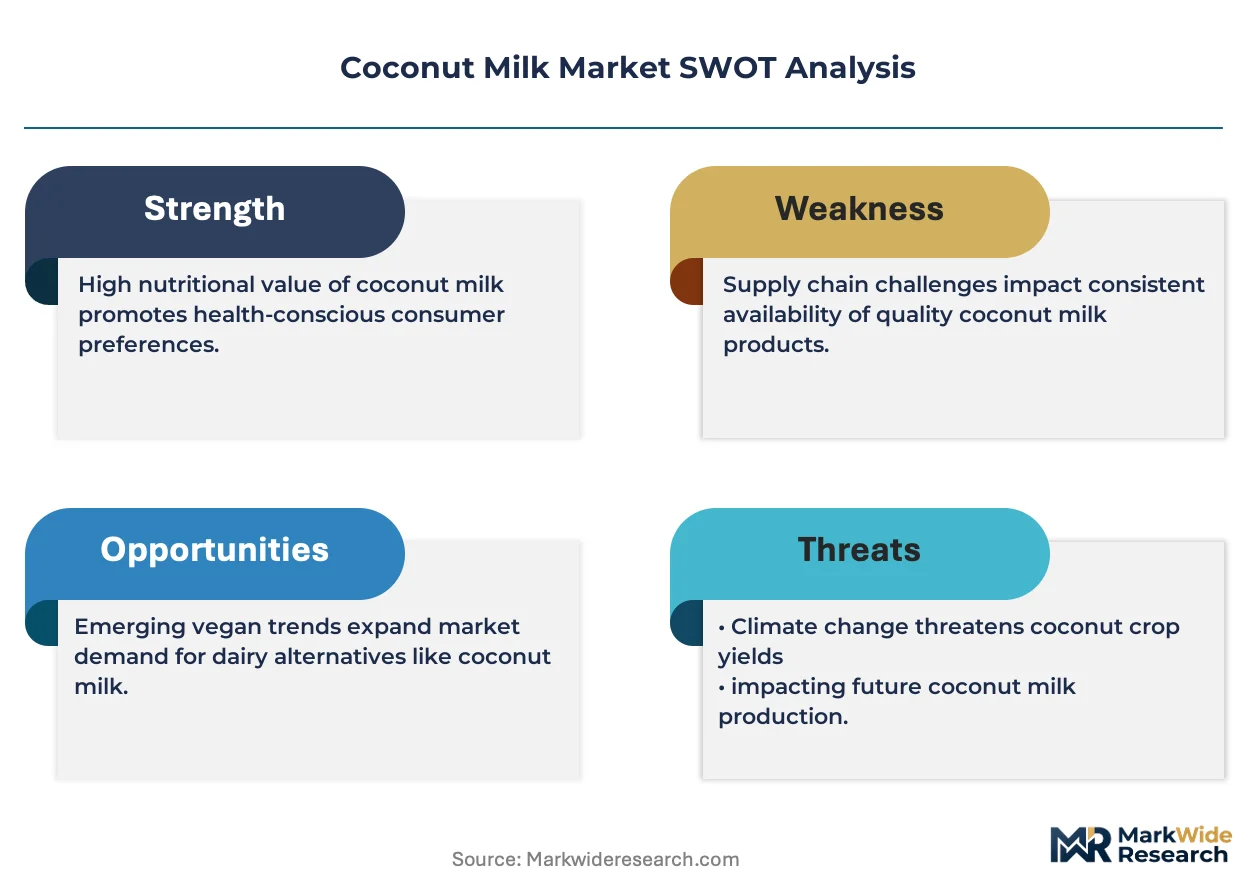
- Supply Chain Vulnerability:Production concentration in Southeast Asia exposes the supply chain to climate-related disruptions like typhoons, creating price and volume volatility for processors.
- Competition from Alternatives:The market faces intense competition from other plant-based milks, including almond, soy, and oat, which offer different nutritional profiles and price points.
- Negative Health Perceptions:The high saturated fat content of traditional coconut milk acts as a purchasing barrier for some health-conscious consumers, despite its plant-based origin.
Strategic Opportunities
- Functional Fortification:Fortifying products with vitamins D and B12 creates functional beverages that appeal to consumers seeking enhanced nutritional benefits from their dairy alternatives.
- Food Service Channel Expansion:Penetrating coffee chains and fast-casual restaurants in North America offers a significant volume opportunity beyond traditional retail channels.
- Emerging Market Entry:Entering Latin American markets like Brazil, where plant-based diets are gaining traction, presents a growth avenue for branded and private-label lines.
Industry Challenges
- Regulatory Compliance Complexity:Stakeholders face challenges in navigating divergent food labeling regulations for allergens and nutritional information between jurisdictions like the FDA in the US and EFSA in the EU.
- Supply Chain Certification:Establishing and verifying certified sustainable supply chains is a significant operational hurdle, requiring investment in traceability systems to meet retailer and consumer demands for transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Milk Market |
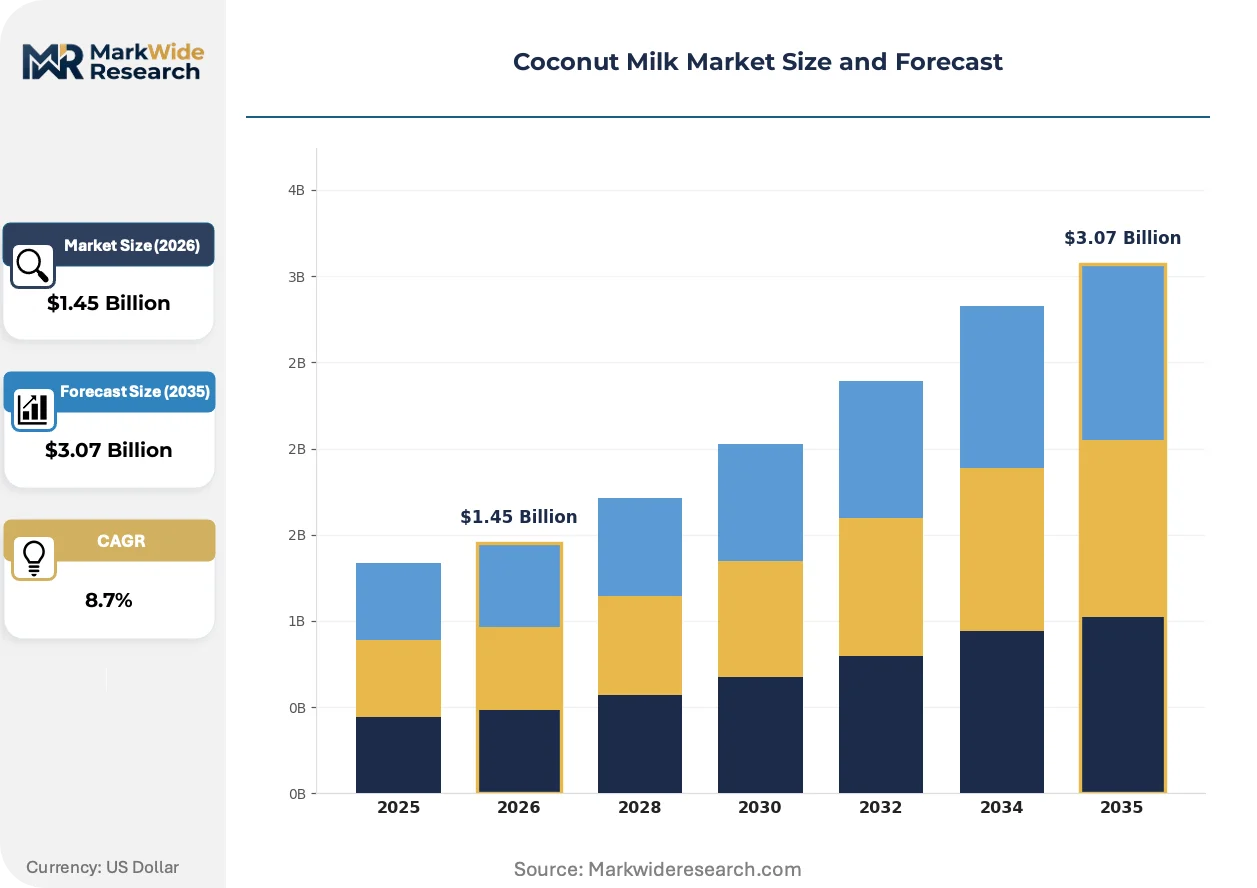
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Coconut Milk, Light Coconut Milk, Creamed Coconut Milk, Organic Coconut Milk, Flavored Coconut Milk Application: Beverages, Culinary Use, Personal Care Products, Pharmaceuticals, Dairy Alternatives Packaging Type: Tetra Pak, Cans, Bottles, Cartons, Pouches End User: Food Service Operators, Retail Consumers, Cosmetics Manufacturers, Nutraceutical Companies, Confectionery Producers |
| Companies Covered | Thai Coconut Public Company Limited, Theppadungporn Coconut Co., Ltd., Goya Foods, Inc., Danone S.A., McCormick & Company, Incorporated, Axelum Resources Corp., Sambu Group, Vita Coco, Chaokoh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Milk Market Strategic Shifts & Innovations
Innovations in processing and packaging are converging with clean-label consumer demands to redefine product value. This dynamic pushes manufacturers to balance extended shelf life and sensory attributes with minimalist ingredient lists and sustainable sourcing claims.
Ultra-High Temperature (UHT) processing is a key sterilization technology that ensures product safety and stability without refrigeration. Food and beverage manufacturers are widely adopting UHT systems for dairy-alternative beverages. This technology is expanding into shelf-stable, ready-to-drink formats, allowing coconut milk to penetrate mainstream retail grocery aisles previously dominated by traditional dairy products.
European Union food safety laws, overseen by the EFSA, are setting stricter limits on contaminants and mandating clearer allergen labeling. These regulations force processors to enhance quality control measures from raw material sourcing to final packaging. The beverage segment, particularly products in Tetra Pak cartons marketed to families, is most affected, requiring rigorous compliance to maintain market access.
Consumer purchasing criteria are evolving from a focus on basic ingredients to a preference for brands with transparent and certified supply chains. This shift disrupts traditional private-label strategies, forcing retailers to partner with suppliers who can provide verifiable sustainability or organic certifications. This behavior is most prominent among retail consumers in the United States, where clean-label claims heavily influence purchasing decisions.
Coconut Milk Market Segmentation
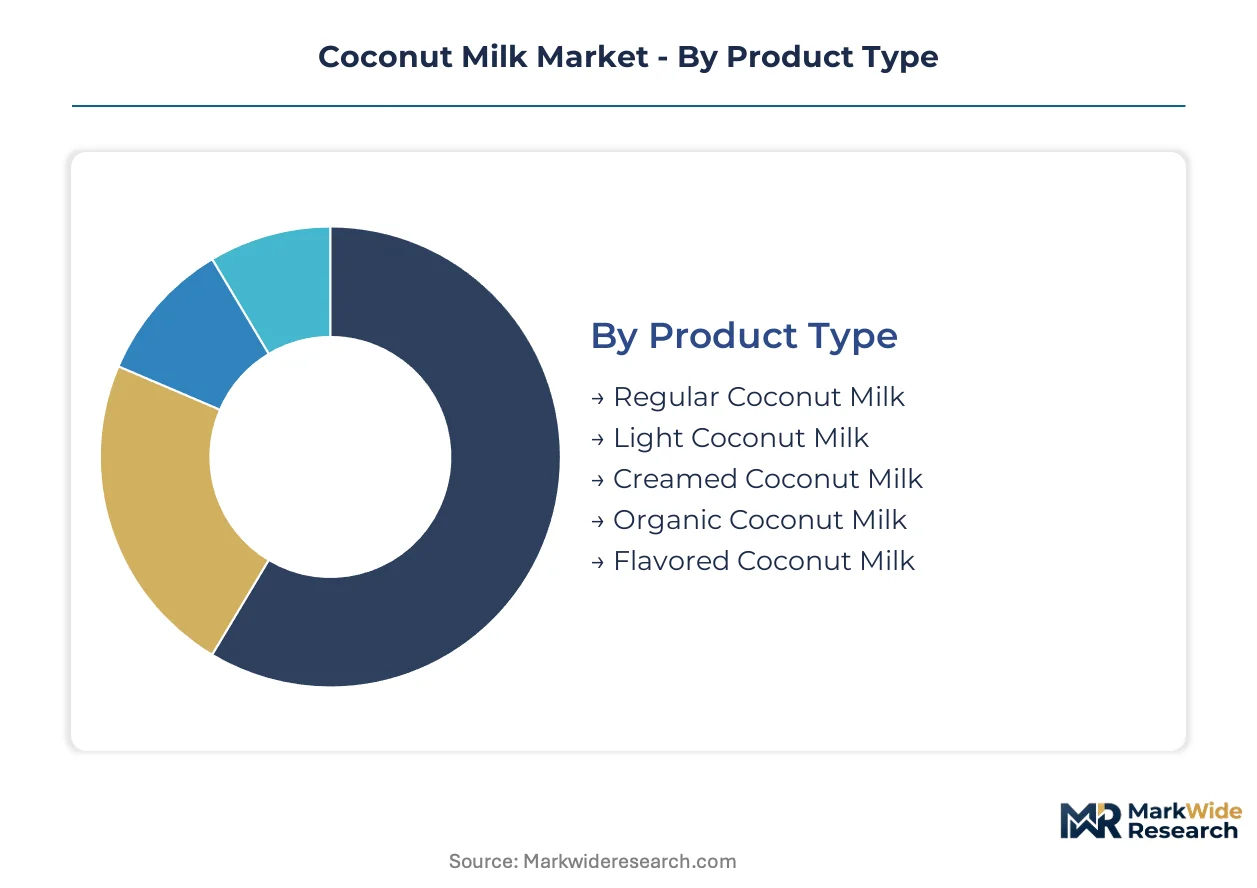
The coconut milk market exhibits distinct segmentation across various dimensions, reflecting its versatility and broad consumer appeal. Understanding these segments is crucial for stakeholders to identify specific growth vectors and tailor product development strategies effectively. Each category highlights unique demand drivers and operational complexities within the industry.
Product Type:
The capital intensity across coconut milk product types varies significantly, with specialized processing lines dictating investment profiles for manufacturers.
- Organic Coconut Milk:This product type adheres to strict organic farming standards, ensuring no synthetic pesticides or fertilizers are used in cultivation. Demand concentrates in the United States, driven by consumer preference for clean-label and sustainably sourced food items.
- Regular Coconut Milk:Characterized by its traditional fat content, regular coconut milk is a staple ingredient in many culinary traditions globally. Demand is widespread across all geographies, serving as a foundational component in both home cooking and commercial food preparation.
- Light Coconut Milk:This version contains a reduced fat content compared to its regular counterpart, appealing to health-conscious consumers.
- Creamed Coconut Milk:A thicker, more concentrated form of coconut milk, often used for richer textures in desserts and sauces.
- Flavored Coconut Milk:These products incorporate natural or artificial flavorings, expanding their appeal as ready-to-drink beverages or culinary enhancements.
Regular Coconut Milk absorbs the bulk of installed capacity; Organic Coconut Milk is expanding most quickly.
Application:
Volume dynamics within coconut milk applications reflect diverse consumer habits and industrial scale requirements.
- Beverages:Coconut milk serves as a key ingredient in dairy-free drinks, smoothies, and ready-to-drink coffee alternatives, often packaged in Tetra Pak. Demand concentrates in North America, driven by the plant-based diet trend and convenience.
- Culinary Use:This application encompasses its use in cooking, baking, and as a base for sauces and curries across various cuisines. Demand is significant across Southeast Asia and Europe, where it is an integral part of traditional and modern recipes.
- Dairy Alternatives:Coconut milk forms the basis for dairy-free yogurts, cheeses, and ice creams, catering to lactose-intolerant or vegan consumers.
- Personal Care Products:Its moisturizing properties make coconut milk a popular ingredient in lotions, shampoos, and soaps for cosmetic manufacturers.
- Pharmaceuticals:Coconut milk extracts find niche applications in certain pharmaceutical formulations, valued for specific nutritional components.
Market expansion is primarily driven by Beverages, while Pharmaceuticals represents a specialized but growing niche.
Packaging Type:
Customer preferences and distribution channel requirements heavily influence the choice of packaging type for coconut milk products.
- Tetra Pak:This aseptic packaging ensures extended shelf life without refrigeration, making it ideal for ready-to-drink coconut milk beverages. Demand is high in the United States for retail consumers seeking convenience and longevity.
- Cans:Traditional metal cans offer robust protection and long-term storage, commonly used for culinary-grade coconut milk. Demand remains strong in Asian markets, where it is a household staple for cooking.
- Bottles:Glass or plastic bottles are utilized for premium or smaller-batch coconut milk products, often for refrigerated items.
- Cartons:Similar to Tetra Pak, cartons provide shelf-stable solutions, particularly for multi-serve beverage formats.
- Pouches:Flexible pouches offer convenience and reduced material waste, catering to single-serve or travel-friendly options.
The convenience offered by Tetra Pak supports its widespread adoption, but Cans offer cost efficiencies for bulk consumers.
End User:
Margin structures for coconut milk products vary considerably based on the end-user segment, reflecting different value-add propositions and purchasing power.
- Retail Consumers:Individual shoppers purchasing coconut milk for home consumption through supermarkets and online channels. Their purchasing decisions are influenced by brand, organic certifications, and packaging size in the United States.
- Food Service Operators:Restaurants, cafes, and institutional kitchens using coconut milk as an ingredient in their menu offerings. These operators prioritize consistent supply, bulk packaging, and competitive pricing for their North American operations.
- Cosmetics Manufacturers:Companies formulating personal care products that incorporate coconut milk for its natural properties.
- Nutraceutical Companies:Businesses developing health supplements and functional foods using specific components derived from coconut milk.
- Confectionery Producers:Manufacturers creating sweets, chocolates, and desserts where coconut milk provides flavor and texture.
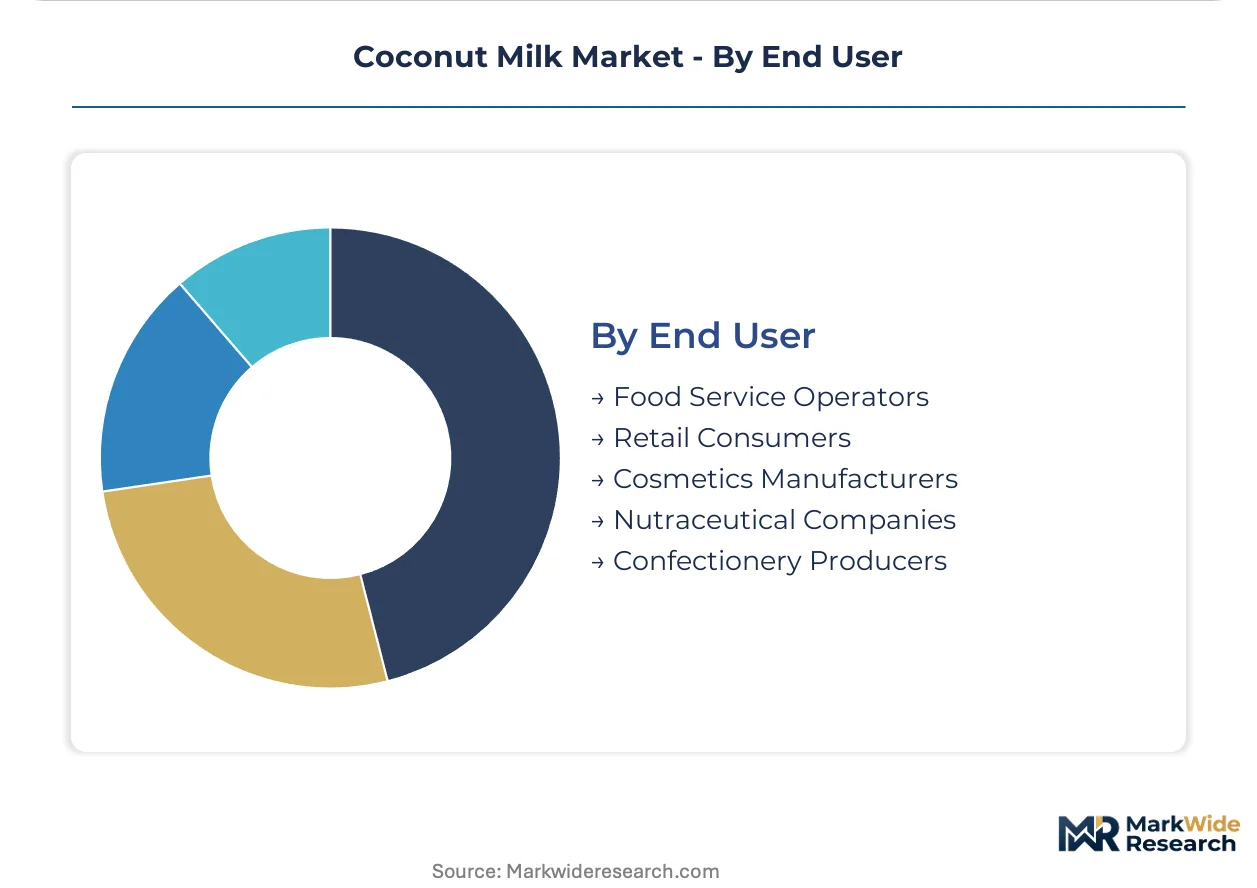
Retail Consumers represent the largest direct consumption segment, with Nutraceutical Companies seeking specialized formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in developed economies drives the global coconut milk market, especially within the plant-based dairy alternatives sector. Consumer shifts towards plant-based diets, particularly in the United States, underpin this growth. Regulatory frameworks in key regions also shape market access and product formulation, influencing trade flows and product innovation.
United States
Consumer preference for clean-label and plant-based foods drives significant demand for coconut milk products in the United States. The FDA's food labeling regulations mandate clear allergen and nutritional information, influencing product development. California and New York metro areas show high retail consumer uptake for dairy alternatives and organic options.
Thailand
Strong culinary traditions and a robust export industry fuel coconut milk consumption and production in Thailand. The Thai Ministry of Agriculture and Cooperatives oversees quality standards for coconut cultivation and processing, ensuring product integrity. Bangkok serves as a major processing and export hub for branded coconut products destined for international markets.
Germany
European consumers prioritize sustainable sourcing and organic certifications, boosting demand for coconut milk in Germany's retail sector. European Union food safety laws, enforced by the EFSA, set strict limits on contaminants in imported food products. The Rhine-Ruhr metropolitan region demonstrates strong retail sales for plant-based beverages and culinary ingredients.
Brazil
Growing interest in plant-based diets and health-conscious consumer trends stimulate market expansion for coconut milk in Brazil. ANVISA, the country's health surveillance agency, regulates food additives and labeling for dairy alternative products, ensuring consumer safety. São Paulo acts as a primary distribution and consumption center for new beverage formats and culinary applications.
Coconut Milk Market Key Industry Players
Supply chain consolidation through strategic partnerships dominates the current landscape as major processors seek efficiency and quality control. This shift from multi-source ingredient procurement to dedicated supplier relationships strengthens the position of integrated players. The market structure exhibits a blend of global food conglomerates and specialized regional players, each targeting distinct segments. Strategic archetypes include large-scale ingredient suppliers and branded consumer product manufacturers with extensive agricultural networks. Key competitive moves involve securing certified sustainable supply chains and expanding global distribution networks for plant-based offerings.
Within the global distribution archetype, Danone S.A. leverages its extensive reach to push plant-based dairy alternatives into mainstream retail channels across multiple continents. Theppadungporn Coconut Co., Ltd. exemplifies a specialized branded player, controlling quality from plantation to packaging for its diverse range of coconut products. Vita Coco occupies a position as a prominent branded beverage player, focusing on ready-to-drink formats for health-conscious consumers in North America and beyond. These companies demonstrate varied approaches to market penetration, from broad portfolio integration to focused product specialization and brand building.
| Leading Market Players |
|---|
| Thai Coconut Public Company Limited |
| Theppadungporn Coconut Co., Ltd. |
| Goya Foods, Inc. |
| Danone S.A. |
| McCormick & Company, Incorporated |
| Axelum Resources Corp. |
| Sambu Group |
| Vita Coco |
| Chaokoh |
| Others |
Cost & Logistics Intelligence
Captive supply strategies by major processors anchor both the supply position and the pricing power within the coconut milk market. This approach reduces reliance on volatile spot markets and secures consistent raw material quality for branded products.
Pricing Analysis
Pricing for coconut milk products bundles specific attributes like organic certification and clean-label verification, influencing consumer choice. Transactional per-unit pricing with volume discounts dominates the market. Organic certification level and packaging format are key differentiation drivers. Pricing softness stems from intense competition from alternative plant-based milks. Food service operators are highly price-sensitive, while retail consumers for organic products exhibit lower sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with production concentration in Southeast Asia, particularly Thailand, exposing the supply chain to climate-related disruptions. The industry relies heavily on mature coconut flesh and specific packaging materials like Tetra Pak. Climate-related disruptions like typhoons represent a significant structural risk. Distribution runs through extensive retail networks and specialized food service channels globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coconut milk market is in a technology-transition phase, with UHT processing replacing traditional sterilization methods to extend shelf life and enable broader distribution.
For Market Incumbents:Acquire certified supply chain assets and advanced UHT processing capabilities to mitigate climate-related disruptions and secure raw material quality. Consolidate agricultural networks to counter competition from alternative plant-based milks. Invest in traceability systems to meet evolving consumer expectations for transparency and sustainability. Expand global distribution networks for plant-based offerings to maintain market share against emerging brands.
For New Entrants and Emerging Players:European Union food safety laws, overseen by the EFSA, open a window for new entrants focusing on rigorous quality control. Target Latin American markets like Brazil for plant-based diet adoption, offering functional fortifications such as added vitamins D and B12. Penetrate the North American food service channel, particularly coffee chains, with shelf-stable ready-to-drink formats. Develop products with clean-label attributes to appeal to health-conscious consumers.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized branded players controlling quality from plantation to packaging. The market exhibits strong long-term viability driven by sustained plant-based diet adoption. Target branded consumer product manufacturers with established distribution networks and organic certifications for acquisition. The signal to watch is the increasing penetration of coconut milk into mainstream dairy-alternative categories beyond traditional culinary uses.
| Strategic Initiative | Industry Significance |
|---|---|
| Distribution Channel Expansion | Danone S.A. leverages global reach to push plant-based dairy alternatives into mainstream retail channels. |
| Product Line Diversification | Theppadungporn Coconut Co., Ltd. controls quality from plantation to packaging for a diverse range of coconut products. |
| Sustainable Sourcing Certification | Consumer preference for certified organic products supports a premium segment in the United States. |
| UHT Processing Investment | Ultra-High Temperature processing extends shelf life, enabling broader distribution of ready-to-drink beverages. |
| Functional Fortification Development | Fortifying products with vitamins D and B12 creates functional beverages appealing to health-conscious consumers. |
Research Approach
Regulatory filings from the FDA, EFSA reports, and industry association publications formed the secondary backbone for this analysis. Primary interviews were conducted with food and beverage manufacturers, food service operators, and retail category managers across key geographies. This approach allowed for bottom-up data collection and top-down validation of market trends.
A bottom-up approach aggregated data from specific product types and end-user segments, while a top-down analysis validated overall market trends. The forecast framework segmented the market by product type, application, packaging type, end-user, and regional demand across the analysis window. Compound annual growth rates were derived from historical data and projected growth drivers, incorporating plant-based diet adoption rates and UHT processing penetration.
Caveats apply where unforeseen macroeconomic shifts or significant supply chain disruptions could materially shift the outlook. Forecasts reflect underlying assumptions regarding consumer behavior and technological adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Dairy-Free Spreads Market