
 Frozen Desserts Market | 2026-2036
Frozen Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Desserts Market Intelligence
Aftermarket service revenue from equipment maintenance and flavor formulation consulting is narrowing as manufacturers bring technical support in-house. Unilever sustains broad geographic coverage through its dual-brand strategy across premium and mass-market tiers. Nestlé dominates European retail freezers with its heritage dairy portfolio and direct-to-store distribution networks. General Mills competes in the North American novelty segment through licensed character partnerships and seasonal limited editions.
Frozen desserts comprise aerated, sweetened, and frozen dairy or non-dairy preparations typically containing 10-16% milkfat, 12-16% sweetener solids, and 0.2-0.5% stabilizer systems, produced via continuous freezing at -6°C to -3°C followed by hardening below -18°C for texture fixation and shelf-life extension. Ice cream occupies the largest margin pool across retail channels due to volume scale and brand loyalty, while gelato captures premium positioning in specialty shops with lower overrun and higher ingredient density. Frozen yogurt leverages health-positioning among adult consumers through live culture claims and reduced fat content, though its distribution concentrates in urban convenience networks.
FDA enforces standard of identity requirements for ice cream and frozen custard under 21 CFR 135, while EFSA evaluates novel ingredient approvals for plant-based fat replacers and alternative proteins entering European formulations. The EU Green Deal's packaging waste directives are forcing reformulation of multi-layer laminate wrappers toward mono-material recyclable structures. Stakeholders must monitor how dual carbon goals in China and evolving FSSAI labeling norms in India reshape export qualification requirements for multinational frozen dessert portfolios.
Market Dynamics
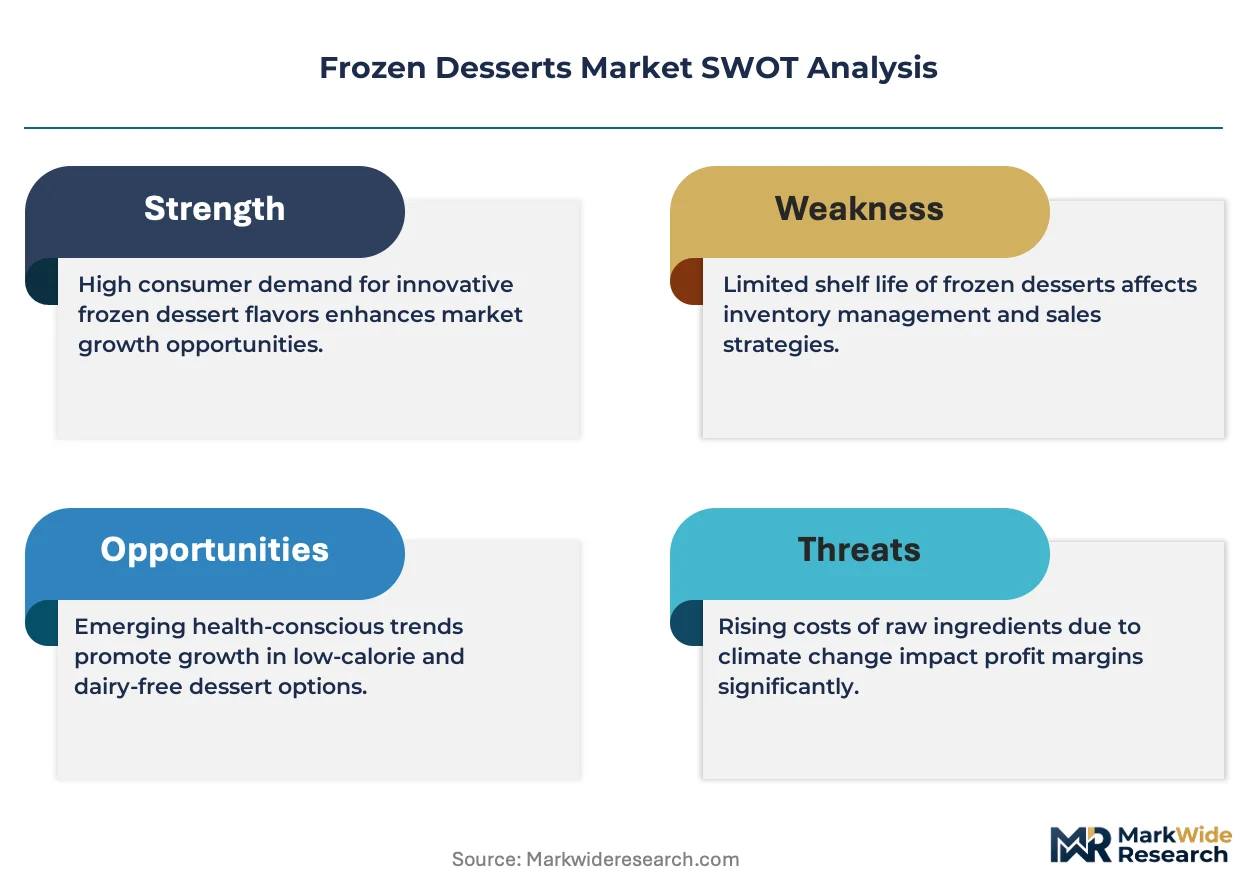
Clean-label reformulation mandates and FDA nutritional disclosure rules are compressing formulation cycles while forcing simultaneous investment in stabilizer alternatives and front-of-pack redesign. Manufacturers must balance heritage recipe integrity against evaporating permissible ingredient lists.
Growth Catalysts
- EU Green Deal packaging directives:Mono-material recyclable wrapper mandates are accelerating equipment replacement cycles across European production lines. Converters retrofit laminators to eliminate multi-layer structures.
- Artisanal gelato density:Lower overrun production methods command shelf-space premiums in United States specialty retail. Foodservice operators expand dedicated gelato cases in urban convenience networks.
- Live culture frozen yogurt:Reduced-fat positioning with probiotic claims captures adult health-conscious segments. Distribution concentrates in Japan's metropolitan convenience channels.
Market Restraints
- Dairy input cost volatility:Milkfat and milk solids concentrate price swings compress margin predictability for standard ice cream portfolios. Hedging instruments provide incomplete coverage for small-to-mid processors.
- Stabilizer supply concentration:Guar gum and locust bean gum sourcing clusters in India and Pakistan create single-origin vulnerability. Climate-induced crop variability amplifies formulation cost uncertainty.
- 21 CFR 135 identity standards:FDA's rigid compositional thresholds for ice cream and frozen custard block rapid plant-based line extensions. Reformulators must navigate lengthy petition processes for fat-replacer approvals.
Strategic Opportunities
- Functional ingredient claims:Adaptogen and protein-fortified frozen novelties open premium positioning in United States wellness-oriented retail. Brands leverage permissive supplement-labeling pathways distinct from standard food identity rules.
- Direct-to-freezer distribution:Bypassing traditional distributor layers lets manufacturers capture data on velocity and flavor performance. Nestlé's European retail freezer networks demonstrate captive route economics.
- FSSAI evolving norms:India's tightening labeling and fortification standards create first-mover advantage for compliant exporters. Multinational portfolios must requalify formulations for this expanding import market.
Industry Challenges
- Clean-label stabilizer R&D timelines:Replacing hydrocolloid systems with fruit pectin or starch alternatives demands 18-24 month texture-validation cycles. Sensory parity with legacy formulations remains elusive.
- Dual carbon compliance:China's energy-intensity targets and refrigeration emissions standards force cold-chain infrastructure reinvestment. Domestic manufacturers face stranded asset risk in legacy hardening tunnel equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Desserts Market |
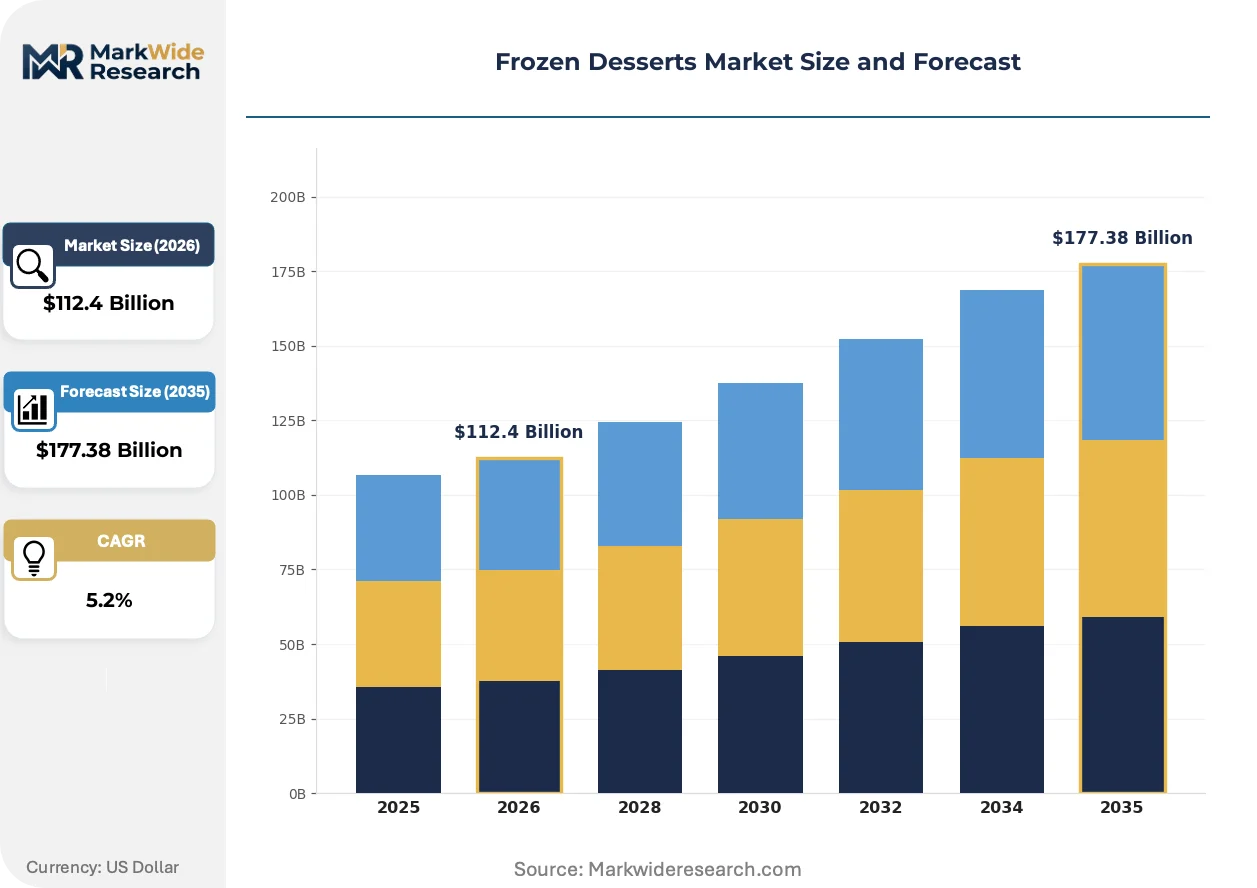
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $177.38 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream, Sorbet, Gelato, Frozen Yogurt, Sherbet Flavor Profile: Vanilla, Chocolate, Fruit, Nut, Coffee, Caramel Distribution Channel: Supermarkets, Convenience Stores, Specialty Shops, Online Retailers, Food Service End User: Children, Adults, Seniors, Foodservice Operators, Catering Companies |
| Companies Covered | Blue Bell Ice Cream, General Mills, Unilever, Danone, Dairy Farmers of America, Nestlé, Wells Enterprises, Conagra Brands, Froneri International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Desserts Market Strategic Shifts & Innovations
Refrigeration technology and formulation science are converging to compress production timelines while expanding permissible ingredient palettes. Three developments dominate competitive differentiation.
Continuous freezing systems with scraped-surface heat exchange are collapsing batch-to-batch variation in overrun control. Mid-scale Italian gelato producers deploy these units to achieve artisanal texture at industrial throughput. The technology is collapsing the historical tradeoff between scale consistency and density premium.
EFSA's novel food approval pathways for alternative proteins and plant-based fat replacers are extending formulation lead times for European launches. Manufacturers pre-submit dossiers 24-36 months ahead of intended market entry. Frozen dessert lines with heritage dairy positioning face the steepest compliance burden as they pivot toward hybrid formulations.
Licensed character partnerships and seasonal limited-edition releases are compressing product development calendars to 8-12 week cycles. North American novelty producers align flavor drops with entertainment release windows. This pattern concentrates in the United States where cross-promotional retail placement commands end-cap premiums.
Frozen Desserts Market Segmentation
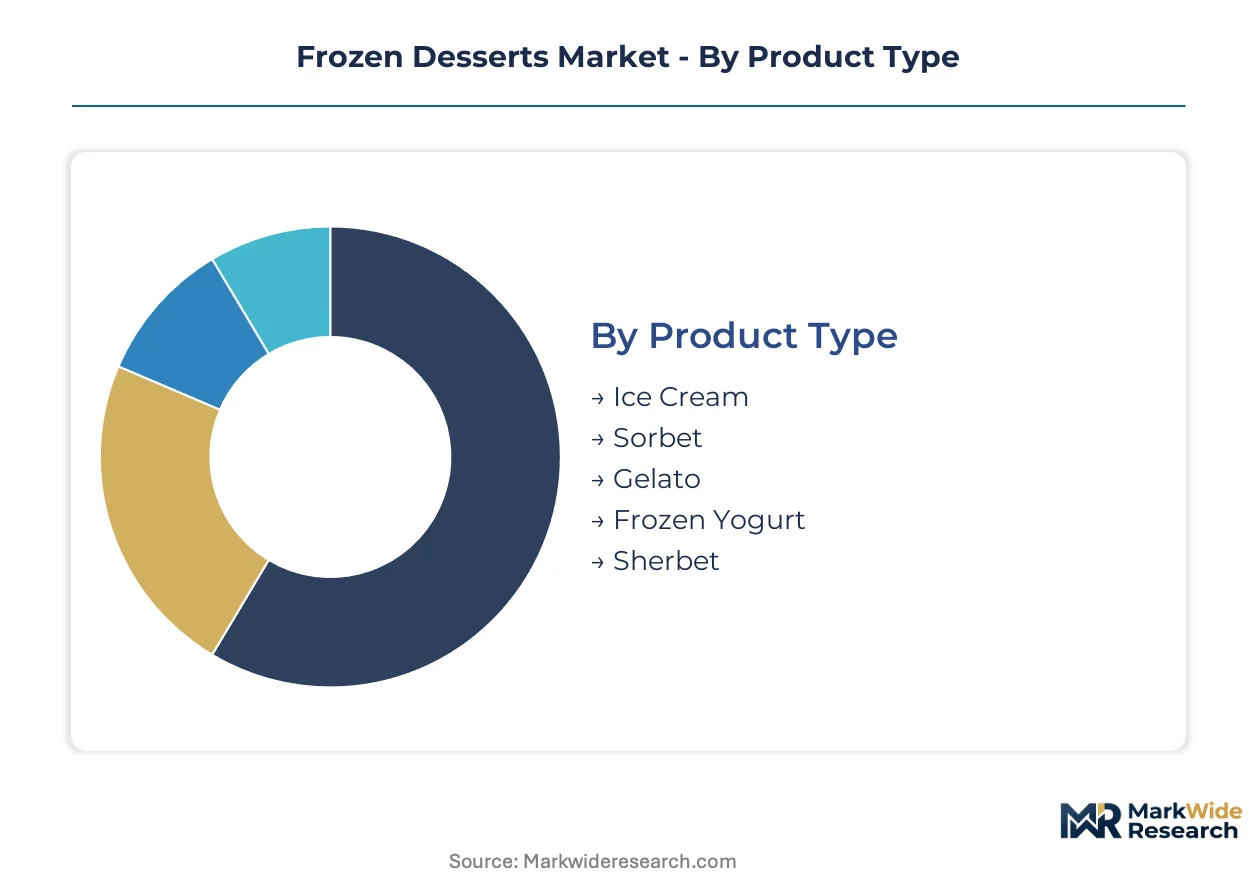
Segmentation in frozen desserts reveals how texture technology, flavor chemistry, and cold-chain logistics fragment addressable demand across distinct consumption occasions and purchase contexts. Manufacturers align formulation investments with channel-specific velocity patterns rather than pursuing universal product architectures.
Product Type:
The use-case spectrum spans indulgent refreshment to functional nutrition, with aeration levels and fat content determining channel placement and margin structure.
- Ice Cream:Standard formulations contain 10-16% milkfat with 80-100% overrun, produced via continuous freezing at -6°C to -3°C. Demand concentrates in United States supermarkets where heritage brand loyalty sustains repeat purchase velocity despite input cost volatility.
- Gelato:Lower overrun (20-35%) and higher ingredient density create premium positioning in Italy's artisanal shops and United States specialty retail. Foodservice operators deploy dedicated display cases to signal density differentiation.
- Sorbet:Water-based formulations with fruit puree content above 25% serve dairy-avoidant consumers and palate-cleansing occasions in fine dining.
- Frozen Yogurt:Live culture claims and reduced fat content capture adult wellness segments in Japan's metropolitan convenience networks.
- Sherbet:2% milkfat threshold positions between ice cream and sorbet, concentrating in North American family-pack retail.
Established volume favors ice cream; emerging adoption favors gelato.
Flavor Profile:
Flavor selection maps to ingredient sourcing security and seasonal production scheduling rather than pure preference data.
- Vanilla:Madagascar and Tahitian bean sourcing concentrates procurement risk for premium positioning. United States manufacturers hedge through multi-origin contracts.
- Chocolate:Cocoa butter and cocoa powder cost volatility drives margin compression. European processors face EFSA novel ingredient scrutiny for alkalized variants.
- Fruit:Seasonal harvest windows constrain production calendars. Strawberry and raspberry concentrates dominate clean-label formulations.
- Nut:Pistachio and hazelnut paste sourcing clusters in Mediterranean supply basins. Allergen labeling requirements intensify with FSSAI norm evolution.
- Coffee:Arabica extract integration targets adult afternoon consumption occasions in urban convenience channels.
- Caramel:Maillard-reaction derived flavor systems compete with natural extract positioning in premium tiers.
Classic profiles anchor manufacturing efficiency; emerging profiles expand permissible ingredient palettes.
Distribution Channel:
Cold-chain infrastructure investment and inventory turnover velocity determine channel economics.
- Supermarkets:Multi-door freezer placement commands slotting fees and promotional calendar coordination. Nestlé's direct-to-freezer networks demonstrate captive route economics.
- Convenience Stores:Impulse purchase velocity favors single-serve formats with 90-day shelf-life windows. Japan's metropolitan chains concentrate frozen yogurt distribution.
- Specialty Shops:Gelato density and artisanal production methods justify price premiums through experiential retail.
- Online Retailers:Dry-ice packaging requirements and last-mile cold-chain reliability constrain geographic expansion.
- Food Service:Bulk portion control and equipment leasing bundling shape B2B procurement patterns.
Traditional retail maintains volume concentration; direct channels capture data assets.
End User:
Demographic targeting aligns with nutritional claim permissibility and portion format preferences.
- Children:Licensed character packaging and reduced portion sizes drive novelty segment development. Seasonal limited editions compress product calendars to entertainment release windows.
- Adults:Functional ingredient claims and reduced-sugar positioning open premium wellness segments. Adaptogen fortification leverages supplement-labeling pathways.
- Seniors:Protein fortification and texture modification address swallowing difficulty and nutritional density requirements.
- Foodservice Operators:Equipment maintenance contracts and flavor formulation consulting create aftermarket revenue streams.
- Catering Companies:Bulk portion dispensing systems and event-specific flavor customization demand flexible production scheduling.
Household consumption sustains baseline volume; institutional procurement expands contract manufacturing utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Italian consumers absorb gelato premiums with minimal volume trade-off, while Indian buyers remain acutely price-sensitive to dairy input swings. The United States occupies a middle ground where brand loyalty buffers moderate price increases.
United States
Heritage brand loyalty sustains repeat purchase velocity in supermarket freezer aisles despite milkfat cost volatility. FDA enforces 21 CFR 135 identity standards that constrain rapid plant-based line extensions. Chicago and New York metropolitan areas concentrate artisanal gelato case expansion among foodservice operators.
Italy
Artisanal density and lower overrun production methods command shelf-space premiums in specialty retail channels. EU Green Deal packaging directives accelerate mono-material wrapper conversion across Lombardy and Piedmont production clusters. Bologna and Florence anchor dedicated gelato equipment manufacturing districts.
Japan
Live culture frozen yogurt with reduced-fat positioning captures adult wellness segments in metropolitan convenience networks. METI refrigeration emissions standards force cold-chain infrastructure reinvestment. Tokyo and Osaka concentrate distribution for probiotic-claim products.
India
Price sensitivity to dairy input swings compresses margin predictability for standard ice cream portfolios. FSSAI evolving labeling and fortification standards create compliance hurdles for multinational exporters. Maharashtra and Gujarat host the largest dairy processing clusters serving frozen dessert formulation.
Germany
EFSA novel ingredient approval pathways extend lead times for plant-based fat replacer launches. REACH compliance adds formulation validation burden for hybrid dairy alternatives. Bavaria and North Rhine-Westphalia concentrate retail freezer network density.
Frozen Desserts Market Key Industry Players
Capability concentration sits with heritage dairy specialists; scale advantage sits with diversified multinationals. The market structures around three tiers: global packaged goods conglomerates with captive distribution, regional dairy cooperatives with backward integration into milk supply, and artisanal specialists with equipment-lease bundling. Consolidation pressure runs through direct-to-freezer network expansion and clean-label stabilizer R&D partnerships.
Within the diversified multinational tier, Unilever and Nestlé occupy positions defined by geographic coverage breadth and heritage brand portfolios. General Mills exemplifies the North American novelty specialist archetype through licensed character partnerships. Among cooperative structures, Dairy Farmers of America anchors farmer-owned supply integration. Froneri International Limited represents the European-focused joint-venture model for frozen dessert manufacturing scale.
| Leading Market Players |
|---|
| Blue Bell Ice Cream |
| General Mills |
| Unilever |
| Danone |
| Dairy Farmers of America |
| Nestlé |
| Wells Enterprises |
| Conagra Brands |
| Froneri International Limited |
| Others |
Cost & Logistics Intelligence
Guar gum and locust bean gum sourcing concentration in India and Pakistan determines both pricing tier spreads and supply chain shape. Climate-induced crop variability amplifies formulation cost uncertainty, forcing manufacturers to hedge through multi-origin contracts or absorb margin compression in standard ice cream portfolios.
Pricing Analysis
Aftermarket service revenue from equipment maintenance contracts and flavor formulation consulting drives lifetime value for gelato equipment manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates artisanal Italian producers from mid-scale regional operators and mass-market commodity suppliers. Price differentiation hinges on certification tier and after-sales service bundling. Pricing pressure stems from dairy input cost volatility, with small-to-mid processors facing the steepest margin compression. Foodservice operators demonstrate the lowest price sensitivity, while Indian retail consumers remain acutely responsive to dairy input swings.
Supply Chain Analysis
Supplier-financing facilities extended by Indian and Pakistani guar gum processors to European stabilizer blenders anchor working capital structures across the formulation tier. Geographic supply concentration centers on India, Pakistan, and Mediterranean hazelnut and pistachio paste producers. Raw material dependencies rest on milkfat solids, cocoa butter, and hydrocolloid stabilizers. Single-source vulnerability in South Asian gum sourcing creates structural risk exposure. Distribution runs through Nestlé's direct-to-freezer captive route networks in Europe and traditional multi-layer distributor structures in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects through direct-to-freezer distribution networks that bypass traditional wholesale layers and capture real-time velocity data. Interoperability between equipment leasing and flavor formulation consulting creates ecosystem lock-in.
For Market Incumbents: Build captive route economics as the defensive moat. Deepen direct-to-freezer network density in United States metropolitan corridors to outflank distributor-dependent competitors. Invest in clean-label stabilizer R&D partnerships to hedge against guar gum supply concentration. FDA's 21 CFR 135 petition timelines threaten rapid plant-based pivots, making early dossier submission the critical certification lever.
For New Entrants and Emerging Players: Pursue functional ingredient claims in United States wellness-oriented retail as the most penetrable white-space target. Target India's expanding import market ahead of FSSAI compliance deadline convergence. Leverage supplement-labeling pathways for adaptogen-fortified novelties to bypass standard food identity restrictions. Direct-to-consumer subscription models for premium gelato offer the clearest go-to-market angle.
For Investors and Strategic Acquirers: Regional dairy cooperatives with backward integration into milk supply represent the priority acquisition archetype. Long-term viability frames around cold-chain infrastructure reinvestment cycles and clean-label reformulation capability. Watch EFSA novel food approval velocity as the signal indicating whether heritage dairy portfolios can successfully pivot toward hybrid formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Freezer Network Expansion | Nestlé's European captive routes demonstrate data capture advantages over distributor-dependent rivals. |
| Clean-Label Stabilizer R&D Partnership | Fruit pectin alternatives demand 18-24 month texture-validation cycles with sensory parity elusive. |
| Mono-Material Packaging Conversion | EU Green Deal directives force laminator retrofits across Lombardy and Piedmont production clusters. |
| Functional Ingredient Line Extension | Adaptogen fortification leverages permissive supplement-labeling pathways distinct from FDA food identity rules. |
| Cold-Chain Infrastructure Reinvestment | China's dual carbon goals strand legacy hardening tunnel assets in domestic manufacturer portfolios. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across regulatory and trade databases. Interview targets included gelato equipment manufacturers, dairy procurement directors at multinational processors, foodservice operators with dedicated display case networks, and flavor formulation consultants. Secondary sources encompassed FDA 21 CFR 135 filings, EFSA novel food approval dossiers, EU Green Deal packaging directive texts, and FSSAI labeling norm evolution records. Bottom-up segmentation modeling triangulated against top-down macroeconomic anchors.
Forecast inputs considered product type segmentation across ice cream, gelato, sorbet, frozen yogurt, and sherbet; flavor profile clustering; distribution channel economics; and end-user demographic targeting. Deployment of continuous freezing systems versus batch production methods provided an industry-specific technology dimension. CAGRs derived from volume trajectory modeling across the analysis window, incorporating input cost elasticity assumptions and regulatory compliance timeline impacts.
Sensitivities concentrate around dairy commodity price volatility, EFSA approval velocity for plant-based fat replacers, and FSSAI implementation timelines. Forecasts reflect documented assumptions regarding clean-label reformulation adoption curves and cold-chain infrastructure reinvestment rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Bangladesh Frozen Food Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Frozen Fruit Bars Market