
 Dairy-Free Ice Creams Market | 2026-2036
Dairy-Free Ice Creams Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy-Free Ice Creams Market Analysis
EU F-Gas Regulation is repositioning cold-chain infrastructure investments across European manufacturing facilities. Unilever leverages its global distribution network to secure shelf placement in conventional freezer aisles beyond specialty stores. Oatly anchors its production strategy around oat-base formulations that bypass nut-allergen labeling complexities. Danone competes through fermented coconut and almond bases that deliver texture parity with conventional dairy ice cream.
Dairy-free ice creams are frozen desserts formulated from plant-derived lipids and proteins, typically containing 8-14% fat content achieved through emulsified coconut, oat, or cashew bases, then pasteurized and frozen under continuous overrun control to replicate the mouthfeel of dairy-based products. Almond milk formulations currently lead volume distribution due to established consumer familiarity and neutral flavor compatibility, while oat milk bases represent the fastest-expanding segment driven by sustainability positioning and allergen-friendly claims. Coconut milk variants command premium shelf pricing in health-conscious channels, reflecting higher raw material costs and shorter supply chains from Southeast Asian sourcing clusters.
The FDA enforces dairy identity standards that restrict plant-based products from using "milk" labeling without qualifying modifiers, directly influencing package design and consumer communication strategies. EFSA guidelines on novel food ingredients govern the approval of emerging protein bases such as pea and fava bean extracts entering European formulations. Stakeholders must monitor how evolving allergen threshold regulations and clean-label enforcement reshape permissible ingredient declarations and reformulation cycles across multiple jurisdictions.
Market Dynamics
Refrigeration infrastructure mandates under the EU F-Gas Regulation are forcing plant-based frozen dessert manufacturers to retool production lines and cold-chain logistics, reshaping capital allocation across European facilities and pressuring margin structures industry-wide.
Growth Catalysts
- Flexitarian dietary patterns:United States consumers are driving repeat purchases across premium and mass-market tiers, expanding addressable demand beyond traditional vegan segments into mainstream grocery channels.
- FDA dairy identity standards:Evolving labeling requirements are accelerating clean-label innovation as manufacturers reformulate to meet qualifying modifier rules while maintaining sensory parity.
- Continuous overrun control technology:Advanced freezing equipment is enabling texture replication that closes the mouthfeel gap with conventional dairy ice cream, supporting premium pricing acceptance.
Market Restraints
- Coconut lipid cost volatility:Southeast Asian sourcing clusters face climate-induced yield fluctuations that transmit directly into formulation costs for premium-positioned variants.
- Almond water intensity:California aquifer depletion risks are elevating input cost uncertainty for the leading volume base, pressuring long-term supply contracts.
- Novel food approval timelines:EFSA guidelines on emerging protein bases such as pea and fava bean extracts are creating multi-year regulatory lag before European market entry.
Strategic Opportunities
- Expanded freezer space allocation:Retail grocery chains are dedicating incremental shelf capacity to plant-based frozen desserts, opening distribution access beyond specialty stores.
- Fermented base technology:Cultured coconut and almond formulations are delivering probiotic functionality that commands health-channel premium positioning.
- Oat-base allergen positioning:Formulations bypassing nut-allergen labeling complexities are capturing school and institutional foodservice contracts closed to almond and cashew variants.
Industry Challenges
- Emulsifier clean-label substitution:Removing synthetic stabilizers while maintaining 8-14% fat emulsion stability requires reformulation expertise currently concentrated among specialized ingredient suppliers.
- Multi-jurisdiction compliance:Divergent allergen threshold regulations across FDA, EFSA, and national frameworks are fragmenting packaging and declaration requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy-Free Ice Creams Market |
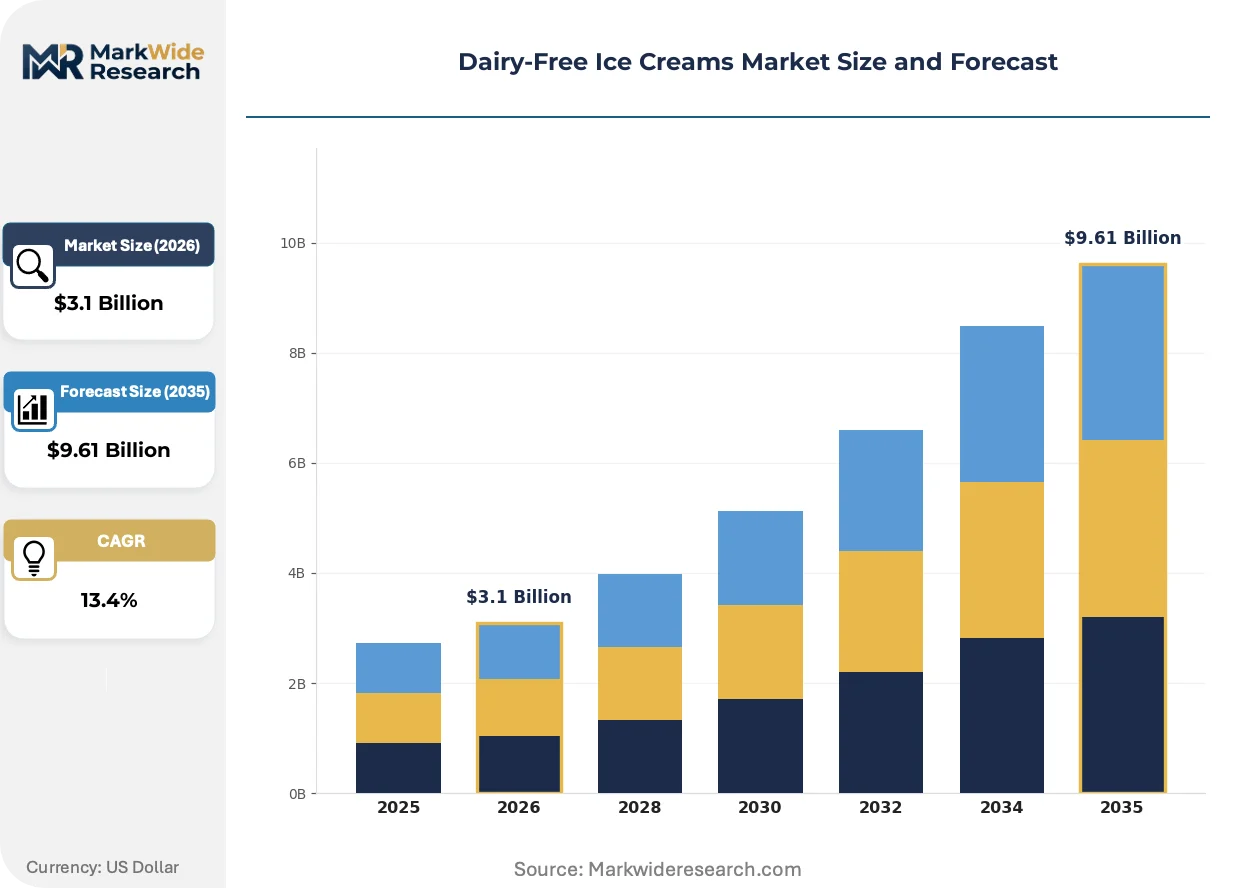
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $9.61 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Milk, Almond Milk, Soy Milk, Cashew Milk Ingredient Source: Nuts, Seeds, Fruits, Legumes Flavor Profile: Chocolate, Vanilla, Strawberry, Matcha Consumer Segment: Health-Conscious, Vegan, Lactose-Intolerant, Flexitarian |
| Companies Covered | General Mills, Van Leeuwen Ice Cream, Unilever, So Delicious Dairy Free, NadaMoo!, Nestlé, Oatly, Ben & Jerry's, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy-Free Ice Creams Market Emerging Trajectories
Precision fermentation and advanced emulsion science are redefining what plant-based frozen desserts can deliver, shifting competitive advantage from ingredient sourcing to bioprocessing capabilities and texture engineering.
High-pressure processing is absorbing functionality previously delivered by thermal pasteurization, preserving volatile flavor compounds in oat and coconut bases. Premium manufacturers are adopting this technology to reduce cooked off-notes that historically signaled plant origin. The structural consequence is absorption of premium positioning by brands with capital-intensive cold-processing infrastructure, compressing margins for conventional thermal processors.
REACH chemical safety evaluations are extending scrutiny to food-contact materials in frozen dessert packaging, particularly for recycled content claims. Industrial consequence includes accelerated migration toward virgin-grade barrier films or certified-compostable alternatives. European formulations with shorter supply chains from Southeast Asian coconut clusters face the most acute compliance cost pressure.
Direct-to-consumer subscription models are fragmenting traditional grocery channel concentration, with flexitarian households in metropolitan United States markets accepting frozen delivery logistics. E-commerce fulfillment is displacing conventional freezer-aisle discovery for trial purchases. Geographic concentration of this shift centers on coastal urban corridors with established cold-chain last-mile infrastructure.
Dairy-Free Ice Creams Market Segmentation
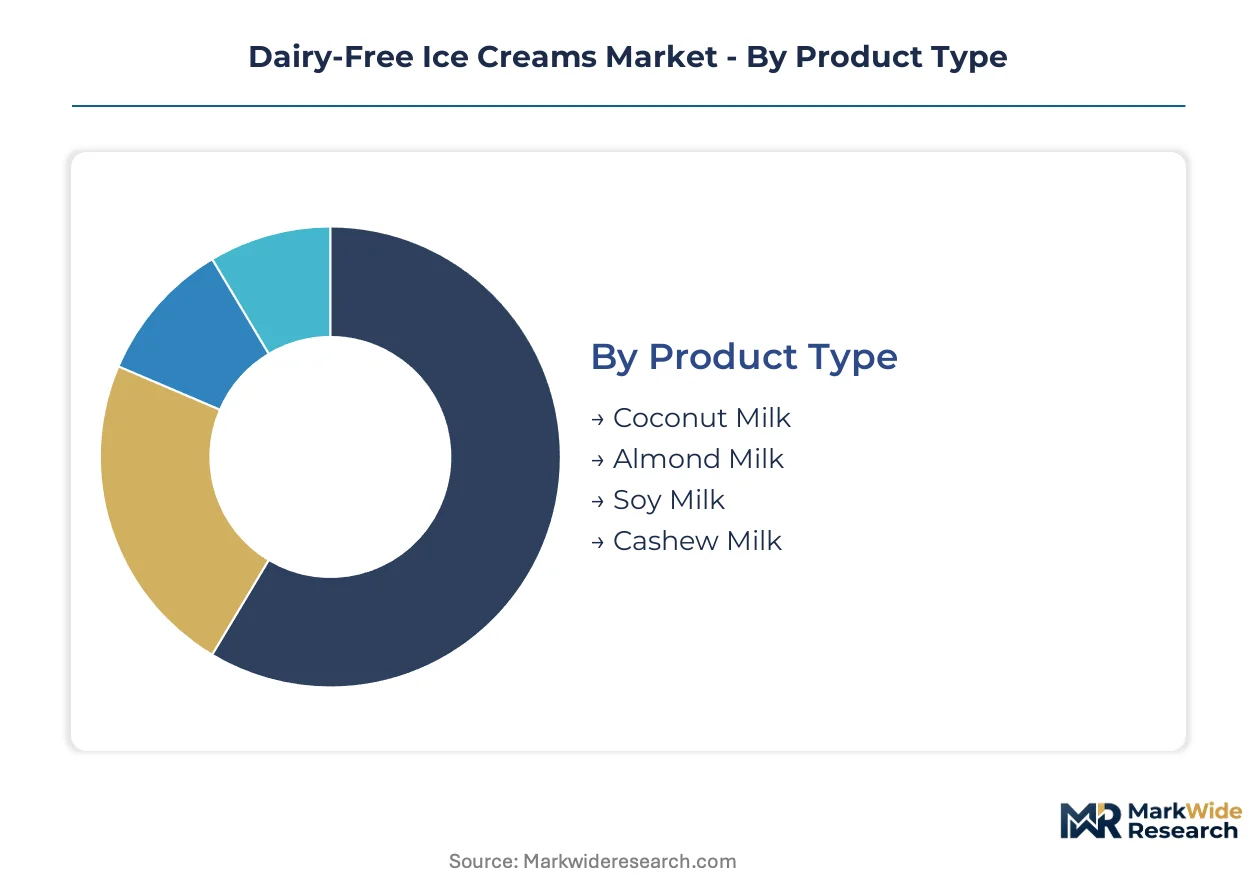
Plant-based frozen dessert manufacturers align formulation investments with distinct consumer upgrade cycles. Each segmentation dimension reveals where substitution economics favor premium positioning over commodity parity.
Product Type:
Reformulation cycles track shifting lipid economics and allergen threshold regulations across major production bases.
- Almond Milk:Neutral flavor compatibility and established consumer familiarity sustain volume leadership in United States retail channels. California aquifer depletion risks elevate long-term input cost uncertainty for this base.
- Coconut Milk:Higher fat content delivers superior mouthfeel replication through emulsified lipid structures. Southeast Asian sourcing clusters command premium shelf pricing in health-conscious channels reflecting raw material costs.
- Soy Milk:Legacy base with mature supply infrastructure and price-competitive positioning in mass-market tiers.
- Cashew Milk:Creamy texture profile supports premium positioning though nut-allergen labeling restricts institutional foodservice access.
Almond milk sits at the top of the volume ranking, with oat-base formulations climbing the fastest despite their absence from formal segmentation tables.
Ingredient Source:
Procurement patterns concentrate around supply security and clean-label compliance velocity.
- Nuts:Almond and cashew bases dominate current formulation portfolios with established emulsion science and sensory benchmarking against conventional dairy.
- Seeds:Sunflower and pumpkin protein extracts are gaining traction in allergen-free positioning that bypasses nut-declaration requirements.
- Fruits:Coconut lipid systems anchor premium variants with tropical flavor associations and shorter supply chains from Southeast Asian clusters.
- Legumes:Pea and fava bean protein bases face multi-year EFSA novel food approval timelines before European market entry.
Nut-derived bases retain the largest procurement allocation, with legume sources expanding most quickly once regulatory clearance accelerates.
Flavor Profile:
Flavor innovation cycles follow premiumization trajectories in flexitarian household purchasing.
- Chocolate:Cocoa butter compatibility with coconut lipid emulsions supports rich mouthfeel delivery in premium tier positioning.
- Vanilla:Benchmark flavor for sensory parity testing against conventional dairy, sustaining mass-market repeat purchase rates.
- Strawberry:Fruit particulate integration challenges drive clean-label stabilizer innovation in texture maintenance.
- Matcha:Antioxidant positioning and Asian flavor trend adoption command specialty channel premium pricing.
Vanilla and chocolate anchor baseline volume, with matcha gaining share fastest in coastal metropolitan markets.
Consumer Segment:
Addressable demand expansion depends on crossing over from restriction-based to preference-based purchasing.
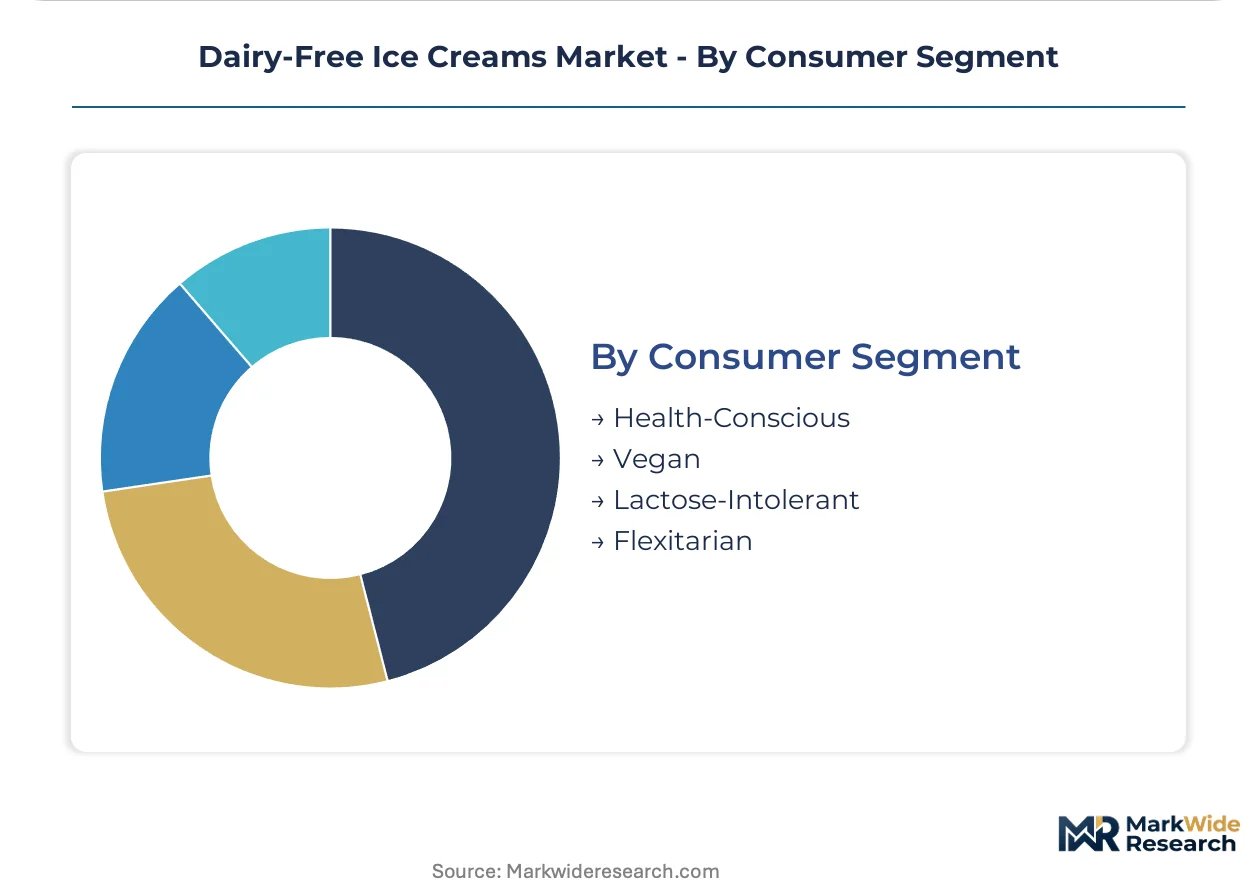
- Flexitarian:United States households reducing but not eliminating dairy consumption drive repeat purchases across premium and mass-market tiers with environmental motivation.
- Health-Conscious:Clean-label scrutiny and probiotic functionality demands favor fermented coconut and almond formulations in specialty retail.
- Lactose-Intolerant:Medical necessity segment with price-sensitive purchasing patterns and established brand loyalty thresholds.
- Vegan:Ethical positioning supports premium pricing acceptance though total addressable population remains smaller than flexitarian expansion.
Flexitarian consumers now dominate absolute volume contribution, with health-conscious positioning showing the steepest expansion trajectory in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food scientist clusters in California and Wisconsin anchor formulation expertise for plant-based frozen desserts, while flexitarian consumer density in coastal metropolitan areas drives retail expansion strategies.
United States
Flexitarian households in New York, Los Angeles, and Chicago metro areas generate repeat purchases across premium and mass-market tiers. FDA dairy identity standards restrict "milk" labeling without qualifying modifiers, forcing package redesign investments. Ben & Jerry's Vermont headquarters anchors East Coast innovation pipelines for texture-engineered oat and almond bases.
Germany
Clean-label scrutiny from Berlin and Hamburg health-conscious consumers favors fermented coconut formulations with probiotic positioning. EFSA novel food guidelines govern emerging protein bases such as pea and fava bean extracts. Bavarian dairy processing infrastructure is retooling for plant-based production lines under EU F-Gas refrigeration mandates.
United Kingdom
London's flexitarian density supports premium pricing acceptance for oat-base variants in specialty retail channels. REACH chemical safety evaluations extend scrutiny to food-contact materials in frozen dessert packaging. Manchester and Birmingham distribution hubs are absorbing incremental cold-chain capacity for direct-to-consumer subscription fulfillment.
Canada
Toronto and Vancouver metropolitan markets show concentrated demand for allergen-friendly oat-base formulations bypassing nut-declaration requirements. Health Canada labeling standards align with FDA qualifying modifier rules for plant-based dairy alternatives. Quebec's food processing corridor is integrating high-pressure processing equipment to reduce cooked off-notes in coconut lipid systems.
Australia
Sydney and Melbourne coastal urban corridors with established cold-chain last-mile infrastructure support frozen delivery logistics for direct-to-consumer models. TGA guidelines on novel ingredients influence approval timelines for emerging protein bases. Southeast Asian coconut sourcing clusters maintain supply relationships with Australian premium manufacturers despite climate-induced yield volatility.
Dairy-Free Ice Creams Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price positioning. The vendor base spans multinational CPG holdings with global freezer-aisle access and emerging challengers dependent on specialty retail and e-commerce channels. Three archetypes dominate: legacy dairy diversifiers, plant-native pure-plays, and chef-founded premium artisans. Capacity expansion and strategic retail shelf partnerships constitute the dominant competitive moves.
Within the diversified conglomerate tier, Unilever and Nestlé occupy positions leveraging global distribution networks for conventional freezer-aisle placement beyond specialty stores. Among plant-native specialists, Oatly anchors oat-base production strategy around allergen-friendly claims, while NadaMoo! exemplifies the chef-founded artisan archetype with premium coconut-milk positioning. Danone sits within the fermented-base technology vector through cultured coconut and almond formulations delivering probiotic functionality.
| Leading Market Players |
|---|
| General Mills |
| Van Leeuwen Ice Cream |
| Unilever |
| So Delicious Dairy Free |
| NadaMoo! |
| Nestlé |
| Oatly |
| Ben & Jerry's |
| Danone |
| Others |
Supply Flow & Price Mechanics
Premium-coconut and commodity-oat tier divergence manifests in divergent margin structures and sourcing configurations across the dairy-free frozen dessert category. Coconut lipid systems command shelf price premiums reflecting Southeast Asian cluster concentration and climate-exposed yield volatility, while oat-base formulations exploit domestic North American grain infrastructure for cost-competitive mass-market positioning.
Pricing Analysis
Ingredient-bundled versus unbundled formulation splits dominate pricing architecture, with finished-product manufacturers absorbing coconut lipid cost swings while oat-base buyers negotiate grain commodity contracts directly. Three-tier pricing structure across premium, standard, and economy levels tracks fat content percentage and clean-label certification density. Pricing pressure stems from California aquifer depletion elevating almond input costs across the volume-leading segment. Health-conscious flexitarian households show lowest price sensitivity, while lactose-intolerant medical-necessity buyers concentrate in economy tiers.
Supply Chain Analysis
Direct-to-retail freezer-aisle channels handle mainstream grocery volume, while direct-to-consumer subscription logistics absorb coastal metropolitan trial purchases. Raw material sourcing concentrates in Thailand, Indonesia, and Vietnam for coconut lipid clusters, with oat grain drawn from Canadian prairie provinces and upper Midwest United States farming regions. Supply chain risk centers on single-source vulnerability to Southeast Asian climate-induced yield fluctuations. Distribution runs through refrigerated third-party logistics networks with EU F-Gas Regulation compliance mandates reshaping European cold-chain infrastructure investments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dairy-free ice creams market reads as a late-cycle quality story where flexitarian preference shifts toward fermented-base probiotic functionality and clean-label emulsifier systems favor premium specification tiers over commodity parity.
For Market Incumbents: Acquire high-pressure processing equipment assets to preserve volatile flavor compounds in oat and coconut bases, eliminating cooked off-notes that signal plant origin. Secure long-term supply contracts with Southeast Asian coconut clusters before climate volatility hardens procurement terms. Capacity addition in Quebec and Wisconsin food processing corridors anchors North American production resilience against EU F-Gas refrigeration compliance costs.
For New Entrants and Emerging Players: Enter via school and institutional foodservice contracts closed to nut-allergen formulations, exploiting oat-base allergen-friendly positioning that legacy almond-dependent incumbents cannot serve. Target metropolitan United States direct-to-consumer subscription corridors with established cold-chain last-mile infrastructure. White-space concentration in fermented coconut probiotic variants offers health-channel premium pricing with lower competitive density than mass-market oat bases.
For Investors and Strategic Acquirers: Consolidation pressure builds where cold-processing infrastructure scarcity separates premium-positioned brands from thermal-commodity processors with compressed margin trajectories. Acquisition target archetypes include chef-founded artisan labels with coconut-milk positioning and installed high-pressure processing capacity. Watch EFSA novel food approval timelines for pea and fava bean protein bases as inflection signals for legume-source competitive entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermented Base Technology Investment | Cultured coconut and almond formulations deliver probiotic functionality commanding health-channel premium positioning. |
| High-Pressure Processing Equipment Deployment | Cold pasteurization preserves volatile flavor compounds, eliminating cooked off-notes in oat lipid systems. |
| Oat-Base Allergen-Friendly Repositioning | Nut-free labeling captures school and institutional foodservice contracts closed to almond and cashew variants. |
| Direct-to-Consumer Subscription Launch | Coastal metropolitan flexitarian households accept frozen delivery logistics, fragmenting traditional grocery channel concentration. |
| Southeast Asian Supply Contract Securement | Long-term coconut lipid agreements hedge climate-induced yield volatility before procurement terms harden. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional manufacturing cluster. The analysis combines executive interviews with plant-based frozen dessert formulation scientists, retail category buyers at grocery chains, cold-chain logistics operators, and regulatory affairs specialists with secondary validation from FDA dairy identity standard filings, EFSA novel food submission databases, EU F-Gas Regulation implementation records, and refrigerated transport trade association data. Bottom-up volume modeling and top-down value triangulation cross-validate segment-level outputs.
Granularity-level framing applies country-specific consumer segmentation and base-ingredient procurement patterns across the projection horizon. The analytical framework models product type, ingredient source, flavor profile, and consumer segment dimensions with regional regulatory cluster overlays. CAGRs derive from trend-line extrapolation of flexitarian household penetration rates and premium-tier pricing acceptance trajectories, stress-tested against coconut lipid cost volatility scenarios and EFSA approval timeline uncertainties for emerging legume protein bases.
Inputs from refrigerated logistics operators and Southeast Asian commodity brokers were available through the study window; gaps in forward-year coconut yield forecasting introduce uncertainty bands around premium-tier margin projections. Forecasts reflect documented assumptions regarding flexitarian dietary pattern persistence and clean-label enforcement velocity. Periodic stress-testing of base assumptions is recommended against FDA labeling rule amendments and climate-induced supply disruption scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Coconut Milk Powder Market