
 Global Guilt-Free Desserts Market | 2026-2036
Global Guilt-Free Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Guilt-Free Desserts Market Foresight
The EU's F-Gas Regulation is pivoting refrigeration-dependent dessert manufacturers toward climate-friendly cold-chain systems. Daiya Foods Inc. leverages its plant-based cheese expertise to anchor dairy-free frozen dessert lines across North American retail. Danone S.A. competes through specialized fermentation platforms that sustain clean-label positioning in European markets. Halo Top differentiates via high-protein, low-calorie formulations that dominate the better-for-you ice cream segment.
Guilt-free desserts comprise formulated sweet products engineered with reduced glycemic load, alternative sweeteners such as allulose or monk fruit extract, and modified fat systems to deliver sensory satisfaction without conventional caloric density. Their primary commercial purpose centers on enabling indulgent consumption occasions for consumers managing weight, blood glucose, or allergen restrictions. Low-sugar and keto product types currently lead volume contribution, while vegan and dairy-free segments capture expanding margin pools as oat and coconut milk bases displace traditional dairy inputs. Online retailers represent the fastest-growing distribution channel, though supermarkets retain structural dominance through refrigerated case placement and impulse purchase velocity.
The FDA's evolving Nutrition Facts panel requirements and the EU's Nutri-Score front-of-pack system jointly pressure reformulation timelines across multinational portfolios. India's FSSAI and China's SAMR are tightening import standards for alternative sweeteners, creating divergent compliance pathways for brands seeking Asian market entry. Health Canada and Brazil's ANVISA are advancing comparable added-sugar disclosure frameworks that will further fragment regulatory testing burdens. Stakeholders must monitor accelerating divergence between permissive and restrictive jurisdictions to optimize product registration sequencing and avoid stranded formulation investments.
Market Dynamics
The EU's F-Gas Regulation is forcing refrigeration-dependent dessert manufacturers to abandon hydrofluorocarbon-based cold-chain infrastructure, creating simultaneous cost pressure and competitive differentiation for early climate-tech adopters.
Growth Catalysts
- Clean-label certification mandates:The EU's Nutri-Score front-of-pack labeling requirements push reformulation toward reduced-sugar profiles that command premium shelf positioning in German and French retail.
- Alternative sweetener maturation:Allulose and monk fruit extract production scaling is lowering input costs for keto and diabetic-friendly product lines across North American manufacturing.
- Millennial and Gen Z health consciousness:These demographics now represent the dominant purchasing cohort for supermarket and online retail channels, prioritizing glycemic load transparency over traditional indulgence signals.
Market Restraints
- Input cost volatility:Oat and coconut milk base prices fluctuate with agricultural yield cycles in Southeast Asian sourcing regions, compressing margin stability for dairy-free portfolios.
- Supply concentration risk:Alternative sweetener synthesis depends on a limited number of Chinese and Indian chemical manufacturers, creating single-source vulnerability for allulose-dependent formulations.
- Technical sensory limitations:Current fat-mimicking systems fail to replicate mouthfeel depth in frozen applications below 50% caloric reduction, capping reformulation ambition.
Strategic Opportunities
- Brazil's ANVISA added-sugar disclosure framework:Early compliance positions brands for preferential retail access as Latin America's largest market tightens nutritional transparency requirements.
- Direct-to-consumer subscription models:Frozen dessert brands bypass supermarket slotting fees through temperature-controlled last-mile logistics, capturing full margin in urban Australian and US coastal markets.
- Fermentation-derived protein integration:Precision fermentation platforms enable animal-free dairy protein incorporation, opening clean-label positioning in European markets with strict dairy nomenclature protections.
Industry Challenges
- Refrigerated logistics talent scarcity:Cold-chain engineering expertise concentrates in legacy pharmaceutical and seafood sectors, forcing dessert manufacturers to compete for qualified personnel.
- Dual certification timeline compression:Simultaneous FDA Nutrition Facts panel updates and EU Nutri-Score alignment require parallel reformulation tracks, straining R&D bandwidth.
- Clean-label ingredient IP fragmentation:Patent thickets around specific allulose production methods and fat-mimicking emulsion systems complicate freedom-to-operate assessments for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Guilt-Free Desserts Market |
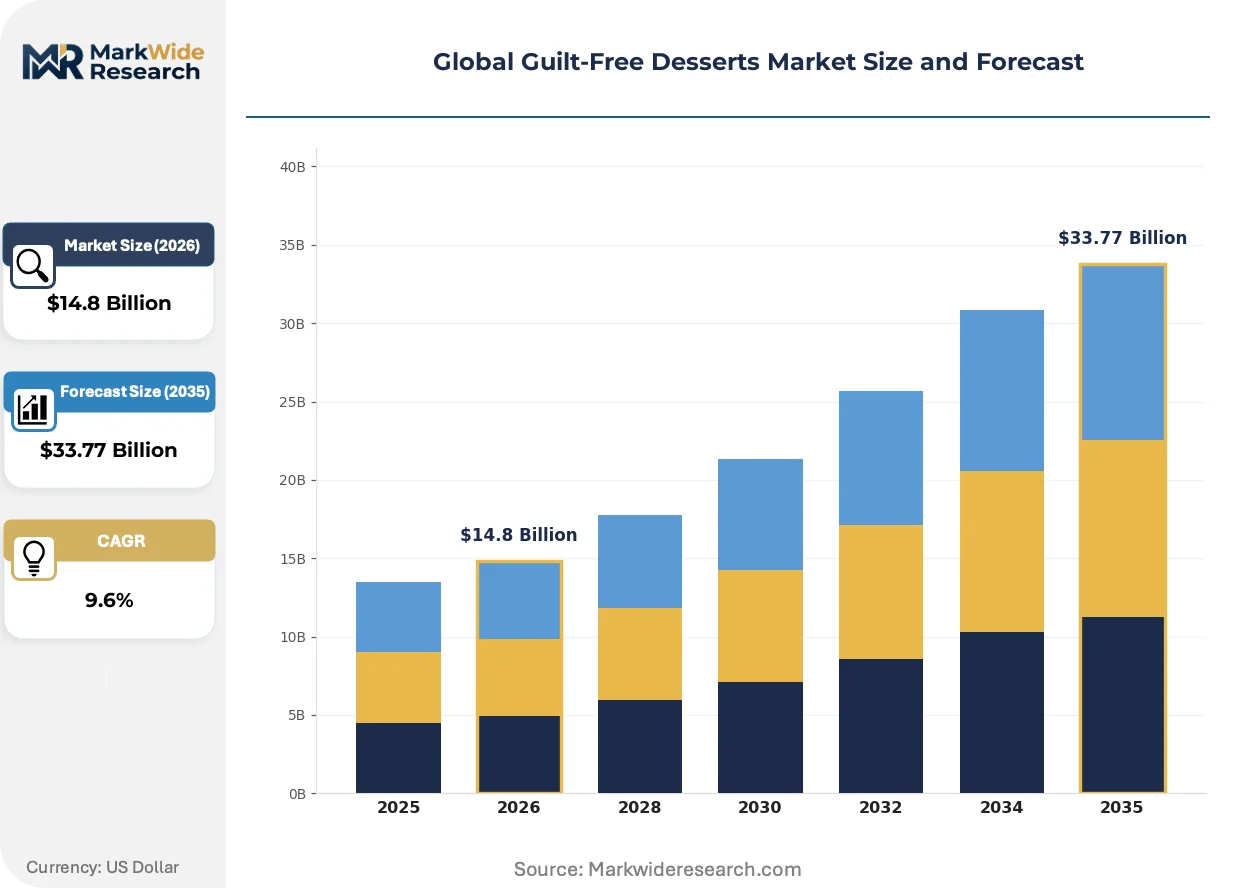
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.77 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Sugar, Keto, Vegan, Gluten-Free, Dairy-Free Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Health Food Shops, Convenience Stores Application: Weight Management, Diabetes-Friendly, Sport Nutrition, Plant-Based Diets, Allergy Sensitive End User: Fitness Enthusiasts, Diabetic Patients, Vegans, Allergy-Conscious Consumers, Senior Citizens |
| Companies Covered | Daiya Foods Inc., HP Hood (Planet Oat), Danone S.A., Cado, Halo Top, Unilever, Ben & Jerry's Homemade, Inc, Karma Baker, Grupo Bimbo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Guilt-Free Desserts Market Shifts & Advancements
Formulation science and regulatory disclosure requirements are converging to reshape how guilt-free desserts achieve sensory legitimacy while maintaining nutritional claims.
Precision fermentation for dairy protein production is modularizing the ingredient supply base. Specialty dessert manufacturers in Denmark and the Netherlands adopt these platforms to bypass traditional dairy supply chains. The technology is modularizing what was previously a consolidated upstream input market into distributed, contract-manufacturable protein sources.
The EU's F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants with GWP above 150. Dessert manufacturers dependent on frozen distribution must retrofit cold-chain infrastructure or face operational penalties. German and Italian producers lead transition investment, securing competitive positioning as 2030 phaseout deadlines approach.
Subscription-based frozen dessert purchasing is compressing traditional supermarket impulse dynamics. Urban consumers in Sydney, Los Angeles, and London now schedule recurring deliveries of portion-controlled, diet-specific treats. This channel shift rewards brands with direct customer data capture and reduces slotting fee dependence.
Global Guilt-Free Desserts Market Segmentation
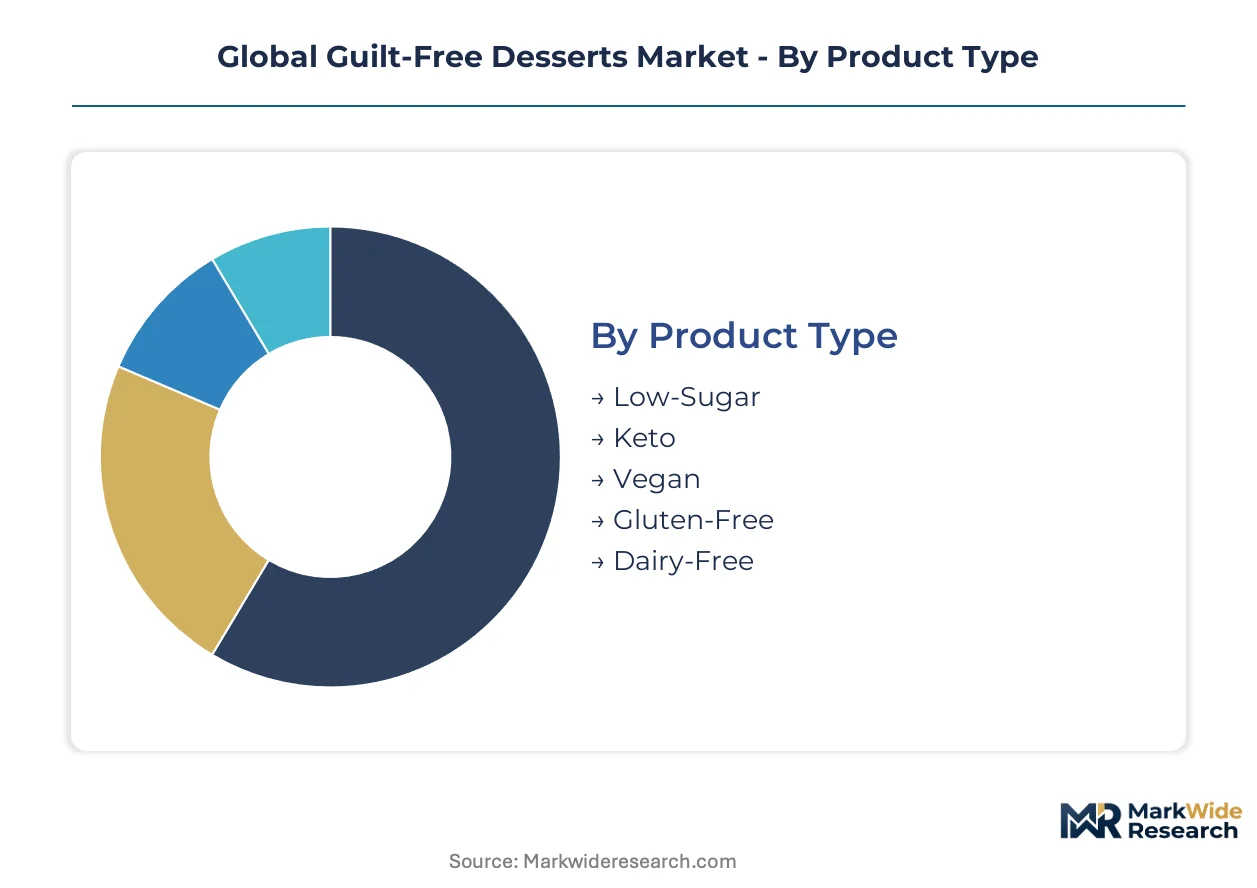
Guilt-free dessert manufacturers navigate divergent certification burdens across product categories. Each segment demands distinct regulatory pathways, from FDA Nutrition Facts compliance to EU Nutri-Score alignment and allergen-specific labeling protocols.
Product Type:
Low-sugar and keto formulations face the heaviest FDA disclosure burdens, while vegan and dairy-free lines trigger EU dairy nomenclature protections that constrain clean-label positioning.
- Low-Sugar:Formulations achieve glycemic reduction through allulose, monk fruit extract, or erythritol substitution. Demand concentrates in United States supermarket channels where FDA added-sugar disclosure rules create shelf-positioning advantages for early reformulators.
- Keto:Ultra-low carbohydrate profiles rely on modified fat systems and sugar alcohol blends to maintain ketogenic metabolic thresholds. German and Australian consumers drive premium pricing through specialized health food retail, though sensory limitations below 50% caloric reduction cap mass-market penetration.
- Vegan:Plant-based formulations exclude all animal derivatives, typically anchoring on oat or coconut milk bases.
- Gluten-Free:Celiac-safe products require certified ingredient segregation and dedicated production lines.
- Dairy-Free:Lactose-eliminated lines leverage almond, soy, or pea protein bases, with oat milk displacing earlier-generation alternatives.
Leading the category by volume: Low-Sugar. Growing fastest: Keto.
Distribution Channel:
Channel selection dictates margin capture, with direct-to-consumer models bypassing slotting fees while refrigerated case placement in supermarkets sustains impulse velocity.
- Supermarkets:Dominant volume channel leveraging refrigerated and frozen case placement for impulse conversion. United States and German retail chains command premium positioning fees for clean-label certified SKUs.
- Online Retailers:Temperature-controlled last-mile logistics enable subscription models in Sydney, Los Angeles, and London urban corridors, capturing full margin and direct consumer data.
- Specialty Stores:Curated health-focused retail emphasizing certification transparency and premium pricing.
- Health Food Shops:Independent retailers prioritizing local and organic credentials alongside functional claims.
- Convenience Stores:Grab-and-go formats for single-serve portions, limited by refrigeration constraints.
Supermarkets retain structural dominance. Online Retailers expand most quickly through subscription mechanics.
Application:
Application segmentation reflects divergent consumer health objectives, each requiring substantiation against distinct regulatory claim standards.
- Weight Management:Portion-controlled, reduced-calorie formulations targeting sustained energy deficit. United States consumers drive volume through portion-packaging innovation, though technical sensory limitations constrain reformulation ambition below 50% caloric reduction.
- Diabetes-Friendly:Glycemic-index-optimized products using alternative sweeteners with minimal insulin response. Australian and German markets exhibit strongest demand concentration as diabetic population screening expands.
- Sport Nutrition:High-protein recovery formats integrating whey or fermentation-derived protein isolates.
- Plant-Based Diets:Fully vegan formulations aligned with ethical consumption frameworks.
- Allergy Sensitive:Top-eight-allergen-eliminated products requiring dedicated supply chain segregation.
Weight Management commands volume leadership. Diabetes-Friendly posts the steepest expansion trajectory as screening protocols widen addressable populations.
End User:
End user targeting determines formulation complexity, with diabetic patients and allergy-conscious consumers imposing the strictest input verification requirements.
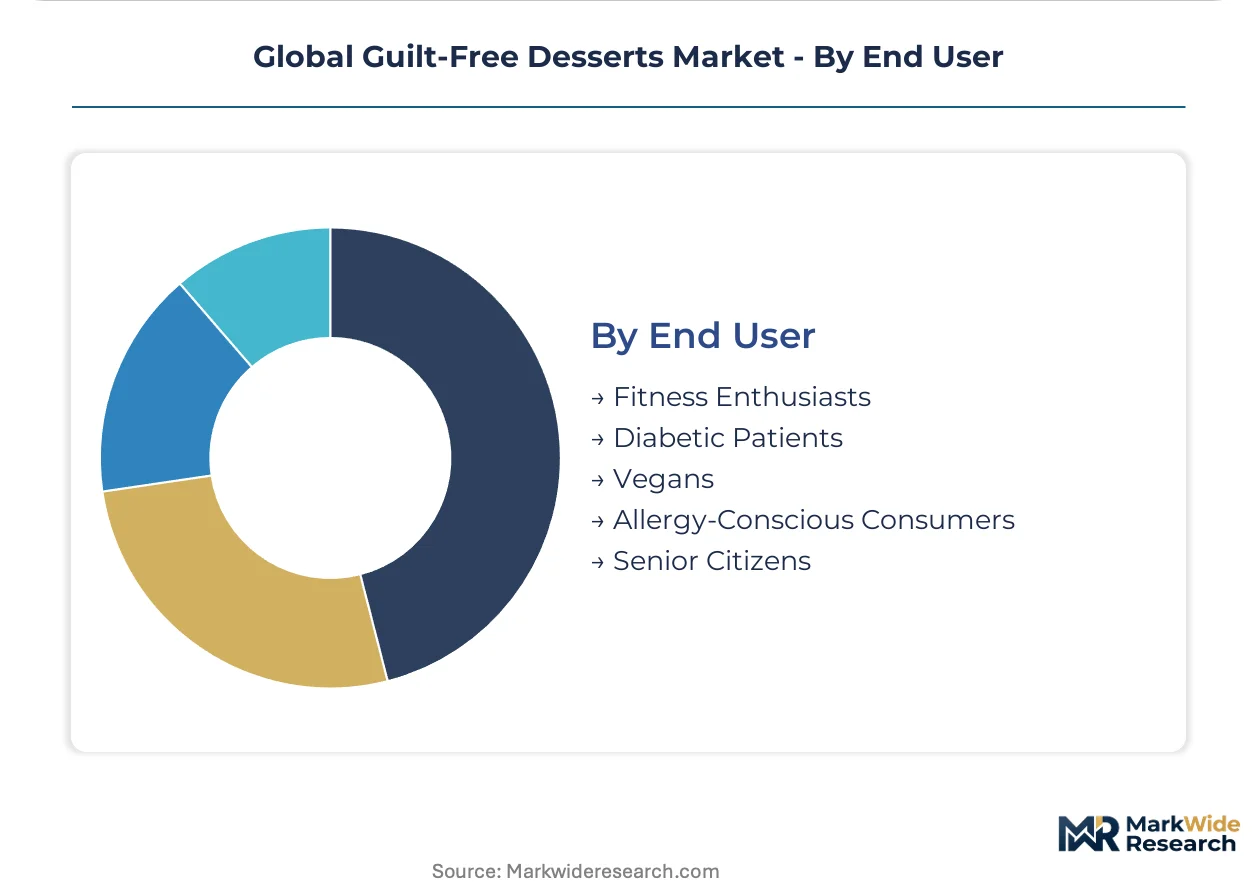
- Fitness Enthusiasts:Protein-forward consumers prioritizing macronutrient transparency and post-workout recovery functionality. United States and Australian gym-adjacent retail channels concentrate demand for high-protein frozen desserts.
- Diabetic Patients:Medically motivated purchasers requiring verified glycemic load documentation and endocrinologist endorsement. German and Australian healthcare retail integration supports premium pricing for clinically validated formulations.
- Vegans:Ethically driven consumers rejecting all animal derivatives regardless of health claims.
- Allergy-Conscious Consumers:Risk-averse purchasers demanding certified allergen-free production environments.
- Senior Citizens:Texture-modified and nutrient-dense formats addressing chewing limitations and metabolic slowing.
Fitness Enthusiasts anchor current volume. Diabetic Patients gain share fastest through clinical channel expansion and reimbursement pilot programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the United Arab Emirates and Singapore accelerate cold-chain infrastructure investment for temperature-sensitive dessert distribution. These hubs channel reformulated products into adjacent markets while serving as regulatory testing grounds for alternative sweetener approvals.
United States
FDA Nutrition Facts panel updates and added-sugar disclosure mandates drive supermarket reformulation. Millennial and Gen Z consumers in Los Angeles and New York Metro sustain subscription-model growth for portion-controlled frozen desserts. Cold-chain engineering talent concentrates in legacy pharmaceutical hubs around Boston and the Research Triangle.
Germany
EU Nutri-Score front-of-pack labeling creates premium shelf positioning for reduced-sugar SKUs in Berlin and Munich retail chains. The F-Gas Regulation forces hydrofluorocarbon phaseout in frozen distribution networks. Bavarian producers lead climate-friendly refrigeration retrofit investment ahead of 2030 deadlines.
Australia
TGA-aligned diabetic screening expansion widens addressable populations for glycemic-index-optimized products. Sydney and Melbourne urban corridors anchor direct-to-consumer subscription mechanics with temperature-controlled last-mile logistics. Health food retail integration supports premium pricing for clinically validated formulations.
China
SAMR tightening of alternative sweetener import standards creates divergent compliance pathways for brands seeking market entry. Shanghai and Guangzhou cold-chain clusters trial climate-friendly refrigeration systems under municipal carbon-reduction targets. Domestic oat milk base production scales to reduce Southeast Asian agricultural yield dependency.
Brazil
ANVISA added-sugar disclosure framework advances nutritional transparency requirements for Latin America's largest market. São Paulo and Rio de Janeiro metropolitan areas concentrate health-conscious consumer cohorts demanding clean-label certification. Early compliance positions brands for preferential retail access as enforcement tightens.
Global Guilt-Free Desserts Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, distribution, and certification vectors. The vendor base stratifies into three tiers: multinational CPG houses with refrigerated logistics scale, mid-cap clean-label specialists leveraging fermentation platforms, and emerging direct-to-consumer brands bypassing supermarket slotting fees. Dominant competitive moves include portfolio diversification into plant-based lines and strategic partnerships for climate-friendly cold-chain retrofit.
Within the plant-based specialist tier, Daiya Foods Inc. and Danone S.A. exemplify divergent scale approaches to dairy-free frozen dessert positioning. Halo Top occupies a position in the better-for-you segment through high-protein, low-calorie formulation archetypes. Unilever represents diversified conglomerate competition with refrigerated case placement leverage across multiple retail channels.
| Leading Market Players |
|---|
| Daiya Foods Inc. |
| HP Hood (Planet Oat) |
| Danone S.A. |
| Cado |
| Halo Top |
| Unilever |
| Ben & Jerry's Homemade, Inc |
| Karma Baker |
| Grupo Bimbo |
| Others |
Supply & Pricing Matrix
Precision fermentation for dairy protein production is redistributing cost economics across alternative sweetener and plant-based base supply tiers while simultaneously fragmenting upstream concentration among contract manufacturers in Denmark and the Netherlands. This technology transition enables smaller brands to bypass traditional dairy procurement scale requirements, compressing premium pricing power for legacy incumbents dependent on conventional cold-chain infrastructure.
Pricing Analysis
Short lead-time premiums dominate contract negotiations for temperature-controlled last-mile logistics in urban Australian and United States coastal corridors, while spot inventory of oat milk bases trades at discounts during Southeast Asian harvest peaks. Three-tier pricing structure across premium clean-label certified, standard reformulated, and economy conventional tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from F-Gas Regulation compliance costs forcing refrigeration retrofit investments. Price-sensitive mass-market supermarket buyers contrast with least-sensitive diabetic patient segments in German healthcare retail channels.
Supply Chain Analysis
Domestic-content mandates under China's SAMR alternative sweetener frameworks and India's FSSAI import standards are reshaping sourcing patterns toward regional allulose and monk fruit extract synthesis capacity. Geographic supply concentration centers on Chinese and Indian chemical manufacturers for alternative sweeteners, Southeast Asian agricultural zones for oat and coconut milk bases, and German-Italian refrigeration equipment suppliers. Raw material dependencies include allulose feedstocks, plant-based milk bases, and hydrofluorocarbon replacement refrigerants. Single-source vulnerability for allulose synthesis creates structural risk. Distribution runs through temperature-controlled supermarket refrigerated cases and direct-to-consumer subscription logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around clean-label certification capabilities, with EU Nutri-Score and FDA added-sugar disclosure timelines forcing undercapitalized reformulators toward exit or acquisition.
For Market Incumbents: Deploy precision fermentation platform licensing to defend margin position against emerging contract-manufactured protein entrants. Backward integration into oat milk base cultivation in Southeast Asian sourcing regions mitigates agricultural yield volatility threatening dairy-free portfolio stability. Channel control through exclusive refrigerated case placement agreements with United States and German supermarket chains limits subscription-model erosion.
For New Entrants and Emerging Players: ANVISA's added-sugar disclosure framework in Brazil opens a window for early compliance positioning ahead of enforcement tightening in Latin America's largest market. Target diabetic patient segments in Australian healthcare retail through clinical validation partnerships with endocrinology practices. Direct-to-consumer subscription mechanics with temperature-controlled last-mile logistics offer the most penetrable go-to-market angle for bypassing supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap clean-label specialists possessing fermentation platform capabilities given accelerating EU dairy nomenclature protection enforcement. Five-to-ten year viability favors brands with parallel FDA and EU regulatory submission track records rather than single-jurisdiction players. Acquisition target archetype: precision fermentation-enabled dessert manufacturers with established cold-chain partnerships. Signal to watch: ANVISA approval timeline acceleration as Brazilian enforcement commitment indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Licensing | Enables animal-free dairy protein incorporation bypassing traditional supply chain concentration in EU markets. |
| Cold-Chain Infrastructure Retrofit | F-Gas Regulation compliance secures operational continuity ahead of 2030 hydrofluorocarbon phaseout deadlines. |
| Direct-to-Consumer Subscription Launch | Captures full margin and customer data in Sydney, Los Angeles, and London urban corridors. |
| Clean-Label Certification Investment | EU Nutri-Score alignment commands premium shelf positioning in German and French retail chains. |
| Alternative Sweetener Supply Agreement | Long-term offtake contracts with Chinese and Indian manufacturers mitigate single-source vulnerability. |
Research Methodology
Document review covered FDA Nutrition Facts panel guidance, EU F-Gas Regulation implementation timelines, and ANVISA disclosure framework drafts, complemented by interviews with brand managers at multinational CPG houses, category buyers at United States and German supermarket chains, cold-chain logistics engineers, and regulatory affairs specialists. Secondary validation drew from customs records for alternative sweetener trade flows, Nielsen retail audit data for clean-label SKU placement, and SEC filings for refrigerated logistics infrastructure disclosures. Bottom-up demand modeling triangulated against top-down market sizing.
Segment-level projections across product type, distribution channel, application, and end user dimensions fed aggregate market estimates over the projection horizon. CAGRs were derived from regression analysis against diabetic population screening expansion rates, millennial and Gen Z purchasing cohort penetration curves, and alternative sweetener production scaling curves. Industry-specific forecast inputs included F-Gas Regulation compliance cost trajectories and precision fermentation platform commercialization timelines.
Caveats apply where SAMR alternative sweetener standard revisions, Southeast Asian agricultural yield disruptions, or F-Gas Regulation enforcement acceleration could materially shift the outlook. Forecasts reflect assumptions regarding regulatory alignment timelines and consumer willingness-to-pay for clean-label certification. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Sweet Spreads Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Cultures Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Super Foods Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Goldenseal Market