
 Soy Milk Market | 2026-2036
Soy Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Milk Market Analysis
The EU Green Deal's sustainable protein transition targets is consolidating demand toward plant-based dairy alternatives across European retail and food service channels. Danone S.A. leverages its specialized nutrition expertise to anchor premium fortified soy milk lines in continental European supermarkets. Vitasoy International Holdings Ltd sustains manufacturing scale advantages across Greater China and Southeast Asian export markets. SunOpta Inc. competes through organic ingredient sourcing and private-label contract manufacturing for North American retail banners.
Soy milk is an aqueous extract of soaked, ground, and filtered soybeans, typically containing 2-4% protein and 1-2% fat by weight, produced through either traditional stone milling or modern ultra-high-temperature processing for extended shelf stability. Its primary commercial purpose is to serve as a functional dairy alternative in beverages, cooking applications, and specialized nutrition products where emulsion stability and neutral flavor profiles are required. Organic product type commands margin premiums in European and North American health stores, while flavored variants drive volume in Asian convenience retail and food service channels. Online retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models and specialized health platforms expand refrigerated delivery infrastructure.
FDA nutrition labeling requirements and USDA organic certification standards govern product composition and marketing claims in the United States, while EFSA health claim regulations and EU organic labeling directives shape market access across European member states. China's SAMR food safety standards and GB national quality specifications additionally influence export-oriented manufacturers serving Asia-Pacific supply chains. Stakeholders must monitor evolving protein content thresholds and clean-label enforcement trends that will determine formulation investments and geographic prioritization.
Market Dynamics
Barista-grade formulation standards are restructuring procurement specifications across specialty coffee chains, forcing manufacturers to rebuild emulsion stability and foam retention capabilities from the ground up.
Growth Catalysts
- EU Green Deal protein transition targets:Binding sustainable protein quotas are redirecting institutional food service procurement toward plant-based dairy alternatives in Germany, France, and the Netherlands.
- Specialty coffee chain expansion:Third-wave coffee operators in Seoul, Melbourne, and London are mandating dedicated steam wand-compatible soy milk SKUs with neutral flavor profiles.
- Enzymatic debittering processes:Novel enzymatic treatments are eliminating beany off-notes that previously limited soy milk adoption in Western European beverage applications.
Market Restraints
- Organic soybean supply concentration:Certified organic soybean sourcing clusters in the US Midwest and Canadian prairies, creating price volatility during drought cycles.
- Ultra-high-temperature equipment capex thresholds:Aseptic filling lines require capital commitments that exclude smaller regional processors from extended-shelf-life segments.
- Oat milk substitution pressure:Barista-formulated oat alternatives are capturing menu slots in Scandinavian and UK coffee chains previously reserved for soy.
Strategic Opportunities
- Vietnamese food service penetration:Underdeveloped plant-based dairy infrastructure in Ho Chi Minh City and Hanoi creates first-mover positioning for fortified soy milk distributors.
- Direct-to-consumer refrigerated subscription:Cold-chain logistics investments enable bypass of traditional retail slotting fees in metropolitan Australian and Japanese markets.
- EFSA health claim authorization pathways:Pending approvals for cholesterol-reduction claims would unlock pharmacy channel placement across EU member states.
Industry Challenges
- Food technologist specialization gaps:Formulation expertise bridging traditional dairy science and plant protein functionality remains scarce in R&D departments.
- Dual organic-nonorganic production line segregation:USDA and EU organic certification requirements demand dedicated processing equipment that strains asset utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Milk Market |
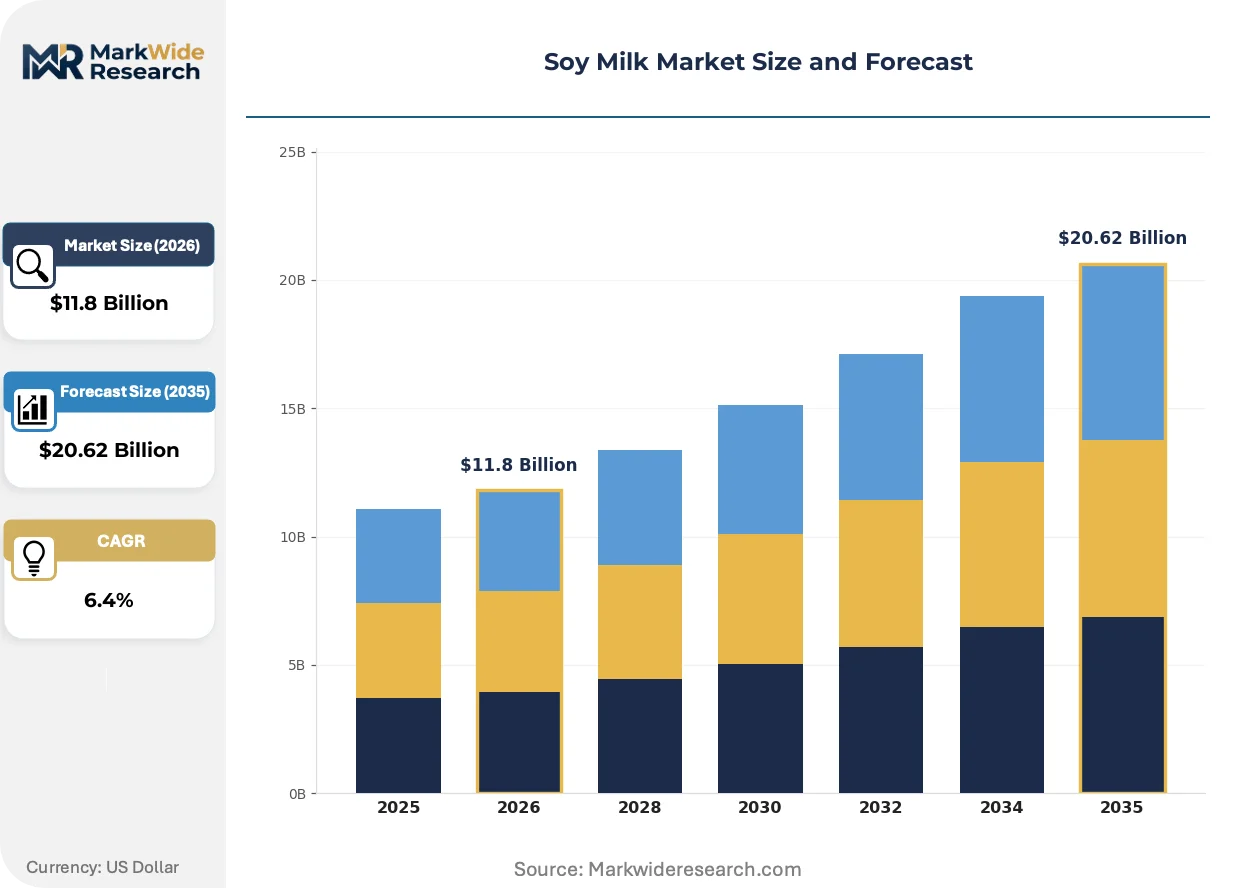
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
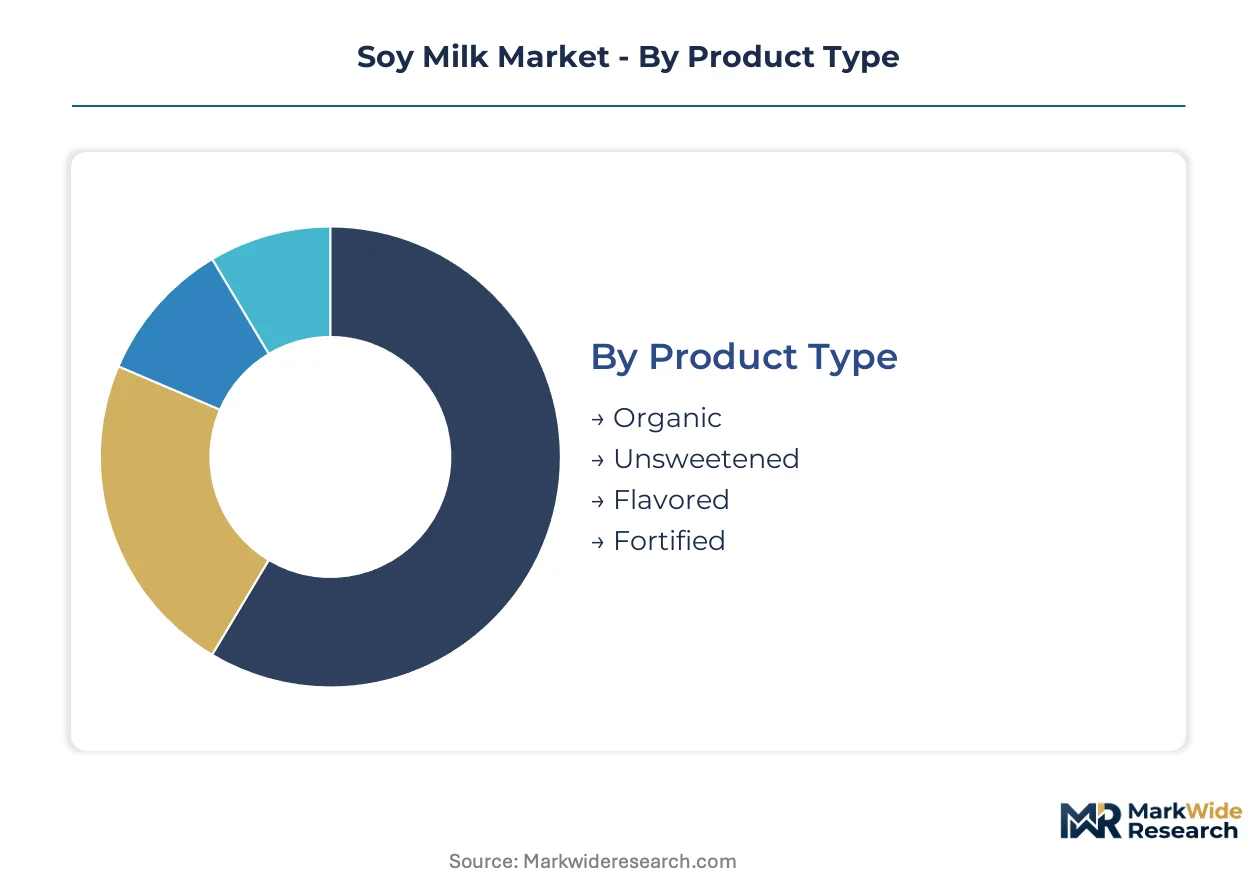
| Segmentation | Product Type: Organic, Unsweetened, Flavored, Fortified Distribution Channel: Supermarkets, Health Stores, Online Retailers, Food Service Use Case: Dietary Substitute, Cooking Ingredient, Smoothies, Beverages Customer Type: Health-Conscious Consumers, Lactose Intolerant, Vegans, Culinary Professionals |
| Companies Covered | Vitasoy International Holdings Ltd, Danone S.A., SunOpta Inc., The Hain Celestial Group, Inc., Kikkoman Corporation, Eden Foods Inc., Pacific Foods of Oregon, LLC, Earth’s Own Food Company Inc., Morinaga Milk Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Milk Market Emerging Trajectories
Processing technology convergence and regulatory claim frameworks are redefining what constitutes premium positioning in plant-based dairy alternatives.
High-pressure processing technology is consolidating quality assurance protocols across refrigerated soy milk segments. Cold-brew coffee chains in Portland and Sydney are adopting HPP-treated formulations to eliminate thermal degradation of protein structures. This shift is consolidating shelf-life extension capabilities among processors with capital-intensive HPP infrastructure, compressing margins for conventional UHT-dependent suppliers.
EFSA health claim substantiation requirements are tightening protein content thresholds for cholesterol-related marketing. Manufacturers must now maintain minimum 2.5% protein by weight and demonstrate LDL reduction efficacy through clinical trials. Fortified soy milk lines targeting pharmacy and clinical nutrition channels in Germany and Italy are reformulating to meet these evidentiary standards ahead of enforcement deadlines.
Specialty coffee operators are unbundling procurement decisions from centralized dairy contracts. Independent café owners in Copenhagen and Berlin are negotiating direct supply relationships with regional soy milk processors, bypassing traditional broadline food service distributors. This channel fragmentation is most pronounced in Nordic markets where barista training academies now specify preferred soy milk brands in certification curricula.
Soy Milk Market Segmentation
Soy milk formulation standards diverge sharply across consumption contexts, from clinical nutrition specifications to barista-grade emulsion requirements. Procurement channels impose distinct shelf-life, packaging, and certification demands that reshape manufacturing priorities. Understanding these segment boundaries clarifies where margin concentration and volume expansion opportunities separate.
Product Type:
Formulation chemistry and certification status define the technology axis for product differentiation.
- Organic:USDA and EU organic certification mandates segregated processing equipment and certified soybean sourcing clusters in the US Midwest and Canadian prairies. German health stores and North American natural food banners command 20-40% price premiums over conventional lines, though drought cycles in organic soybean regions create input cost volatility.
- Fortified:Calcium, vitamin D, and B12 enrichment targets clinical nutrition and pediatric dietary applications where micronutrient density determines reimbursement eligibility. Pharmacy channel placement in Italy and Germany depends on EFSA health claim substantiation for cholesterol reduction efficacy.
- Unsweetened:Neutral flavor profiles serve cooking applications and specialty coffee chains requiring steam wand compatibility without competing sweetness notes.
- Flavored:Vanilla, chocolate, and regional variants drive volume in Asian convenience retail and school nutrition programs where palatability overrides clean-label preferences.
Mature deployment sits with Unsweetened formulations in food service and cooking applications. Newer deployment is concentrated in Fortified lines targeting clinical nutrition channels.
Distribution Channel:
Channel economics and cold-chain infrastructure requirements create distinct margin structures.
- Supermarkets:Extended-shelf-life UHT formats dominate shelf placement in German discounters and Australian retail banners, where private-label expansion compresses branded margins. Slotting fees and promotional calendars favor manufacturers with national distribution scale.
- Online Retailers:Direct-to-consumer subscription models and specialized health platforms in metropolitan Australian and Japanese markets are climbing the fastest, bypassing traditional retail gatekeepers through refrigerated delivery infrastructure investments.
- Health Stores:Refrigerated organic and HPP-treated formats command premium positioning in North American and European natural food channels.
- Food Service:Barista-grade specifications with dedicated steam wand compatibility and foam retention capabilities dominate procurement in Seoul, Melbourne, and London specialty coffee chains.
Volume concentration remains with Supermarkets. Margin expansion is shifting toward Online Retailers.
Use Case:
Functional requirements and consumption occasions segment demand by performance specifications.
- Dietary Substitute:Complete nutrition profiles with protein content above 2.5% by weight serve lactose-intolerant consumers and pediatric dietary management in clinical settings.
- Cooking Ingredient:Heat-stable emulsions with neutral flavor profiles concentrate demand in East Asian household applications and Western plant-based recipe development.
- Smoothies:Creamy mouthfeel and blendability with frozen fruit drives adoption in fitness-oriented consumption occasions.
- Beverages:Ready-to-drink formats with extended ambient shelf life dominate vending and convenience retail in Southeast Asian urban corridors.
Established demand centers on Cooking Ingredient applications. Emerging formulation investment targets Dietary Substitute clinical nutrition specifications.
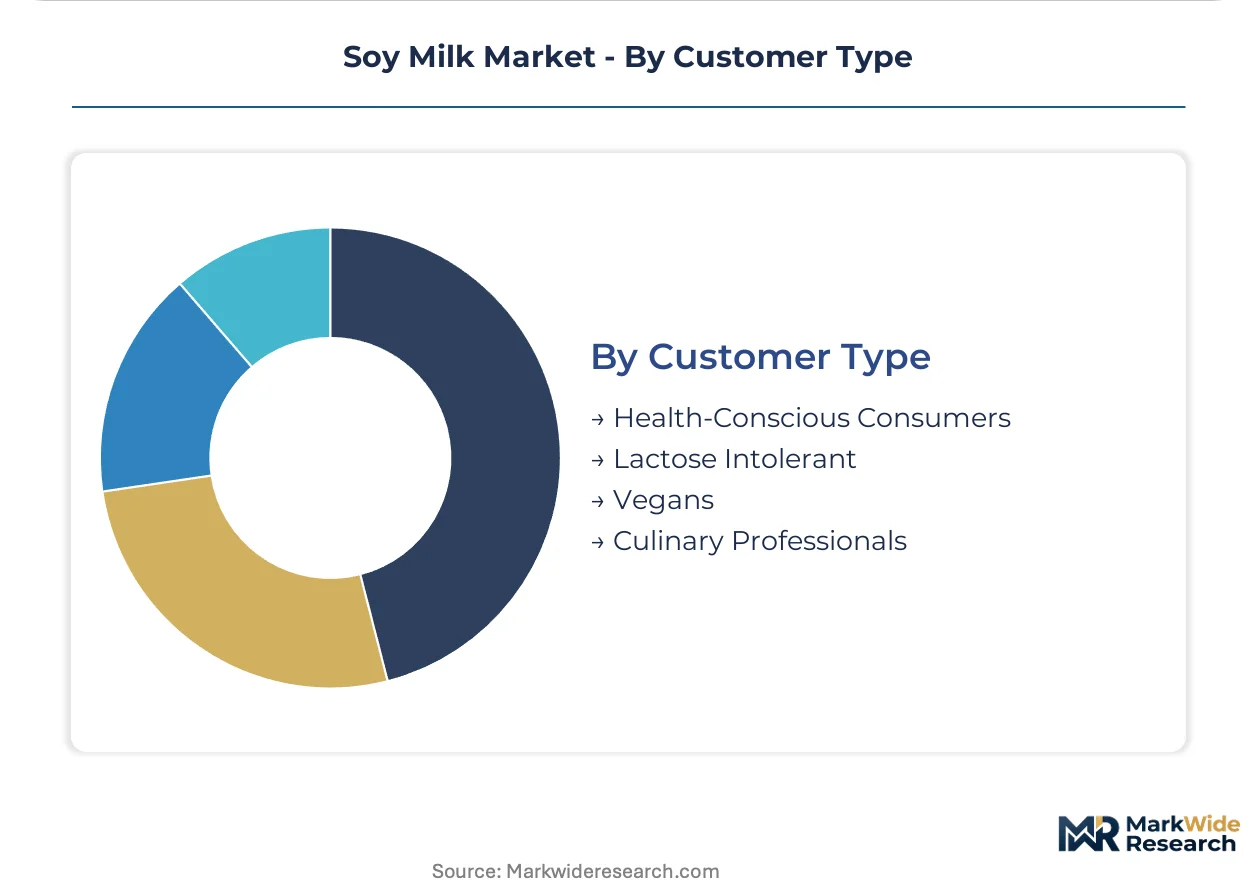
Customer Type:
Purchase motivation and nutritional knowledge level determine channel preference and price sensitivity.
- Health-Conscious Consumers:Clean-label scrutiny and organic certification awareness drive premium willingness in European and North American metropolitan markets.
- Lactose Intolerant:Digestive tolerance and calcium bioavailability specifications dominate purchase criteria in clinical and household contexts.
- Vegans:Ethical sourcing verification and complete amino acid profiles command loyalty in dedicated plant-based retail and subscription channels.
- Culinary Professionals:Consistent emulsion performance under thermal stress and neutral flavor neutrality determine procurement in restaurant and café operations.
Volume leadership rests with Health-Conscious Consumers. Fastest share gains are occurring among Culinary Professionals as barista-grade specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City's specialty coffee corridor is attracting barista-grade soy milk distributors seeking first-mover positioning in Vietnam's underdeveloped plant-based dairy infrastructure.
Germany
Food service operators and retail discounters are expanding private-label soy milk portfolios to meet EU Green Deal protein transition targets. EFSA health claim regulations shape fortified product formulations targeting pharmacy channel placement. Berlin-Brandenburg anchors clinical nutrition procurement for cholesterol-reduction certified lines.
United States
FDA nutrition labeling requirements and USDA organic certification standards govern product composition across extended-shelf-life segments. Health-conscious consumers in metropolitan markets drive refrigerated HPP-treated format adoption. Portland's cold-brew coffee chains specify enzymatically debittered formulations for neutral flavor profiles.
China
SAMR food safety standards and GB national quality specifications influence manufacturing protocols for domestic and export-oriented production. Vitasoy International Holdings Ltd sustains manufacturing scale advantages across Greater China. Yangtze River Delta processing clusters supply Southeast Asian export markets with UHT-stable formulations.
Australia
Direct-to-consumer refrigerated subscription models are bypassing traditional retail slotting fees in metropolitan Sydney and Melbourne markets. Online retailers represent the fastest-growing distribution channel through specialized health platform expansion. Third-wave coffee operators mandate dedicated steam wand-compatible SKUs with foam retention capabilities.
Japan
METI industrial policy supports plant-based protein diversification in food service channels. Cold-chain logistics investments enable metropolitan refrigerated delivery infrastructure for subscription services. Tokyo's specialty coffee academies specify preferred soy milk brands in barista certification curricula.
Soy Milk Market Vendor Landscape
The competitive structure tilts toward diversified nutrition conglomerates with specialized plant-based portfolios. Tiered positioning separates premium fortified clinical nutrition lines from private-label contract manufacturing operations. Three archetypes dominate: pan-Asian beverage specialists, North American organic ingredient sourcers, and European dairy-alternative nutrition leaders. Geographic expansion through regional manufacturing partnerships and enzymatic processing technology licensing constitute the primary competitive vectors.
Among Asia-Pacific headquartered beverage specialists, Vitasoy International Holdings Ltd exemplifies scale-driven manufacturing consolidation across Greater China and Southeast Asian export corridors. Danone S.A. occupies a position within the European nutrition conglomerate archetype, leveraging specialized nutrition expertise for continental European supermarket placement. SunOpta Inc. represents the North American organic ingredient sourcing and private-label contract manufacturing segment, competing through certified supply chain control for retail banner relationships.
| Leading Market Players |
|---|
| Vitasoy International Holdings Ltd |
| Danone S.A. |
| SunOpta Inc. |
| The Hain Celestial Group, Inc. |
| Kikkoman Corporation |
| Eden Foods Inc. |
| Pacific Foods of Oregon, LLC |
| Earth's Own Food Company Inc. |
| Morinaga Milk Industry Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Barista-grade formulation mandates from specialty coffee chains in Seoul, Melbourne, and London are forcing manufacturers to rebuild emulsion stability capabilities from the ground up, compressing margins for conventional processors while concentrating pricing power among enzymatic debittering technology holders.
Pricing Analysis
Outcome-based pricing anchors on foam retention performance and steam wand compatibility metrics that determine menu placement in third-wave coffee operations. Three-tier pricing structure across premium fortified clinical nutrition, standard UHT food service, and economy private-label retail separates organic certified lines commanding 20-40% premiums from conventional bulk supply. Cost compression in standard UHT tiers is intensifying because German and Australian retail discounters are expanding private-label portfolios. Health-conscious consumers in metropolitan North American and European markets exhibit lowest price sensitivity, while Asian convenience retail channels demonstrate highest elasticity to volume discounts.
Supply Chain Analysis
EU Green Deal domestic-content requirements for sustainable protein transition are redirecting soybean sourcing toward certified organic clusters in the US Midwest and Canadian prairies. Certified organic soybean supply, aseptic UHT filling equipment, and refrigerated cold-chain logistics constitute critical input dependencies. Single-source vulnerability concentrates in organic soybean regions exposed to drought-induced price volatility. Distribution runs through broadline food service distributors in developed markets, though direct-to-consumer refrigerated subscription models are bypassing traditional gatekeepers in Australian and Japanese metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic soybean supply concentration in drought-exposed regions props pricing premiums, creating a supply-constrained market structure where certified sourcing capabilities determine competitive viability.
For Market Incumbents: Anchor barista-grade formulation leadership through enzymatic debittering technology licensing to defend against oat milk substitution pressure in Scandinavian and UK coffee chains. Pursue backward integration into certified organic soybean sourcing clusters to secure input cost stability against drought cycles. Prioritize EFSA health claim substantiation investments for cholesterol-reduction certification enabling pharmacy channel placement in Germany and Italy. For New Entrants and Emerging Players: Launch via direct-to-consumer refrigerated subscription models in Ho Chi Minh City and Hanoi to exploit underdeveloped Vietnamese plant-based dairy infrastructure. Target Vietnamese food service penetration as the most penetrable white space, leveraging first-mover positioning before broadline distributors establish procurement relationships. Pursue enzymatic processing technology partnerships rather than capital-intensive UHT equipment investments. For Investors and Strategic Acquirers: The window for entry favors regional processors with certified organic supply chain control and barista-grade formulation capabilities. Long-term viability hinges on exposure to clinical nutrition and specialty coffee channels rather than commoditized private-label retail. Monitor EFSA health claim authorization timelines as the critical inflection signal for pharmacy channel revenue potential across EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Debittering Technology Licensing | Neutral flavor profiles unlock Western European beverage applications previously limited by beany off-notes. |
| Certified Organic Supply Chain Integration | USDA and EU organic certification mandates create defensible margin premiums in health store channels. |
| Direct-to-Consumer Refrigerated Subscription Launch | Metropolitan Australian and Japanese markets enable bypass of traditional retail slotting fees. |
| EFSA Health Claim Authorization Pursuit | Cholesterol-reduction certification unlocks pharmacy placement in Germany and Italy. |
| Barista Academy Certification Partnership | Tokyo and Melbourne coffee training curricula specify preferred brands in procurement decisions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant-based dairy R&D directors, food service procurement managers at specialty coffee chains, organic certification auditors, UHT equipment manufacturers, and refrigerated logistics operators. FDA nutrition labeling guidance, EFSA health claim substantiation protocols, SAMR GB standards documentation, and EU Green Deal implementation frameworks provided regulatory boundary conditions. Bottom-up volume modeling across formulation tiers and top-down value reconciliation against retail audit data ensured cross-validation integrity.
Data-stream reconciliation merged production capacity surveys with channel shipment patterns and end-user consumption metrics across the projection horizon. Segmentation dimensions encompassed product certification status, distribution channel economics, use case functional requirements, and customer motivation archetypes. CAGRs derived from trend extrapolation of protein transition policy targets, specialty coffee outlet expansion rates, and enzymatic processing technology adoption curves. Forecast inputs incorporated organic soybean yield volatility indices and barista-grade specification proliferation timelines.
Regulatory enforcement delays, organic supply disruption events, and oat milk substitution acceleration are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions regarding EFSA authorization timelines and EU Green Deal procurement mandate implementation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Peanut Milk Market