
 Savory Yogurt Market | 2026-2036
Savory Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Savory Yogurt Market Outlook
Restaurant chain procurement consolidation is repositioning volume toward contract suppliers with national distribution networks. Nestlé leverages its dairy processing scale to serve centralized kitchen contracts across multiple markets. Chobani differentiates through chef-collaboration programs that embed savory yogurt into menu development. Sohha Savory Yogurt specializes in small-batch herbed formulations that occupy the premium independent restaurant segment.
Savory yogurt denotes cultured dairy or plant-based products formulated with salt, herbs, spices, or umami agents rather than fruit or sweeteners, typically maintaining live bacterial cultures and protein contents between 8 grams and 20 grams per serving depending on straining method and milk source. Greek formulations lead current manufacturing throughput due to their structural stability in hot applications, while plant-based alternatives represent the fastest-expanding margin pool as oat and coconut bases achieve comparable mouthfeel. Herbed flavor profiles capture the largest share of foodservice procurement, though umami-forward variants are gaining traction in East Asian-inspired menu applications.
The FDA oversees acidified food regulations that determine thermal processing requirements for shelf-stable savory yogurt exports into the United States, while EFSA and national EU regulators enforce labeling standards for live culture claims and plant-based dairy alternatives. India's FSSAI recently tightened microbiological standards for cultured products containing savory additives, affecting import clearance timelines. Stakeholders must monitor evolving divergence between pasteurized and raw-milk fermentation allowances as classification determines both market access and premium positioning potential.
Market Dynamics
Restaurant chain procurement consolidation is compressing supplier margins while favoring contract manufacturers with national cold-chain distribution networks and centralized kitchen integration capabilities.
Growth Catalysts
- Clean-label fermentation protocols:EFSA labeling standards for live culture claims are accelerating R&D investment in verified probiotic stability across shelf-stable formats.
- Urban foodservice hub density:Concentrated demand clusters in Mumbai, Berlin, and Los Angeles are pulling volume toward regional dairy processors with chef-direct technical service teams.
- Plant-based protein advances:Oat and coconut base formulation breakthroughs are expanding addressable market into vegan and flexitarian menu categories previously closed to dairy.
Market Restraints
- Input cost volatility:Organic herb and spice sourcing faces weather-driven price swings from Mediterranean and Indian growing regions.
- Supply concentration risk:Greek yogurt straining equipment manufacturing concentrates in northern Italian and Bavarian machinery suppliers.
- Regulatory friction:FDA acidified food thermal processing requirements create extended clearance timelines for shelf-stable export formats.
Strategic Opportunities
- Underpenetrated institutional channels:K-12 school nutrition programs and hospital foodservice represent untapped volume for protein-forward savory yogurt cup formats.
- Technology convergence:Precision fermentation combined with AI-driven flavor mapping is enabling rapid umami profile optimization without traditional aging.
- Direct-to-chef distribution:Specialty food distributors with culinary education programs are bypassing broadline intermediaries in independent restaurant segments.
Industry Challenges
- Microbiological certification timelines:India's FSSAI tightened standards for savory additive cultures are extending batch release protocols.
- Cold-chain capex intensity:Live culture maintenance requires continuous refrigeration investment from production through foodservice delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savory Yogurt Market |
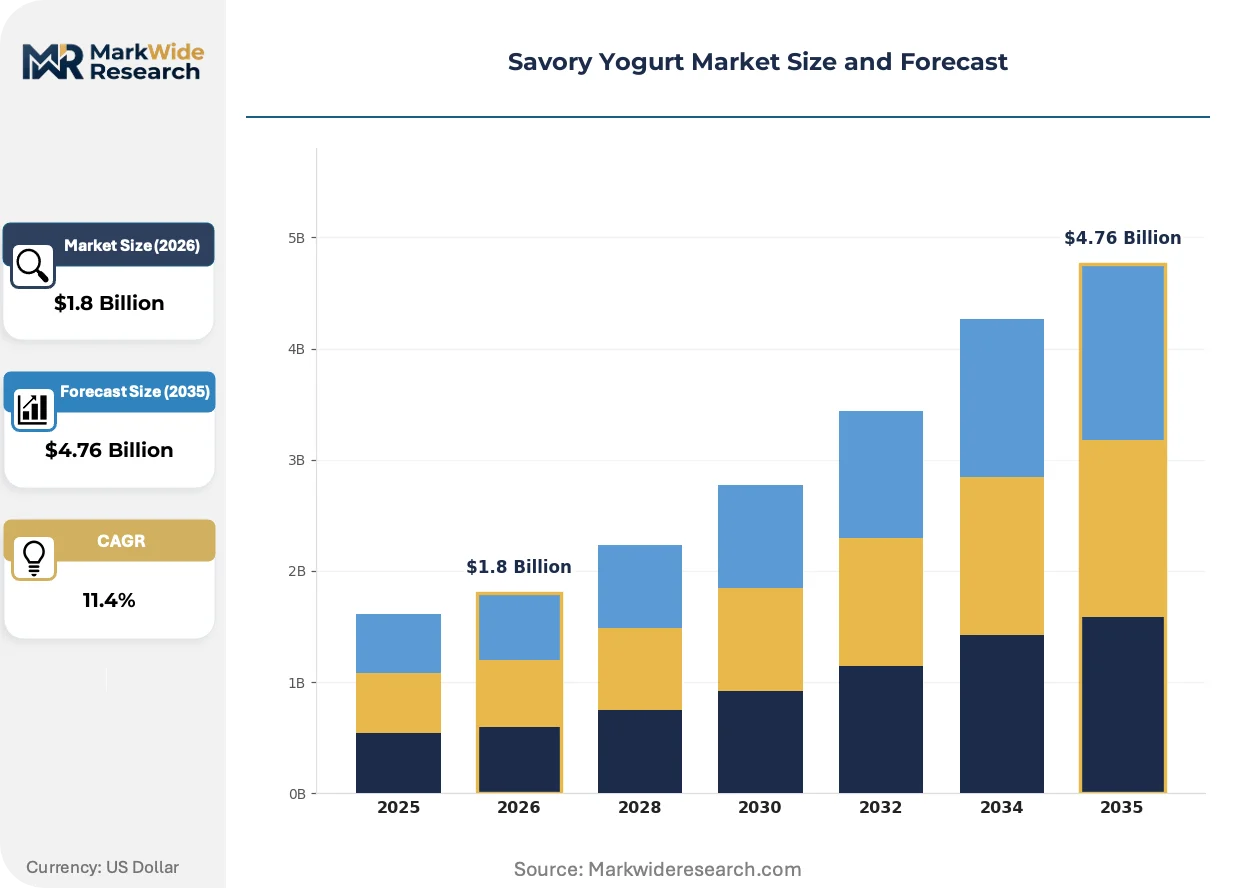
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek, Plant-Based, Drinkable, Traditional Flavor Profile: Herbed, Spicy, Umami, Savory-Sweet Packaging Type: Tub, Sachet, Bottle, Cup End User: Restaurant, Retailer, Catering, Home Consumer |
| Companies Covered | Fage International, Stonyfield Farm, Nestlé, La Terra Fina, Sohha Savory Yogurt, Danone, General Mills, Wallaby Yogurt Company, Chobani, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savory Yogurt Market Strategic Shifts
Active reformulation of base substrates and fermentation protocols is compressing product development cycles while expanding temperature tolerance for hot-application menu integration.
Precision fermentation using non-dairy substrates is electrifying texture engineering in plant-based savory yogurt. Fast-casual chains in California and New York are piloting these formats for hot bowl applications. The technology is electrifying margin expansion previously locked behind dairy commodity pricing structures.
REACH chemical safety standards are tightening scrutiny on flavoring additives and processing aids used in herbed formulations. Manufacturers reformulating for compliance are accelerating natural extract substitution programs. European export-oriented suppliers face the steepest reformulation cost curves.
Chef-collaborative menu development is replacing traditional broker-driven sampling programs. Independent restaurant operators now expect co-development relationships with technical dairy specialists. This pattern concentrates in coastal United States urban clusters with established farm-to-table supply infrastructure.
Savory Yogurt Market Segmentation
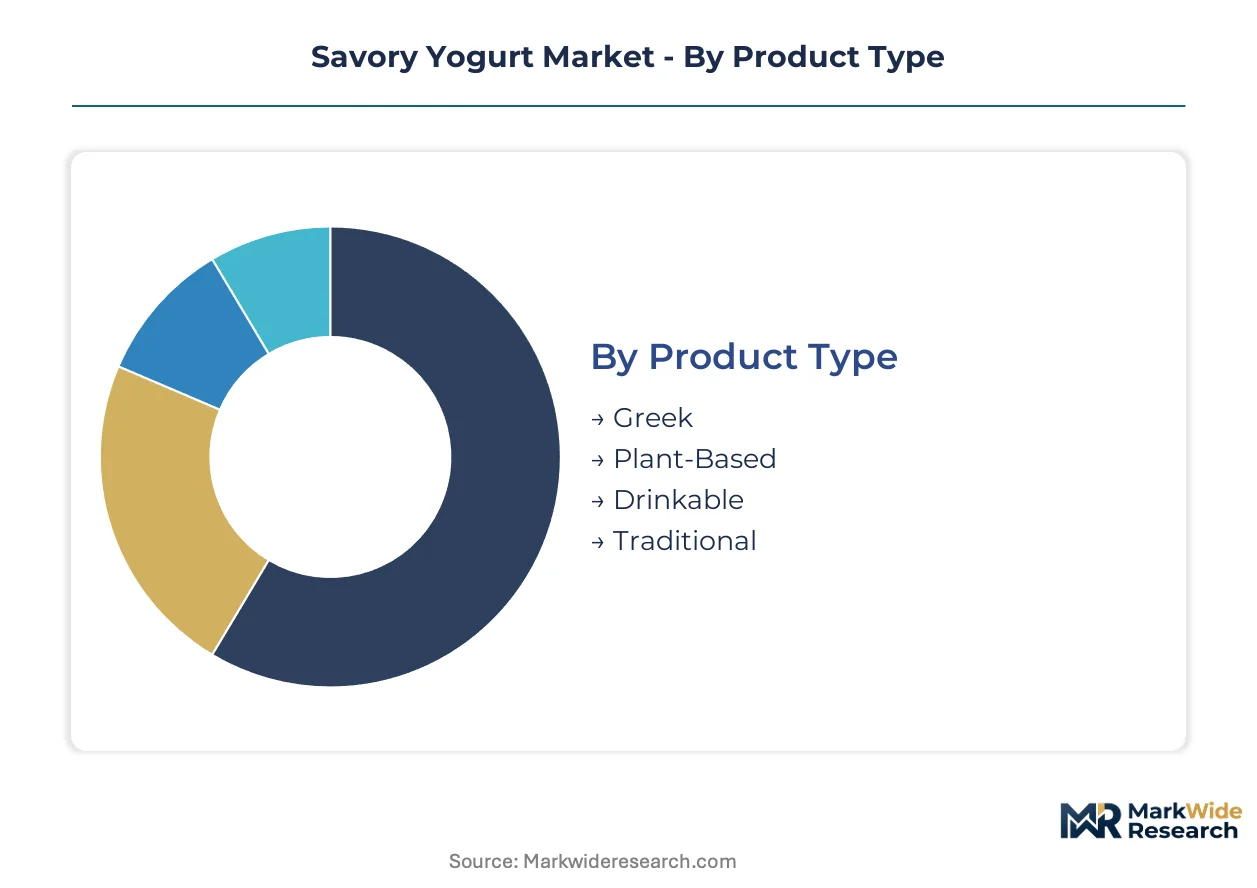
Savory yogurt manufacturers configure production lines around structural stability requirements and cold-chain economics. Segment boundaries determine margin capture, with foodservice procurement favoring bulk formats while retail channels demand single-serve convenience. Each dimension carries distinct regulatory footprints and shelf-life engineering constraints.
Product Type:
Greek formulations command premium positioning through straining intensity, while plant-based alternatives disrupt commodity dairy pricing with precision fermentation advances.
- Greek:Strained to 8-20 grams protein per serving with structural integrity that withstands hot bowl applications. Demand clusters in Los Angeles and Berlin fast-casual chains where kitchen staff use it as a marinade base. EFSA live culture verification requirements favor established processors with in-house microbiology labs.
- Plant-Based:Oat and coconut substrates achieve mouthfeel parity through enzymatic texture engineering. Mumbai vegan restaurant clusters and California flexitarian menus pull volume fastest. REACH chemical safety standards on flavoring additives create reformulation cost curves for European export suppliers.
- Drinkable:Lower viscosity formats for beverage applications and sauce thinning.
- Traditional:Unstrained cultured dairy maintaining regional fermentation heritage profiles.
Today's leader: Greek. Tomorrow's challenger: Plant-Based.
Flavor Profile:
Herb sourcing geography determines cost volatility, while umami development cycles separate premium positioning from commodity alternatives.
- Herbed:Dill, mint, and za'atar formulations dominate foodservice procurement volumes. Mediterranean and Indian growing regions supply raw botanicals with weather-driven price swings. FDA acidified food thermal processing requirements extend shelf-stable export timelines for herbed variants.
- Umami:Miso, tamari, and fermented mushroom extracts enable East Asian menu integration. Precision fermentation compresses aging cycles from months to days. Fast-casual chains in New York and California pilot these formats for hot application stability.
- Spicy:Chili and pepper-based heat profiles for Latin American and South Asian menu applications.
- Savory-Sweet:Hybrid formulations bridging dessert and appetizer categories for flexible menu placement.
Herbed captures current procurement volumes; umami profiles are climbing the fastest as chef-collaboration programs expand.
Packaging Type:
Foodservice scale favors bulk formats with pump dispensing, while retail channels optimize for single-serve portability and resealability.
- Tub:Multi-serve containers dominate restaurant back-of-house procurement with portion-control economics. National distribution networks with centralized kitchen integration capabilities favor this format. Cold-chain capex intensity concentrates supplier selection on refrigerated logistics specialists.
- Sachet:Single-serve portions for airline catering and institutional channels with precise portion control requirements.
- Bottle:Pourable formats for sauce and dressing applications in fast-casual assembly lines.
- Cup:Retail-ready single serves with live culture maintenance through continuous refrigeration.
Tub formats anchor foodservice volume; bottle configurations are gaining share fastest in fast-casual automation.
End User:
Procurement consolidation across restaurant chains compresses supplier margins while independent operators demand technical service depth.
- Restaurant:Chain procurement consolidation favors contract manufacturers with national cold-chain networks. Chef-collaboration programs now replace traditional broker sampling. Coastal United States urban clusters with farm-to-table infrastructure concentrate co-development relationships.
- Retailer:Clean-label fermentation protocols and verified probiotic stability drive shelf placement decisions.
- Catering:Volume events and institutional feeding require portion-controlled formats with extended hold times.
- Home Consumer:Premium small-batch herbed formulations occupy specialty retail and direct-to-consumer channels.
Restaurant channels command current volume concentration; K-12 school nutrition programs represent the steepest expansion trajectory for protein-forward cup formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States foodservice procurement consolidation outpaces Germany's chef-collaboration density, while India's regulatory tightening creates divergent clearance timelines for savory yogurt exporters. Urban demand clusters in Los Angeles, Berlin, and Mumbai reshape regional processor selection criteria.
United States
Fast-casual chains in Los Angeles and New York pilot hot-bowl applications with structural-stable Greek formulations. FDA acidified food regulations determine thermal processing requirements for shelf-stable exports. Coastal urban clusters with farm-to-table infrastructure concentrate chef-direct technical service relationships.
Germany
EFSA live culture verification standards accelerate R&D investment in verified probiotic stability across Berlin fast-casual procurement. REACH chemical safety standards tighten scrutiny on herbed formulation additives. Bavarian machinery suppliers concentrate Greek yogurt straining equipment manufacturing.
India
Mumbai vegan restaurant clusters pull volume fastest for oat and coconut base alternatives. FSSAI tightened microbiological standards for savory additive cultures extend batch release protocols. Urban foodservice hub density concentrates demand around regional dairy processors with technical service teams.
France
ANSM oversight of novel food additives intersects with EFSA labeling standards for plant-based dairy alternatives. Mediterranean herb sourcing corridors face weather-driven price volatility. Parisian independent restaurant segments demand co-development relationships with technical dairy specialists.
Canada
Health Canada dairy alternative classification determines market access for precision-fermented oat bases. Cold-chain capex intensity favors refrigerated logistics specialists with national distribution networks. Toronto and Vancouver urban foodservice hubs pull volume toward contract manufacturers with centralized kitchen integration.
Savory Yogurt Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement tiers. Consolidation concentrates around contract manufacturers with national cold-chain networks and centralized kitchen capabilities. Three archetypes dominate: multinational dairy processors leveraging scale, chef-collaboration specialists embedding technical service, and small-batch herbed formulators occupying premium independent segments. M&A activity targets regional dairy processors with live-culture certification infrastructure, while capacity expansion concentrates in oat and coconut base fermentation facilities.
Within the multinational tier, Nestlé and Danone exemplify diversified conglomerates with dairy processing scale serving centralized kitchen contracts. Chobani occupies a position bridging chef-collaboration programs with national distribution reach. Sohha Savory Yogurt anchors the premium independent segment through small-batch herbed formulations. These three represent distinct strategic postures: scale-driven contract manufacturing, technical service embedding, and artisanal positioning.
| Leading Market Players |
|---|
| Fage International |
| Stonyfield Farm |
| Nestlé |
| La Terra Fina |
| Sohha Savory Yogurt |
| Danone |
| General Mills |
| Wallaby Yogurt Company |
| Chobani |
| Others |
Value Chain & Pricing Dynamics
Family-owned Mediterranean herb suppliers and private-equity-consolidated dairy processors anchor supply behavior, translating weather-driven botanical volatility into tiered contract structures that discipline pricing across premium and commodity tiers.
Pricing Analysis
Capacity additions in oat and coconut base fermentation facilities are reshaping price floors for plant-based alternatives. Three-tier pricing structure across premium, standard, and economy levels separates small-batch herbed formulations from contract-manufactured Greek yogurt and private-label commodity alternatives. Cost compression in foodservice bulk formats is intensifying because restaurant chain procurement consolidation favors national distributors with refrigerated logistics scale. K-12 school nutrition programs exhibit highest price sensitivity, while coastal independent restaurants with chef-collaboration programs absorb premium positioning.
Supply Chain Analysis
Organic herb sourcing rests on Mediterranean and Indian growing regions with weather-driven yield variability. Raw material dependencies include Greek yogurt straining equipment from northern Italian and Bavarian machinery suppliers, live culture strains from specialized fermentation labs, and oat base substrates from North American grain processors. Single-source vulnerability concentrates in Greek yogurt straining equipment manufacturing. Distribution runs through refrigerated logistics specialists with national cold-chain networks serving centralized kitchen contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Savory yogurt constitutes a late-cycle quality story as chef-collaboration programs pull procurement toward verified live culture claims and clean-label fermentation protocols that command specification premiums.
For Market Incumbents: Acquire regional dairy processors with FSSAI-certified live culture infrastructure to defend against contract manufacturer margin compression. Consolidate backward integration into organic herb sourcing corridors in Mediterranean growing regions to stabilize input cost volatility. EFSA labeling standard divergence between pasteurized and raw-milk fermentation allowances creates certification investment leverage. For New Entrants and Emerging Players: REACH chemical safety standards in Europe open a window for natural extract substitution programs targeting export-oriented reformulation demand. Precision fermentation capabilities in oat and coconut bases represent the most penetrable white-space for vegan fast-casual procurement in California and New York. Direct-to-chef distribution with embedded technical service bypasses broadline intermediary concentration. For Investors and Strategic Acquirers: Valuations sit cheapest among regional dairy processors with chef-direct technical service teams and live-culture certification infrastructure. Long-term viability hinges on plant-based protein advance capture and precision fermentation scale economics. Watch FSSAI microbiological clearance timeline divergence as inflection indicator for import-dependent market access.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables oat and coconut base mouthfeel parity with dairy commodity cost structures. |
| Chef-Collaboration Program Expansion | Embeds savory yogurt into menu development pipelines across Los Angeles and Berlin fast-casual chains. |
| Backward Integration into Herb Sourcing | Captures Mediterranean and Indian growing region supply through direct agricultural partnerships. |
| Live Culture Certification Investment | Secures EFSA verification and FSSAI clearance for premium positioning in regulated export markets. |
| Refrigerated Logistics Network Buildout | Supports national cold-chain distribution for centralized kitchen contract fulfillment. |
Study Parameters
Bottom-up foodservice procurement modeling reconciled against top-down dairy processing capacity tracking forms the analytical core. Primary interviews with restaurant chain procurement directors, chef-collaboration program managers, regional dairy processor technical specialists, and refrigerated logistics operators combined with secondary validation against FDA acidified food regulations, EFSA labeling standards, FSSAI microbiological guidelines, and customs trade data. Triangulation across these sources ensures segment-level volume reconciliation.
Input-output matrices map Greek straining intensity, plant-based substrate formulation, and herbed additive concentration against end-use channel requirements across the projection horizon. Segmentation dimensions include product type, flavor profile, packaging configuration, and end-user procurement tier. CAGRs derive from fitted growth curves calibrated to urban foodservice hub density and regulatory clearance timeline assumptions. Precision fermentation adoption curves and clean-label protocol penetration serve as industry-specific forecast inputs.
Revisions become necessary when FSSAI regulatory tightening accelerates, EFSA live culture verification standards diverge from FDA acidified food frameworks, or oat base substrate supply concentrates beyond current North American sourcing patterns. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market