
 Non-Dairy Cheese Market | 2026-2036
Non-Dairy Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Dairy Cheese Market Outlook
Premium artisan non-dairy cheese is consolidating around cultured cashew and fermented nut bases while commodity segments compete on price with starch-heavy, oil-based formulations. Miyoko's Creamery leverages live cultures and European-style aging to sustain its position in the refrigerated specialty case. Flora Food Group anchors the mass-market channel through retail partnerships across multiple continents. Daiya Foods differentiates via broad foodservice distribution and pizza-chain supply contracts.
Non-dairy cheese denotes plant-based alternatives engineered to replicate the texture, melt profile, and flavor release of fermented milk cheese through protein extraction, emulsification, and enzymatic or bacterial culturing of bases such as cashews, almonds, or soy isolates. Cream cheese and shreds dominate current volume as bagel chains and pizza operators standardize plant-based offerings, while blocks remain a smaller margin pool concentrated in specialty retail. Coconut oil and cashew bases lead formulation innovation for melt and stretch, though soy protein retains cost advantages in private-label production.
FDA standards of identity for cheese analogs, EFSA novel food approvals for fermented proteins, and USDA organic certification requirements collectively shape ingredient sourcing transparency and cross-border market access. The EU Green Deal's farm-to-fork targets are pressuring conventional dairy pricing, indirectly widening the competitive window for plant-based alternatives. Stakeholders must monitor fermentation technology patents and shifting retailer private-label strategies as the primary vectors of margin compression or expansion.
Market Dynamics
Fermentation technology patents and shifting retailer private-label strategies are compressing margins for branded non-dairy cheese while opening white space for ingredient suppliers with proprietary culture libraries.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Conventional dairy pricing pressures in Germany and the Netherlands are widening the competitive window for plant-based alternatives in foodservice procurement.
- Pizza-chain standardization:Fast-casual operators across the United States are locking in multi-year supply contracts for melt-optimized shreds, creating volume anchors for formulation scale.
- Cultured cashew bases:Live fermentation processes are delivering stretch and umami profiles that narrow the sensory gap with dairy cheese in refrigerated specialty cases.
Market Restraints
- Cashew supply concentration:Vietnam and India dominate raw cashew processing, exposing formulations to commodity price swings and tariff friction.
- FDA standards of identity:Labeling restrictions on dairy terms create retail placement friction and limit direct comparison marketing in US grocery.
- Starch-heavy commodity competition:Low-cost oil-and-starch formulations from private-label suppliers are anchoring price floors below sustainable production costs for premium players.
Strategic Opportunities
- Fermented protein novel food approvals:EFSA clearance pathways for precision-fermented casein analogs are creating first-mover windows for European production facilities.
- Bagel chain expansion:Cream cheese analog placement is penetrating morning-daypart menus in the United Kingdom and Australia as QSR operators diversify protein options.
- Direct-to-foodservice channels:Bypassing retail slotting fees through pizza-chain and stadium concession partnerships is rebuilding margin structures for mid-scale producers.
Industry Challenges
- Fermentation scale-up capex:Bioreactor infrastructure and sterile culture maintenance demand capital intensity that strains venture-backed balance sheets.
- Clean-label certification timelines:USDA organic and Non-GMO Project verification cycles extend go-to-market schedules by 8-14 months for new SKUs.
- Enzyme IP fragmentation:Patent thickets around microbial transglutaminase and lipase applications are forcing licensing negotiations that erode R&D efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Dairy Cheese Market |
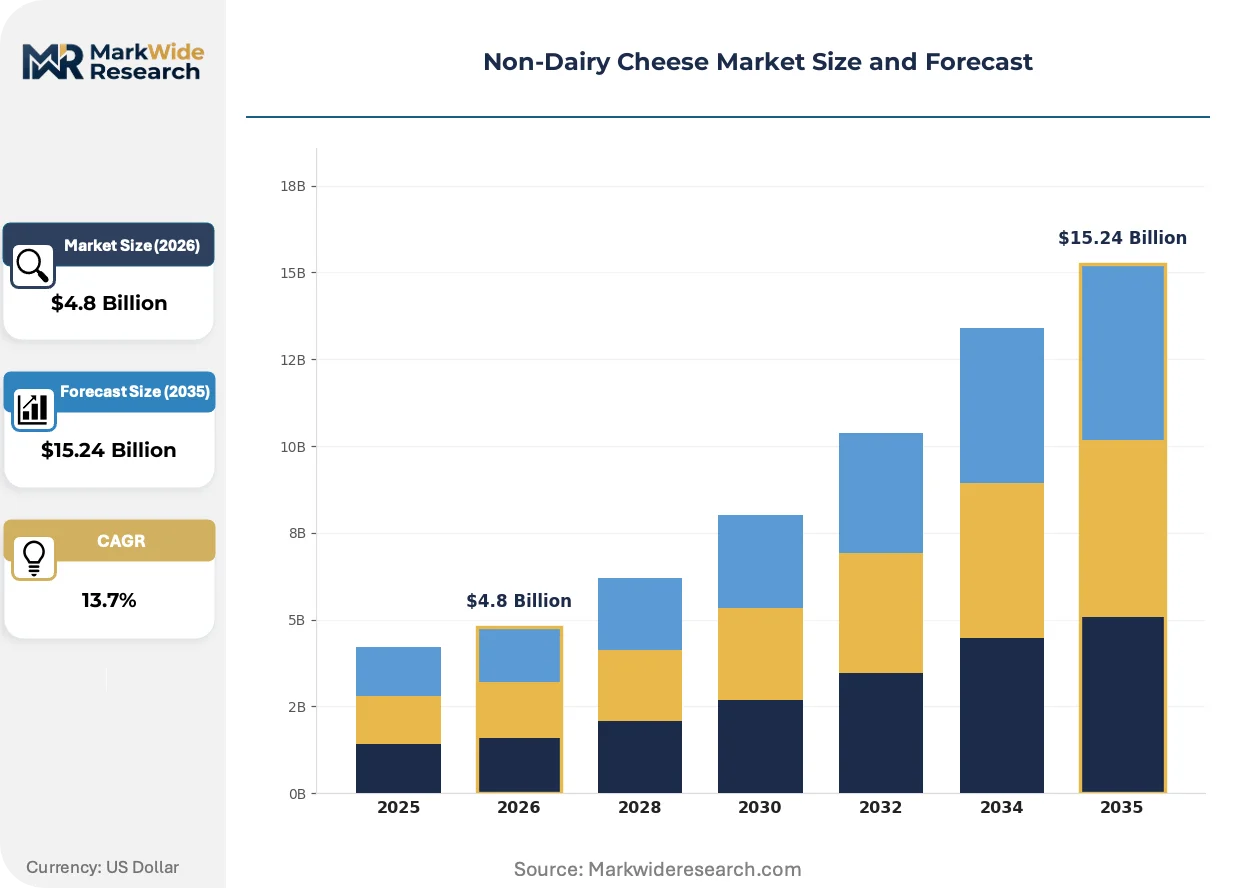
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Cheese, Slices, Shreds, Blocks Base Ingredient: Coconut Oil, Almond Milk, Soy Protein, Cashews Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Customer Type: Vegan Consumers, Lactose Intolerant, Health-Conscious Adults, Culinary Professionals |
| Companies Covered | Daiya Foods (Otsuka Holdings), Flora Food Group, Miyoko's Creamery, Kite Hill, Danone (Follow Your Heart), Saputo (Vitalite), Bel Group (Nurishh, Boursin Plant-Based), Treeline Cheese, Tofutti Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Dairy Cheese Market Strategic Shifts
Precision fermentation and enzymatic protein modification are converging to deliver functional parity with dairy cheese, while regulatory clarity and buyer procurement evolution reshape competitive entry points.
Precision fermentation of dairy-identical proteins is rewriting the technical foundation of melt and stretch performance. Specialty pizza operators in the United States and Germany are piloting these ingredients at 10,000-unit scale. The technology is compressing the premium-commodity price gap by enabling cost structures competitive with mass-market analogs.
EFSA novel food approval frameworks for fermented proteins are tightening safety documentation requirements while accelerating pathway transparency. European producers are restructuring regulatory affairs teams to parallel-track dossier preparation with product development. Block cheese formats targeting German and French retail are most affected, with reformulation cycles compressing to 18-month windows.
Foodservice procurement consolidation around sustainability metrics is displacing ingredient-agnostic sourcing. Large contract caterers in the United Kingdom and Netherlands are embedding Scope 3 emissions thresholds into supplier scorecards. This shift is most visible in university and corporate dining contracts, where plant-based cheese specifications now mandate cashew traceability and fermentation energy disclosure.
Non-Dairy Cheese Market Segmentation
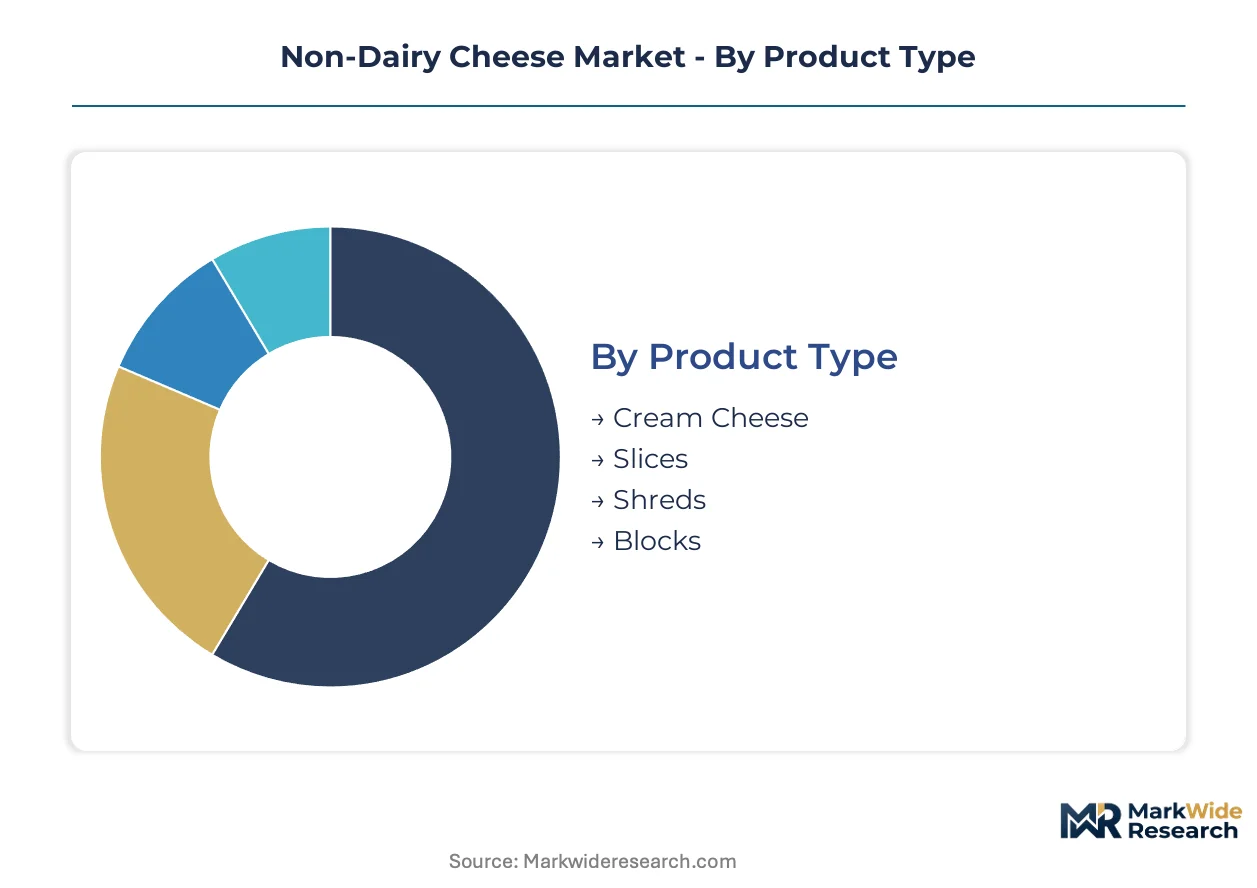
Non-dairy cheese segments diverge sharply between standalone retail formats and embedded foodservice applications. Understanding these integration patterns reveals where formulation investments concentrate and where margin structures differ.
Product Type:
Cream cheese and shreds operate as embedded ingredients in prepared foods, while slices and blocks compete as standalone center-of-plate items with distinct technical requirements.
- Cream Cheese:Spreadable analogs rely on cultured cashew bases and coconut oil emulsions to replicate mouthfeel. Bagel chains in the United States and United Kingdom anchor procurement volumes as morning-daypart menus standardize plant-based options.
- Shreds:Melt-optimized formulations using modified starches and enzymatically treated proteins target pizza-chain specifications. Fast-casual operators lock multi-year supply contracts, creating volume anchors that subsidize R&D amortization across production runs.
- Slices:Processed formats for sandwich assembly prioritize shelf stability and peelability over stretch performance. Retail deli cases in Germany and the Netherlands drive placement.
- Blocks:Aged and cultured varieties for shredding or crumbling command refrigerated specialty case positioning. European artisan producers concentrate here, constrained by fermentation scale-up costs.
Shreds lead volumes today; cream cheese is gaining share fastest.
Base Ingredient:
Ingredient selection stratifies across cost tiers, with commodity bases enabling private-label penetration and premium inputs sustaining branded differentiation.
- Cashews:Fermented cashew bases deliver umami depth and stretch profiles that narrow the sensory gap with dairy cheese. FDA and EFSA labeling frameworks shape how producers communicate live culture content to refrigerated specialty buyers.
- Coconut Oil:Saturated fat content enables melt and mouthfeel replication at lower cost than nut bases. Commodity shreds and slices rely heavily here, though clean-label certification timelines extend go-to-market schedules.
- Soy Protein:Isolates and concentrates retain cost advantages for private-label production, particularly in Asian markets with established processing infrastructure.
- Almond Milk:Neutral flavor profiles suit cream cheese applications, though water intensity in California cultivation raises sustainability scrutiny from UK and Netherlands contract caterers.
Coconut oil leads volumes today; cashews are expanding most quickly.
Distribution Channel:
Channel selection determines margin capture, with direct foodservice bypassing retail slotting fees and specialty stores enabling premium price realization.
- Supermarkets:Mass-market placement demands scale and slotting fee absorption. Flora Food Group anchors this channel through retail partnerships spanning multiple continents.
- Specialty Stores:Refrigerated cases in natural food retailers reward fermentation-based differentiation and aging claims. Miyoko's Creamery concentrates here.
- Wholesale:Foodservice distributors aggregate pizza-chain and stadium concession demand, rebuilding margin structures for mid-scale producers through volume commitments.
- Online Retail:Direct-to-consumer subscriptions and marketplace listings enable trial-size formats and flavor variety packs, though cold-chain logistics constrain expansion.
Supermarkets lead volumes today; wholesale is climbing the fastest.
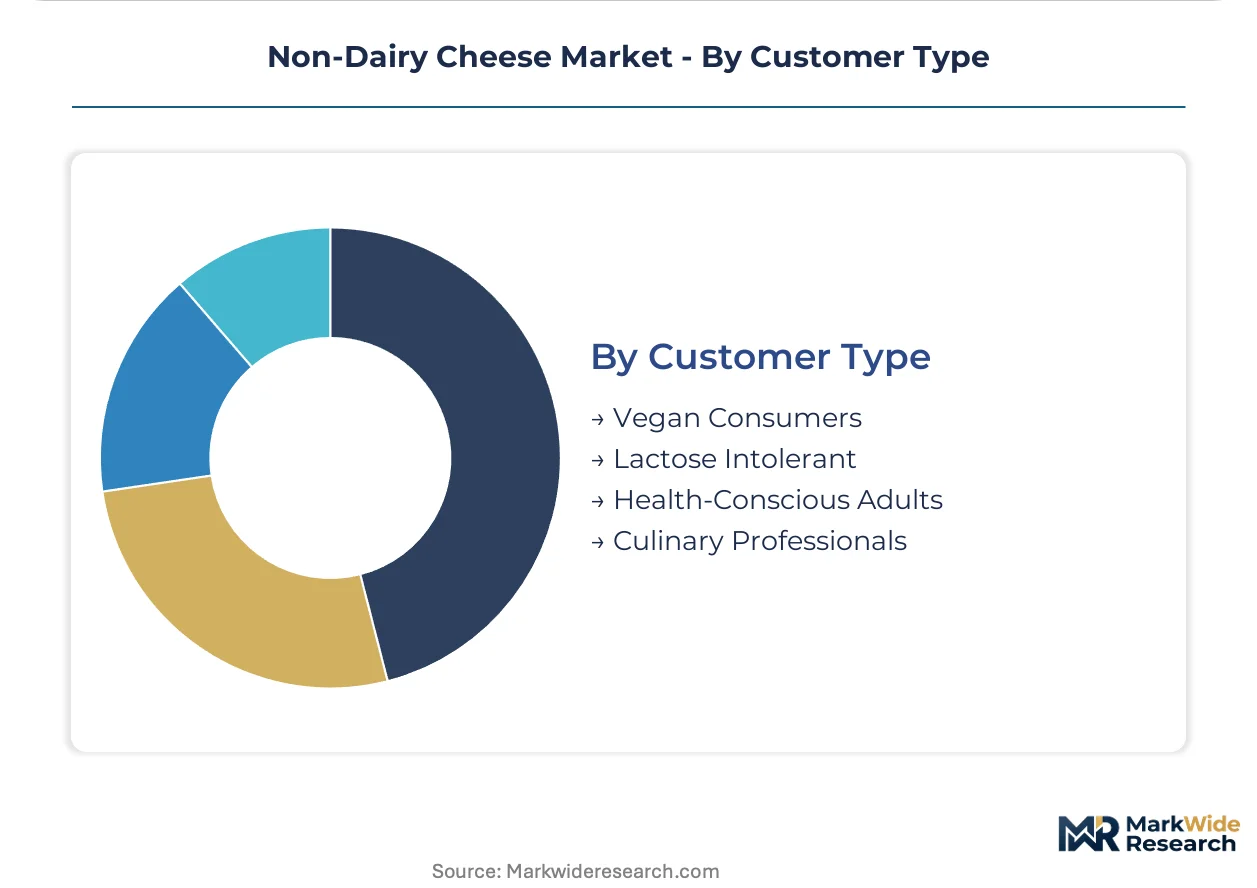
Customer Type:
User segments separate between dietary necessity and elective substitution, with distinct price sensitivity and quality thresholds.
- Vegan Consumers:Ethical and environmental motivations sustain premium tolerance for fermentation-based and aged varieties. This segment validates clean-label certifications and traceability claims.
- Lactose Intolerant:Functional necessity drives consistent purchase but price sensitivity limits upside to commodity formats. Private-label penetration concentrates here.
- Health-Conscious Adults:Flexitarian adoption patterns favor reduced-saturated-fat formulations, pressuring coconut oil reliance and accelerating almond and cashew innovation.
- Culinary Professionals:Performance under heat and precise melt control dictate procurement for pizza and hot-sandwich applications, favoring shreds with calibrated starch-protein ratios.
Lactose intolerant consumers lead volumes today; culinary professionals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States present contrasting demand profiles, with German consumers gravitating toward fermented artisan formats while US buyers prioritize melt-optimized shreds for foodservice integration.
United States
Fast-casual pizza chains and bagel operators anchor procurement volumes for shreds and cream cheese analogs. FDA standards of identity restrict dairy terminology on labeling, creating placement friction in conventional grocery. California's Central Valley hosts cashew processing and formulation R&D clusters serving West Coast distribution networks.
Germany
EU Green Deal farm-to-fork targets pressure conventional dairy pricing, widening procurement windows for plant-based alternatives in contract catering. EFSA novel food frameworks shape approval pathways for precision-fermented ingredients. Berlin and Hamburg concentrate artisan producers targeting refrigerated specialty retail with aged nut-based varieties.
United Kingdom
Bagel chain expansion and university dining contracts drive cream cheese analog demand in morning-daypart menus. Scope 3 emissions thresholds embedded in caterer scorecards mandate ingredient traceability. London and Manchester host formulation labs serving foodservice distributors with sustainability-certified supply chains.
Netherlands
Corporate dining and stadium concession procurement consolidates around sustainability metrics, favoring cashew-traceable suppliers. REACH compliance requirements shape emulsifier and additive selection for European market access. Rotterdam's logistics hub enables cold-chain distribution across Benelux retail and foodservice channels.
Australia
QSR operators diversify protein options through cream cheese placement in breakfast menus, mirroring UK adoption patterns. The country's national food standards regulator enforces labeling clarity for dairy alternatives. Sydney and Melbourne concentrate retail distribution infrastructure for plant-based specialty products.
Non-Dairy Cheese Market Competitive Environment
Top-tier vendors anchor mass-market retail through multi-continental partnerships, while mid-scale specialists concentrate on fermentation-based differentiation in specialty channels. The vendor base stratifies across three archetypes: culture-forward artisans, commodity-scale suppliers, and diversified dairy incumbents with plant-based extensions. M&A activity accelerates as conventional dairy processors acquire fermentation capabilities, and strategic partnerships with pizza-chain operators lock in volume commitments.
Among diversified dairy incumbants, Bel Group and Saputo occupy positions exemplifying portfolio extension strategies into plant-based lines. Miyoko's Creamery represents the culture-forward artisan archetype, anchoring premium positioning through live fermentation claims. Flora Food Group sits within the scale-driven tier, leveraging retail partnerships across multiple continents for mass-market penetration.
| Leading Market Players |
|---|
| Daiya Foods (Otsuka Holdings) |
| Flora Food Group |
| Miyoko's Creamery |
| Kite Hill |
| Danone (Follow Your Heart) |
| Saputo (Vitalite) |
| Bel Group (Nurishh, Boursin Plant-Based) |
| Treeline Cheese |
| Tofutti Brands |
| Others |
Value Chain & Pricing Dynamics
Pizza-chain procurement concentration anchors contract-based pricing for melt-optimized shreds, while specialty retail buyers absorb premium markups for fermented cashew blocks. This bifurcation creates divergent margin structures that reshape supplier investment priorities across formulation tiers.
Pricing Analysis
Ingredient-plus-service bundling separates commodity shreds from artisan blocks. Three-tier pricing structure across premium, standard, and economy levels reflects fermentation depth, cashew content, and aging claims. Price differentiation hinges on live culture certification and clean-label verification cycles. Cost compression in the starch-heavy commodity tier is intensifying because private-label suppliers anchor price floors below sustainable production costs. Lactose-intolerant consumers exhibit highest price sensitivity; vegan buyers tolerate premium positioning.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Chicago, and Singapore orchestrate hub-and-spoke cold-chain logistics for refrigerated SKUs. Raw cashew processing concentrates in Vietnam and India, with coconut oil sourcing anchored in Indonesia and the Philippines. Formulation draws from enzymatic inputs, microbial cultures, and emulsifier blends. Single-source vulnerability in Vietnamese cashew shelling exposes margin volatility. Distribution runs through foodservice wholesalers and supermarket retail networks with divergent slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance costs in Germany and the Netherlands run below FDA labeling friction in the United States, creating arbitrage windows for European production scale-up.
For Market Incumbents: Lock in multi-year pizza-chain supply contracts before precision-fermented casein analogs achieve EFSA clearance and erode melt-performance differentiation. Defend margin position through backward integration into cashew processing in Vietnam or captive fermentation infrastructure in Portugal. Patent thickets around microbial transglutaminase applications threaten R&D efficiency; licensing negotiations demand dedicated legal capacity. For New Entrants and Emerging Players: Enter via direct-to-foodservice channels bypassing retail slotting fees, targeting stadium concessions and university dining contracts in the United Kingdom and Australia. Bagel chain cream cheese placement offers the most penetrable white space, with morning-daypart menu standardization accelerating. Lead with sustainability-certified supply chains and Scope 3 emissions disclosure to satisfy procurement scorecards. For Investors and Strategic Acquirers: Conventional dairy processors with plant-based extension strategies are the most active acquirer in this space, seeking fermentation capabilities and culture libraries. Long-term viability rests on precision-fermentation scale-up economics achieving parity with commodity analogs. Watch EFSA novel food approval timelines for fermented protein dossiers as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Live culture infrastructure in Portugal and California anchors artisan positioning for European and North American retail. |
| Backward Integration into Cashew Processing | Vietnamese shelling facility investments reduce exposure to commodity price swings and tariff friction. |
| EFSA Novel Food Dossier Preparation | Parallel-track regulatory affairs teams accelerate precision-fermented casein pathways for block cheese formats. |
| Direct-to-Foodservice Channel Development | Pizza-chain and stadium concession partnerships rebuild margin structures without retail slotting fee absorption. |
| Clean-Label Certification Investment | USDA organic and Non-GMO Project verification sustains premium positioning in natural food retail cases. |
Study Parameters
Direct dialogue with fermentation technology directors, foodservice procurement managers at contract caterers, regulatory affairs leads at alternative protein startups, and retail category buyers grounded qualitative findings. Secondary validation drew from FDA standards of identity filings, EFSA novel food approval databases, EU Green Deal farm-to-fork policy documents, and customs trade data on cashew kernel imports. Bottom-up SKU-level volume aggregation and top-down macroeconomic calibration ensured triangulation integrity.
Segment-level projections across product type, base ingredient, distribution channel, and customer type fed into analytical framework outputs across the analysis window. CAGRs derived from historical trajectory fitting and diffusion curve modeling for precision-fermentation adoption. Inputs included pizza-chain contract disclosure patterns, bioreactor capacity expansion announcements, and clean-label certification pipeline data.
Inputs from EFSA regulatory filing databases and foodservice procurement databases were available through the study window; gaps in private-label supplier cost structures introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions on fermentation scale-up economics and cashew commodity price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
Coconut Cream Market