
 North America Drinkable Yogurt Market | 2026-2036
North America Drinkable Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
North America Drinkable Yogurt Market Analytics
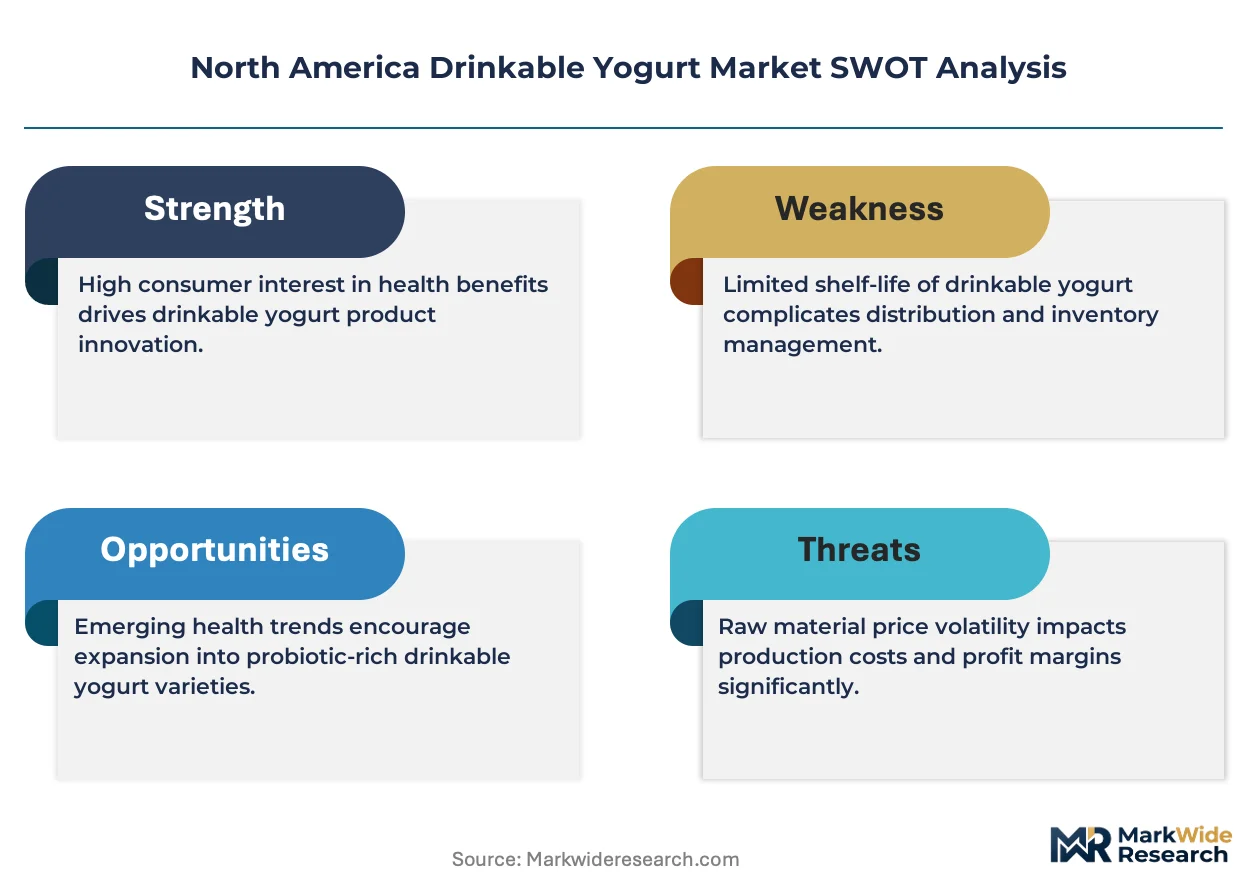
Asset-light co-manufacturing partnerships is reconfiguring competitive entry barriers for emerging brands in the North America drinkable yogurt space. Danone leverages its continental dairy network to sustain refrigerated distribution density. Chobani LLC anchors its position through in-house fermentation technology and direct-store-delivery control. Lifeway Foods Inc. specializes in kefir-based drinkable formats that occupy a distinct probiotic niche.
Drinkable yogurt comprises fermented milk processed to a pourable viscosity, typically containing live bacterial cultures and protein concentrations ranging from 3% to 10%, designed for on-the-go consumption without utensils. Probiotic variants command premium shelf positioning as consumers prioritize gut-health claims validated by strain-specific research. Organic formulations face margin pressure from feed-cost volatility but maintain loyalty among core health-store shoppers. Tetra Pak packaging extends ambient distribution reach for brands competing outside traditional cold-chain strongholds.
The FDA oversees dairy identity standards and labeling claims, while USDA Organic certification shapes procurement specifications for ingredient sourcing. Health Canada enforces parallel compositional standards that govern cross-border product formulations. Stakeholders must monitor evolving positions on live-culture count thresholds and added-sugar disclosure rules that will determine permissible marketing language.
Market Dynamics
Refrigerated distribution density constraints are forcing brands to choose between asset-heavy cold-chain buildouts and ambient-stable formulation pivots, reshaping capital deployment across the North America drinkable yogurt landscape.
Growth Catalysts
- FDA added-sugar disclosure mandates:Reformulation pressure is accelerating clean-label innovation as manufacturers reduce sugar content to avoid prominent front-of-package warnings.
- Urban coastal corridor premium grocery penetration:Dense populations with disposable income and health consciousness are absorbing higher-margin functional variants at accelerated velocity.
- Strain-specific probiotic research validation:Clinical evidence supporting gut-health claims is expanding permissible marketing language and justifying shelf-space premiums.
Market Restraints
- Organic dairy feed-cost volatility:Corn and soybean price swings compress margins for certified-organic formulations despite loyal health-store shopper retention.
- Cold-chain infrastructure concentration:Refrigerated trucking and warehouse capacity bottlenecks in secondary US markets limit distribution reach for perishable live-culture products.
- Plant-based dairy substitutes:Oat and almond milk beverages are capturing on-the-go consumption occasions with lower price points and extended ambient stability.
Strategic Opportunities
- Mexico underpenetrated retail channels:Modern trade expansion in Mexican metropolitan areas offers first-mover positioning for ambient-stable Tetra Pak formats.
- US workplace wellness programs:Corporate cafeteria and micro-market contracts represent institutional volume anchors with recurring procurement patterns.
- USDA Organic certification tailwinds:Federal procurement preferences and retailer shelf-reset policies favor certified suppliers in premium positioning battles.
Industry Challenges
- Live-culture count assay standardization:Inconsistent CFU measurement methodologies across laboratories create compliance documentation burdens and label claim litigation exposure.
- Fermentation technician scarcity:Specialized dairy microbiology expertise is concentrating at established manufacturers, constraining quality control scaling for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Drinkable Yogurt Market |
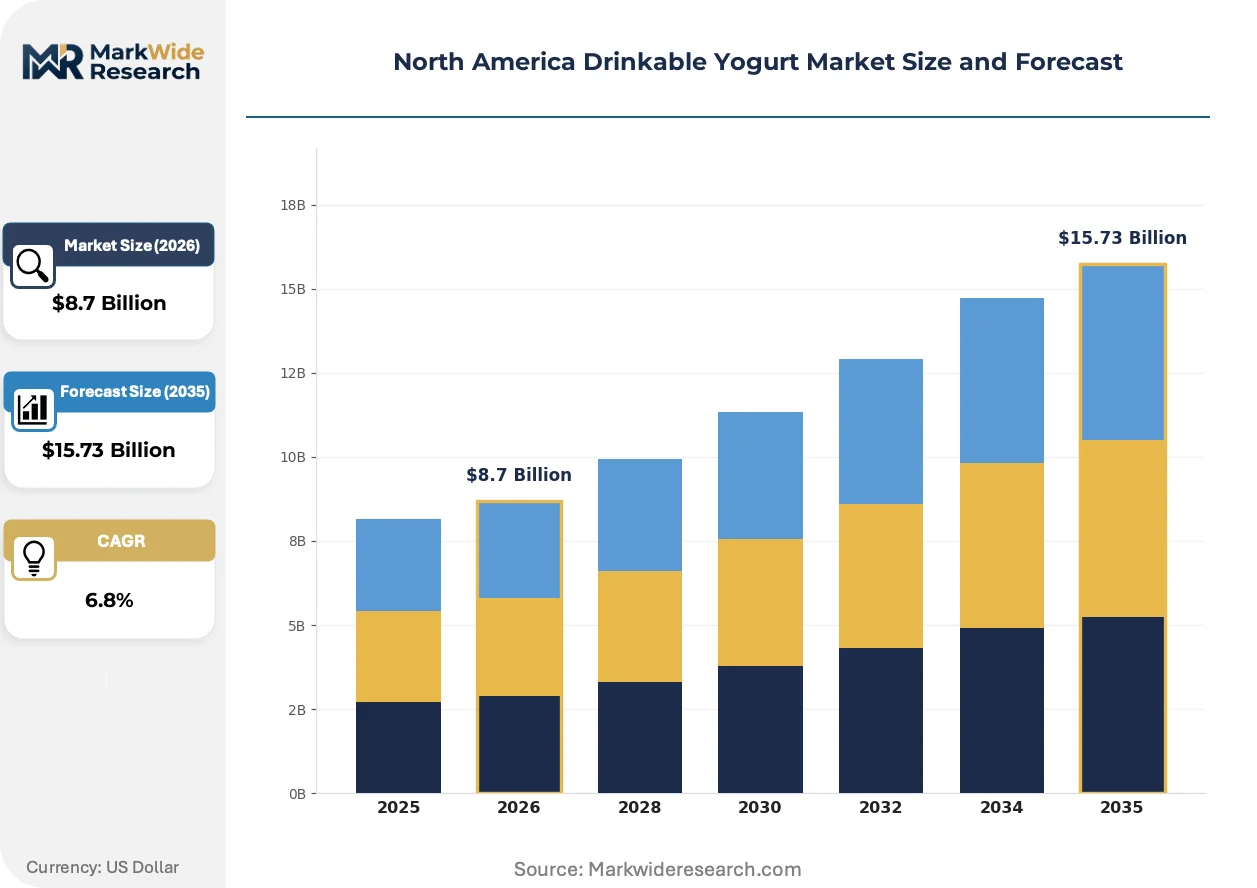
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotic, Organic, Flavored, Low-Fat Distribution Channel: Supermarkets, Health Stores, Online Retailers, Convenience Stores End User: Children, Adults, Athletes, Health-Conscious Consumers Packaging Type: Bottles, Tetra Paks, Cups, Pouches |
| Companies Covered | Chobani LLC, Danone, Yoplait USA, Inc., Groupe Lactalis, Califia Farms, General Mills Inc., Stonyfield Farm, Maple Hill Creamery, Lifeway Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Drinkable Yogurt Market Evolving Landscape
Formulation science and packaging engineering are converging to collapse the traditional tradeoff between probiotic viability and ambient distribution reach, unlocking channel expansion previously blocked by refrigeration requirements.
Aseptic fermentation followed by flash-cooling preservation is hybridizing live-culture stability with extended shelf-life performance. Mid-tier brands adopting this process are penetrating convenience stores and vending channels previously ceded to shelf-stable competitors. The technology is hybridizing cold-chain and ambient supply economics, forcing incumbents to defend refrigerated strongholds or match capital-light distribution flexibility.
Health Canada's parallel compositional standards for cross-border formulations are tightening identity requirements for fermented milk beverages. Dual-compliance costs are rising for manufacturers serving both US and Canadian markets. The policy is compressing formulation flexibility most severely for mid-size brands lacking dedicated regulatory affairs teams.
Direct-to-subscription replenishment models are displacing traditional grocery replenishment cycles among urban professional households. Brands capturing email-first relationships are building switching costs through personalized strain recommendations and flexible delivery cadences. This pattern is most visible in California and New York metropolitan corridors where premium convenience commands price tolerance.
North America Drinkable Yogurt Market Segmentation
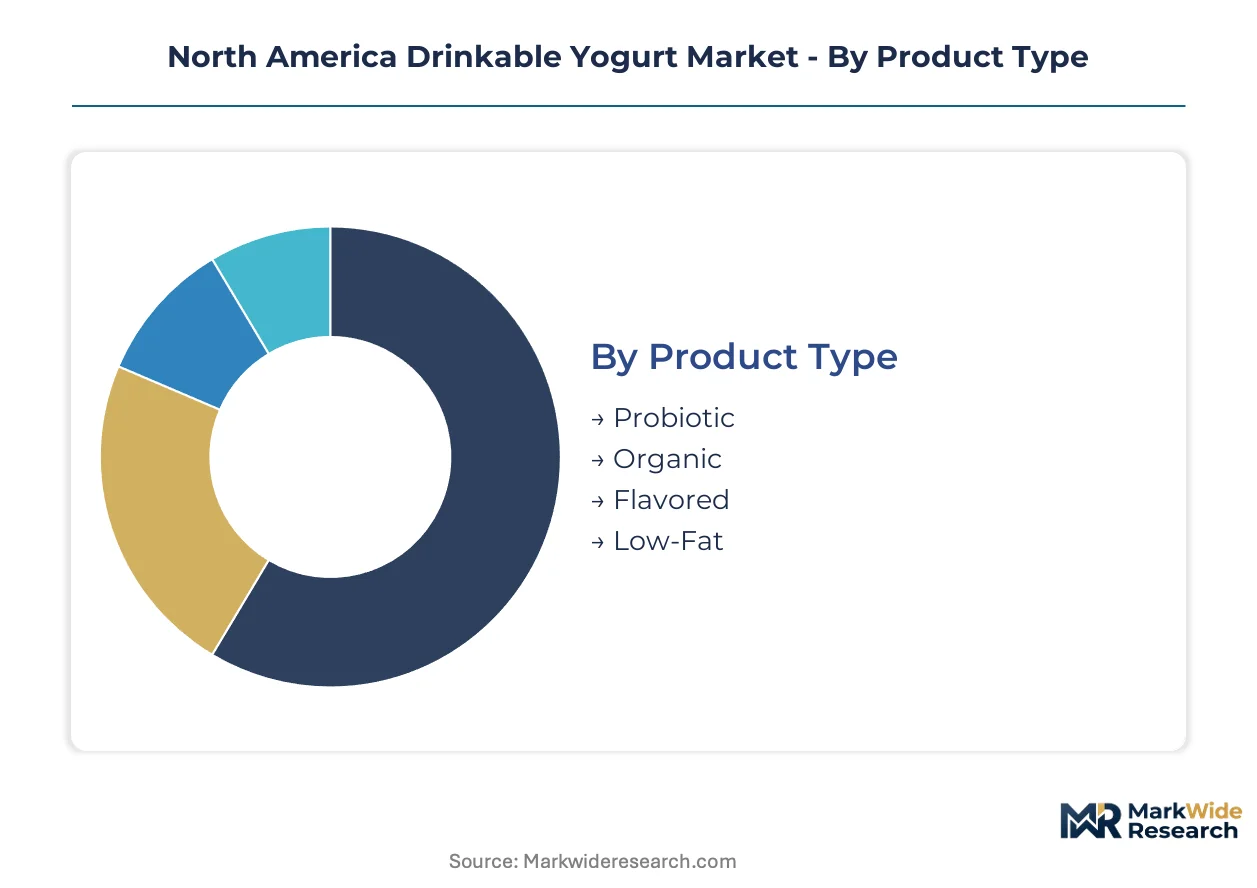
Segmentation in the North America drinkable yogurt market reveals how formulation priorities, channel economics, and consumption occasions fragment demand across distinct value propositions. Each dimension carries specific regulatory and logistical constraints that shape manufacturer resource allocation.
Product Type:
Probiotic variants anchor the mature revenue base while organic formulations accelerate on certification premiums.
- Probiotic:Live bacterial cultures at specified CFU counts deliver gut-health claims validated by strain-specific clinical research. Demand concentrates among urban professional households in California and New York metropolitan corridors where wellness spending commands price tolerance. FDA scrutiny of live-culture count thresholds creates compliance documentation burdens.
- Organic:USDA-certified formulations require verified feed sourcing and antibiotic-free dairy herds. Health-store shoppers in Pacific Northwest and Northeast urban clusters sustain loyalty despite margin pressure from corn and soybean price volatility. Retailer shelf-reset policies increasingly favor certified suppliers.
- Flavored:Fruit and vanilla profiles broaden household penetration through palatability engineering for children and occasional consumers.
- Low-Fat:Reduced-fat identity standards align with FDA nutritional labeling frameworks and workplace wellness program procurement specifications.
Probiotic handles the majority of throughput; organic is climbing the fastest on share.
Distribution Channel:
Channel selection determines cold-chain investment intensity and margin structure through refrigerated versus ambient-stable format compatibility.
- Supermarkets:Traditional grocery dominates volume through refrigerated case placement and promotional slotting fees. Chobani and Danone leverage direct-store-delivery control to secure premium positioning in Northeast and Midwest metropolitan stores.
- Health Stores:Specialty retailers concentrate organic and kefir-based SKUs with educated staff recommendations driving conversion.
- Online Retailers:Subscription replenishment models displace traditional grocery cycles among urban professional households with flexible delivery cadences.
- Convenience Stores:Ambient-stable Tetra Pak formats penetrate grab-and-go occasions previously ceded to plant-based substitutes.
Supermarkets absorb the dominant volume share; online retailers are expanding most quickly on penetration.
End User:
User-based segmentation aligns formulation architecture with distinct nutritional priorities and consumption rituals across life stages.
- Children:Single-serve pouches and flavored profiles with controlled sugar content target school lunch and snack occasions. Parents in suburban US markets prioritize calcium fortification and portion control.
- Adults:Protein-enhanced and low-fat variants serve breakfast replacement and workplace consumption with convenience positioning.
- Athletes:Higher protein concentrations and recovery-focused marketing target fitness enthusiasts with performance claims.
- Health-Conscious Consumers:Strain-specific probiotic and organic certifications justify shelf-space premiums among shoppers prioritizing gut microbiome research.
Adults generate the bulk of purchase frequency; health-conscious consumers show the steepest expansion trajectory.
Packaging Type:
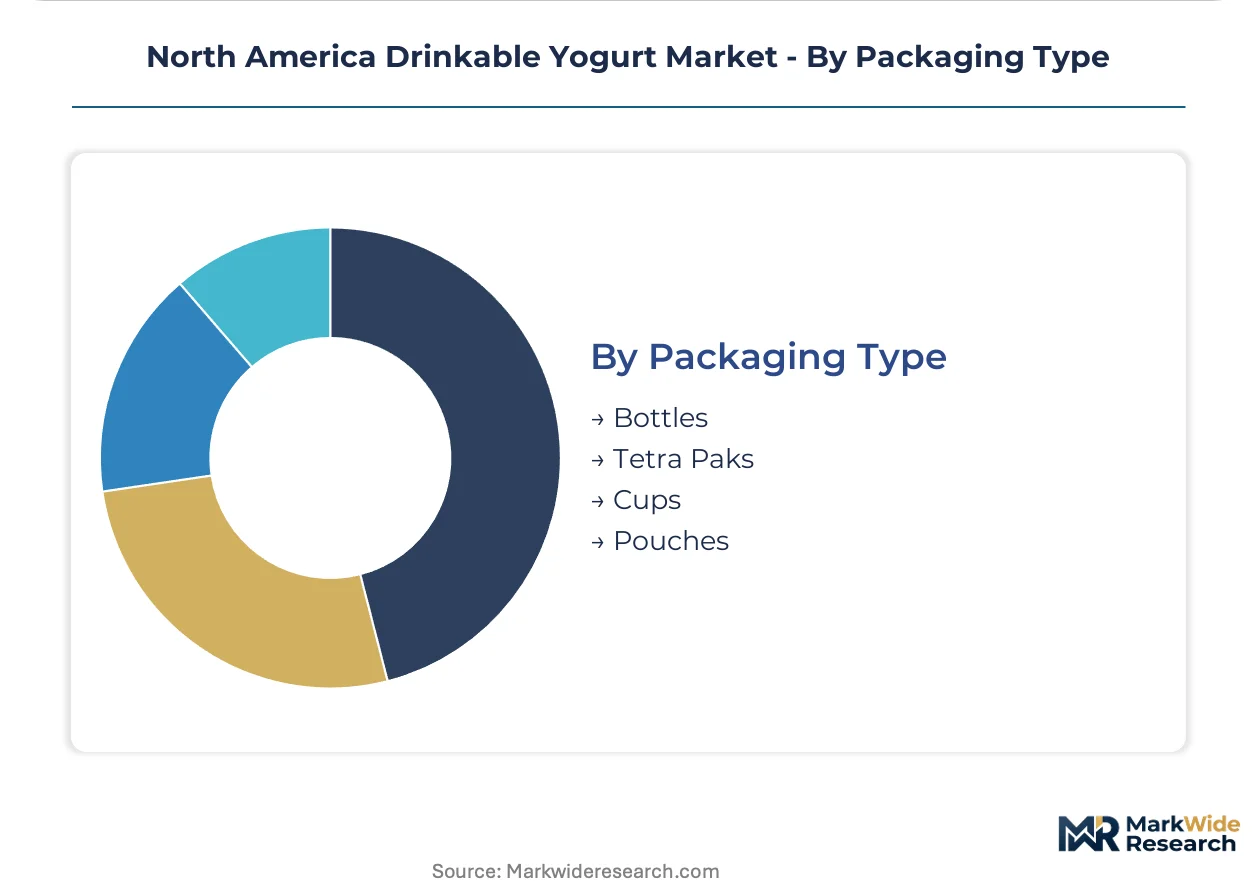
Packaging engineering determines distribution reach by resolving the traditional tradeoff between probiotic viability and ambient stability.
- Bottles:Refrigerated HDPE and PET formats dominate premium positioning with transparent visibility of product consistency. Cold-chain dependency limits penetration in secondary US markets with warehouse capacity constraints.
- Tetra Paks:Aseptic carton technology enables ambient distribution through convenience stores and vending channels. Mexico's modern trade expansion favors this format for shelf-stable penetration.
- Cups:Single-serve portions target foodservice and institutional contracts with portion-controlled dispensing.
- Pouches:Flexible packaging reduces shipping cube and targets children's lunchbox occasions with resealable functionality.
Bottles retain the largest installed base; Tetra Paks are gaining share fastest through channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA added-sugar disclosure mandates and USDA Organic certification preferences are reshaping procurement patterns across North American metropolitan corridors. Health Canada compositional standards create dual-compliance costs for cross-border manufacturers. Mexico's modern trade expansion opens shelf-stable distribution channels previously constrained by cold-chain limitations.
United States
Urban coastal corridors in California and New York metropolitan areas absorb premium functional variants at accelerated velocity. Workplace wellness program procurement specifications favor low-fat and protein-enhanced formulations for institutional contracts. FDA live-culture count threshold scrutiny creates compliance documentation burdens for manufacturers targeting health-conscious consumers.
Canada
Health Canada enforces parallel compositional standards that govern cross-border product formulations for manufacturers serving both markets. Toronto and Vancouver metropolitan clusters concentrate demand for organic and kefir-based SKUs with educated retail staff driving conversion. Dual-compliance costs compress formulation flexibility for mid-size brands lacking dedicated regulatory affairs teams.
Mexico
Modern trade expansion in Mexico City and Monterrey metropolitan areas offers first-mover positioning for ambient-stable Tetra Pak formats. The country's national food safety regulator enforces dairy identity standards that align with US FDA frameworks for cross-border supply chains. Northern border states serve as manufacturing locations for brands seeking duty-advantaged access to US southwestern markets.
North America Drinkable Yogurt Market Competitive Landscape
Channel-controlling players compete with product-specialist players across refrigerated and ambient distribution vectors. The market structure consolidates around direct-store-delivery networks and co-manufacturing partnerships that lower entry barriers for emerging brands. Three archetypes dominate: multinational dairy conglomerates with continental cold-chain density, mid-tier specialists leveraging in-house fermentation technology, and kefir-based niche players occupying distinct probiotic positioning. Competitive moves concentrate on strategic partnerships for ambient-stable formulation access and portfolio diversification into plant-adjacent functional beverages.
Within the multinational conglomerate tier, Danone and General Mills Inc. represent channel-controlling archetypes with refrigerated distribution density across North American metropolitan markets. Chobani LLC exemplifies the mid-tier specialist model through in-house fermentation capabilities and direct-store-delivery control. Lifeway Foods Inc. anchors the kefir-specialist niche with distinct probiotic positioning that commands premium shelf space in health-store channels.
| Leading Market Players |
|---|
| Chobani LLC |
| Danone |
| Yoplait USA, Inc. |
| Groupe Lactalis |
| Califia Farms |
| General Mills Inc. |
| Stonyfield Farm |
| Maple Hill Creamery |
| Lifeway Foods Inc. |
| Others |
Value Network & Pricing Analysis
US Midwest dairy herd concentration and corn-belt feed sourcing anchor input cost volatility that compresses margin pools for organic-certified processors downstream. Cold-chain infrastructure scarcity in secondary markets forces brands to absorb premium logistics costs or surrender shelf access to ambient-stable competitors.
Pricing Analysis
Certification level creates the primary spread across the North America drinkable yogurt landscape. Three-tier pricing structure across premium, standard, and economy levels reflects USDA Organic designation, strain-specific probiotic claims, and conventional formulations. Cost compression in the organic tier is intensifying because feed-cost volatility outpaces retail price elasticity. Workplace wellness program procurement managers show lowest price sensitivity; convenience store shoppers in secondary markets exhibit highest.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates cross-border formulation compliance costs for dual-market manufacturers. Supply concentrates in Wisconsin, New York, and Vermont for conventional dairy inputs; organic feed sourcing draws from Iowa, Illinois, and Minnesota. Single-source vulnerability in refrigerated trucking capacity during peak summer months threatens live-culture viability. Distribution runs through direct-store-delivery networks controlled by incumbents in metropolitan corridors, with ambient-stable Tetra Pak formats penetrating convenience and vending channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment models and personalized strain recommendation services are expanding faster than base product throughput, creating recurring-revenue attach opportunities that outpace hardware margins.
For Market Incumbents: Build regulatory affairs capabilities as a moat against dual-compliance cost burdens from Health Canada and FDA divergence. Deepen backward integration into organic dairy herd networks to secure feed-cost insulation. Channel control through direct-store-delivery density remains the priority lever against ambient-stable challengers. For New Entrants and Emerging Players: Mexico's modern trade corridors in Mexico City and Monterrey offer first-mover positioning for Tetra Pak formats bypassing cold-chain bottlenecks. Workplace wellness program contracts provide institutional volume anchors with recurring procurement patterns. Target corporate cafeteria and micro-market channels with protein-enhanced variants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ambient-stable fermentation technology sub-segments, enabling asset-light scaling. Mid-tier specialists with in-house aseptic processing capabilities present viable acquisition targets within a five-to-ten year viability window. Monitor FDA live-culture count threshold rulings as the signal to watch for compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Fermentation Technology Adoption | Flash-cooling preservation unlocks convenience store penetration previously blocked by refrigeration requirements. |
| Direct-to-Subscription Channel Launch | Email-first relationships with urban professional households build switching costs through personalized delivery cadences. |
| USDA Organic Certification Investment | Federal procurement preferences and retailer shelf-reset policies favor certified suppliers in premium positioning battles. |
| Cross-Border Regulatory Affairs Buildout | Dedicated compliance teams reduce dual-cost burdens from Health Canada and FDA parallel standards. |
| Workplace Wellness Program Partnership | Corporate cafeteria contracts provide institutional volume anchors with recurring procurement patterns in metropolitan corridors. |
Research Methodology
A standing panel of dairy processing executives, retail category buyers, fermentation technology specialists, and cold-chain logistics operators provided ongoing calibration throughout the study. Primary interviews with supply chain planners at co-manufacturing facilities and regulatory affairs leads at cross-border operators were cross-referenced against FDA enforcement letters, Health Canada compositional standard updates, USDA Organic certification databases, and Nielsen retail audit data. Bottom-up volume builds and top-down macroeconomic triangulation anchored all market sizing.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning probiotic strain specificity, organic certification status, packaging format viability, and distribution channel cold-chain intensity. CAGRs were derived from weighted average growth trajectories across these dimensions, incorporating feed-cost volatility indices and refrigerated trucking capacity utilization as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant-based dairy substitutes or ambient-stable fermentation technology disruptors would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Lactose-Free Milk Market