
 Non-Dairy Creamer Market | 2026-2036
Non-Dairy Creamer Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Dairy Creamer Market Intelligence
Coffeehouse and food service channels are pivoting toward oat and almond-based creamer formats as consumer preference shifts away from conventional dairy. Nestlé S.A. anchors its position through extensive retail distribution and proprietary emulsification technology. Kerry Group plc specializes in customized ingredient systems for commercial beverage operators. Califia Farms differentiates through barista-specific liquid formulations and refrigerated supply chain control.
Non-dairy creamer comprises a stabilized emulsion of vegetable oils, proteins, sweeteners, and emulsifiers designed to replicate the mouthfeel and whitening function of dairy cream in hot beverages. Hydrogenated oil content and protein source—whether soy, pea, oat, or almond—determine functional performance in acidic coffee environments. Powdered formats retain dominance in institutional and hospitality procurement due to shelf stability and lower logistics costs. Liquid creamers capture expanding share in retail and specialty coffee channels where refrigerated distribution infrastructure supports premium positioning. Food service customer types generate the highest volume throughput, though online sales channels exhibit the fastest route-to-market expansion for emerging brands.
The FDA governs labeling and nutritional disclosure for plant-based creamers in the United States, while the EPA regulates wastewater and emissions from vegetable oil processing facilities that supply core inputs. EFSA and EMA frameworks in Europe impose stricter additive scrutiny, particularly around titanium dioxide whitening agents and phosphate stabilizers. Stakeholders must monitor evolving trans-fat restrictions and clean-label certification requirements across multiple jurisdictions to sustain formulation compliance and market access.
Market Dynamics
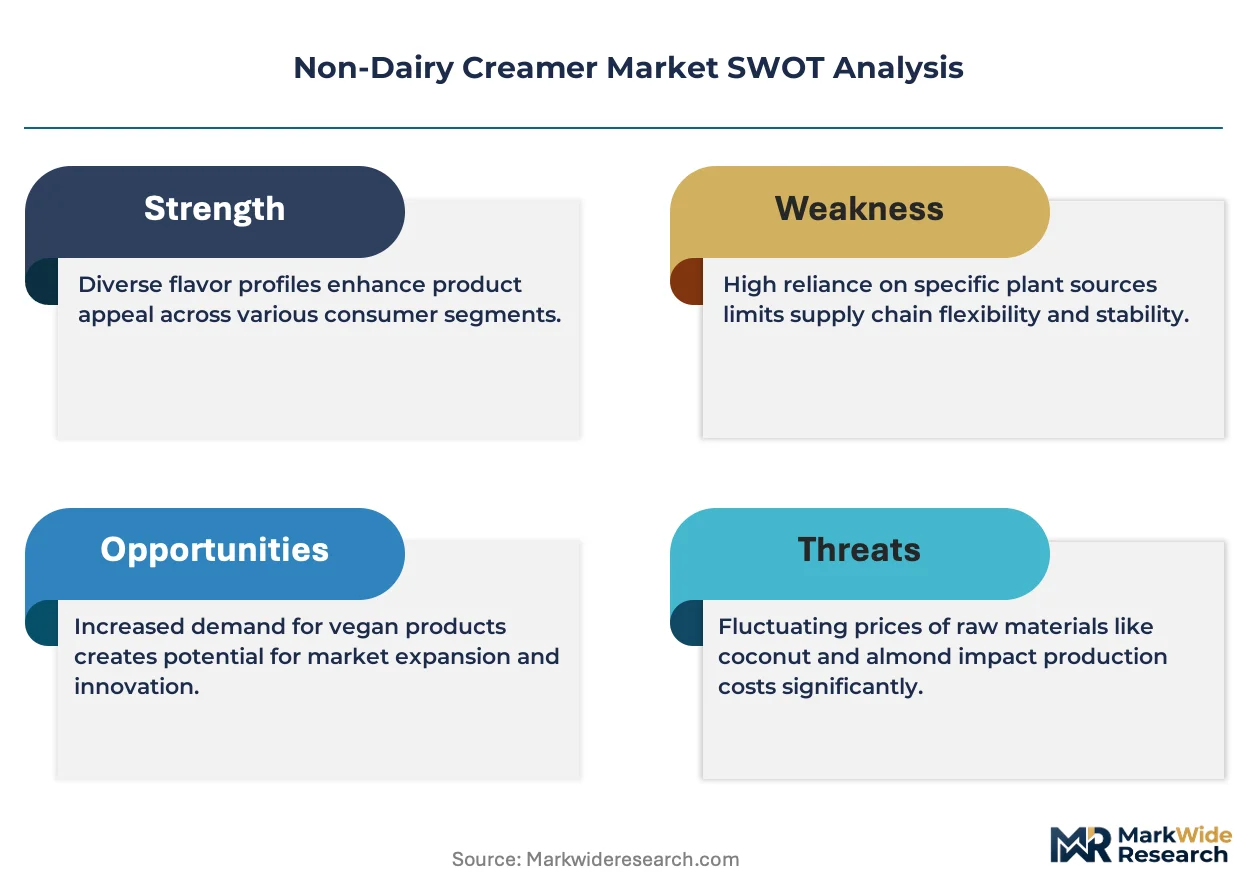
The FDA's updated labeling requirements for plant-based dairy alternatives are compressing formulation flexibility while specialty coffee chains accelerate procurement of oat and almond-based formats, creating simultaneous regulatory and demand-side pressure on emulsifier and protein sourcing decisions.
Growth Catalysts
- Clean-label mandates:The FDA's trans-fat disclosure rules are forcing reformulation toward non-hydrogenated oil systems, expanding addressable market for high-oleic sunflower and coconut oil emulsions.
- Specialty coffee channel expansion:Cold brew and ready-to-drink penetration in the United States is driving refrigerated liquid creamer volume through dedicated barista-grade procurement specifications.
- Plant protein diversification:Pea protein isolate functionality improvements are displacing soy in acidic coffee environments, opening formulation latitude for allergen-free positioning.
Market Restraints
- Vegetable oil input volatility:Coconut and palm kernel oil price swings compress margin stability for manufacturers dependent on tropical supply origins.
- Emulsifier regulatory friction:EFSA scrutiny of titanium dioxide whitening agents and phosphate stabilizers limits European formulation options versus United States permissibility.
- Powder-to-liquid infrastructure gap:Refrigerated distribution network density constraints in secondary United States markets cap liquid creamer penetration velocity.
Strategic Opportunities
- Functional beverage convergence:Protein-fortified and adaptogen-enhanced creamer formats are capturing shelf space in United States natural channel retail, commanding premium positioning through wellness credentialing.
- Food service direct procurement:Quick-service restaurant chains are consolidating supplier relationships through customized ingredient system contracts, bypassing traditional retail brokerage layers.
- Clean-label certification tailwinds:Non-GMO Project and USDA Organic verification requirements are creating defensible segmentation for processors with captive certified oil and protein supply.
Industry Challenges
- Emulsification chemistry talent scarcity:Formulation scientists capable of stabilizing high-protein, low-fat emulsions in acidic hot beverage matrices command premium compensation and limited availability.
- Refrigerated co-packer capacity constraints:Aseptic liquid creamer production lines require capital-intensive cleanroom infrastructure with 18-24 month lead times for equipment procurement and commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Dairy Creamer Market |
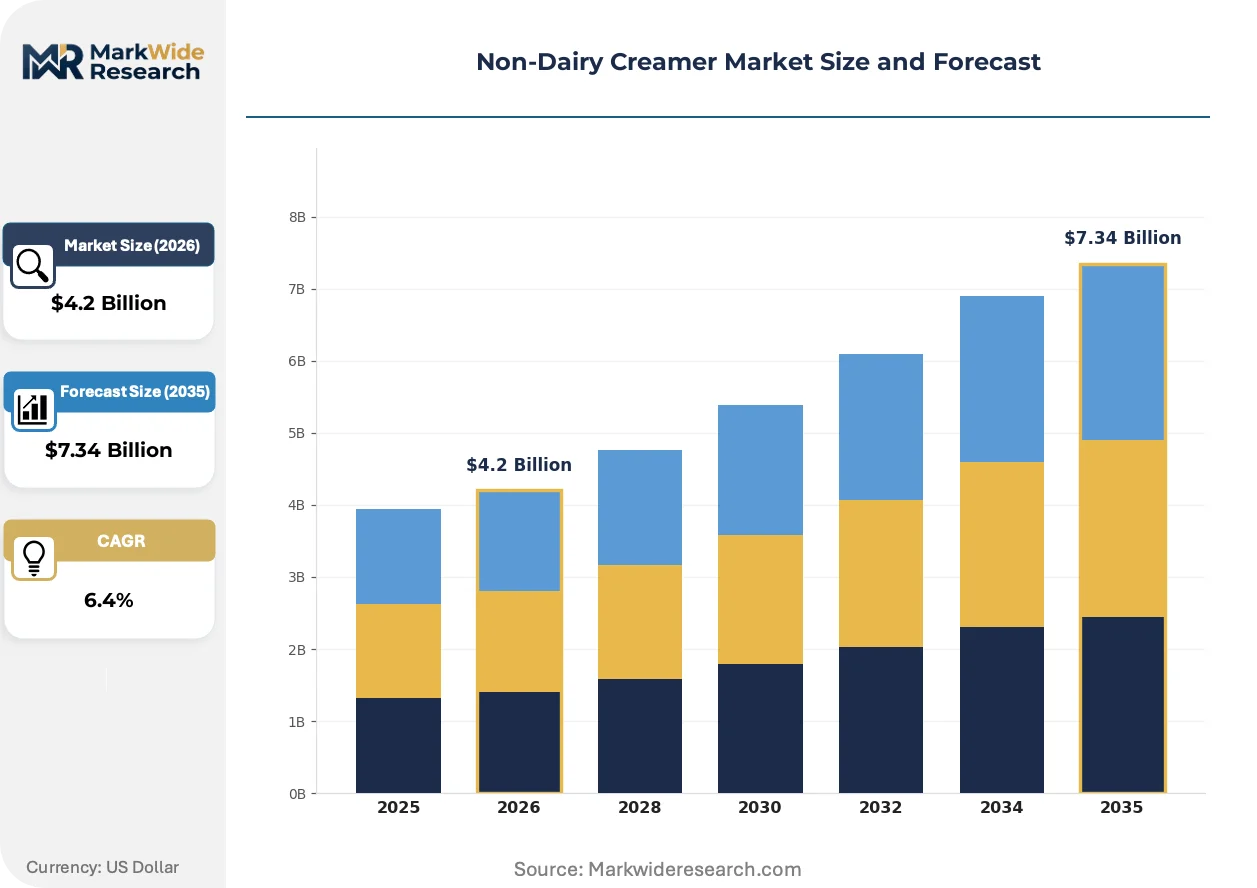
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Concentrated, Instant Application: Coffee, Tea, Cooking, Bakery Customer Type: Retail, Food Service, Hospitality, Online Sales Packaging Type: Pouches, Tubs, Cartons, Sachets |
| Companies Covered | Kerry Group plc, Kraft Heinz, Nestlé S.A., Califia Farms LLC, Oatly Group AB, Royal FrieslandCampina N.V., Cargill Incorporated, Ripple Foods PBC, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Dairy Creamer Market Strategic Shifts & Innovations
Reformulation priorities are pivoting around mouthfeel replication without hydrogenated oils, while regulatory divergence between United States and European additive permissibility is fragmenting global product architectures and forcing regional SKU proliferation.
High-pressure homogenization and microfluidization processing is converging with enzymatically modified plant protein systems to achieve dairy-equivalent whitening and body in reduced-fat formulations. Specialty coffee roasters and café chains are adopting these technologies at pilot scale for proprietary house creamer programs. The structural consequence is compression of traditional emulsifier supplier margins as beverage operators bring emulsion production in-house through equipment leasing arrangements.
REACH restrictions on titanium dioxide food-grade applications in Europe are forcing whitening function substitution through calcium carbonate and modified starch systems, increasing formulation complexity and sensory testing burden. United States processors maintain TiO2 permissibility under FDA GRAS status, creating transatlantic product divergence. Manufacturers serving both markets are bifurcating supply chains, with European production lines absorbing higher raw material costs for compliant alternatives.
Café operators are consolidating procurement through direct supplier contracts specifying customized viscosity, fat content, and flavor profiles, displacing retail-branded creamer resale in food service settings. This channel disintermediation concentrates volume with fewer ingredient system vendors capable of formulation-to-distribution integration. The United States specialty coffee corridor from Seattle to Los Angeles exhibits the most advanced direct-procurement contracting, with multi-year agreements locking in refrigerated logistics capacity.
Non-Dairy Creamer Market Segmentation
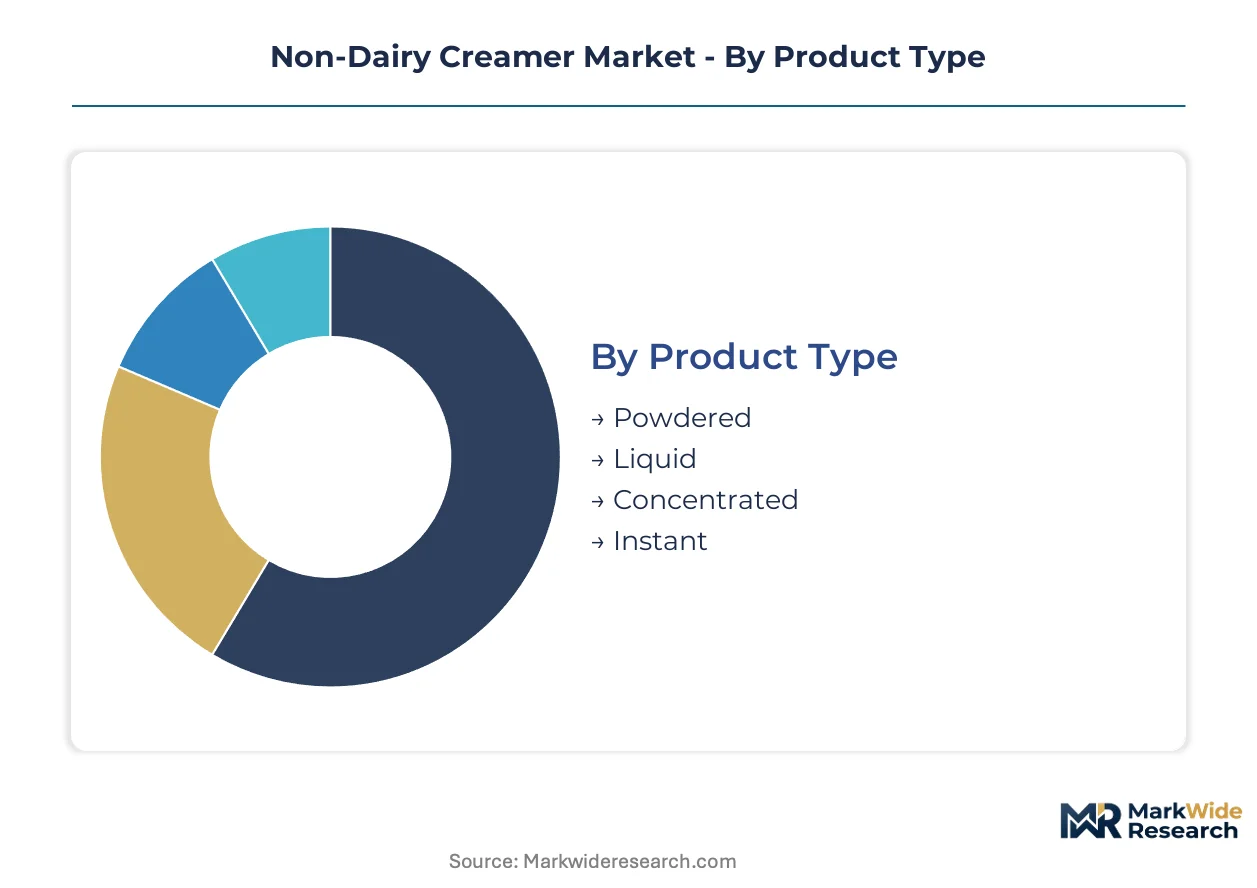
Non-dairy creamer procurement decisions bifurcate across format stability requirements and channel-specific distribution infrastructure. Product architecture, end-use application, and packaging economics each create distinct margin profiles and sourcing priorities for manufacturers and buyers.
Product Type:
Upgrade cycles in food service equipment and retail shelving favor formats with superior stability or premium positioning.
- Powdered:Dehydrated emulsion of vegetable oils, proteins, and maltodextrin carriers delivers 12-24 month ambient shelf life. Institutional procurement in United States healthcare and education sectors drives volume through cost-per-cup efficiency and minimal cold-chain dependency.
- Liquid:Refrigerated emulsion requiring aseptic processing and continuous cold distribution. Specialty coffee chains in Seattle, Portland, and Los Angeles specify barista-grade viscosity and fat content for latte art performance, compressing powder share in premium channels.
- Concentrated:Reduced-water formulations for dilution at point-of-use. Limited penetration in commercial bakery and large-scale food manufacturing where tanker delivery and bulk storage reduce packaging waste.
- Instant:Agglomerated particles for rapid cold-water dispersion. Emerging placement in ready-to-drink coffee manufacturing and outdoor recreation retail where preparation speed outweighs cost premiums.
Volume placements concentrate in Powdered; the faster expansion belongs to Liquid.
Application:
End-use specification intensity varies sharply, with beverage applications demanding precise emulsion stability under thermal and acidic stress.
- Coffee:Dominant consumption vector requiring whitening function, acid stability, and mouthfeel replication. Cold brew penetration in United States metropolitan markets drives reformulation toward lower-fat, cleaner-label emulsions that perform in chilled, acidic matrices without feathering or oil separation.
- Tea:Lower volume but higher flavor compatibility requirements. Black tea consumption in United Kingdom and India accepts traditional dairy alternatives; green and herbal tea segments in Japan and South Korea demand neutral-flavored oat and almond bases without tannin interaction.
- Cooking:Soup, sauce, and prepared meal manufacturing utilizes creamer as fat and protein source. Industrial buyers prioritize 50-pound bulk sacks and tanker delivery with consistent viscosity for automated sauce lines.
- Bakery:Ingredient substitution in frostings, fillings, and dough conditioning. Clean-label certification requirements from United States natural channel retailers constrain emulsifier selection, favoring lecithin over synthetic alternatives.
Application mix tilts toward Coffee for absolute volume; Tea and Bakery are climbing the fastest on per-unit premium realization.
Customer Type:
Channel margin structures and procurement consolidation patterns determine supplier relationship economics.
- Retail:Supermarket and mass merchandiser placement requiring slotting fees and promotional support. United States conventional grocery and club store channels favor multi-pack pouches and flavored variety packs for household pantry stocking.
- Food Service:Quick-service restaurant and café chain procurement through direct supplier contracts. Customized viscosity, fat content, and flavor specifications displace retail-branded resale, concentrating volume with integrated ingredient system vendors.
- Hospitality:Hotel, airline, and institutional catering procurement via broadline distributors. Single-serve sachet and portion cup formats dominate for portion control and waste reduction.
- Online Sales:Direct-to-consumer and subscription models exhibiting steepest expansion trajectory. Emerging brands bypass retail brokerage layers through refrigerated logistics partnerships and influencer-driven trial conversion.
Food Service captures the highest absolute throughput; Online Sales is gaining share fastest on route-to-market disintermediation.
Packaging Type:
Unit economics and sustainability credentialing reshape material selection across temperature-controlled and ambient chains.
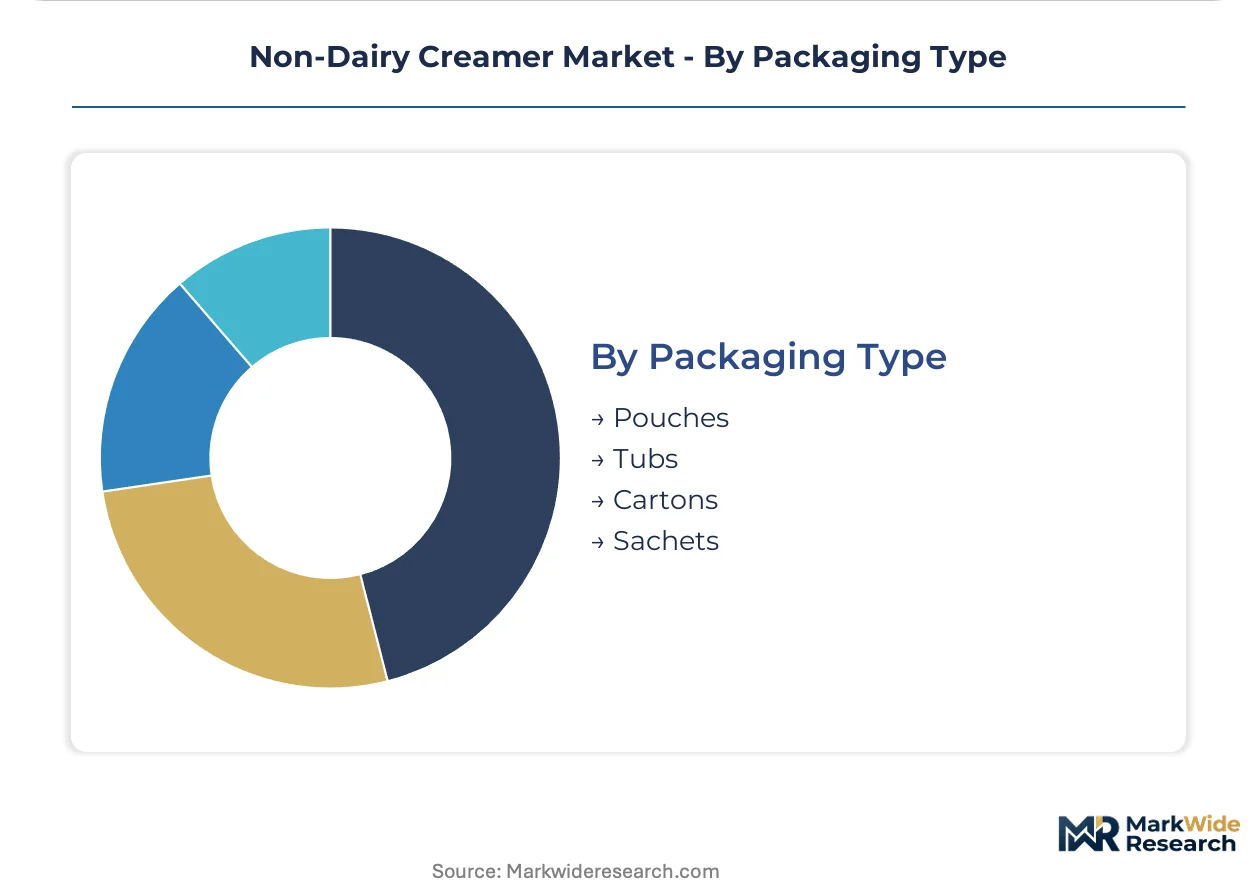
- Pouches:Flexible film laminates for retail multi-packs and food service bulk refill. Reduced material weight versus rigid containers supports sustainability positioning in European markets with extended producer responsibility frameworks.
- Tubs:Injection-molded polypropylene for refrigerated liquid creamer. United States dairy case placement requires tamper-evident closures and handle integration for gallon-scale formats.
- Cartons:Aseptic brick packs for ambient-stable liquid creamer. Extended shelf life without refrigeration enables export logistics and emergency stockpiling applications.
- Sachets:Individual portion packets for hospitality and food service. Paper-based and compostable film alternatives are displacing conventional plastic in European Union markets ahead of single-use plastic restrictions.
Pouch and Tub formats dominate current volume; Carton and Sachet alternatives are expanding most quickly on sustainability-driven material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Southeast Asia and North American processing corridors, while consumption concentrates in United States metropolitan markets and European specialty coffee channels. Regulatory divergence between FDA GRAS permissibility and EFSA additive restrictions is fragmenting product architectures across Atlantic supply chains.
United States
Cold brew penetration in Seattle, Portland, and Los Angeles drives refrigerated liquid creamer volume through dedicated barista-grade procurement specifications. FDA trans-fat disclosure rules under the Nutrition Labeling and Education Act are forcing reformulation toward non-hydrogenated oil systems. The Pacific Northwest specialty coffee corridor exhibits the most advanced direct-procurement contracting, with multi-year agreements locking in refrigerated logistics capacity.
Germany
Clean-label certification requirements from natural channel retailers are constraining emulsifier selection, favoring lecithin over synthetic alternatives. ECHA REACH restrictions on titanium dioxide food-grade applications are forcing whitening function substitution through calcium carbonate systems. Industrial processing clusters in North Rhine-Westphalia are absorbing higher raw material costs for compliant European formulations.
China
Instant coffee and ready-to-drink manufacturing expansion in Yangtze River Delta cities is driving powder creamer volume through cost-per-cup efficiency priorities. SAMR food additive standards under GB national standards govern emulsifier and stabilizer permissibility. Shanghai and Jiangsu province processing facilities are scaling high-pressure homogenization capacity for domestic beverage brand supply.
United Kingdom
Black tea consumption accepts traditional dairy alternatives, while specialty coffee channels demand neutral-flavored oat bases without tannin interaction. EFSA scrutiny of phosphate stabilizers limits formulation options versus United States permissibility. London and Southeast England café operators are consolidating procurement through direct supplier contracts specifying customized viscosity profiles.
Brazil
Instant coffee manufacturing for export markets sustains powder creamer demand through bulk tanker delivery and 50-pound sack formats. ANVISA food additive regulations govern emulsifier and whitening agent standards for domestic and export-bound production. São Paulo state industrial corridors prioritize consistent viscosity for automated sauce and prepared meal lines.
Non-Dairy Creamer Market Key Industry Players
Top-tier vendors anchor retail distribution and proprietary emulsification technology, while mid-tier ingredient system specialists capture food service direct procurement. The competitive terrain splits between diversified multinational processors with captive oil supply and focused plant-based innovators with refrigerated supply chain control. Strategic archetypes include integrated ingredient system vendors, barista-grade liquid specialists, and clean-label certification holders. Dominant competitive moves center on customized formulation contracts and aseptic production line capacity expansion.
Among diversified processors, Nestlé S.A. and Kerry Group plc exemplify contrasting strategic positions. Nestlé S.A. represents the integrated multinational archetype with extensive retail brokerage networks and proprietary emulsification capabilities. Kerry Group plc occupies the food service ingredient system specialist position, focusing on customized viscosity and fat content specifications for commercial beverage operators. Califia Farms LLC anchors the barista-grade liquid creamer segment, differentiating through refrigerated supply chain control and specialty coffee channel penetration.
| Leading Market Players |
|---|
| Kerry Group plc |
| Kraft Heinz |
| Nestlé S.A. |
| Califia Farms LLC |
| Oatly Group AB |
| Royal FrieslandCampina N.V. |
| Cargill Incorporated |
| Ripple Foods PBC |
| Danone S.A. |
| Others |
Cost & Logistics Intelligence
Coconut and palm kernel oil price swings propagate through formulation costs into three-tier pricing structure across premium, standard, and economy levels, with certified organic and non-GMO verified creamers commanding shelf space premiums while commodity powder formats compete on cost-per-cup efficiency in institutional procurement.
Pricing Analysis
Margin tightening in economy-tier powder segments reflects coconut oil price volatility and compressed logistics budgets in United States healthcare and education sectors. Price differentiation hinges on clean-label certification grade and refrigerated distribution infrastructure investment, with food service buyers exhibiting lowest price sensitivity due to customized formulation contracts while hospitality procurement through broadline distributors prioritizes cost-per-portion minimization above all else.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian coconut and palm kernel oil processors, where tropical climate disruption and export policy shifts create feedstock uncertainty. Manufacturing draws from Indonesia, Malaysia, and the Philippines for tropical oils, while high-oleic sunflower sourcing centers on Ukraine and Argentina. Tariff exposure on processed vegetable oil imports into the United States and European Union threatens margin stability. Distribution runs through refrigerated logistics partnerships for liquid formats and ambient freight networks for powder, with co-packer capacity constraints in aseptic liquid production creating 18-24 month equipment lead time bottlenecks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Non-Dairy Creamer Market operates as a cost-of-compliance story where FDA trans-fat disclosure rules and EFSA titanium dioxide restrictions erect formulation barriers that favor incumbents with captive certified supply chains and in-house emulsification expertise.
For Market Incumbents: Deepen backward integration into high-oleic sunflower and coconut oil supply through long-term offtake agreements with Indonesian and Malaysian processors, insulating margin exposure from commodity volatility. Expand aseptic co-packer partnerships in the Pacific Northwest and California to lock in refrigerated logistics capacity ahead of specialty coffee chain consolidation. Fortify position against emerging oat protein specialists by accelerating non-GMO Project and USDA Organic certification coverage across powder and liquid portfolios. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models leveraging refrigerated logistics partnerships and influencer-driven trial conversion, bypassing retail slotting fee barriers. Target online sales channels where route-to-market disintermediation allows premium positioning without conventional grocery brokerage layers. Penetrate the functional beverage convergence segment through protein-fortified and adaptogen-enhanced formats commanding wellness credential premiums in United States natural channel retail. For Investors and Strategic Acquirers: FDA enforcement actions against non-compliant trans-fat labeling are the leading indicator that formulation compliance capabilities will separate viable acquisition targets from distressed assets. The five-to-ten-year viability window favors processors with captive certified oil supply and in-house emulsification chemistry teams. Prioritize mid-tier ingredient system specialists with food service direct procurement contracts and aseptic production line capacity. Watch for European REACH restriction expansion on phosphate stabilizers as the next compliance inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Oil Supply | Long-term offtake agreements with Indonesian and Malaysian processors lock in non-GMO and organic feedstock access. |
| Aseptic Production Line Expansion | Cleanroom infrastructure investment in Pacific Northwest and California corridors captures specialty coffee chain volume. |
| Clean-Label Certification Acceleration | Non-GMO Project and USDA Organic verification creates defensible segmentation against commodity powder competitors. |
| Food Service Direct Procurement Contracts | Customized formulation agreements with quick-service restaurant chains displace retail-branded resale and concentrate volume. |
| Functional Beverage Format Development | Protein-fortified and adaptogen-enhanced creamers capture wellness-premium positioning in natural channel retail. |
Research Approach
Document review covered FDA GRAS notifications, EFSA additive safety opinions, SEC 10-K filings from diversified processors, and specialty coffee industry trade publications, complemented by interviews with formulation scientists at commercial ingredient system vendors, procurement directors at quick-service restaurant chains, refrigerated logistics operators, and clean-label certification program administrators. Secondary validation drew from customs and trade data on vegetable oil imports, Nielsen retail audit data on creamer placement, and food service distribution channel reports. Bottom-up volume modeling triangulated against top-down market sizing from macroeconomic consumption indicators.
Segment-level value outputs emerged from pricing stratification across powdered, liquid, concentrated, and instant formats, with application splits across coffee, tea, cooking, and bakery end-uses, and customer type disaggregation across retail, food service, hospitality, and online channels. CAGRs were derived from regression analysis of historical volume trends against cold brew penetration rates, specialty coffee chain expansion, and regulatory reformulation timelines. Forecast inputs incorporated FDA trans-fat enforcement trajectory, EFSA titanium dioxide restriction implementation, and refrigerated distribution network density expansion in secondary United States markets.
Vegetable oil commodity price volatility, regulatory enforcement timing on clean-label mandates, and co-packer capacity commissioning delays are the dominant revision risks to volume and value projections. Deviation in coconut and palm kernel oil supply stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market