
 Coffee Creamer Market | 2026-2036
Coffee Creamer Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Creamer Market Analysis
Specialty coffee shops and premium home brewers are unwinding the historical dominance of conventional dairy creamers in mass-market grocery. Nestlé S.A. leverages its manufacturing scale to dominate liquid creamer shelves across North American retail. Danone anchors its position through specialized non-dairy formulations that target lactose-intolerant and vegan consumer segments. Kerry Group plc differentiates via custom ingredient systems supplied to private-label brands and foodservice operators.
Coffee creamer denotes a processed additive—emulsified from dairy proteins, vegetable oils, or plant-based alternatives such as oat, almond, or coconut extracts—designed to modify coffee color, mouthfeel, and flavor stability at serving temperatures between 60°C and 85°C. Non-dairy formulations now lead growth as oat and almond bases displace soy in retail and foodservice channels, while powdered creamers retain cost-driven volume in institutional settings. Liquid formats command higher margins through refrigerated distribution and premium positioning, whereas sugar-free and organic formulations concentrate in specialty retail and direct-to-consumer channels.
FDA labeling requirements for added sugars and dairy alternatives shape formulation transparency and shelf placement in the United States, while EFSA novel food assessments govern oat and almond base approvals across Europe. USDA organic certification and EU organic regulation create tiered market access that rewards certified producers with premium channel placement. Stakeholders must monitor evolving plant protein allergen thresholds and clean-label enforcement trajectories that will determine which base ingredients retain formulation approval and consumer trust.
Market Dynamics
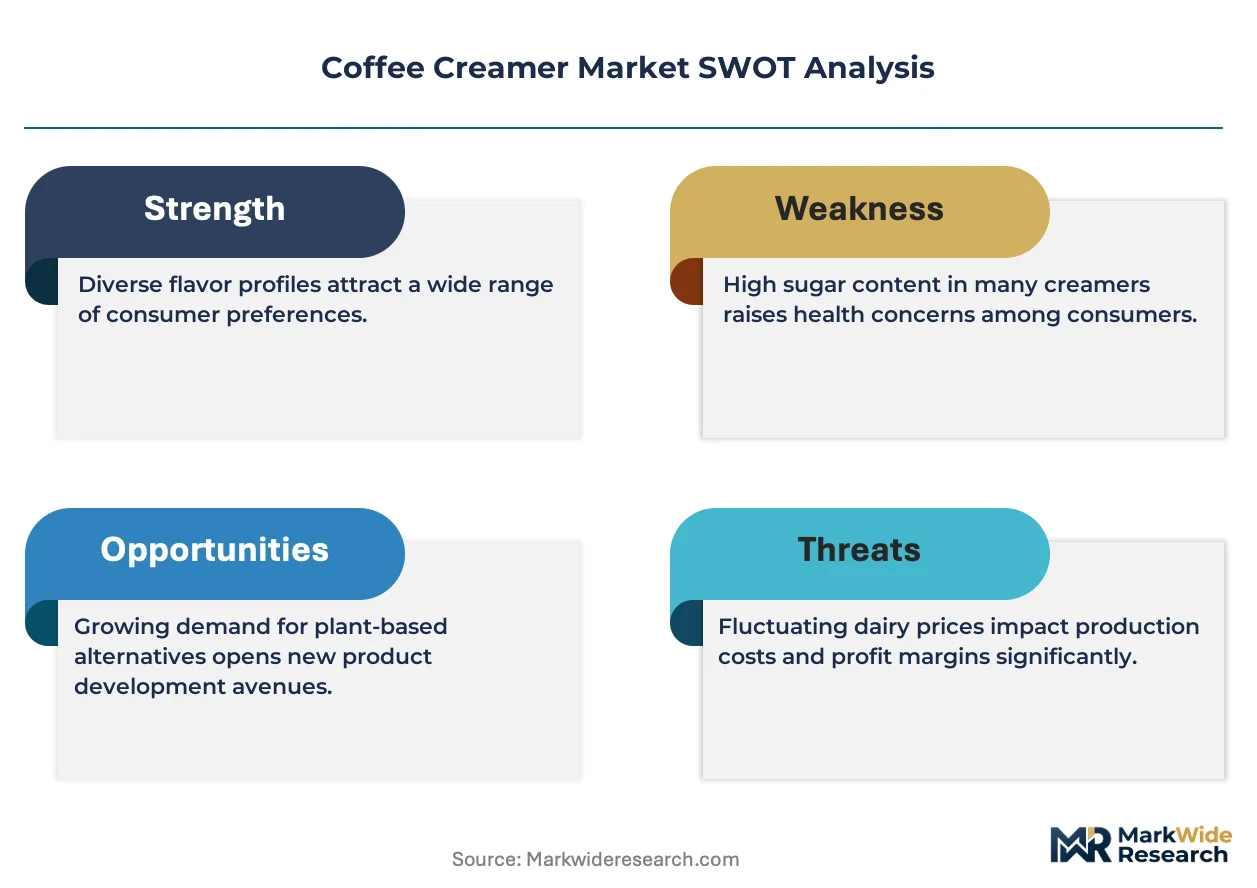
Plant-based formulation standards are tightening under FDA and EFSA oversight, forcing manufacturers to reformulate emulsion systems while specialty coffee chains accelerate non-dairy menu expansion. This regulatory-product convergence is compressing traditional dairy creamer shelf space and reallocating R&D budgets toward oat and almond protein stabilization.
Growth Catalysts
- Barista Culture Maturation:Specialty coffee chains in the United States are standardizing oat-based creamers across corporate locations, creating pull-through demand for compatible retail formats.
- EFSA Novel Food Pathways:Streamlined approval processes for almond and coconut extracts are accelerating European market entry for innovative non-dairy formulations.
- Clean-Label Enforcement:FDA added-sugar disclosure mandates are driving reformulation toward unsweetened and naturally sweetened variants in refrigerated dairy cases.
Market Restraints
- Vegetable Oil Price Volatility:Palm and coconut oil input costs fluctuate with Southeast Asian weather patterns and export restrictions, compressing margin stability for emulsion-based products.
- Refrigerated Distribution Concentration:Cold-chain infrastructure in the United States concentrates among three national carriers, creating bottleneck risk for liquid creamer shelf replenishment.
- Protein Cross-Reactivity Limits:Oat base formulations face technical barriers in achieving foam stability comparable to dairy proteins without allergen-adjacent processing aids.
Strategic Opportunities
- Direct-to-Consumer Subscription:Premium organic formulations are bypassing traditional retail slotting fees through curated delivery models targeting home brewing enthusiasts.
- USDA Organic Tier Expansion:Certified producers gain preferential placement in natural channel resets, creating margin expansion for compliant manufacturing investments.
- Foodservice Customization:Private-label ingredient systems allow regional coffee roasters to develop proprietary creamer profiles without captive production assets.
Industry Challenges
- Emulsion Chemistry Talent Scarcity:Formulation scientists with dual expertise in plant protein functionality and thermal stability command premium compensation, constraining mid-tier manufacturer hiring pipelines.
- Dual Certification Timelines:Simultaneous USDA Organic and EU Organic pursuit requires 18-24 month validation cycles that delay product launch windows.
- Legacy Equipment Retrofit Costs:Aseptic filling lines designed for dairy emulsions require substantial capital modification to handle high-viscosity oat bases without shearing damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Creamer Market |
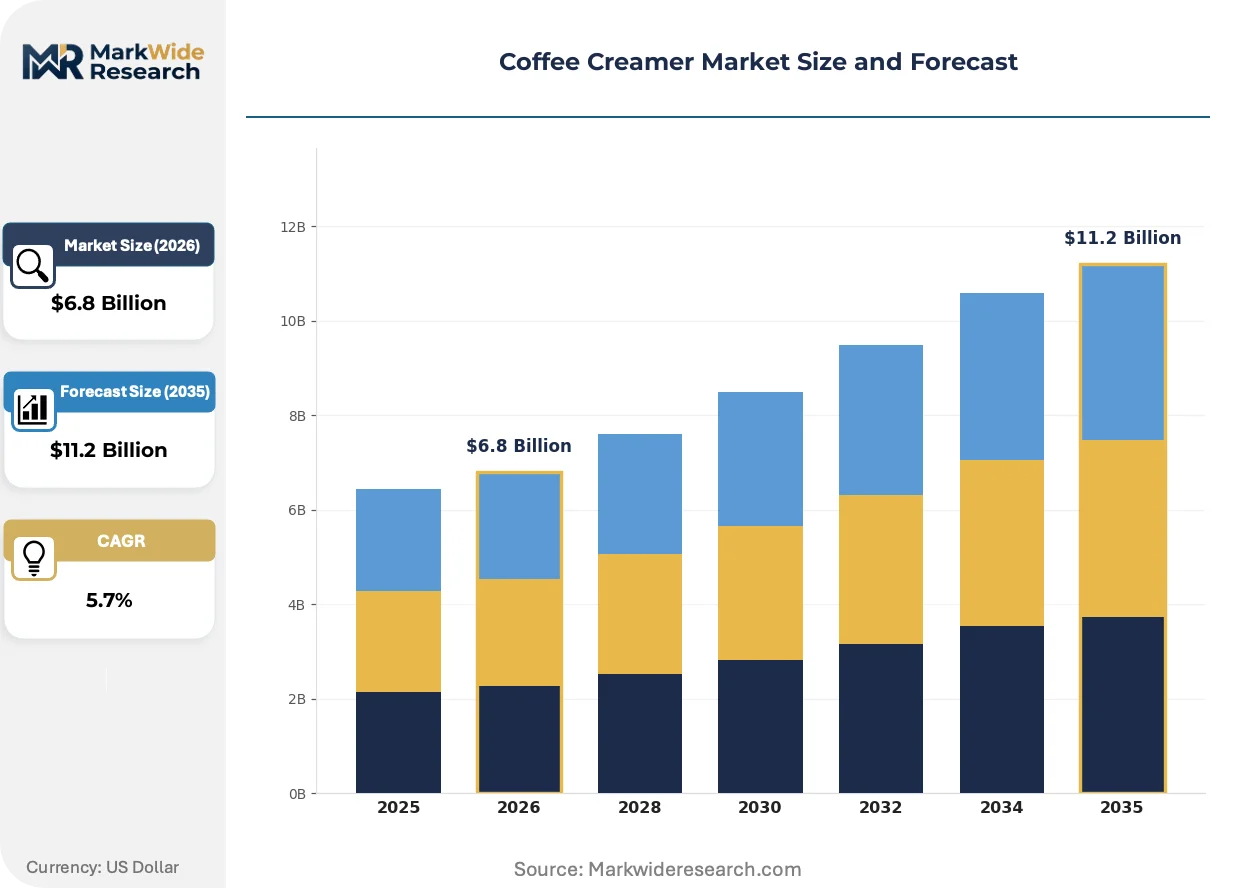
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy-Based, Non-Dairy, Powdered, Liquid Flavor: Vanilla, Hazelnut, Caramel, Mocha Formulation: Organic, Sugar-Free, Creamy, Light Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Coffee Shops |
| Companies Covered | Nestlé S.A., Danone, Chobani LLC, DreamPak LLC, Viceroy Holland B.V., PT Santos Premium Krimer, Kerry Group plc, FrieslandCampina, Land O'Lakes, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Creamer Market Emerging Trajectories
Oat protein emulsion technology is actively reshaping competitive positioning in both retail and foodservice channels. Manufacturers are racing to secure supply agreements with specialty grain processors while reformulating for clean-label compliance.
High-pressure homogenization of oat lipid bodies is supplanting traditional gum-stabilized emulsions in premium liquid creamer production. Third-wave coffee roasters in Portland and Brooklyn are adopting these formulations within 18-month procurement cycles. The technology is compressing ingredient declaration lengths from eight-plus additives to three core components, enabling shelf placement in perimeter refrigerated sections previously reserved for fluid dairy.
EFSA's updated guidance on novel food allergen thresholds is forcing reformulation transparency across European supply chains. Manufacturers must now disclose sub-protein fractions in oat and almond bases that previously escaped labeling requirements. German and Dutch retail buyers are responding by demanding batch-level certificates of analysis before purchase order authorization.
Home brewing equipment penetration is rotating demand toward barista-grade creamers in suburban United States markets. Specialty retailers in Texas and Florida are displacing conventional grocery creamer facings with micro-foam optimized formulations. This pattern concentrates in regions where single-serve espresso machine sales exceeded drip coffee maker volumes during the past holiday retail cycle.
Coffee Creamer Market Segmentation
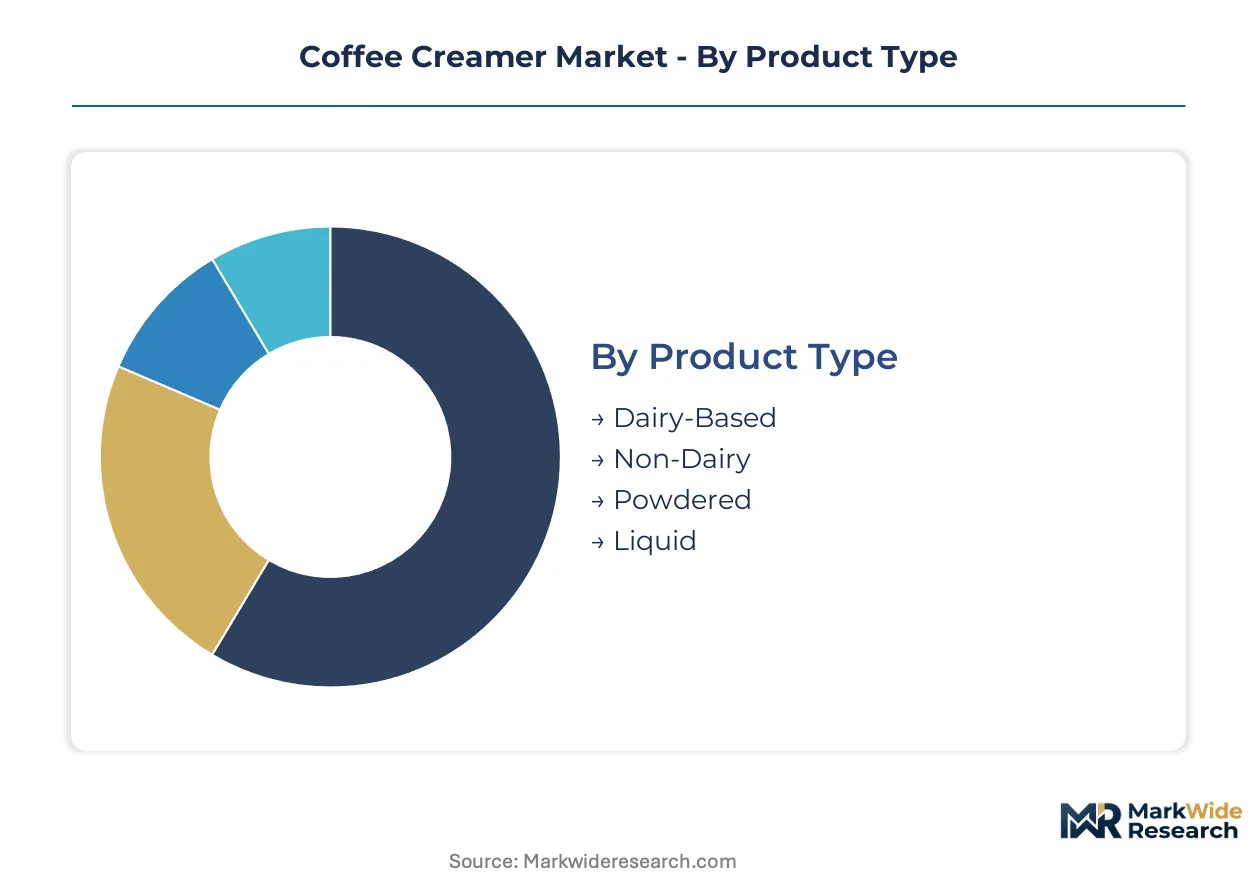
Coffee creamer segmentation tracks the divergence between mass-market retail velocity and premium channel specialization. Manufacturers calibrate formulation investments against distribution access and margin architecture rather than volume alone.
Product Type:
Domestic consumption concentrates in liquid and powdered formats across United States retail, while export demand pulls non-dairy innovations toward European and Asian specialty channels.
- Non-Dairy:Oat, almond, and coconut protein emulsions displace soy bases in refrigerated cases. United States barista culture standardizes oat formulations, creating pull-through for compatible retail SKUs.
- Liquid:Refrigerated dairy and plant-based emulsions command premium shelf placement through cold-chain infrastructure. Convenience stores and specialty grocers allocate perimeter space to these higher-margin formats.
- Dairy-Based:Conventional fluid dairy creamers retain cost-sensitive household penetration in midwestern United States markets.
- Powdered:Hydrogenated vegetable oil and sodium caseinate blends sustain institutional foodservice and office coffee service volumes.
Non-Dairy commands the established base. The steepest expansion runs through Liquid.
Flavor:
Flavor preferences stratify by consumption occasion intensity, with darker roast pairings driving premium positioning and lighter profiles sustaining habitual daily use.
- Vanilla:The foundational flavor standard bridges conventional dairy and plant-based formulations. United States mass-market retailers maintain vanilla as the default facing in multi-flavor planograms.
- Hazelnut:Nut-derived flavor systems align with European taste preferences and specialty coffee shop menu standards. German and Italian retail buyers prioritize hazelnut in premium private-label development.
- Caramel:Butterscotch-derived profiles target dessert-coffee occasions in suburban United States markets.
- Mocha:Chocolate-coffee fusion appeals to younger demographic segments in direct-to-consumer subscription channels.
Vanilla anchors volume throughput. Caramel is climbing the fastest in suburban retail resets.
Formulation:
Regulatory pressure on added-sugar disclosure and organic certification compliance is forcing tiered production strategies across manufacturing footprints.
- Organic:USDA-certified and EU Organic-regulated supply chains command 18-24 month validation timelines. Certified producers secure preferential placement in natural channel resets.
- Sugar-Free:Erythritol and monk fruit sweetened variants respond to FDA added-sugar labeling mandates. Reformulation activity concentrates in refrigerated dairy cases.
- Creamy:Higher fat-content emulsions target espresso-based preparation in specialty coffee chains.
- Light:Reduced-calorie formulations sustain diet-conscious household penetration in conventional grocery.
Organic commands the established base. Sugar-Free is gaining share fastest through label-driven reformulation.
Distribution Channel:
Channel selection determines formulation viscosity, packaging format, and promotional investment intensity with divergent margin structures.
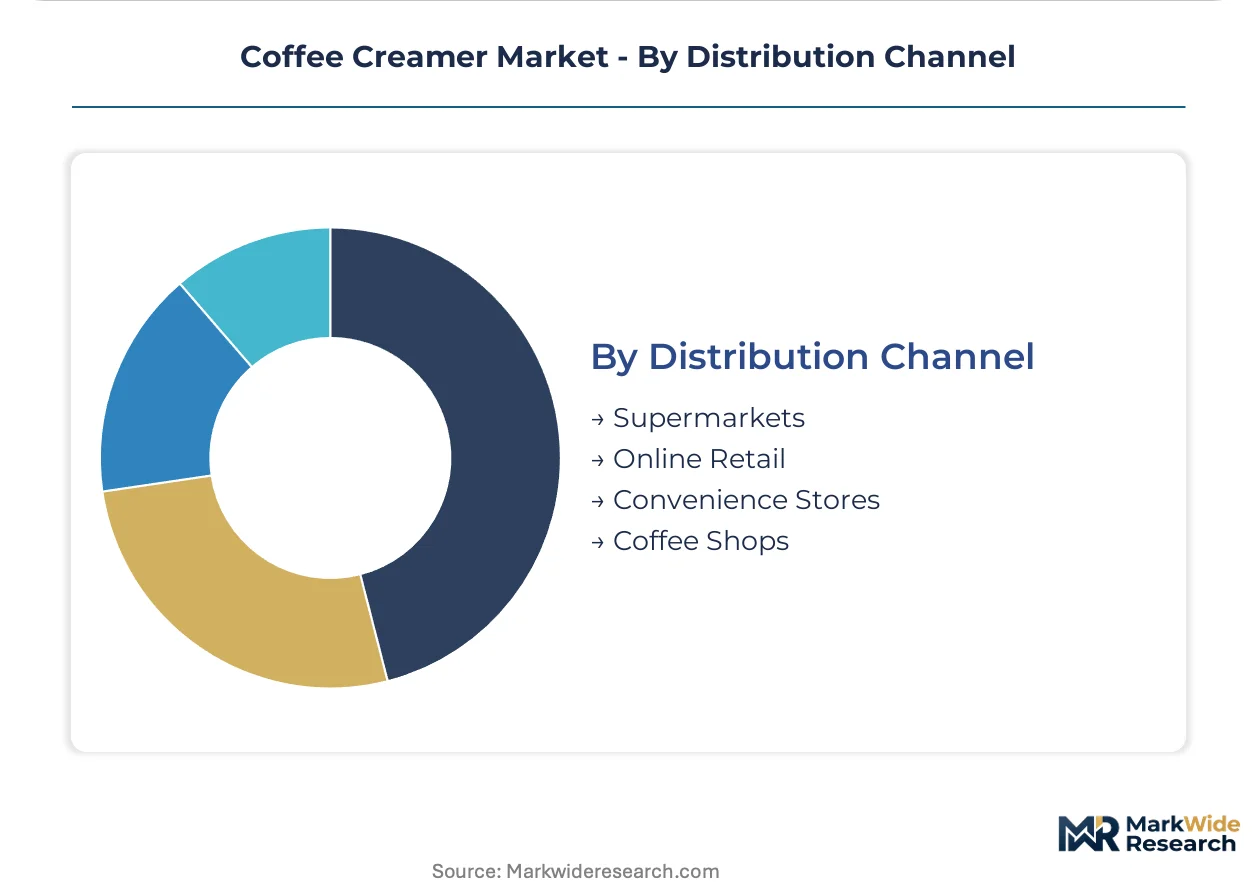
- Supermarkets:Refrigerated dairy cases and ambient coffee aisles allocate slotting fees by velocity tier. United States national chains reset creamer facings seasonally around holiday brewing peaks.
- Coffee Shops:Foodservice operators specify barista-grade foam stability and thermal performance. Portland and Brooklyn roasters adopt high-pressure homogenized oat formulations within compressed procurement cycles.
- Online Retail:Direct-to-consumer subscription models bypass slotting fees for premium organic and micro-foam optimized SKUs.
- Convenience Stores:Ambient liquid and single-serve powder sachets serve immediate consumption occasions in travel corridor locations.
Supermarkets command the established base. Coffee Shops show the steepest expansion trajectory through specialty chain standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barista culture and at-home brewing equipment penetration concentrate purchasing power among specialty coffee enthusiasts in suburban United States markets, while European retail buyers demand reformulation transparency under tightening novel food assessments.
United States
Single-serve espresso machine sales in Texas and Florida exceeded drip coffee maker volumes during the past holiday cycle, rotating demand toward micro-foam optimized formulations. FDA added-sugar disclosure mandates drive reformulation toward unsweetened variants in refrigerated dairy cases. Portland and Brooklyn roasters adopt high-pressure homogenized oat formulations within compressed procurement cycles.
Germany
Retail buyers prioritize hazelnut-flavored private-label development aligned with European taste preferences. EFSA novel food allergen threshold guidance forces batch-level certificates of analysis before purchase order authorization. Berlin-based specialty chains standardize oat protein emulsion procurement from regional grain processors.
United Kingdom
Clean-label enforcement accelerates displacement of conventional dairy creamers in mass-market grocery resets. EU organic regulation creates tiered market access rewarding certified producers with premium channel placement. London coffee shops specify barista-grade foam stability requirements for oat-based alternatives.
Netherlands
Specialty grain processors concentrate supply agreements with manufacturers racing to secure oat protein stabilization capacity. EFSA streamlined approval processes for almond and coconut extracts accelerate innovative formulation market entry. Amsterdam retail buyers demand shortened ingredient declarations for perimeter refrigerated placement.
Indonesia
Export demand pulls coconut protein emulsion innovations toward Asian specialty channels. Palm oil input cost fluctuations with Southeast Asian weather patterns compress margin stability for regional emulsion-based production. Jakarta foodservice operators develop proprietary creamer profiles through private-label ingredient systems.
Coffee Creamer Market Vendor Landscape
Player mix skews toward diversified multinational food conglomerates with captive dairy and plant protein processing assets. Market structure concentrates shelf presence through refrigerated distribution scale and retail slotting fee capacity. Strategic archetypes include manufacturing-scale liquid creamer suppliers, specialized non-dairy formulators, and private-label ingredient system providers. Dominant competitive moves center on portfolio diversification into oat and almond bases and strategic partnerships with specialty grain processors.
Among Swiss-based conglomerates, Nestlé S.A. represents manufacturing-scale dominance across North American retail liquid creamer shelves. Danone S.A. exemplifies specialized non-dairy formulation targeting lactose-intolerant and vegan consumer segments. Kerry Group plc occupies a position as a custom ingredient system supplier to private-label brands and foodservice operators.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone |
| Chobani LLC |
| DreamPak LLC |
| Viceroy Holland B.V. |
| PT Santos Premium Krimer |
| Kerry Group plc |
| FrieslandCampina |
| Land O'Lakes, Inc. |
| Others |
Supply Flow & Price Mechanics
Oat protein displacement of soy and dairy bases redraws procurement geography toward Nordic and North American grain processors while compressing formulation cost premiums against legacy emulsion systems. This substitution dynamic simultaneously elevates cold-chain logistics spending and concentrates supplier qualification burdens on manufacturers seeking clean-label shelf placement.
Pricing Analysis
High-pressure homogenization equipment upgrades separate premium liquid creamers from conventional gum-stabilized formulations and powdered alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects USDA organic certification status, barista-grade foam performance, and refrigerated versus ambient distribution requirements. Cost compression in mid-tier liquid formats is intensifying because oat protein stabilization patents concentrate among a handful of equipment suppliers. Foodservice operators demonstrate lowest price sensitivity due to menu differentiation imperatives, while institutional buyers in office coffee service remain most cost-responsive.
Supply Chain Analysis
Inventory cycles for specialty oat and almond protein concentrates now stretch 8-12 weeks longer than conventional dairy powder equivalents due to batch-level EFSA allergen documentation requirements. Supply concentrates in the United States, Canada, and Sweden for premium grain processing; Indonesia and the Philippines for coconut lipid extraction; and the Netherlands for European distribution hub consolidation. Raw material dependencies encompass Nordic oat cultivars, Southeast Asian palm and coconut oils, and North American sodium caseinate streams. Single-source vulnerability runs through specialty grain processors with validated high-pressure homogenization capacity. Distribution runs through refrigerated trucking networks concentrated among three national United States carriers and temperature-controlled European rail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise in plant protein thermal stability commands compensation premiums that constrain mid-tier manufacturer hiring pipelines, creating asymmetric capability access between conglomerates and emerging players. This scarcity dynamic rewards early investment in specialized talent acquisition and equipment partnerships.
For Market Incumbents: Secure exclusive supply agreements with Nordic and North American specialty grain processors before capacity expansion cycles complete. Defend shelf position by retrofitting aseptic filling lines for high-viscosity oat bases, as legacy dairy equipment shears plant lipid bodies below barista-grade foam thresholds. Prioritize dual USDA-EU organic certification to lock premium channel placement before validation timelines extend further.
For New Entrants and Emerging Players: Direct-to-consumer subscription fulfillment gaps where incumbents under-serve home brewing enthusiasts in Texas and Florida suburban markets represent the most penetrable entry vector. Target micro-foam optimized formulations with shortened ingredient declarations that bypass retail slotting fee barriers. Build go-to-market velocity through Portland and Brooklyn third-wave roaster partnerships before specialty chain procurement standardizes.
For Investors and Strategic Acquirers: EFSA's updated novel food allergen threshold guidance reshapes the acquisition landscape by elevating batch-level documentation capabilities above commodity manufacturing scale. Long-term viability over the next decade hinges on securing formulation scientists with dual plant protein and thermal stability expertise. Monitor German and Dutch retail buyer demands for shortened ingredient declarations as the signal indicating which acquisition targets possess compliant clean-label infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Homogenization Equipment Deployment | Enables three-ingredient clean-label declarations that unlock perimeter refrigerated placement in United States natural channels. |
| Dual USDA-EU Organic Certification Pursuit | Creates 18-24 month validation barriers that protect premium positioning against faster-follower competition. |
| Specialty Grain Processor Supply Agreements | Captures Nordic and North American oat protein capacity before competitor expansion cycles absorb available volume. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees while capturing home brewing enthusiasts in single-serve espresso machine penetration corridors. |
| Foodservice Customization Partnerships | Allows regional roasters to develop proprietary creamer profiles without captive production asset requirements. |
Methodological Framework
A spread of perspectives from formulation scientists at multinational food conglomerates, procurement directors at specialty coffee chains, refrigerated distribution logistics managers, and private-label brand managers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA labeling guidance documents, EFSA novel food assessment records, USDA organic certification databases, and Nielsen retail velocity data. Bottom-up SKU-level volume triangulation against top-down category expenditure estimates anchored the market sizing framework.
Segmentation dimensions modeled encompass product type (liquid, powdered, non-dairy, dairy-based), flavor profile, formulation certification tier, and distribution channel structure across the projection horizon. CAGRs were derived from weighted growth assumptions applied to each segment's base-year penetration and projected velocity shifts. Forecast inputs incorporated barista culture maturation indices in United States metropolitan statistical areas, single-serve espresso equipment penetration rates, and EFSA regulatory timeline probabilities.
Underlying assumptions cover sustained oat protein supply expansion, stable Southeast Asian palm oil export flows, and continued FDA enforcement of added-sugar disclosure mandates, with deviation risk concentrated in specialty grain processor capacity constraints and cold-chain logistics bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Butter Crisco Market
Processed Foods
Industrial Margarine Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Pizza Market
Processed Foods
Dairy Desserts Market
Processed Foods
Fat Free Food Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Processed Meat Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Europe Egg Powder Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
South America Soup Market
Processed Foods
Fermented Foods Market