
 Non-Dairy Yogurt Market | 2026-2036
Non-Dairy Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Dairy Yogurt Market Analysis
Plant-based food formulation expertise is unwinding supply constraints as trained dairy-alternative technologists migrate from conventional yogurt operations. Danone S.A. leverages its fermented-protein infrastructure to sustain multi-continental production of oat and almond bases. Chobani LLC anchors its competitive stance through in-house culture development for non-dairy matrices. Oatly AB differentiates via proprietary enzymatic processing that controls viscosity without added gums.
Non-dairy yogurt denotes a cultured, spoonable product manufactured from plant-derived substrates—typically oat, almond, coconut, or cashew bases—fermented with bacterial cultures at controlled temperatures to achieve target pH and texture. The finished product serves as a direct functional substitute for dairy yogurt in retail, foodservice, and ingredient applications, delivering comparable protein, fat, and probiotic profiles. Coconut yogurt dominates refrigerated shelf sets in North American supermarkets due to its creamy mouthfeel and established consumer recognition. Almond yogurt competes aggressively on price per ounce, capturing volume in conventional grocery channels where value positioning matters. Soy yogurt retains strength in Asian markets and health-food-store distribution where isoflavone content and protein completeness drive repeat purchase.
FDA labeling requirements for plant-based dairy alternatives shape how manufacturers position protein claims and nutritional equivalence on packaging. EFSA novel-food assessments for emerging bases such as fava bean or pea protein constrain European launch timelines and reformulation cycles. USDA organic certification and Non-GMO Project verification function as de facto market-access filters in premium retail channels. Stakeholders must monitor evolving enforcement of dairy-term restrictions across jurisdictions, as definitions of "yogurt" tighten or loosen depending on regulatory interpretation and industry litigation outcomes.
Market Dynamics
Clean-label formulation mandates from FDA and EFSA are forcing manufacturers to eliminate artificial stabilizers and declare allergen cross-contamination risks, compressing formulation cycles and raising R&D intensity across the supply base.
Growth Catalysts
- Foodservice Channel Expansion:Quick-service and fast-casual operators are accelerating bulk procurement of plant-based alternatives as consumer trial converts to repeat purchase in away-from-home occasions.
- REACH Compliance Infrastructure:European manufacturers that invested early in novel-food dossiers for emerging bases like fava bean protein now capture first-mover shelf space ahead of delayed entrants.
- Enzymatic Processing Advances:Proprietary viscosity-control methods eliminate dependency on added gums, satisfying clean-label requirements while maintaining spoonable texture targets.
Market Restraints
- Input Cost Volatility:Almond base pricing fluctuates with California drought cycles and pollination labor shortages, compressing margin predictability for value-positioned SKUs.
- Supply Concentration Risk:Coconut cream sourcing clusters in Southeast Asian processing hubs, exposing manufacturers to shipping lane disruptions and currency exposure.
- Technical Limitation:Protein completeness gaps in oat and coconut matrices require blending strategies or fortification, adding formulation complexity versus dairy equivalence claims.
Strategic Opportunities
- Underpenetrated European Markets:EFSA novel-food approval timelines have delayed German and French launches for pea-protein bases, creating white space for prepared entrants.
- Ingredient Application Pivot:Non-dairy yogurt is penetrating smoothie formulations and frozen dessert bases as food manufacturers seek cultured acidity without dairy allergen labeling.
- USDA Organic Certification Tailwind:Premium retail channels increasingly filter access through organic and Non-GMO Project verification, rewarding early certifiers with preferred placement.
Industry Challenges
- Fermentation Technologist Scarcity:Trained dairy-alternative culture specialists remain concentrated in legacy operations, slowing scale-up for new market entrants.
- Cross-Contamination Compliance Burden:Shared production lines require validated cleaning protocols and declared allergen risk statements, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Dairy Yogurt Market |
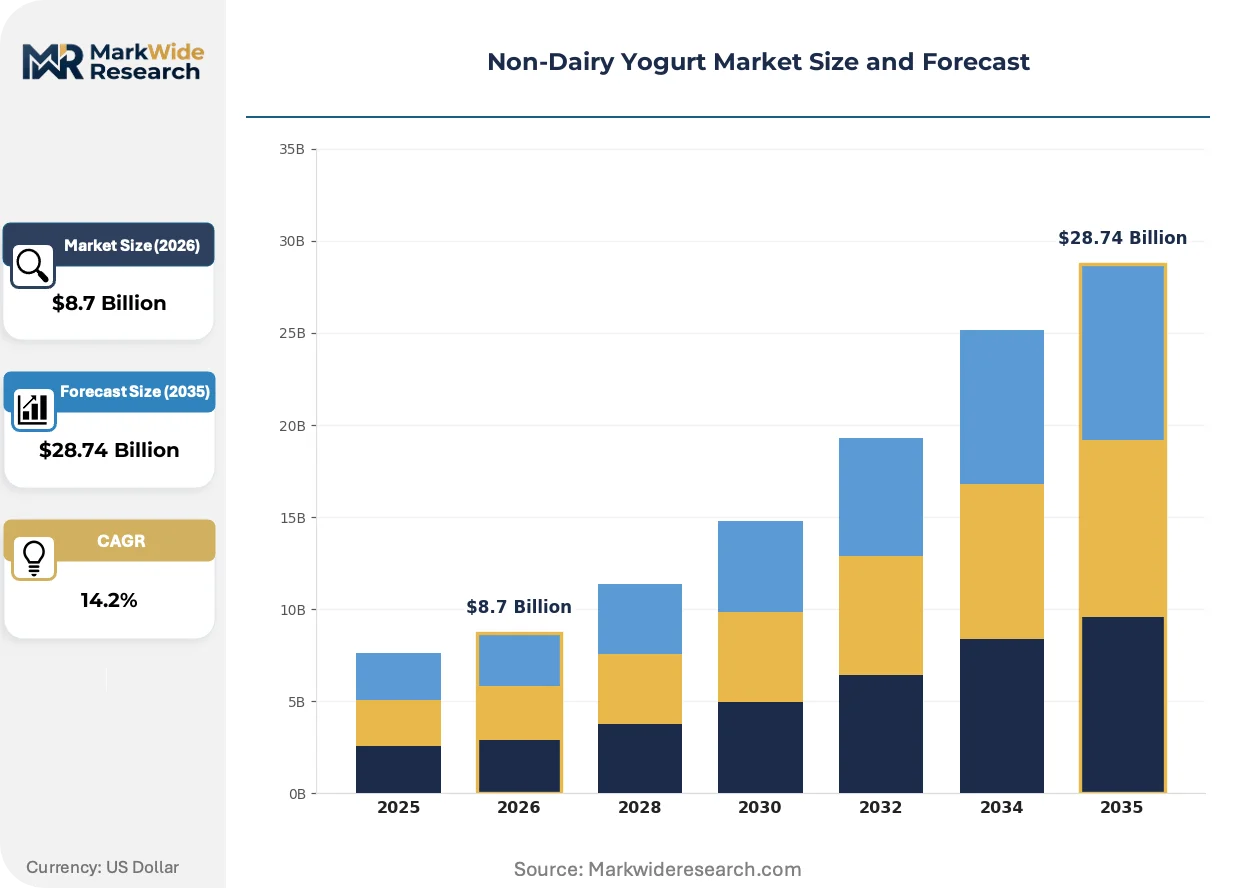
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Yogurt, Almond Yogurt, Soy Yogurt, Cashew Yogurt Flavor: Vanilla, Blueberry, Mango, Strawberry Packaging Type: Plastic Cups, Glass Jars, Tetra Packs, Pouches Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores |
| Companies Covered | Chobani LLC, Kite Hill Inc., The Hain Celestial Group Inc., Oatly AB, Forager Project LLC, Danone S.A., Nestlé SA, Good Karma Foods Inc., General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Dairy Yogurt Market Emerging Trajectories
Formulation science and regulatory interpretation are actively reshaping competitive positioning, with enzymatic methods and clean-label mandates compressing traditional additive-dependent production models.
Precision fermentation of oat substrates is supplanting conventional starch-hydrolysis approaches in texture engineering. Mid-tier manufacturers adopting these methods achieve viscosity targets without locust bean gum or carrageenan, satisfying retailer clean-label requirements while reducing ingredient cost complexity.
EFSA novel-food assessments for emerging protein bases are tightening European launch windows and extending reformulation cycles. Manufacturers targeting fava bean or chickpea substrates face 12-18 month evaluation timelines, compressing first-mover advantages and favoring incumbents with established dossier expertise.
Retail procurement patterns are consolidating around certified organic and non-GMO verification as table-stakes requirements. Conventional grocery buyers in the United States now prioritize suppliers with dual certification, displacing uncertified alternatives from premium shelf sets and channeling volume toward compliant producers.
Non-Dairy Yogurt Market Segmentation
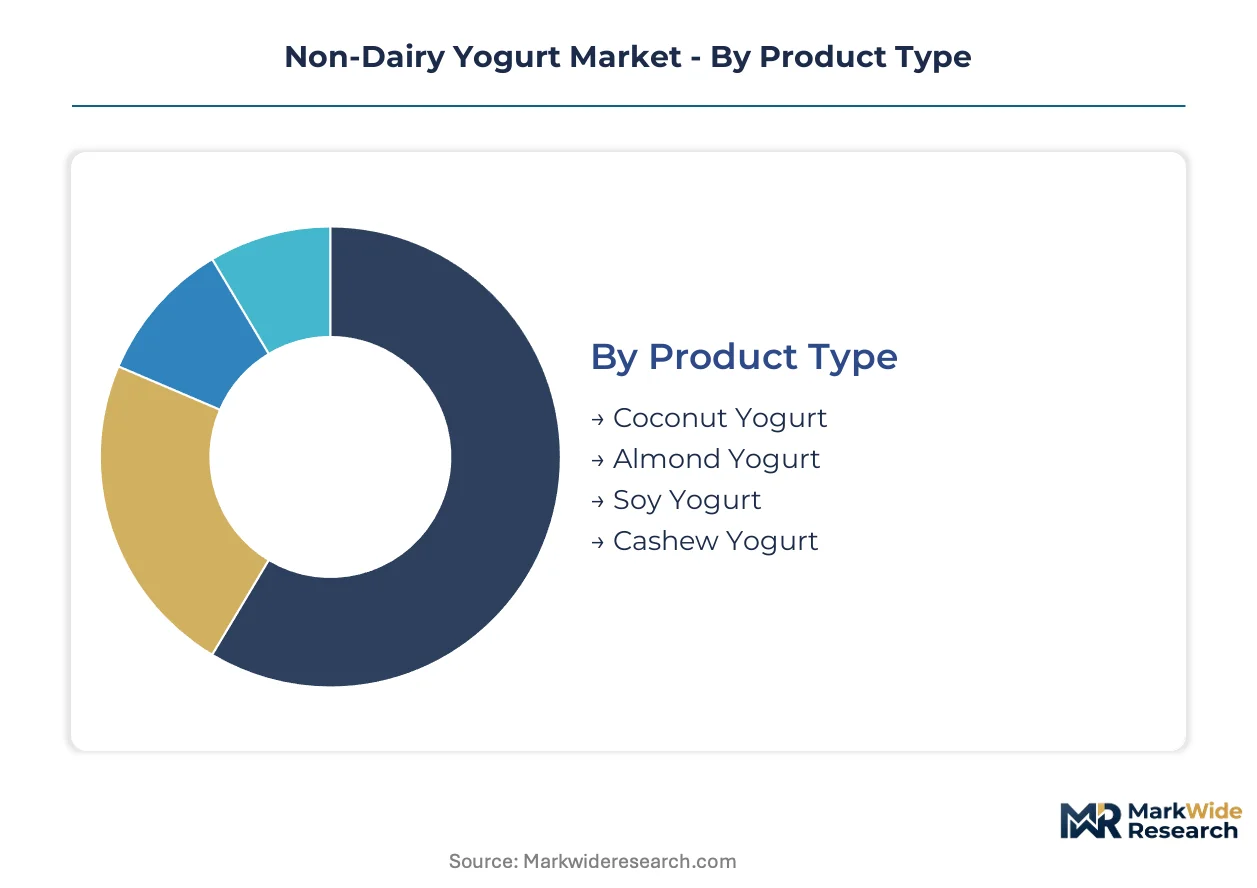
Segmentation in non-dairy yogurt reveals how substrate selection, flavor positioning, and channel strategy interact to determine margin capture. Manufacturers optimize formulations differently for conventional grocery velocity versus premium health-store placement.
Product Type:
Channel mix varies sharply by base substrate, with coconut and almond variants dominating conventional retail while soy retains foodservice and ethnic grocery strength.
- Coconut Yogurt:High-fat coconut cream delivers spoonable viscosity without added stabilizers, satisfying clean-label requirements. United States conventional supermarkets allocate prime refrigerated placement to coconut-based SKUs, driven by established consumer recognition and creamy mouthfeel expectations.
- Almond Yogurt:Lower input costs versus coconut enable aggressive price-per-ounce positioning in value-oriented channels. California almond processing clusters support supply chain efficiency for North American manufacturers, though drought-driven input volatility compresses margin predictability.
- Soy Yogurt:Retains strength in Asian markets and health-food distribution where isoflavone content and protein completeness drive repeat purchase.
- Cashew Yogurt:Premium positioning in specialty retail leverages cashew's neutral flavor profile for clean-label dessert applications.
Coconut yogurt dominates installed base. Almond yogurt is where expansion concentrates.
Flavor:
Flavor selection maps directly to occasion-based consumption patterns and daypart targeting across retail and foodservice channels.
- Vanilla:Neutral base flavor supports mix-in customization and smoothie ingredient applications, capturing volume in bulk foodservice formats.
- Blueberry:Antioxidant positioning resonates in premium health-store channels where functional claims drive purchase decisions.
- Mango:Tropical flavor profile targets ethnic grocery segments and summer seasonal promotions in conventional retail.
- Strawberry:Mainstream acceptance makes this the default flavor for trial-size introductions and children's lunchbox formats.
Vanilla commands the broadest channel presence. Blueberry is climbing the fastest in premium placement.
Packaging Type:
Packaging economics determine which segments achieve profitability at different volume tiers and retail formats.
- Plastic Cups:Lightweight, shatter-resistant format dominates conventional grocery refrigerated sets and quick-service bulk procurement.
- Glass Jars:Premium positioning in specialty retail and zero-waste store formats supports higher price points through perceived sustainability.
- Tetra Packs:Ambient stability enables distribution expansion into convenience stores and emerging market retail with limited cold chain.
- Pouches:Single-serve portability targets on-the-go consumption and children's snacking occasions in school and travel channels.
Plastic cups anchor volume throughput. Glass jars are gaining share fastest in sustainability-positioned retail.
Distribution Channel:
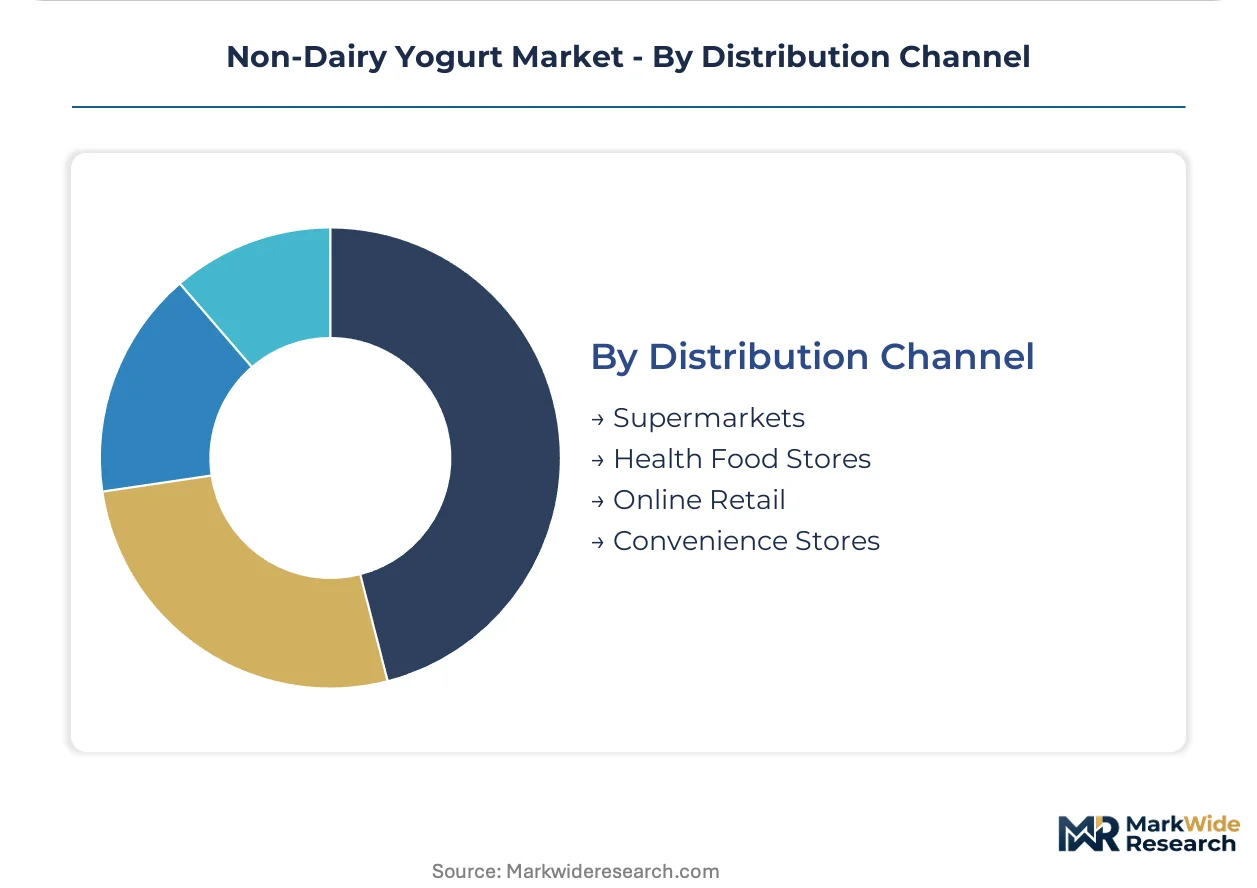
Channel selection dictates certification requirements, margin structure, and formulation complexity for manufacturers.
- Supermarkets:Conventional grocery buyers prioritize dual organic and non-GMO certification as table-stakes for shelf placement, filtering supplier access.
- Health Food Stores:Smaller format retail rewards probiotic strain specificity and functional ingredient fortification with premium positioning.
- Online Retail:Direct-to-consumer and marketplace channels enable subscription models and variety pack configurations unavailable in brick-and-mortar.
- Convenience Stores:Grab-and-go occasion targeting requires single-serve packaging and extended shelf-life formulations through aseptic processing.
Supermarkets control volume concentration. Online retail is where steepest expansion trajectory materializes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling requirements for plant-based dairy alternatives anchor demand concentration in the United States, where retail shelf space expansion and foodservice channel penetration drive volume leadership. Regulatory interpretation of dairy-term usage varies sharply across jurisdictions, fragmenting go-to-market strategies by geography.
United States
Conventional grocery buyers prioritize dual organic and non-GMO certification as table-stakes for shelf placement, filtering supplier access to premium refrigerated sets. FDA enforcement of protein claim substantiation shapes how manufacturers position nutritional equivalence on packaging. California almond processing clusters support supply chain efficiency for North American manufacturers, though drought-driven input volatility compresses margin predictability.
Germany
EFSA novel-food assessments for emerging protein bases constrain launch timelines for fava bean and chickpea substrates, compressing first-mover advantages. REACH compliance infrastructure rewards early investors in dossier preparation with accelerated market access. Berlin and Hamburg anchor retail distribution networks for plant-based alternatives, with conventional grocery chains expanding dedicated shelf space.
France
ANSM oversight of novel-food safety evaluations extends reformulation cycles for emerging bases, favoring incumbents with established regulatory expertise. Île-de-France concentrates foodservice procurement decisions for quick-service operators accelerating plant-based menu placements. Paris-based retail buyers increasingly filter access through organic certification and clean-label verification.
United Kingdom
Post-Brexit regulatory divergence from EU novel-food frameworks creates parallel compliance burdens for manufacturers targeting both markets. London and the Southeast dominate retail concentration for premium plant-based alternatives, with health-food store networks driving probiotic strain specificity. FSA guidance on allergen cross-contamination declarations shapes manufacturing protocol investments.
China
SAMR oversight of plant-based dairy alternative labeling creates uncertainty around protein claim permissibility, slowing multinational launch timelines. Yangtze River Delta manufacturing hubs develop enzymatic processing capabilities for oat substrate viscosity control. Shanghai retail buyers pilot clean-label verification programs, channeling volume toward certified suppliers.
Non-Dairy Yogurt Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary enzymatic processing specialists commanding premium positioning while scale-driven dairy-alternative operations capture volume in conventional grocery. The vendor base fragments across fermentation infrastructure ownership, clean-label certification status, and substrate sourcing strategies. Three archetypes dominate: legacy dairy converters leveraging existing culture development capabilities, oat-focused specialists controlling viscosity without added gums, and diversified food conglomerates optimizing cross-category procurement leverage. M&A activity concentrates on fermentation technologist acquisition and regional brand consolidation, while capacity expansion targets enzymatic processing scale-up in North American and European production hubs.
Within the legacy dairy converter tier, Danone S.A. and Chobani LLC exemplify archetypes leveraging fermented-protein infrastructure and in-house culture development respectively. Among oat-focused specialists, Oatly AB occupies a position defined by proprietary enzymatic processing methods. These three companies anchor competitive dynamics, with each representing distinct strategic bets on substrate specialization, regulatory dossier depth, and channel access prioritization.
| Leading Market Players |
|---|
| Chobani LLC |
| Kite Hill Inc. |
| The Hain Celestial Group Inc. |
| Oatly AB |
| Forager Project LLC |
| Danone S.A. |
| Nestlé SA |
| Good Karma Foods Inc. |
| General Mills Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at California almond processing clusters shapes margin floors for North American manufacturers, compressing price flexibility when drought cycles tighten kernel supply. Scale advantages in enzymatic processing facilities allow oat-base specialists to defend price positions without locust bean gum dependencies, while smaller coconut-cream processors absorb currency exposure from Southeast Asian sourcing.
Pricing Analysis
United States conventional grocery channels price almond yogurt 15-25 percent below coconut equivalents per ounce, reflecting California kernel processing scale versus imported cream logistics. Three-tier pricing structure across premium, standard, and economy levels separates certified organic probiotic strains from conventional base formulations. Cost compression in value-positioned SKUs is intensifying because almond input volatility forces margin trade-offs. Foodservice bulk buyers exhibit highest price sensitivity, while health-food store consumers accept premiums for strain-specific functional claims.
Supply Chain Analysis
California anchors almond base supply with kernel processing clusters concentrated in the Central Valley, while Thailand and Indonesia dominate coconut cream extraction for North American refrigerated sets. Raw material flows draw from California pollination-dependent orchards, Southeast Asian copra crushing hubs, and Nordic enzymatic processing facilities. Single-source vulnerability concentrates in California drought exposure for almond pricing and Malacca Strait shipping lanes for coconut cream delivery. Distribution runs through conventional grocery refrigerated sets, foodservice broadline distributors, and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from precision-fermented dairy proteins that bypass plant-base formulation constraints entirely, requiring defensive repositioning around clean-label credibility and culture-development moats.
For Market Incumbents: Fortify fermentation technologist retention through captive culture-development programs and in-house enzymatic processing scale-up in North American production hubs. Secure backward integration into oat substrate supply through direct agricultural partnerships, reducing dependency on commodity spot markets. Prioritize dual organic and non-GMO certification maintenance as conventional grocery buyers harden table-stakes requirements.
For New Entrants and Emerging Players: Anchor in German and French retail white space where EFSA novel-food timelines have delayed pea-protein and fava-bean base launches. Target foodservice ingredient applications for smoothie and frozen dessert formulations, where cultured acidity demand outpaces dairy-alternative supply. Lead with enzymatic viscosity-control claims that eliminate added gums, satisfying retailer clean-label procurement filters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation infrastructure owners with established regulatory dossier expertise over brand-dependent marketing plays. Long-term viability hinges on substrate diversification capabilities and culture-development IP depth. Watch EFSA enforcement patterns on dairy-term restrictions as the inflection signal for European market access valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Scale-Up | Proprietary viscosity methods satisfy FDA clean-label guidance while reducing gum dependencies. |
| EFSA Novel-Food Dossier Investment | Early REACH compliance infrastructure captures German and French shelf space ahead of delayed entrants. |
| Fermentation Technologist Acquisition | Trained culture specialists remain concentrated, slowing scale-up for unprepared competitors. |
| Organic Certification Acceleration | USDA and Non-GMO Project verification function as de facto filters for premium retail placement. |
| Foodservice Channel Expansion | Bulk procurement by quick-service operators converts consumer trial into repeat away-from-home purchase. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plant-based R&D directors, fermentation technologists, conventional grocery category buyers, foodservice procurement managers, and regulatory affairs specialists. Secondary validation drew from FDA labeling guidance documents, EFSA novel-food assessment registers, USDA organic certification databases, customs trade flow records, and Nielsen retail audit data. Bottom-up volume estimates triangulated against top-down category spending analysis across the projection horizon.
Across the analysis window, the quantitative framework modeled substrate type, flavor positioning, packaging format, distribution channel, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from trend extrapolation adjusted for input cost volatility and certification penetration curves. Forecast inputs incorporated enzymatic processing adoption rates, EFSA dossier approval timelines, and foodservice channel conversion metrics.
Underlying assumptions cover stable FDA enforcement of protein claim substantiation and EFSA novel-food evaluation pacing, with deviation risk concentrated in California drought severity and shipping lane disruption frequency. Recalibration cycles align with material shifts in clean-label procurement requirements and dairy-term restriction litigation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Germany Dairy Alternatives Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market