
 Global Dairy Cream Market | 2026-2036
Global Dairy Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dairy Cream Market Foresight
Single-source reliance on captive dairy herds is decoupling from multi-source milk pooling across cooperatives and independent farms. Fonterra Cooperative Group leverages its New Zealand farmer network to sustain grass-fed cream differentiation in export markets. Nestlé anchors its supply security through backward integration into regional cold-chain infrastructure across multiple continents. Amul competes on cost through its Gujarat-based cooperative model that controls procurement from millions of smallholder farmers.
Dairy cream denotes the fat-rich layer skimmed from milk, typically containing 18-40% milkfat depending on intended function, with whipping variants requiring minimum 30% fat to achieve stable foam structures in commercial kitchens. The ingredient serves as a texturizing and flavor-carrying base across baking, beverage, and confectionery production lines. Whipping cream occupies the largest margin pool among product types due to premium pricing in foodservice channels, while sour cream is gaining traction in culinary applications driven by fusion cuisine trends. Liquid form dominates institutional procurement volumes, though powder formats are expanding in regions with unreliable cold-chain coverage.
FDA standards in the United States mandate minimum fat content thresholds and pasteurization protocols that shape product formulation and cross-border trade eligibility. EFSA and EU MDR frameworks govern labeling, additive use, and hygiene standards for cream sold across member states, creating compliance cost tiers that favor scaled processors. India's FSSAI enforces fat percentage disclosure and microbial limits that determine market access for domestic and imported brands. Stakeholders must monitor evolving refrigerant regulations and fat-standard harmonization talks that will reshape sourcing territories and plant certification requirements.
Market Dynamics
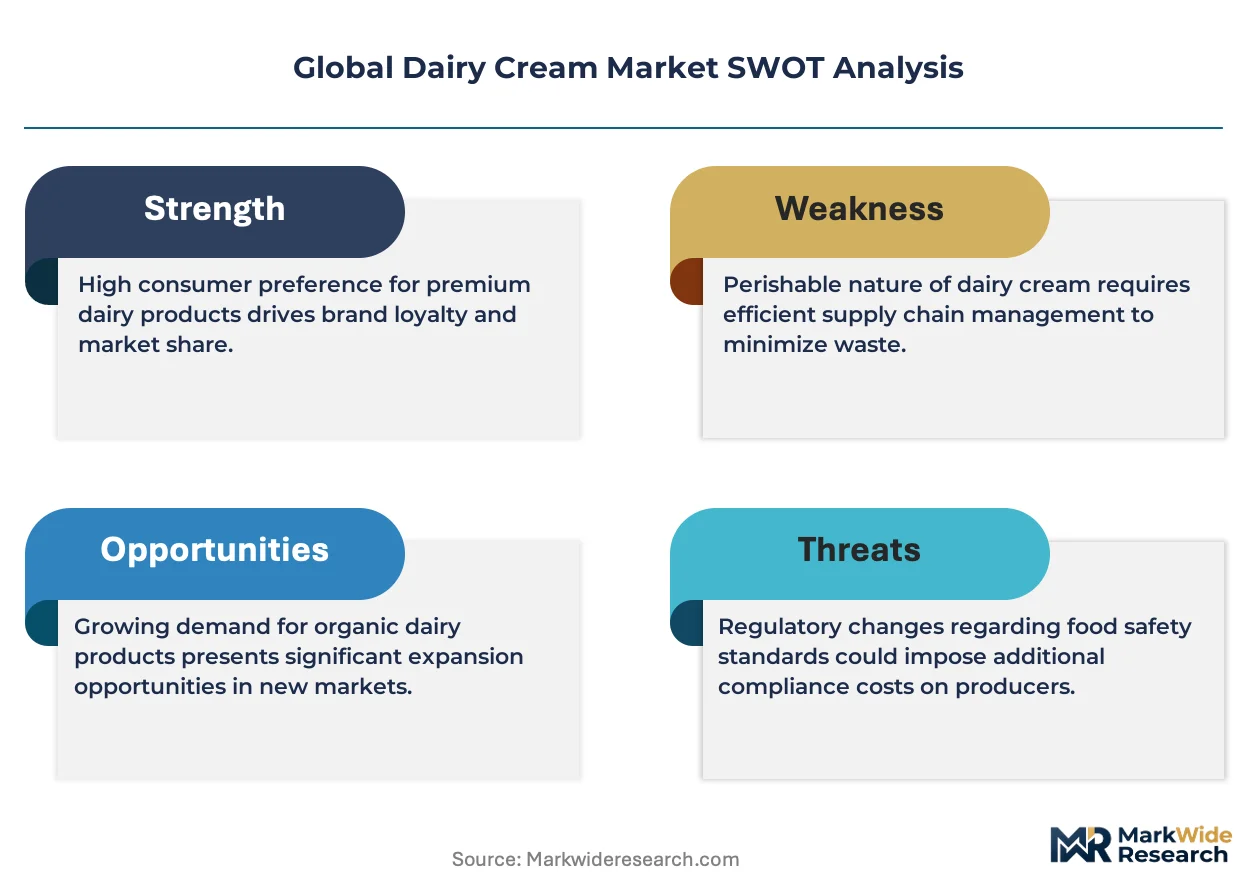
EU F-Gas Regulation phase-down protocols are forcing cold-chain operators to retrofit refrigeration systems for cream storage, compressing operating margins while reshaping capital allocation across logistics networks.
Growth Catalysts
- Quick-service restaurant expansion:Chains in India are standardizing whipped cream applications across beverage and dessert menus, driving bulk procurement contracts for high-fat variants.
- EU Green Deal refrigerant mandates:Lower-GWP alternatives are accelerating equipment replacement cycles in European dairy logistics, creating upgrade demand for compliant cold storage infrastructure.
- Fusion cuisine adoption:Southeast Asian hotels are incorporating sour cream into pastry and savory applications, expanding the addressable foodservice base beyond traditional Western formats.
Market Restraints
- Feed cost volatility:Grass-fed and grain-fed dairy input costs fluctuate with commodity markets, compressing processor margins during price spikes.
- New Zealand supply concentration:Fonterra's cooperative network controls a disproportionate share of export-grade cream, creating single-source dependency risks for international buyers.
- Plant-based substitution:Oat and coconut cream alternatives are capturing lactose-intolerant and vegan consumer segments in premium urban markets.
Strategic Opportunities
- Powder format penetration:Regions with unreliable electricity infrastructure in Africa and South Asia present untapped demand for ambient-stable cream powders in institutional baking.
- Carbon labeling differentiation:EU CSRD disclosure requirements are creating first-mover advantage for processors with verified low-emission supply chains.
- Direct-to-foodservice platforms:Digital procurement portals are bypassing traditional distributor layers, enabling margin capture and customer data ownership for mid-scale processors.
Industry Challenges
- Cold-chain technician scarcity:Qualified refrigeration specialists for dairy-grade equipment are in short supply across emerging markets, extending maintenance response times.
- Multi-jurisdiction certification complexity:Harmonizing FDA pasteurization documentation with EFSA additive standards and FSSAI microbial limits stretches compliance timelines for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dairy Cream Market |
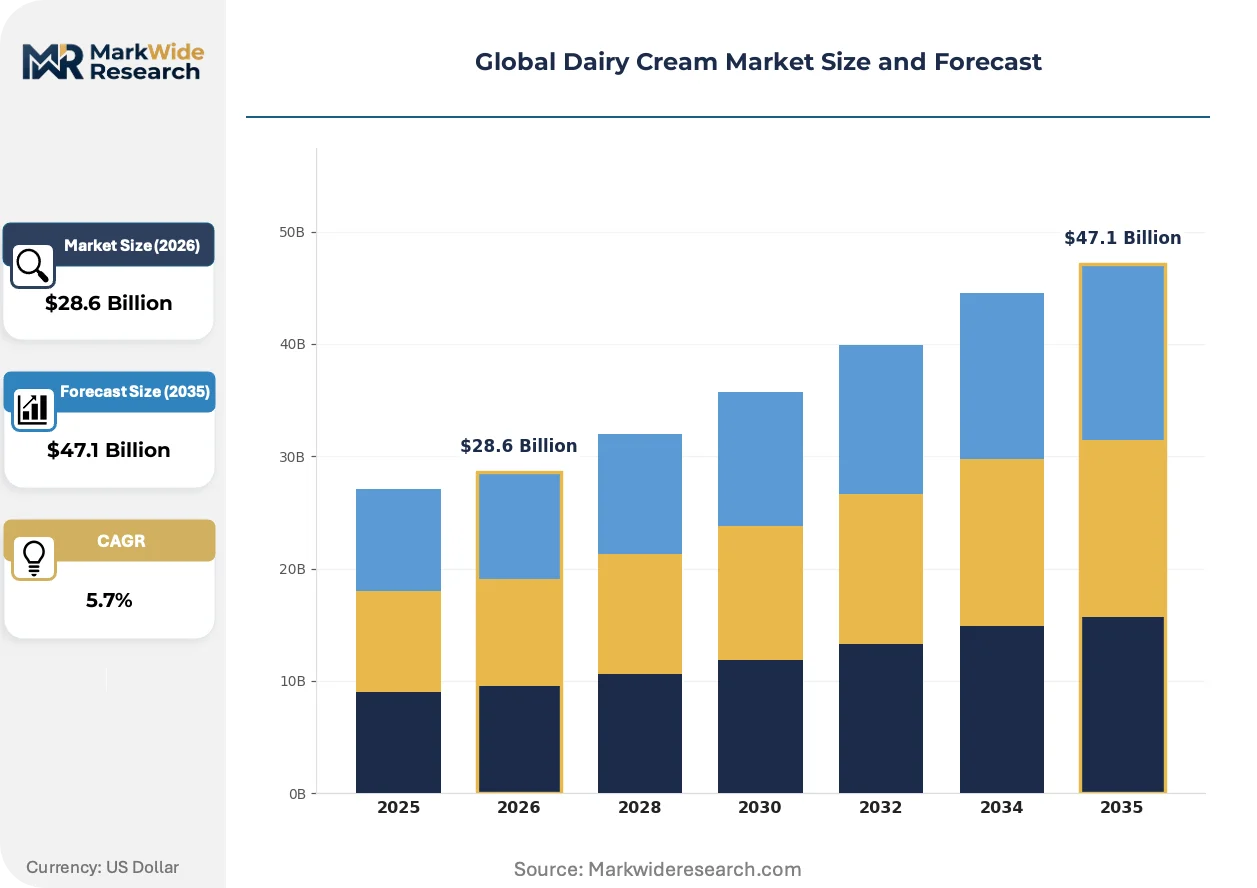
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.1 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whipping Cream, Double Cream, Single Cream, Clotted Cream, Sour Cream Form: Liquid, Powder, Concentrate, Frozen Application: Baking Ingredients, Beverage Components, Dairy Desserts, Confectionery, Culinary Use End User: Food Processing Units, Baking Industry, Beverage Manufacturers, Hotels & Restaurants |
| Companies Covered | Lactalis Group, Nestlé, Dairy Farmers of America, Danone, Arla Foods, FrieslandCampina, Fonterra Cooperative Group, Amul, Land O'Lakes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dairy Cream Market Shifts & Advancements
Aseptic processing advances and clean-label formulation pressures are converging to redefine product stability claims and ingredient transparency expectations across retail and foodservice channels.
High-pressure processing technology is unifying extended shelf-life guarantees with reduced thermal degradation of flavor compounds. Premium ice cream manufacturers in Japan and Western Europe are adopting HPP lines at commercial scale. This convergence is unifying clean-label positioning with logistics flexibility previously reserved for UHT alternatives.
REACH chemical safety frameworks are tightening scrutiny on processing aids and packaging migrants in EU dairy applications. Manufacturers are reformulating to exclude substances under enhanced authorization review. Whipping cream segments with complex additive profiles face the steepest compliance cost escalation.
Foodservice buyers are consolidating supplier relationships toward single-source cream contracts with integrated technical support. Independent bakeries and mid-size restaurant groups are abandoning spot-market purchasing for annual volume agreements with specified fat-content tolerances. This concentration is most visible in India's organized retail corridor from Mumbai to Bangalore.
Global Dairy Cream Market Segmentation
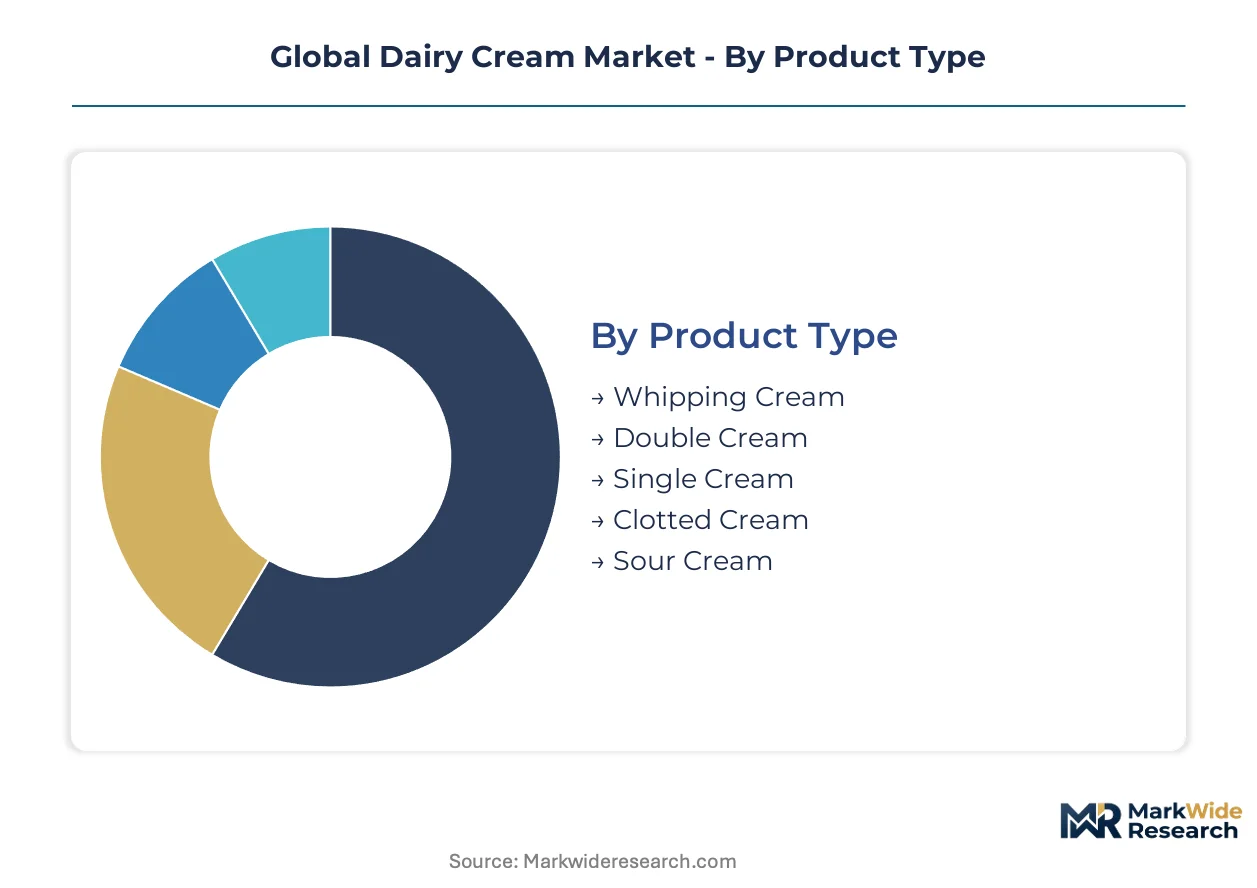
Dairy cream segmentation reveals how fat content specifications, stability requirements, and channel economics partition procurement behavior across food manufacturing and foodservice verticals. Understanding these axes enables processors to align formulation investments with margin concentration points.
Product Type:
Fat percentage thresholds and aeration properties define functional suitability across baking, beverage, and savory applications.
- Whipping Cream:Minimum 30% milkfat content enables stable foam structures required for dessert toppings and beverage applications. Quick-service restaurant chains in India are standardizing this variant across beverage and dessert menus, locking in annual volume contracts with specified fat-content tolerances.
- Sour Cream:Cultured cream with elevated acidity levels serves as a texturizing base for fusion cuisine applications. Southeast Asian hotels are incorporating this variant into pastry and savory formats, expanding addressable foodservice demand beyond traditional Western culinary contexts.
- Double Cream:48% milkfat content delivers rich mouthfeel for premium confectionery and sauce applications.
- Single Cream:18% fat content suits coffee whitening and light sauce applications where viscosity requirements are modest.
- Clotted Cream:Traditional 55% fat content variant retains niche positioning in specialty bakery and heritage foodservice channels.
Whipping cream leads on scale; sour cream leads on momentum.
Form:
Stability requirements and cold-chain reliability determine format selection across institutional procurement channels.
- Liquid:Fresh cream in fluid state dominates institutional procurement volumes where refrigeration infrastructure is dependable. Foodservice buyers are consolidating toward single-source contracts with integrated technical support, abandoning spot-market purchasing for annual volume agreements.
- Powder:Spray-dried cream with extended ambient stability addresses supply gaps in regions with unreliable electricity infrastructure. Africa and South Asia present untapped demand for this format in institutional baking where cold-chain continuity cannot be guaranteed.
- Concentrate:Reduced water content lowers transport costs for long-haul distribution to remote manufacturing facilities.
- Frozen:Blast-frozen cream extends shelf life for industrial users with controlled thawing protocols.
Liquid leads on scale; powder leads on momentum.
Application:
End-use processing conditions and finished product specifications drive fat content and stability requirements.
- Baking Ingredients:Cream functions as a texturizing and flavor-carrying base across pastry production lines. Independent bakeries are migrating from spot procurement to specified fat-content contracts with technical support provisions.
- Beverage Components:Whipped cream toppings and cream-based beverage bases require consistent aeration performance. Chains in India are driving bulk procurement of high-fat variants for standardized menu applications.
- Dairy Desserts:Ice cream and mousse applications demand precise fat percentages for freeze-thaw stability.
- Confectionery:Ganache and truffle production requires specific viscosity profiles achievable only with defined fat ratios.
- Culinary Use:Sauce and soup applications utilize cream for emulsion stability and flavor delivery.
Baking ingredients leads on scale; beverage components leads on momentum.
End User:
Scale and technical sophistication determine procurement modality and supplier relationship structure.
- Hotels & Restaurants:Foodservice channels command premium pricing for whipping cream variants with specified performance guarantees. Digital procurement portals are bypassing traditional distributor layers, enabling margin capture and customer data ownership for mid-scale processors serving this segment.
- Food Processing Units:Industrial manufacturers prioritize volume consistency and documentation compliance for multi-jurisdiction certification. Harmonizing FDA pasteurization documentation with EFSA additive standards stretches compliance timelines for exporters serving these buyers.
- Baking Industry:Artisan and industrial bakeries require fat-content precision for recipe standardization.
- Beverage Manufacturers:Ready-to-drink and coffee chain suppliers demand aseptic processing compatibility.
Hotels and restaurants leads on scale; food processing units leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's cooperative dairy belt anchors global cream supply networks through Amul's farmer federation model. Regional procurement patterns concentrate in dairy processing clusters with cold-chain infrastructure maturity and foodservice channel density.
United States
Quick-service restaurant chains standardize whipped cream applications across beverage menus, locking in bulk procurement contracts. FDA pasteurization thresholds shape cross-border formulation compliance. Wisconsin and California dairy cooperatives supply industrial volumes to Midwest and West Coast food manufacturing corridors.
India
Organized retail and QSR expansion from Mumbai to Bangalore drive whipping cream procurement at scale. FSSAI fat percentage disclosure mandates determine import eligibility for international brands. Gujarat's Anand district hosts the cooperative processing infrastructure that feeds national distribution networks.
Germany
EU F-Gas Regulation retrofit requirements compress cold-chain operator margins while accelerating lower-GWP equipment adoption. EFSA additive standards govern reformulation costs for export-bound production. Bavarian dairy processors supply premium confectionery channels across Central Europe.
Japan
Premium ice cream manufacturers adopt high-pressure processing lines for extended shelf-life without thermal degradation. METI energy efficiency standards influence refrigeration equipment selection. Tokyo-Osaka foodservice corridors command technical performance guarantees from specialized cream suppliers.
New Zealand
Fonterra's farmer cooperative network sustains grass-fed cream differentiation in premium export markets. Dairy-grade cold storage infrastructure concentrates in Waikato and Canterbury processing zones. Export certification harmonization with EU and US standards stretches compliance timelines for international shipments.
Global Dairy Cream Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue plant-based alternatives and powder format niches. The vendor base stratifies across cooperative structures, multinational processors, and regional dairy federations. Three archetypes dominate: grass-fed premium exporters, cost-optimized cooperative networks, and vertically integrated foodservice suppliers. Competitive moves center on cold-chain infrastructure control and direct-to-foodservice digital procurement platforms.
Among cooperative-based processors, Fonterra Cooperative Group and Amul exemplify divergent scale models—Fonterra anchoring export-grade premium positioning through New Zealand farmer networks, Amul compressing costs via Gujarat's smallholder aggregation. Nestlé occupies the multinational integration tier with backward control over regional cold-chain assets across multiple continents. Lactalis Group, Danone, and Arla Foods sit within the European processor cluster where EFSA compliance costs favor scaled operations.
| Leading Market Players |
|---|
| Lactalis Group |
| Nestlé |
| Dairy Farmers of America |
| Danone |
| Arla Foods |
| FrieslandCampina |
| Fonterra Cooperative Group |
| Amul |
| Land O'Lakes |
| Others |
Supply & Pricing Matrix
Qualified refrigeration technicians for dairy-grade equipment cluster in New Zealand and the European Union, where labor-cost differentials between these hubs and emerging markets widen pricing-tier spreads across premium and economy cream segments.
Pricing Analysis
Input-cost pass-through from feed and energy commodities shapes contract structures across the industry. Pricing stratifies across premium grass-fed tiers, standard commercial grades, and economy bulk variants, with certification grade and volume scale as primary differentiation levers. Cost compression in the economy tier is intensifying because grain-fed input volatility and refrigerant retrofit expenses squeeze processor margins. Quick-service restaurant chains exhibit highest price sensitivity due to standardized menu cost targets, while premium confectionery manufacturers show lowest sensitivity given formulation performance requirements.
Supply Chain Analysis
Milkfat supply rests on New Zealand's cooperative processing infrastructure, India's Gujarat-based smallholder aggregation networks, and Germany's Bavarian dairy clusters. Raw material dependencies center on grass and grain feed inputs, specialized cold-storage equipment, and aseptic packaging materials. Single-source vulnerability concentrates in Fonterra's export-grade cream dominance, creating procurement risk for international buyers. Distribution runs through foodservice procurement portals and institutional baking supply networks, with direct-to-manufacturer contracts bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Dairy Cream Market offers margin-expansion pathways through carbon-labeling premium capture and powder-format cost arbitrage in cold-chain-deficient regions.
For Market Incumbents: Lock in grass-fed supply contracts with New Zealand farmer networks to defend premium positioning against plant-based substitutes. Deepen backward integration into regional cold-chain infrastructure to capture logistics margin and secure F-Gas Regulation compliance ahead of retrofit deadlines. Channel control through direct-to-foodservice digital platforms offers customer data ownership and pricing power. For New Entrants and Emerging Players: Launch via ambient-stable powder formats targeting institutional baking in African and South Asian markets where electricity reliability gaps persist. The most penetrable segment lies in mid-scale food processors seeking technical support bundled with volume contracts. A clean-label formulation positioning with minimal additive profiles addresses REACH-driven reformulation demand in EU-bound exports. For Investors and Strategic Acquirers: Mid-scale processors with verified low-emission supply chains and established foodservice portal relationships are the most active acquirer targets in this space. Long-term viability hinges on carbon-labeling differentiation and cold-chain infrastructure control over the next decade. Watch EU CSRD disclosure depth and refrigerant retrofit completion rates as inflection indicators for premium-tier margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold-Chain Infrastructure | Nestlé's regional asset control secures supply continuity across multiple continents under F-Gas mandates. |
| Powder Format Manufacturing Scale-Up | Africa and South Asia institutional baking demand creates first-mover advantage in ambient-stable cream supply. |
| Carbon Labeling Certification Investment | EU CSRD disclosure requirements reward verified low-emission supply chains with premium positioning. |
| Direct-to-Foodservice Digital Platform Launch | Mid-scale processors bypass distributor layers to capture margin and own customer data in India. |
| Clean-Label Formulation Reformulation | REACH scrutiny on processing aids drives additive-free whipping cream compliance cost escalation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged dairy processing executives, cold-chain logistics operators, foodservice procurement managers, and cooperative federation leaders. Secondary validation drew from customs trade data, FSSAI disclosure filings, EU EFSA additive standards documentation, and SEC processor filings. Bottom-up volume modeling and top-down macroeconomic anchoring were cross-checked for consistency.
Historical reference periods anchored the projection horizon to established growth trajectories across product type, form, application, and end-user dimensions. CAGRs were derived from segmented demand modeling and input-cost elasticity analysis. Forecast inputs incorporated QSR expansion rates in India, EU refrigerant phase-down timelines, and powder-format penetration curves in cold-chain-deficient markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under feed commodity spikes and multi-jurisdiction certification delays. Assumptions reflect documented stakeholder input and secondary data triangulation. Feed cost volatility, F-Gas retrofit compliance timelines, and plant-based substitution rates in premium urban markets warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Milk Powder Market
Dairy Products
Latin America Cheese Market
Dairy Products
Global Dairy Market
Dairy Products
China Dairy Market
Dairy Products
Donkey Milk Market
Dairy Products
Europe Yogurt Market
Dairy Products
High Protein Yogurt Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Middle East Dairy Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Germany Milk Protein Market
Dairy Products
Evaporated Milk Market
Dairy Products
South America Yogurt Market
Dairy Products
Processed Cheese Market
Dairy Products
North America Casein Market