
 Low-Fat Ham Market | 2026-2036
Low-Fat Ham Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Ham Market Analytics
Consolidation among supermarket buying groups is realigning procurement leverage across the low-fat ham supply base. JBS S.A. leverages its integrated pork processing network to secure volume contracts with centralized retail purchasers. Danish Crown AmbA anchors its position through cooperative-owned slaughtering capacity that sustains cost discipline. Hormel Foods Corp differentiates via branded health-positioned lines that command premium placement in consolidated channels.
Low-fat ham denotes pork muscle tissue with fat content reduced below standard cured or cooked ham specifications, typically achieved through lean cut selection, trim optimization, or post-curing lipid modification, and serves commercial food manufacturing and retail deli cases where nutritional labeling drives purchase decisions. The cooked segment dominates volume throughput owing to extended shelf stability and food service compatibility, while reduced sodium variants capture expanding margin pools as reformulation investments convert label claims into price premiums. The food service distribution channel navigates operational complexity from shorter delivery windows and specification exactness, whereas supermarkets consolidate category management authority over planogram allocation.
The USDA's Food Safety and Inspection Service sets maximum ingoing nitrite limits that govern curing formulations, while the FDA oversees nutrition labeling claims including "lean" and "reduced fat" eligibility thresholds that shape product development priorities. The EU's EFSA evaluates processed meat additive safety profiles under renewed scientific scrutiny, influencing import acceptance criteria and domestic reformulation mandates. Stakeholders must monitor divergence between North American and European regulatory tolerance levels for curing agents and sodium reduction timelines.
Market Dynamics
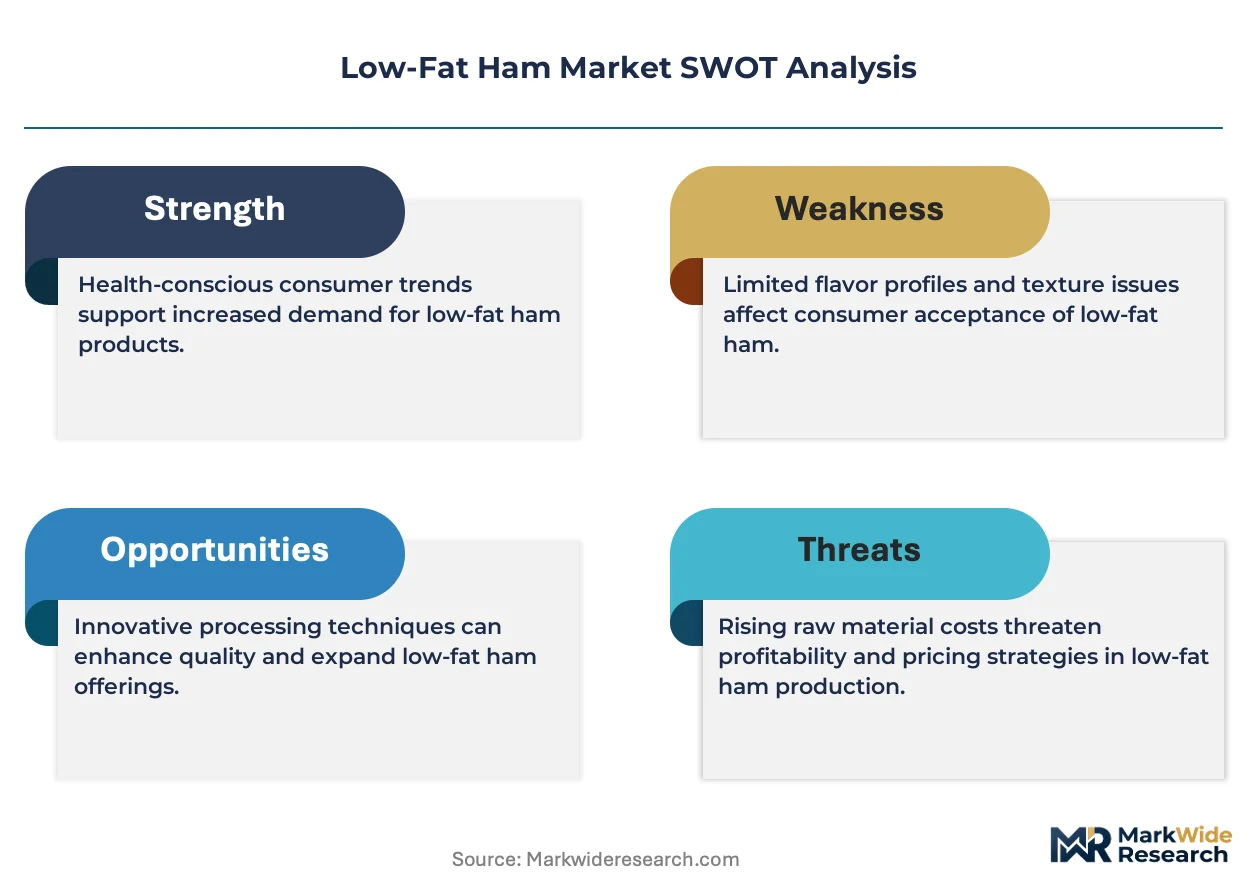
Retail consolidation is compressing supplier margins while reformulation investments for reduced-sodium and clean-label variants absorb disproportionate R&D budgets. The EU's Farm to Fork Strategy nitrite limits and USDA labeling thresholds create divergent compliance roadmaps that fragment product portfolios.
Growth Catalysts
- Germany's discount retail expansion:Aldi and Lidl shelf-space allocations for health-positioned processed meats are pulling volume through centralized procurement. Private-label programs specify lean-content thresholds that favor dedicated low-fat production lines.
- EU Farm to Fork additive scrutiny:EFSA safety evaluations are accelerating clean-label reformulation investments. Manufacturers converting to natural curing alternatives capture premium placement in reformulated-product sets.
- Sodium-reduction technology maturation:Potassium chloride blending and flavor-masking systems are achieving sensory parity at 25-30% salt reduction. Food service distributors specify these variants for healthcare and institutional accounts.
Market Restraints
- Lean pork supply concentration:Danish and Dutch cooperative slaughtering capacity controls premium raw material flows. Independent processors face allocation constraints during seasonal demand spikes.
- Reformulation cost absorption:Natural nitrite alternatives from celery powder and fermented plant extracts carry 15-40% ingredient cost premiums. Margin compression limits pass-through feasibility in price-sensitive retail tiers.
- Clean-label shelf-life tradeoffs:Reduced sodium and eliminated synthetic preservatives shorten distribution windows. Food service operators absorb higher waste rates or demand indemnification clauses.
Strategic Opportunities
- Healthcare channel penetration:Hospital and elder-care food service specifications are hardening around sodium and saturated fat limits. Low-fat ham variants meeting these protocols command contract premiums.
- Direct-to-retailer data partnerships:Scanner-data sharing agreements with consolidated buying groups enable demand-forecasting integration. Production scheduling aligns with promotional calendars, reducing working capital requirements.
- Cell-cultured hybrid development:Blended products combining conventional pork with cultivated muscle tissue address fat-content precision. Early formulations target 90% lipid reduction with structural integrity maintained.
Industry Challenges
- Cross-border formulation complexity:Divergent USDA and EU nitrite maximums force parallel SKU maintenance. Inventory segmentation raises logistics costs and obsolescence risk.
- Sensory panel calibration:Reduced-fat and reduced-sodium variants require expanded consumer testing protocols. Extended development cycles delay commercialization relative to conventional line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Ham Market |
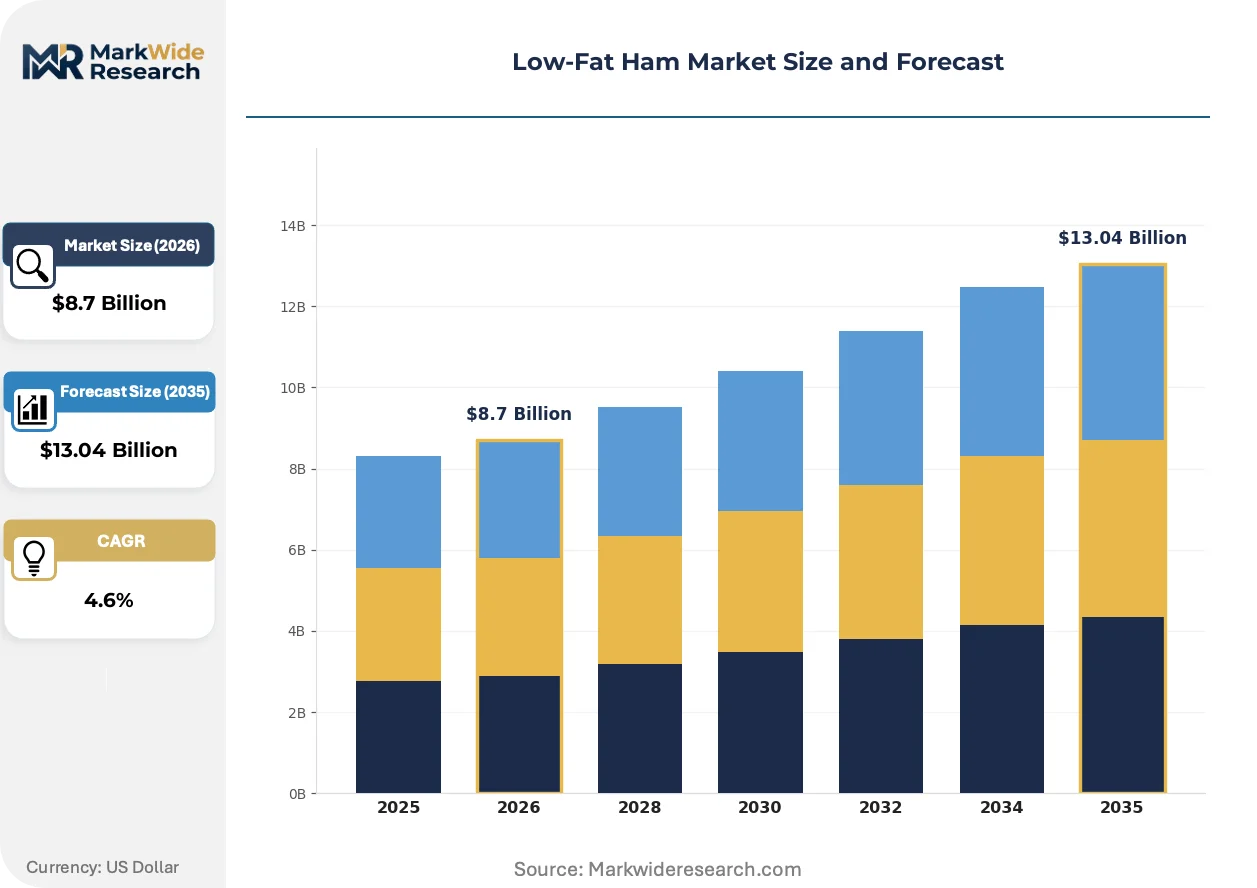
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooked, Cured, Smoked, Reduced Sodium Application: Sandwiches, Salads, Charcuterie, Dishes Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service Customer Type: Health-Conscious Consumers, Catering Services, Restaurants, Retail Chains |
| Companies Covered | JBS S.A., Danish Crown AmbA, Hormel Foods Corp, Tyson Foods Inc, Smithfield Foods, Inc., Plumrose USA, Inc., OSI Group LLC, Vion N.V., Gordon Food Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Ham Market Evolving Landscape
Processing technology is fragmenting into application-specific modules while regulatory divergence forces regional customization. Demand-side consolidation is rewiring procurement specifications and volume commitment structures.
High-pressure processing systems are modularizing across cooked ham production lines, enabling pathogen reduction without thermal degradation of texture. Mid-scale processors in Spain and Italy are adopting 600 MPa units to extend refrigerated shelf life without phosphate dependence. Equipment financing structures are compressing adoption timelines from five-year replacement cycles to 18-month lease-to-own arrangements.
EFSA's 2023 re-evaluation of nitrosamine formation risks is tightening maximum residual limits for ingoing nitrite in cured meats. German and French regulators are advancing domestic implementation ahead of harmonized EU standards. Manufacturers are accelerating fermentation-derived preservative trials to maintain cured-color stability under reduced nitrite ceilings.
Consolidated retail buying groups are unbundling specification-setting from logistics execution, creating tiered supplier relationships. Category managers at centralized European procurement hubs now dictate fat-content, sodium, and additive parameters that regional distributors must fulfill. This bifurcation concentrates technical compliance burden on primary processors while logistics specialists absorb margin-thin fulfillment roles.
Low-Fat Ham Market Segmentation
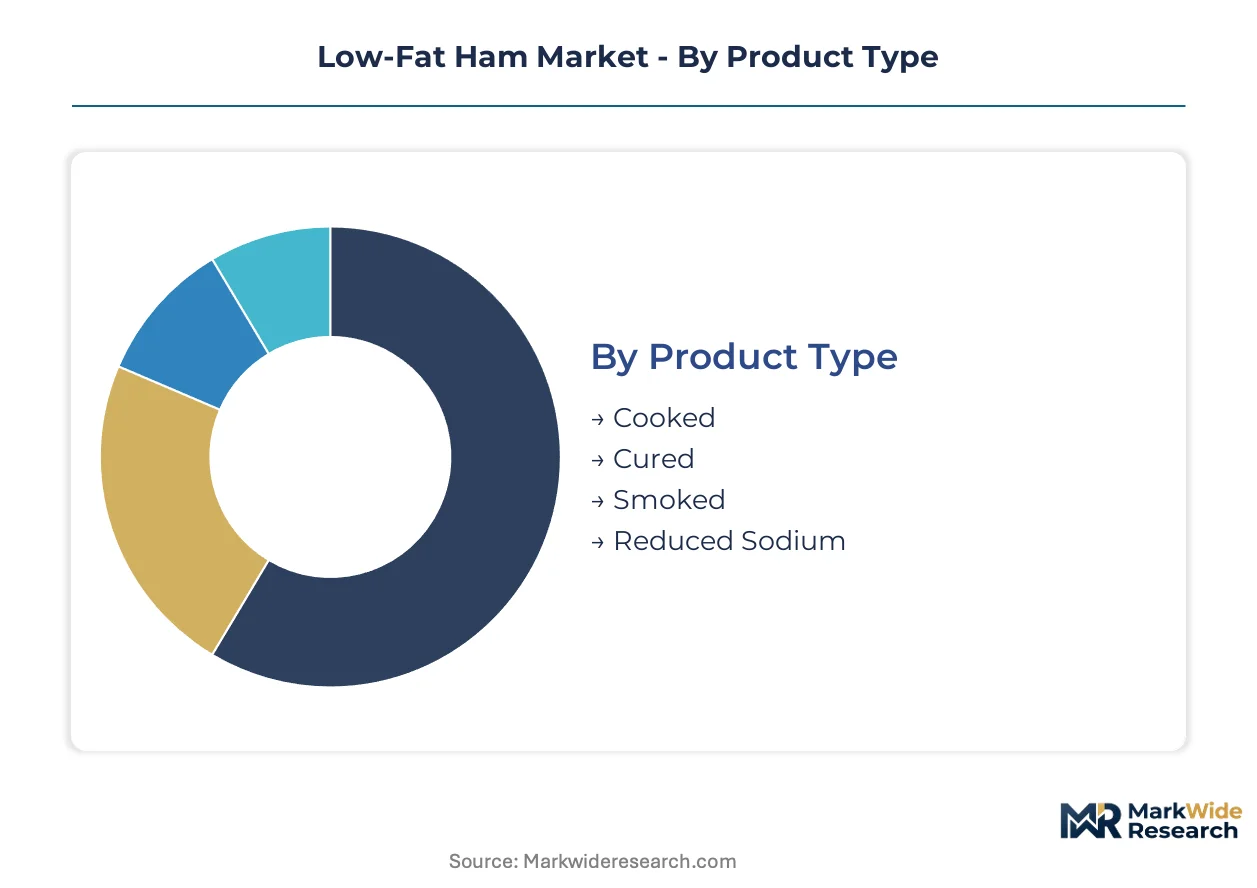
Segmentation in the low-fat ham market maps distinct certification pathways and procurement specifications across product formats and channel structures. Each dimension carries divergent compliance burdens that reshape supplier priorities and margin allocation.
Product Type:
Cooked ham requires USDA Food Safety and Inspection Service process approval, while cured variants face EFSA nitrite maximums and reduced-sodium lines trigger FDA nutrition-label verification.
- Cooked:Thermal processing achieves pathogen reduction while preserving lean muscle texture. Hospital and elder-care food service contracts specify cooked variants for extended holding capacity and HACCP compliance ease. This segment sits at the top of the volume ranking, with Reduced Sodium climbing the fastest.
- Cured:Nitrite-dependent color fixation and shelf stability define formulation requirements. German discount retailers specify residual nitrite thresholds below 50 ppm for private-label placement, compressing formulation latitude.
- Smoked:Natural wood smoke or liquid smoke application adds flavor differentiation. Artisan positioning in French and Italian specialty retail commands placement premiums.
- Reduced Sodium:Potassium chloride blends and umami enhancers replace sodium chloride. Healthcare channel penetration accelerates as sodium limits harden in institutional procurement.
Volume concentrates in cooked formats, though reformulation investments flow disproportionately toward reduced-sodium capabilities.
Application:
End-use specifications fragment by preparation method and service temperature, with food service demanding exact slice geometry and retail favoring resealable convenience.
- Sandwiches:Thin-sliced, uniform stackability dominates quick-service and deli specifications. Aldi and Lidl private-label programs dictate lean-content minimums of 95% for sandwich-tier placement.
- Salads:Diced or julienne formats require moisture retention without purge accumulation. Pre-portioned salad kits in German retail specify low-fat ham with water activity below 0.95.
- Charcuterie:Visual presentation and fat-marbling aesthetics drive premium positioning. Italian and Spanish specialty distributors source cured variants with protected designation origin alignment.
- Dishes:Heat-stable texture for pizza, pasta, and casserole integration. Food manufacturers specify cook yield retention above 85% for processed food inclusion.
Sandwich applications absorb the greatest volume throughput, while charcuterie placement captures expanding margin pools.
Distribution Channel:
Channel selection determines specification complexity, with supermarkets consolidating technical requirements and food service fragmenting into account-specific protocols.
- Supermarkets:Centralized category management dictates fat-content, sodium, and additive parameters. Scanner-data integration enables demand-forecasting partnerships with primary processors.
- Online Retail:Cold-chain reliability and packaging integrity replace shelf-visibility competition. Delivery-window compression requires modified atmosphere packaging with 21-day shelf-life minimums.
- Specialty Stores:Provenance documentation and artisan credentialing support price premiums. French charcuterie specialists require cooperative-owned slaughtering verification.
- Food Service:Specification exactness and shorter delivery windows elevate operational burden. Healthcare and institutional accounts harden around sodium and saturated fat limits with contract premium attachment.
Supermarket procurement commands the largest volume share, with online retail expanding most quickly.
Customer Type:
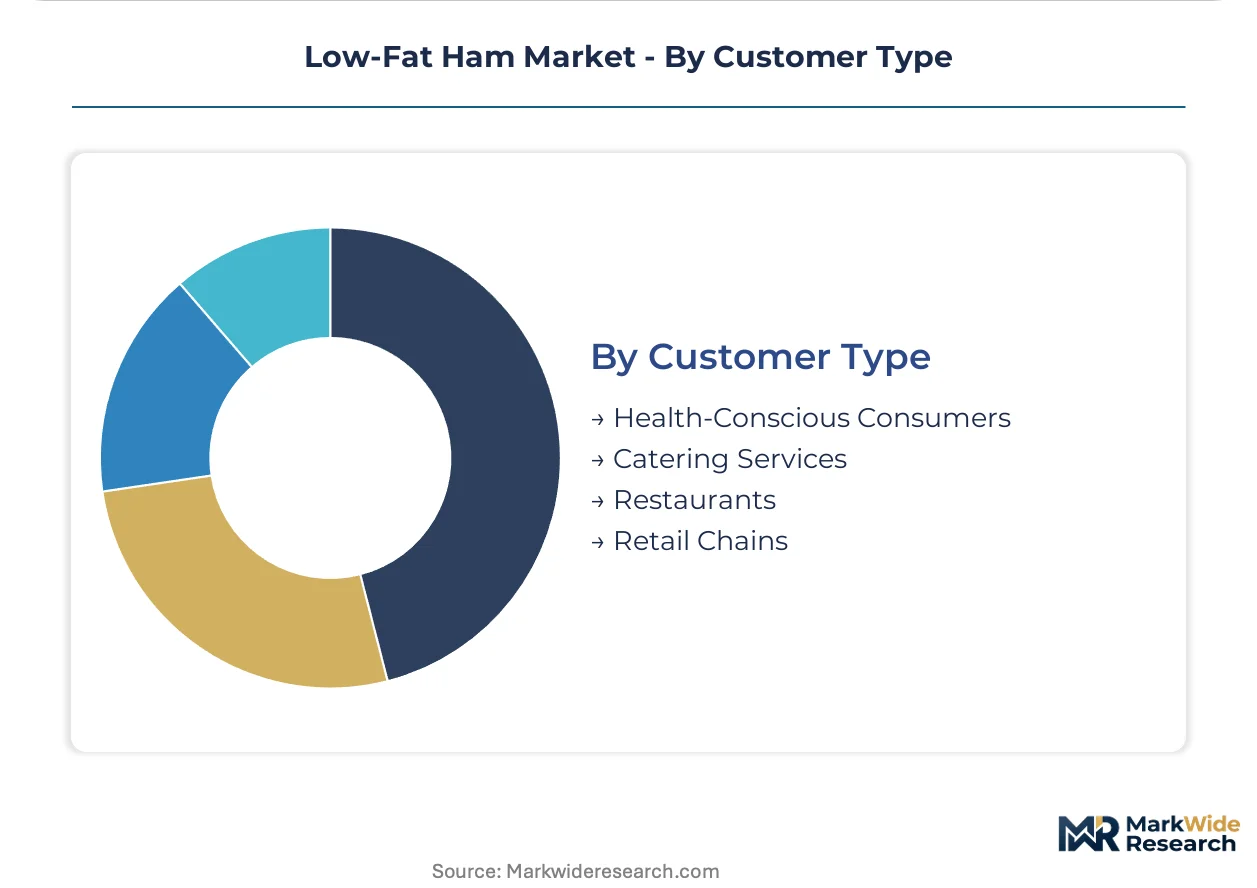
Buyer sophistication varies from label-claim literacy among health-conscious consumers to technical specification authority at consolidated retail chains.
- Health-Conscious Consumers:Nutrition panel scrutiny drives purchase decisions toward reduced-fat and reduced-sodium claims. Clean-label preference accelerates natural curing alternative acceptance despite price premiums.
- Catering Services:Volume scale and menu flexibility requirements favor cooked ham versatility. Contract specifications emphasize portion-cost consistency over provenance differentiation.
- Restaurants:Menu integration and preparation labor reduction influence format selection. Quick-service chains specify pre-sliced, individually quick-frozen portions for inventory rotation efficiency.
- Retail Chains:Consolidated buying groups unbundle specification-setting from logistics execution. Category managers at centralized European hubs now dictate additive parameters that regional distributors must fulfill.
Retail chains dominate procurement volume, with health-conscious consumers gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's discount retail chains pull greater low-fat ham volume than France's specialty charcuterie channels, revealing divergent demand patterns across adjacent European markets.
Germany
Aldi and Lidl centralized procurement specifications favor lean-content thresholds above 95% for private-label placement. The EU Farm to Fork Strategy drives nitrite limit tightening ahead of bloc-wide harmonization. North Rhine-Westphalia's cooperative slaughtering clusters supply dedicated low-fat production lines with cost-disciplined raw material flows.
United States
Hospital and elder-care food service contracts harden around sodium and saturated fat specifications with premium attachment. USDA Food Safety and Inspection Service maximum ingoing nitrite limits govern curing formulation compliance. Midwest pork processing corridors in Iowa and Illinois concentrate cooked ham capacity for institutional distribution.
France
Charcuterie specialists command placement premiums through protected designation origin alignment and artisan credentialing. EFSA nitrosamine formation risk re-evaluations accelerate domestic implementation ahead of EU standards. The Auvergne-Rhône-Alpes region anchors specialty cured ham production with cooperative-owned slaughtering verification requirements.
United Kingdom
Consolidated supermarket buying groups unbundle specification-setting from logistics execution across centralized procurement hubs. FDA-equivalent nutrition labeling thresholds for reduced-fat claims shape import acceptance criteria. The Midlands processing belt supplies reformulated reduced-sodium variants for retail chain private-label programs.
Denmark
Cooperative-owned slaughtering capacity controls premium lean pork raw material flows to independent processors. EFSA additive safety profiles under renewed scientific scrutiny influence domestic reformulation mandates. Danish Crown's integrated network anchors cost discipline through captive supply of specification-grade muscle tissue.
Low-Fat Ham Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply relationships. The market structure concentrates procurement leverage among three to four integrated processors while mid-scale regional operators serve specification-niche accounts. Strategic archetypes include scale-driven volume suppliers, cooperative-anchored cost disciplinarians, and branded health-positioned differentiators. Competitive moves center on backward integration into slaughtering capacity and scanner-data partnerships with consolidated retail buying groups.
Among Brazil-based diversified protein conglomerates, JBS S.A. occupies a position exemplifying scale-driven volume supply archetypes. Danish cooperative structures represent cost-disciplined raw material control, with Danish Crown AmbA anchoring this model. Hormel Foods Corp exemplifies branded health-positioned differentiation through premium placement in consolidated channels. These three entities represent the dominant competitive anchors across divergent strategic vectors.
| Leading Market Players |
|---|
| JBS S.A. |
| Danish Crown AmbA |
| Hormel Foods Corp |
| Tyson Foods Inc |
| Smithfield Foods, Inc. |
| Plumrose USA, Inc. |
| OSI Group LLC |
| Vion N.V. |
| Gordon Food Service |
| Others |
Value Network & Pricing Analysis
Consolidated supermarket buying groups in Germany and the United Kingdom command contract-based long-term offtake structures that compress supplier margins while securing volume commitments. Their centralized procurement leverage forces tiered pricing stratification across premium health-positioned lines, standard private-label placements, and economy-tier commodity ham.
Pricing Analysis
Capacity additions in Spain and Italy are reshaping price floors for cooked ham variants as mid-scale processors deploy high-pressure processing systems. Three-tier pricing structure across premium, standard, and economy levels differentiates by lean-content certification and sodium reduction thresholds. Pricing pressure stems from natural nitrite alternative premiums of 15-40% that limit pass-through feasibility. Discount retail tiers exhibit highest price sensitivity while healthcare channel buyers accept contract premiums for specification compliance.
Supply Chain Analysis
Refrigerated freight cost volatility between Danish cooperative slaughtering clusters and Central European processing hubs elevates landed cost uncertainty for lean pork raw materials. Supply concentrates in Denmark, Germany, and the Netherlands for premium muscle tissue flows. Production draws from potassium chloride blending systems, fermented plant extract preservatives, and modified atmosphere packaging films. Single-source vulnerability sits with Danish Crown's captive supply of specification-grade pork. Distribution runs through centralized retail procurement hubs that unbundle technical compliance from logistics execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-fat ham market functions as a geographic-arbitrage play where EU Farm to Fork nitrite limits create reformulation cost premiums that North American exporters can undercut through USDA-compliant curing formulations.
For Market Incumbents: Anchor backward integration into cooperative-owned slaughtering capacity to secure lean pork allocation during seasonal demand spikes. Defend margin position by accelerating sodium-reduction technology maturation ahead of EFSA implementation timelines. Prioritize scanner-data partnerships with Aldi and Lidl procurement hubs to lock in volume commitments.
For New Entrants and Emerging Players: Enter via healthcare channel penetration where hospital and elder-care food service specifications harden around sodium limits with contract premium attachment. Target reduced-sodium cooked ham production for German discount retail private-label programs. Pursue direct-to-retailer data partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Diversified protein conglomerates with integrated pork processing networks are the most active acquirer in this space. Long-term viability centers on reformulation capability assets over commodity processing capacity. Monitor EFSA nitrosamine risk re-evaluation implementation as the inflection signal for clean-label reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slaughtering Capacity | Danish cooperative structures demonstrate how captive lean pork supply secures cost discipline against raw material allocation constraints. |
| Sodium-Reduction Technology Investment | Potassium chloride blending and flavor-masking systems achieve sensory parity at 25-30% salt reduction for healthcare channel penetration. |
| Scanner-Data Partnership with Retail Chains | Centralized European procurement hubs enable demand-forecasting integration that reduces working capital requirements for primary processors. |
| Natural Curing Alternative Development | Fermentation-derived preservatives from celery powder maintain cured-color stability under reduced EU nitrite ceilings. |
| High-Pressure Processing System Deployment | 600 MPa units in Spain and Italy extend refrigerated shelf life without phosphate dependence for clean-label positioning. |
Research Methodology
Bottom-up food service and retail channel modeling reconciled against top-down pork processing capacity tracking forms the analytical core. Primary interviews with category managers at consolidated buying groups, procurement directors at hospital food service operators, plant managers at cooperative slaughtering facilities, and technical R&D directors at curing ingredient suppliers combined with secondary validation from USDA FSIS regulatory filings, EFSA scientific opinions, EU Farm to Fork Strategy documentation, and Nielsen retail audit data. Triangulation between demand-side procurement specifications and supply-side reformulation capabilities anchors volume and value estimates.
Input-output matrices map lean pork raw material flows through cooked, cured, and reduced-sodium production lines across the projection horizon. Segmentation dimensions include product type, application format, distribution channel structure, and customer sophistication tier. CAGRs derive from demand-forecasting integration with promotional calendars and regulatory compliance timelines. Forecast inputs incorporate EFSA nitrite maximum implementation schedules and potassium chloride blending technology adoption curves.
The model holds under stable EU-US regulatory divergence; deviation in harmonized nitrite standards or accelerated sodium-reduction mandates would shift capacity allocation and margin pools. Forecasts reflect documented assumptions about retail consolidation trajectories and clean-label shelf-life tradeoffs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Animal Protein Market
Meat Products
Pepperoni Foods Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Europe Meat Products Market
Meat Products
Meat Emulsions Market
Meat Products
Pork Meat Market
Meat Products
Low Fat Beef Market
Meat Products
Beef Tallow Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
Pork Belly Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
India Animal Protein Market
Meat Products
3D Printed Meat Market
Meat Products
North America Edible Meat Market