
 Instant Pot Market | 2026-2036
Instant Pot Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Pot Market Foresight
The EU Ecodesign Directive is recalibrating appliance efficiency benchmarks across European markets, compelling manufacturers to redesign heating elements and control systems. Instant Brands leverages its integrated ecosystem of recipe apps and proprietary lid interfaces to sustain repeat purchases. Hamilton Beach anchors North American retail distribution through big-box partnerships, while TTK Prestige dominates South Asian voltage-specific configurations with localized safety certifications.
An Instant Pot is a sealed, microprocessor-controlled electric pressure vessel combining thermal regulation, timed pressure cycling, and multi-function programmability in a single countertop appliance, typically operating between 70-80 kPa working pressure with stainless steel or ceramic-coated aluminum cooking inserts. Its primary commercial purpose is consolidating braising, steaming, and slow-cooking workflows into one device for space-constrained kitchens. Electric pressure cookers occupy the largest volume share as first-time buyers prioritize core functionality over feature proliferation, while multi-cookers capture expanding margin pools through bundled air-frying and sous-vide modules. Meal prep companies represent the fastest-growing end-user segment as centralized kitchens adopt batch-programmable units to reduce labor hours per service cycle.
The US Department of Energy appliance standards, California's Title 20 energy regulations, and China's GB 4706 household appliance safety standards collectively shape wattage ceilings, standby power limits, and pressure relief testing protocols that determine market access. Manufacturers must navigate divergent certification timelines across these jurisdictions, with European CE marking under the Low Voltage Directive adding electromagnetic compatibility requirements absent from North American listings. Stakeholders should monitor how right-to-repair legislation in multiple US states and EU member countries mandates spare parts availability, potentially altering product architecture decisions around modular versus sealed component designs.
Market Dynamics
Programmable induction heating systems are displacing conventional resistive elements as manufacturers respond to tightening wattage ceilings under US Department of Energy appliance standards and China's GB 4706 safety protocols. This technology transition compresses production timelines while demanding recertification across multiple jurisdictions.
Growth Catalysts
- Meal Prep Automation:Centralized commercial kitchens in urban China and coastal United States metropolitan areas deploy batch-programmable units to consolidate braising, steaming, and slow-cooking workflows into single service cycles.
- EU Ecodesign Directive:Recalibrated efficiency benchmarks across European markets compel heating element redesigns that improve energy conversion rates and unlock premium positioning in efficiency-conscious segments.
- Apartment-Dwelling Concentration:Space-constrained urban households prioritize countertop versatility, consolidating multiple appliances into single-footprint devices with multi-function programmability.
Market Restraints
- Stainless Steel Input Volatility:Cooking insert material costs fluctuate with commodity markets, pressuring margin structures on mid-tier product lines where price elasticity constrains pass-through.
- Certification Fragmentation:Divergent electromagnetic compatibility requirements under European CE marking versus North American listings extend product development cycles and limit component standardization.
- Conventional Appliance Substitution:Standalone pressure cookers, rice cookers, and slow cookers retain cost advantages in price-sensitive segments, particularly voltage-specific South Asian configurations.
Strategic Opportunities
- Right-to-Repair Mandates:Legislation in multiple US states and EU member countries mandates spare parts availability, creating openings for modular component architectures and aftermarket service revenue streams.
- Air-Frying Module Convergence:Integration of high-velocity convection elements with existing pressure vessel platforms captures margin expansion in bundled multi-cooker configurations.
- Recipe App Ecosystems:Proprietary lid interfaces and digital content subscriptions generate recurring revenue while locking in repeat hardware purchases through interoperability constraints.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware development for pressure cycling algorithms and thermal regulation requires specialized skill sets that concentrate in coastal technology hubs, constraining manufacturer hiring pipelines.
- Pressure Relief Testing Protocols:China's GB 4706 household appliance safety standards impose rigorous validation timelines that delay market entry for redesigned control systems.
- Legacy Kitchen Integration:Commercial foodservice operators face workflow reconfiguration costs when replacing established equipment lines with programmable countertop units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Pot Market |
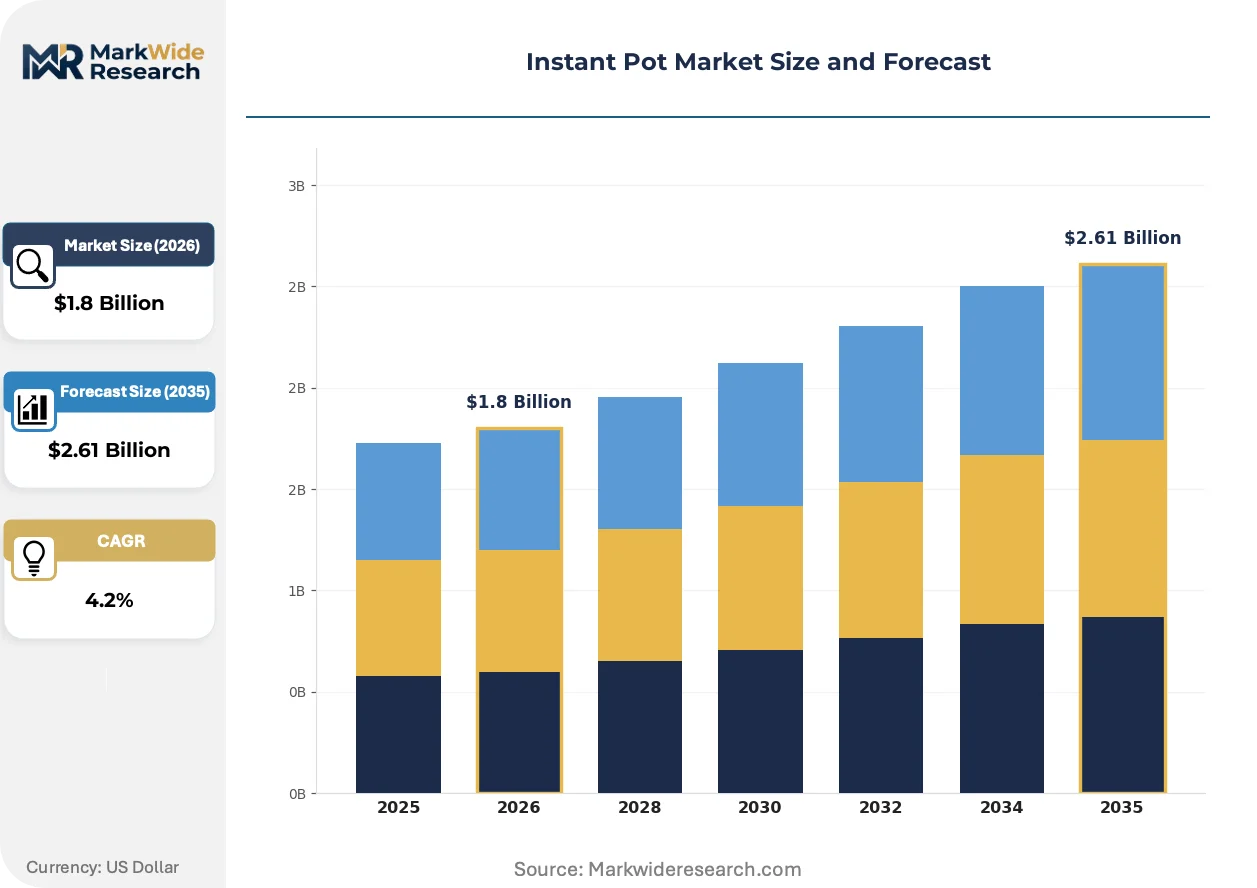
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Pressure Cooker, Air Fryer, Slow Cooker, Multi-Cooker End User: Households, Restaurants, Catering Services, Meal Prep Companies Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Direct Sales Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | National Presto Industries, Hamilton Beach, Instant Brands, TTK Prestige, Panasonic, Breville Group, Zojirushi America Corporation, Hawkins Cookers, SharkNinja, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Pot Market Shifts & Advancements
Digital control architectures and connectivity modules are absorbing development resources as manufacturers differentiate beyond core pressure-cooking functionality. Three converging forces reshape competitive positioning.
Induction coil heating is absorbing capital allocation from traditional resistive elements, converting electrical energy directly into vessel heat with reduced thermal loss. Meal prep companies and commercial kitchen operators adopt these systems to meet batch consistency requirements under compressed service windows. The technology is absorbing margin pressure from energy efficiency mandates while enabling premium pricing tiers.
China's GB 4706 household appliance safety standards and the US Department of Energy appliance standards are tightening wattage ceilings and standby power limits simultaneously. Manufacturers must redesign control boards and heating elements to satisfy divergent testing protocols, extending certification timelines. Electric pressure cooker segments face the steepest compliance costs where core functionality depends on sustained high-wattage operation.
Urban apartment dwellers in China and the United States are consolidating kitchen equipment purchases around multi-function programmability rather than single-purpose appliances. Big-box retail partnerships and direct-to-consumer channels displace traditional appliance showrooms for initial purchase decisions. Coastal metropolitan areas exhibit the strongest preference for countertop versatility where square footage constraints dominate housing economics.
Instant Pot Market Segmentation
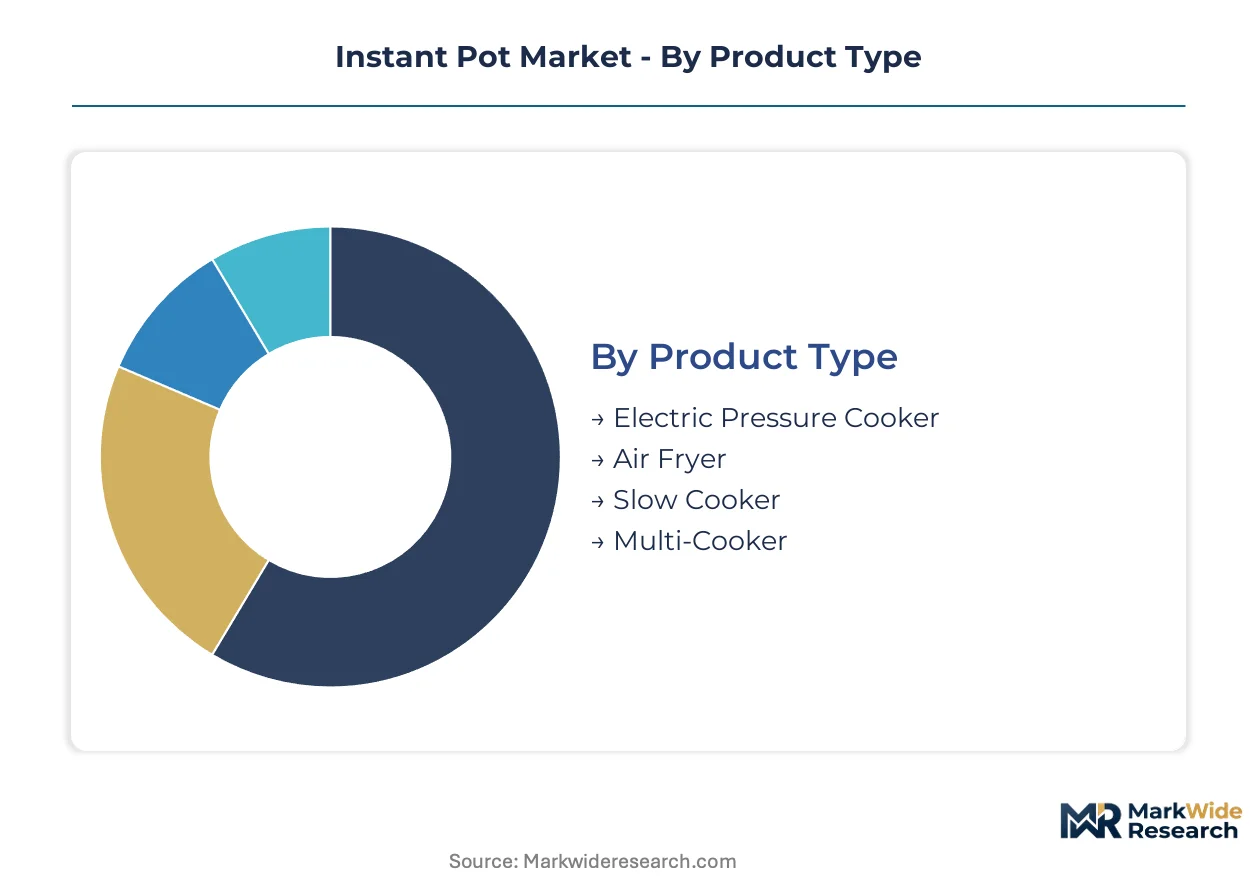
Segmentation in the Instant Pot market reveals how appliance functionality aligns with distinct usage patterns across residential and commercial environments. Manufacturers configure heating systems, pressure algorithms, and vessel capacities differently depending on whether units serve single-family kitchens or high-throughput meal prep operations.
Product Type:
Standalone pressure-cooking units dominate countertop installations where consumers prioritize single-function reliability over bundled capabilities. Embedded multi-function systems are displacing discrete appliances in space-constrained urban households seeking consolidated workflows.
- Electric Pressure Cooker:Sealed stainless steel vessels with microprocessor-controlled thermal cycling between 70-80 kPa working pressure. Demand concentrates in first-time appliance buyers across coastal United States metropolitan areas where core functionality outweighs feature proliferation.
- Multi-Cooker:Programmable platforms integrating pressure cycling with sous-vide, sauté, and rice-cooking modules through unified control architectures. Meal prep companies in urban China deploy these units to compress braising and steaming workflows into single service cycles.
- Air Fryer:High-velocity convection elements packaged as standalone countertop units or lid-integrated modules for existing pressure vessels.
- Slow Cooker:Low-wattage resistive heating elements with extended-duration thermal maintenance, retaining cost advantages in price-sensitive segments.
Volume placements concentrate in Electric Pressure Cooker configurations; the faster expansion belongs to Multi-Cooker platforms.
End User:
Residential purchasers drive replacement cycles and feature upgrades while commercial operators prioritize batch consistency and labor-hour reduction. Certification requirements diverge sharply between household GB 4706 compliance and commercial foodservice safety protocols.
- Meal Prep Companies:Centralized commercial kitchens operating batch-programmable units across multiple vessel configurations to standardize output across distributed service locations. These operators concentrate in coastal United States metropolitan areas and urban China where apartment density supports centralized production models.
- Households:Individual consumers selecting countertop appliances based on square-footage constraints and multi-function versatility rather than single-purpose specialization.
- Restaurants:Full-service and limited-service foodservice operators integrating programmable pressure vessels into back-of-house workflows alongside conventional equipment lines.
- Catering Services:Mobile and event-based foodservice providers requiring portable, high-capacity units with rapid heat-up characteristics.
Households account for the largest installed base; Meal Prep Companies are climbing the fastest as commercial kitchen automation accelerates.
Distribution Channel:
Channel selection reflects purchase urgency, price transparency requirements, and the need for physical product inspection before commitment. Direct-to-consumer platforms are absorbing margin pools previously captured by retail intermediaries.
- Online Retailers:E-commerce platforms enabling price comparison, subscription bundling, and direct-to-consumer warranty registration. Urban apartment dwellers in China and the United States increasingly complete initial purchase decisions through these channels.
- Supermarkets:Mass-market retail placements emphasizing promotional pricing and impulse purchase opportunities for replacement cycles.
- Specialty Stores:Kitchenware retailers offering in-person demonstration and consultation for premium-tier configurations.
- Direct Sales:Manufacturer-controlled channels capturing full margin and enabling proprietary ecosystem lock-in through recipe app integration.
Transaction volume flows predominantly through Online Retailers; Direct Sales channels are gaining share fastest through ecosystem bundling strategies.
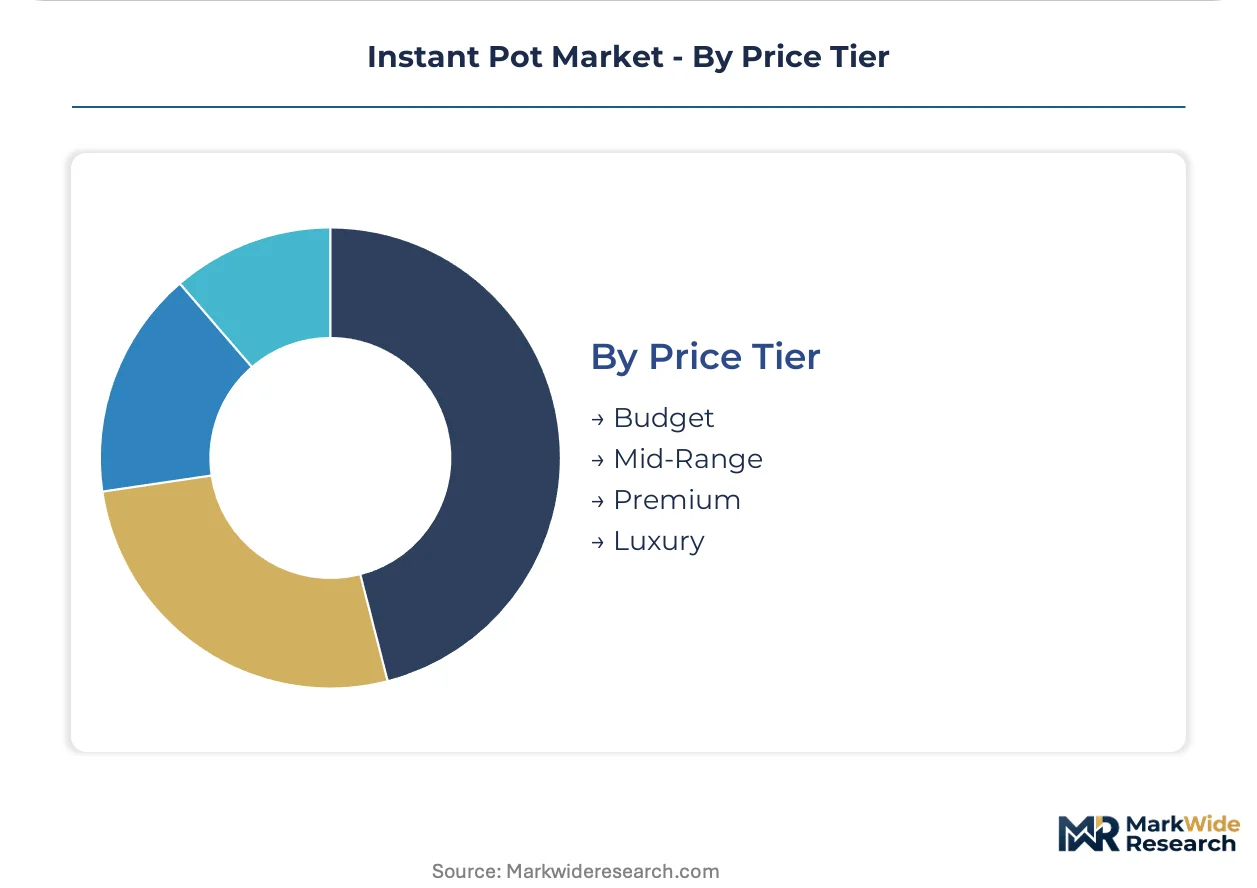
Price Tier:
Pricing stratification mirrors component quality, certification grade, and connectivity feature depth rather than core pressure-cooking capability. Induction heating systems and Wi-Fi-enabled control boards concentrate in upper tiers.
- Premium:Induction coil heating, stainless steel inserts with tri-ply base construction, and app-connected recipe programming. Coastal United States metropolitan buyers prioritize these configurations for durability and feature depth.
- Mid-Range:Resistive heating elements with ceramic-coated aluminum inserts and limited programmability, capturing price-sensitive households seeking basic multi-function capability.
- Budget:Simplified control interfaces, single-pressure settings, and reduced warranty terms targeting first-time appliance purchasers.
- Luxury:Designer exterior finishes, voice-control integration, and exclusive recipe content partnerships commanding substantial markups over functional equivalents.
Unit shipments concentrate in Mid-Range configurations; Premium tiers are expanding most quickly as energy efficiency mandates push buyers toward induction systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal United States metropolitan corridors from Seattle to Boston concentrate the highest household penetration rates for programmable countertop appliances, while urban China's tier-one cities anchor commercial batch-cooking deployments for meal prep automation.
United States
Apartment-dwelling households in New York, Los Angeles, and Chicago drive demand for multi-function countertop versatility that consolidates single-purpose appliances. The US Department of Energy appliance standards tighten wattage ceilings and standby power limits, forcing heating element redesigns. California's Title 20 energy regulations exceed federal baselines, pushing Bay Area and Los Angeles manufacturers toward induction coil systems.
China
Urban meal prep companies in Shanghai, Beijing, and Shenzhen deploy batch-programmable units to compress braising and steaming workflows into single service cycles. GB 4706 household appliance safety standards impose rigorous pressure relief testing protocols that delay certification for redesigned control systems. The Yangtze River Delta manufacturing cluster produces voltage-specific configurations for domestic and export markets.
Germany
Energy-conscious households in Berlin, Munich, and Hamburg prioritize induction heating systems that satisfy EU Ecodesign Directive efficiency benchmarks. CE marking under the Low Voltage Directive adds electromagnetic compatibility requirements absent from North American listings. The Bavarian industrial corridor hosts component suppliers for programmable control boards.
Japan
Space-constrained Tokyo and Osaka households favor compact multi-cooker platforms with precision thermal regulation. METI energy efficiency guidelines shape domestic wattage ceilings and standby power mandates. The Kanto region's electronics manufacturing base supplies microprocessor-controlled thermal cycling systems to regional appliance assemblers.
India
Price-sensitive households in Mumbai, Delhi-NCR, and Bangalore retain demand for voltage-specific pressure cooker configurations with localized safety certifications. BIS standards govern pressure vessel integrity and electrical safety for 230V operation. TTK Prestige anchors domestic manufacturing in Tamil Nadu with region-specific product architectures.
Instant Pot Market Competitive Landscape
Premium-margin players sit above commodity-margin players across feature depth and certification grade, with tiered pricing separating induction-equipped platforms from resistive-element alternatives. The vendor base stratifies between ecosystem-integrated specialists, scale-driven mass-market suppliers, and regional voltage-specific fabricators. Three archetypes dominate: proprietary app-platform owners capturing recurring revenue, big-box retail anchors optimizing distribution breadth, and localized safety-certified producers serving voltage-fragmented South Asian markets. Capacity expansion and recipe app ecosystem lock-in represent the dominant competitive moves.
Within the ecosystem-integrated tier, Instant Brands exemplifies the proprietary platform archetype through its recipe app and lid interface strategy. Hamilton Beach occupies a position as the North American retail distribution anchor through big-box partnerships. TTK Prestige represents the voltage-specific regional specialist with India-focused safety certifications. These three companies illustrate how competitive positioning fragments across digital ecosystem control, retail channel dominance, and localized regulatory compliance.
| Leading Market Players |
|---|
| National Presto Industries |
| Hamilton Beach |
| Instant Brands |
| TTK Prestige |
| Panasonic |
| Breville Group |
| Zojirushi America Corporation |
| Hawkins Cookers |
| SharkNinja |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap appliance manufacturers in China and India anchor component sourcing networks, translating procurement scale into pricing discipline across voltage-specific and induction-equipped product tiers. Their concentrated ownership structures enable long-term supplier commitments that resist margin erosion from stainless steel commodity volatility.
Pricing Analysis
Value-based pricing anchored to energy efficiency outcomes dominates premium tiers, with induction-equipped units commanding substantial markups over resistive-element alternatives based on wattage reduction guarantees. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked induction systems from basic GB 4706-compliant configurations. Pricing pressure stems from stainless steel input volatility pressuring mid-tier margins where pass-through elasticity constrains increases. Budget-tier households exhibit highest price sensitivity; meal prep companies prioritize throughput economics over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta microprocessor suppliers, where firmware development for pressure cycling algorithms concentrates in coastal technology hubs. Manufacturing draws from China, India, and Vietnam for vessel fabrication, control board assembly, and packaging materials. Raw material dependencies span stainless steel cooking inserts, ceramic coatings, and induction coil copper windings. Tariff exposure on Chinese-sourced electronics components threatens margin structures for North American-bound production. Distribution runs through direct-to-consumer platforms and big-box retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's GB 4706 pressure relief testing protocols and the US Department of Energy wattage ceilings create barrier-to-entry moats for certified incumbents.
For Market Incumbents: Acquire embedded systems engineering talent pools in Shanghai and Shenzhen to defend against firmware development scarcity. Consolidate backward integration into induction coil manufacturing to offset commodity copper volatility. Certification investment in EU Ecodesign Directive compliance unlocks premium positioning as efficiency mandates tighten. For New Entrants and Emerging Players: Launch via direct-to-consumer channels targeting apartment-dwelling households in tier-two Chinese cities underserved by meal prep automation. White-space concentrates in voltage-specific South Asian configurations below TTK Prestige's price umbrella. Recipe app ecosystem partnerships offer the most penetrable go-to-market angle against Instant Brands' proprietary lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular-component architecture specialists in Tamil Nadu and Guangdong with right-to-repair compliance infrastructure. Long-term viability over the coming decade hinges on spare parts availability mandates spreading across US states and EU member countries. Watch for induction heating patent expirations as the critical inflection signal for margin compression in premium tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Heating Module Integration | Captures EU Ecodesign Directive compliance premiums in German and French markets. |
| Recipe App Ecosystem Development | Locks in repeat hardware purchases through proprietary lid interface interoperability constraints. |
| Right-to-Repair Modular Architecture | Positions for aftermarket service revenue as California and EU spare parts mandates expand. |
| Meal Prep Channel Partnership | Secures batch-programmable unit volume with urban China centralized kitchen operators. |
| Regional Voltage Certification Investment | Unlocks BIS-compliant access to price-sensitive Mumbai and Delhi-NCR household segments. |
Research Methodology
Multi-period observation of wattage ceiling regulations, induction heating adoption curves, and meal prep company procurement patterns anchored the trend analysis, supplemented by interviews with appliance engineering directors, commercial kitchen operators, big-box retail category managers, and GB 4706 certification specialists. Secondary validation drew from US Department of Energy appliance standard filings, EU Ecodesign Directive implementation documents, China customs export data, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up vessel shipment estimates triangulated against top-down market value reconstruction.
Input-output matrices mapped electric pressure cooker, multi-cooker, and air fryer configurations against end-user segments across the analysis window. Segmentation dimensions modeled include product type, end-user archetype, distribution channel, and price tier. CAGRs derived from regression analysis of historical penetration rates and regulatory enforcement timelines. Forecast inputs incorporated stainless steel price indices and electromagnetic compatibility certification backlog data.
Regulatory enforcement delays, commodity price spikes, and right-to-repair legislative scope expansion are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Commercial Microwaves Market