
 Coconut Milk Products Market | 2026-2036
Coconut Milk Products Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Milk Products Market Intelligence
The rise of fair trade and organic certification standards is broadening the competitive landscape for coconut milk producers. Danone S.A. leverages its extensive distribution network to introduce plant-based options across multiple retail channels. McCormick & Company Inc. integrates coconut milk into its global culinary product lines, targeting both retail and foodservice customers. Vita Coco specializes in the beverage segment, building a strong brand identity around natural ingredients.
Coconut milk products are aqueous emulsions extracted from the grated flesh of mature coconuts, with fat content determining the distinction between milk and cream. These products serve as a foundational ingredient in culinary applications and as a dairy-free base for beverages. While regular coconut milk holds the largest volume share, organic coconut milk represents the fastest-growing product type. The beverage application continues to expand rapidly, while the culinary segment provides a stable, high-margin base.
Product safety and labeling are governed by a matrix of national and international standards, including the US FDA's food safety regulations and the EU's EFSA guidelines on novel foods. The CODEX Alimentarius standard for aqueous coconut products provides a global reference for trade and quality. Navigating the evolving landscape of sustainability claims and clean-label requirements will be critical for maintaining brand trust and market access.
Market Dynamics
The convergence of consumer health consciousness and stricter food allergen labeling regulations is the central force reshaping the coconut milk products market. This dual pressure accelerates the substitution of traditional dairy, positioning coconut milk as a primary plant-based alternative in both beverage and culinary applications.
Growth Catalysts
- Allergen Labeling Mandates:Rules from the US FDA and EFSA push food manufacturers to use coconut milk for clean-label products, avoiding dairy allergen declarations.
- Urban Plant-Based Diets:Growing veganism in US and German cities increases demand for coconut milk in foodservice and beverage applications.
- Ethical Sourcing Certifications:Consumer preference for products with Fair Trade or USDA Organic certifications creates a premium segment and expands market access for producers.
Market Restraints
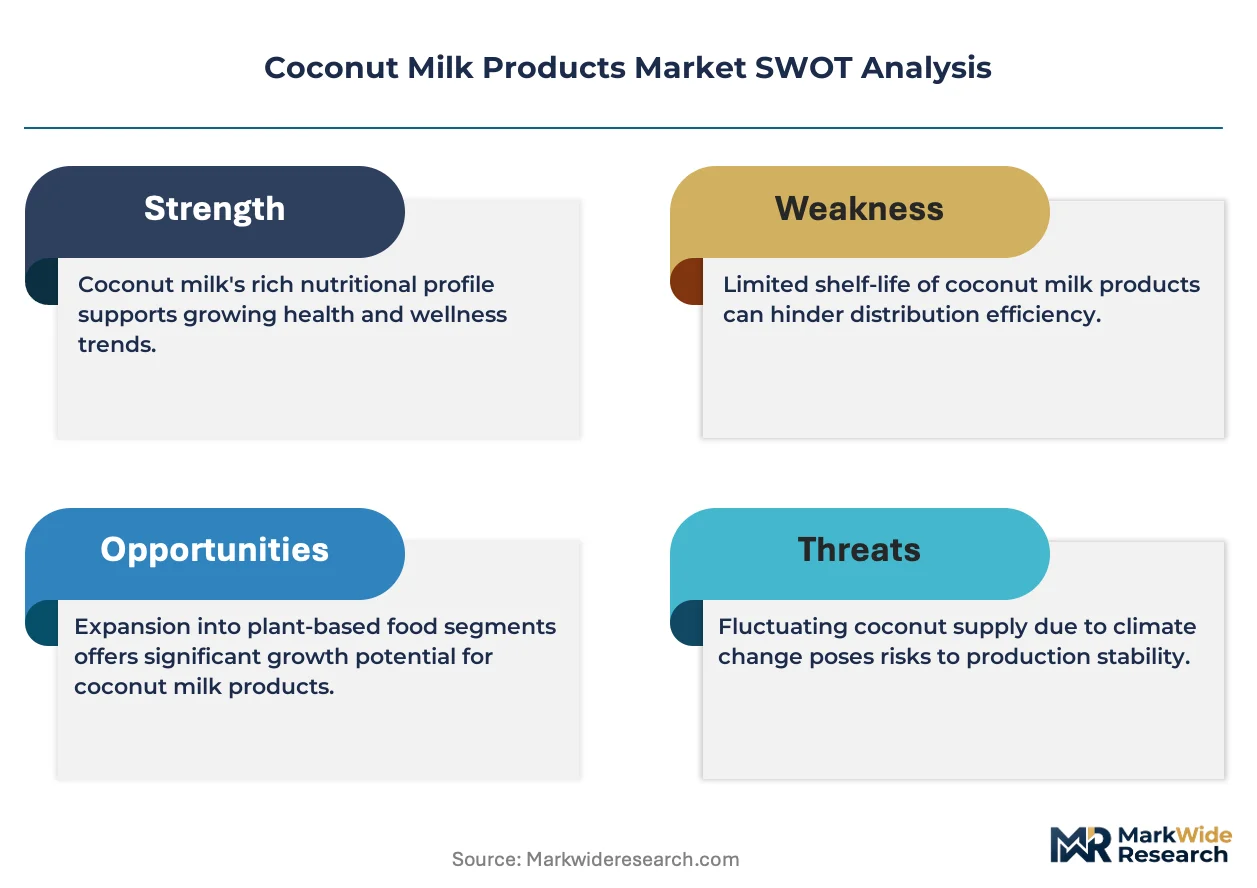
- Raw Material Volatility:Coconut harvests in key producing nations like Indonesia and the Philippines are vulnerable to climate events, creating price instability for processors.
- Intense Plant-Based Competition:Oat, almond, and soy milks are strong substitutes that compete directly for consumer preference and retail shelf space in the beverage sector.
- Emulsion Stability Challenges:Maintaining a consistent texture without additives is a technical hurdle, affecting the shelf life and consumer acceptance of clean-label coconut milk products.
Strategic Opportunities
- Functional Beverage Development:Fortifying coconut milk with vitamins, minerals, and protein creates value-added products targeting consumers seeking functional, plant-based nutrition.
- Eastern European Market Entry:Untapped demand for plant-based options in countries like Poland presents a geographic expansion opportunity beyond saturated Western European markets.
- Foodservice Culinary Formats:Creating shelf-stable coconut cream powders and concentrates for professional chefs provides a high-margin channel targeting the global culinary sector.
Industry Challenges
- Traceability and Sustainability Verification:Implementing full supply chain traceability to meet demands for sustainability, such as those under the EU's CSRD, is a complex operational challenge for processors.
- Navigating Global Quality Standards:Adherence to a patchwork of international standards, including CODEX Alimentarius and national food safety laws, requires significant compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Milk Products Market |
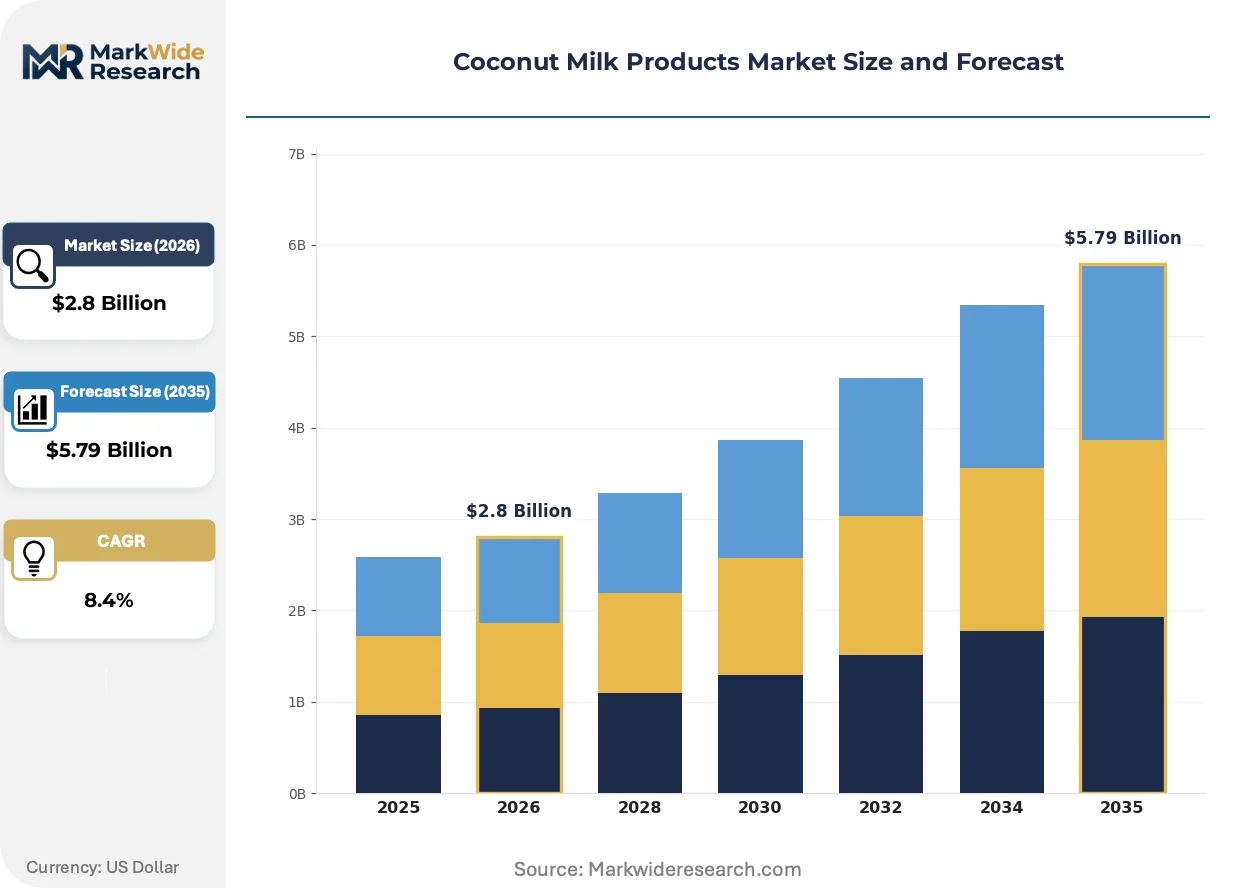
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Coconut Milk, Organic Coconut Milk, Flavored Coconut Milk, Coconut Cream, Coconut Milk Powder Packaging Type: Carton Packs, Glass Bottles, Plastic Bottles, Cans, Sachets Application: Beverages, Culinary, Cosmetics, Pharmaceuticals, Personal Care Customer Type: Retail Consumers, Foodservice Providers, Health Stores, Cosmetic Manufacturers, Pharmaceutical Companies |
| Companies Covered | Goya Foods Inc., McCormick & Company Inc., Vita Coco, Cocotana Coconut Products, Thai Agri Foods Public Company Limited, Thai Coconut Public Company Limited, Danone S.A., Marico Limited, Theppadungporn Coconut Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Milk Products Market Strategic Shifts & Innovations
Product sophistication is redefining the coconut milk landscape. The market is moving beyond simple dairy replacement toward functional ingredients and clean-label formulations that cater to specific consumer health demands and culinary applications.
Advanced extraction and micro-filtration technologies allow for the separation of coconut milk into distinct fat and protein fractions. Food and beverage formulators are adopting these techniques to create customized ingredients for specific applications. This technological capability is expanding into the creation of novel coconut-based yogurts, cheeses, and creamers with improved texture and stability.
The CODEX Alimentarius standard for aqueous coconut products provides a global reference for quality and composition. This standard facilitates international trade by harmonizing definitions for coconut milk and cream, ensuring a level playing field for exporters. Producers in countries like Thailand and Sri Lanka are increasingly aligning their processes with CODEX to secure access to export markets in Europe and North America.
Consumers are increasingly purchasing specialty and organic coconut milk products through online marketplaces and direct-to-consumer (DTC) subscription services. This shift bypasses traditional grocery retail channels, allowing smaller, niche brands to compete directly with established players. The DTC model is gaining significant traction among millennial and Gen Z consumers in urban centers across the United States and the UK.
Coconut Milk Products Market Segmentation
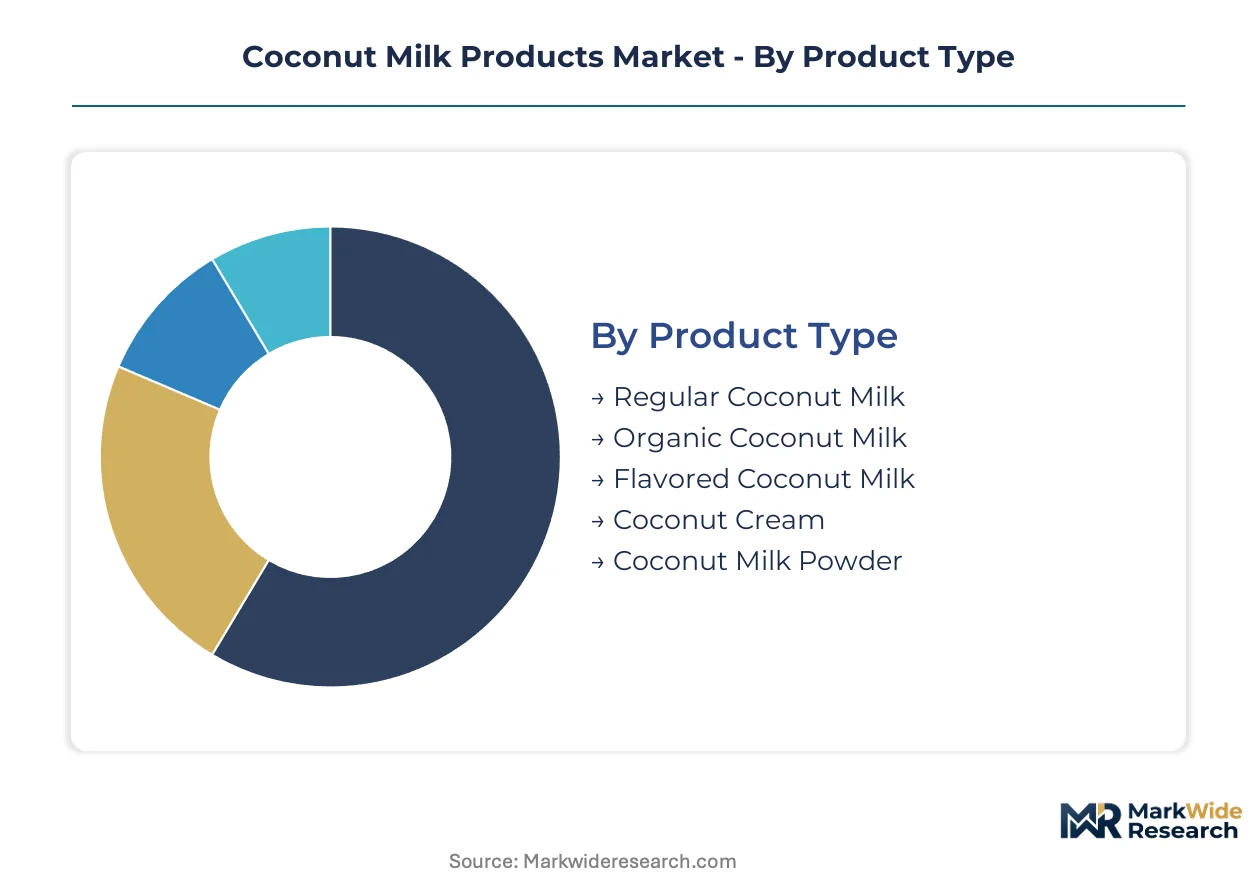
Understanding the varied segments within the coconut milk products market clarifies demand patterns and strategic opportunities. This granular breakdown reveals how product formulations, packaging innovations, and end-use applications shape competitive dynamics. Distinct customer groups also drive specific product development and distribution strategies across regions.
Product Type:
Segmentation by product type highlights how coconut milk products function either as standalone consumer goods or as integrated ingredients within complex formulations.
- Regular Coconut Milk:This product typically contains 17-24% fat, primarily used as a culinary staple in various global cuisines. Demand remains strong in countries like Thailand and India for traditional cooking applications.
- Organic Coconut Milk:Certified organic products adhere to strict agricultural and processing standards, free from synthetic pesticides or fertilizers. Consumer preference for ethical sourcing certifications in urban centers across the United States drives its rapid expansion.
- Flavored Coconut Milk:These products incorporate natural or artificial flavorings, such as vanilla or chocolate, to enhance palatability for beverage consumption.
- Coconut Cream:Distinguished by its higher fat content (20-22%), coconut cream offers a thicker consistency suitable for desserts and rich sauces.
- Coconut Milk Powder:A dehydrated form of coconut milk, this powder provides extended shelf life and convenience for both culinary and industrial applications.
Volume placements concentrate in Regular Coconut Milk; the faster expansion belongs to Organic Coconut Milk.
Packaging Type:
Packaging formats differentiate products based on convenience, shelf life, and cost-efficiency for various distribution channels.
- Carton Packs:These aseptic containers offer extended shelf life without refrigeration, making them ideal for plant-based dairy alternatives in modern retail. Distribution runs primarily through supermarkets and online grocery platforms.
- Cans:Traditional metal cans provide robust protection and long-term stability, commonly used for high-fat coconut milk and cream in culinary applications. They are prevalent in Asian and Latin American markets.
- Glass Bottles:Often associated with premium or organic offerings, glass bottles appeal to consumers seeking perceived purity and recyclability.
- Plastic Bottles:Lightweight and shatter-resistant, plastic bottles are used for ready-to-drink coconut milk beverages, especially in grab-and-go segments.
- Sachets:Small, flexible pouches offer single-serving convenience and cost-effectiveness, particularly popular in developing markets for culinary use.
Carton Packs dominate consumer retail, while Cans maintain a strong presence in traditional culinary markets.
Application:
The diverse applications of coconut milk products span from daily nutrition to specialized industrial uses, catering to distinct consumer needs.
- Beverages:This segment includes ready-to-drink coconut milk, plant-based dairy alternatives, and smoothies, heavily influenced by urban plant-based diets in the United States and Germany. Demand is accelerating due to consumer health consciousness.
- Culinary:Coconut milk serves as a foundational ingredient in cooking and baking, providing flavor and texture to curries, desserts, and sauces. This application segment provides a stable, high-margin base for producers globally.
- Cosmetics:Coconut milk's moisturizing and nourishing properties make it a popular ingredient in lotions, shampoos, and other personal care formulations.
- Pharmaceuticals:Certain components of coconut milk are utilized in pharmaceutical applications for their unique fatty acid profiles and potential health benefits.
- Personal Care:Beyond cosmetics, personal care products like soaps, bath bombs, and hair masks incorporate coconut milk for its natural emollient qualities.
Beverages drive significant market expansion, whereas the Culinary segment provides a stable, high-margin base for producers.
Customer Type:
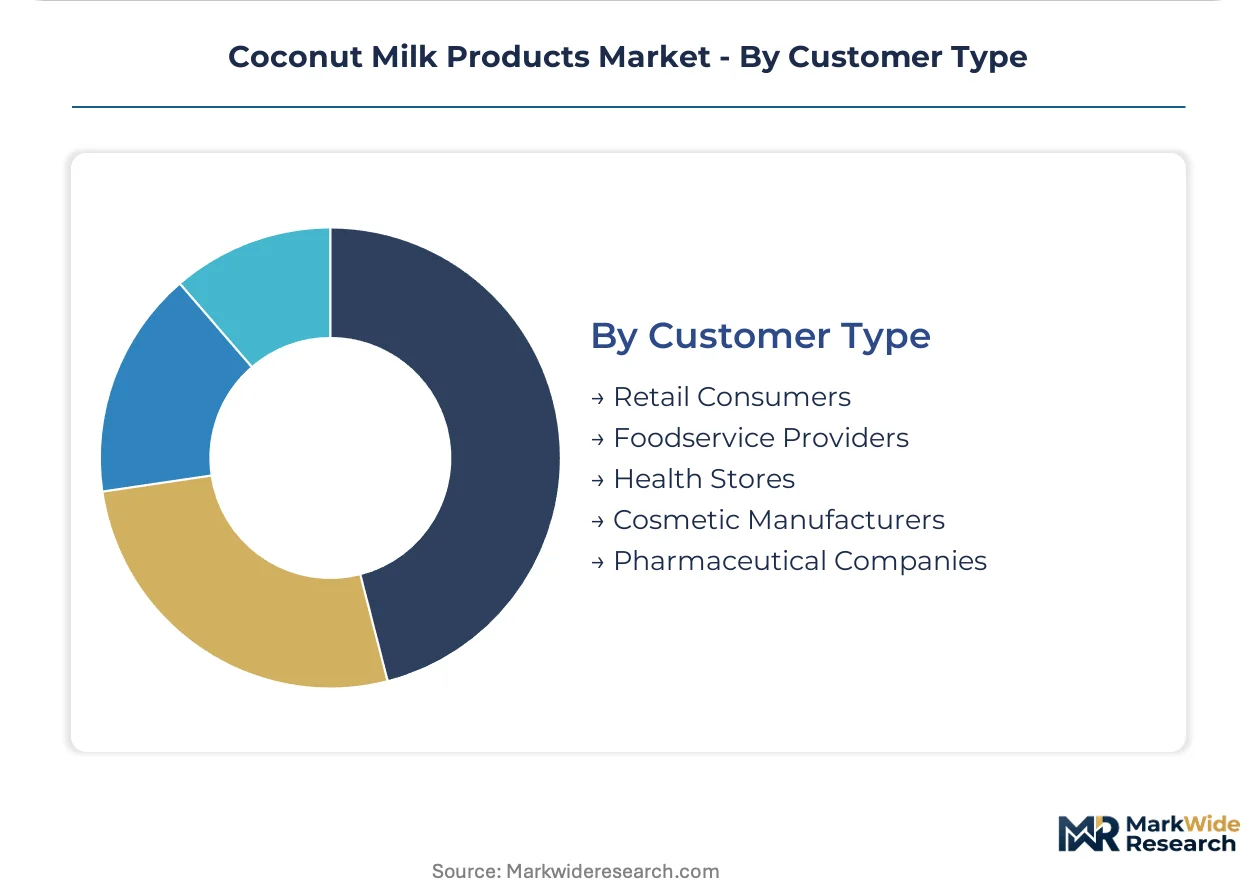
Different customer types dictate specialized product formats and distribution strategies, influencing supply chain configurations and profit margins.
- Retail Consumers:Individual consumers purchase coconut milk products through supermarkets, hypermarkets, and online channels for home consumption. This segment is heavily influenced by clean-label requirements and brand trust.
- Foodservice Providers:Restaurants, cafes, and institutional kitchens utilize coconut milk in bulk for culinary and beverage preparations. McCormick & Company Inc. integrates coconut milk into its global culinary product lines for this sector.
- Health Stores:Specialty retailers focusing on organic, vegan, and health-conscious products cater to a niche but growing consumer base for premium coconut milk.
- Cosmetic Manufacturers:Companies producing beauty and personal care items procure coconut milk as a raw material for their formulations.
- Pharmaceutical Companies:These firms source specific coconut milk derivatives for use in medical and nutraceutical products, often requiring high purity standards.
Retail Consumers represent the largest direct sales channel, while Foodservice Providers offer opportunities for bulk and specialized product formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of coconut cultivation and processing in Southeast Asian nations like Thailand and the Philippines forms a de facto economic zone for coconut milk production. These regions benefit from favorable climates and established agricultural infrastructures. This supply-side strength underpins global market dynamics for coconut milk products.
United States
United States demand for coconut milk products is accelerating due to urban plant-based diets and consumer health consciousness. US FDA allergen labeling mandates drive manufacturers toward coconut milk for clean-label formulations. Major urban centers like New York and Los Angeles exhibit concentrated demand for premium plant-based beverages.
Germany
Germany's market for coconut milk products grows from strong urban plant-based diets seeking dairy alternatives. EFSA guidelines influence product safety and labeling, impacting market access. Cities such as Berlin and Hamburg show high consumer adoption of plant-based dairy substitutes.
Thailand
Thailand serves as a major global producer, with coconut milk deeply embedded as a culinary staple. Producers align with CODEX Alimentarius standards to secure access to European and North American export markets. Processing hubs in Samut Sakhon and Surat Thani drive significant export volumes.
Indonesia
Indonesia represents a critical source of raw materials for the global coconut milk market. Climate events frequently introduce price instability for processors sourcing from the archipelago. Key coconut growing regions in Sumatra and Sulawesi supply a substantial portion of the world's coconut harvest.
Sri Lanka
Sri Lanka emphasizes export-oriented production, particularly for organic and ethically sourced coconut milk. Adherence to CODEX Alimentarius standards enhances market access for Sri Lankan producers. The Coconut Triangle region drives significant processing and export activities for high-quality products.
Coconut Milk Products Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the coconut milk products market, creating a dynamic competitive environment. The landscape exhibits a tiered structure, with large food and beverage companies leveraging extensive distribution networks alongside niche organic brands. Strategic archetypes include global food giants integrating coconut milk into existing lines, regional ingredient suppliers, and specialized plant-based beverage manufacturers. Companies primarily engage in portfolio diversification and geographic expansion, alongside strategic partnerships, to secure market share and access new consumer segments.
Within the global food and beverage sector, Danone S.A., a French multinational food products corporation, exemplifies a diversified conglomerate leveraging its extensive distribution network to introduce plant-based options across multiple retail channels. McCormick & Company Inc., a US-based spice and flavorings company, integrates coconut milk into its global culinary product lines, targeting both retail and foodservice customers worldwide. Vita Coco, a US-based beverage company, occupies a position as a pure-play specialist, building a strong brand identity around natural ingredients and focusing specifically on the beverage segment. These entities represent different strategic approaches to capturing value within the expanding coconut milk products market.
| Leading Market Players |
|---|
| Goya Foods Inc. |
| McCormick & Company Inc. |
| Vita Coco |
| Cocotana Coconut Products |
| Thai Agri Foods Public Company Limited |
| Thai Coconut Public Company Limited |
| Danone S.A. |
| Marico Limited |
| Theppadungporn Coconut Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and sovereign-backed producers in Southeast Asia often control significant raw material access, influencing supply behavior and long-term pricing discipline. Their investment horizons mitigate short-term volatility for processors.
Pricing Analysis
Premium pricing for organic coconut milk with short lead times reflects consumer willingness to pay for certified products. Contract-based long-term offtake dominates for industrial buyers, ensuring supply stability. Price differentiation stems from certification level, such as USDA Organic or Fair Trade, and geographic delivery cost. Pricing softness reflects intense plant-based competition from oat and almond milks in the beverage sector. Retail consumers of conventional coconut milk are most price-sensitive, while foodservice providers for specialty formats exhibit lower price sensitivity.
Supply Chain Analysis
Direct-to-processor channels manage bulk raw material flow from farms in key producing nations. Geographic supply concentration centers on Thailand, Indonesia, and the Philippines for mature coconuts. The supply chain draws from critical inputs like processing enzymes. Commodity price volatility stems from climate events impacting harvests in these nations, creating a structural risk. Retail distribution runs through supermarkets and online grocery platforms for packaged products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coconut milk products market is poised for consolidation, driven by stricter clean-label requirements that pressure smaller players. Technical hurdles in emulsion stability further challenge less capitalized firms.
For Market Incumbents: Cement market share by investing in advanced extraction technologies to improve product stability and shelf life. Expand direct sourcing from certified farms in Thailand and Sri Lanka to control raw material quality and secure supply. This mitigates the threat from intense plant-based competition and leverages vertical integration into raw material processing.
For New Entrants and Emerging Players: Begin with targeted market entry into underpenetrated regions like Eastern Europe, specifically Poland, for plant-based dairy alternatives. Develop novel coconut-based yogurts and creamers with improved texture and stability, addressing specific culinary needs. The most penetrable segment lies within urban centers, leveraging direct-to-consumer subscription models for brand building.
For Investors and Strategic Acquirers: Regulatory harmonization of global quality standards is the leading indicator that market access barriers are shifting. The market exhibits robust long-term viability over a five-to-ten year window, driven by sustained consumer demand for plant-based options. Target acquisition archetype includes vertically integrated mid-cap specialists with strong sustainability certifications. Watch for adoption rates of CODEX Alimentarius standards by smaller producers as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in advanced extraction technologies | Improves emulsion stability and enables novel coconut-based product development for Danone S.A. |
| Expand direct sourcing from certified farms | Secures raw material supply and reinforces sustainability claims for Vita Coco's brand identity. |
| Enter Eastern European markets | Taps into underpenetrated demand for plant-based alternatives in countries like Poland. |
| Develop shelf-stable coconut cream powders | Creates high-margin formats for foodservice culinary applications, targeting professional chefs. |
| Leverage direct-to-consumer (DTC) channels | Bypasses traditional retail, enabling niche brands to reach millennial and Gen Z consumers. |
Research Approach
US FDA filings, EFSA guidelines, and CODEX Alimentarius standards formed the secondary backbone for market sizing and trend identification. This was complemented by primary interviews with industry stakeholders, including food technologists, procurement managers, brand marketing executives, and retail buyers. The analysis employed both bottom-up and top-down triangulation to validate market estimates.
Historical trendline analysis provided the foundational data for projecting market trajectories across the analysis window. Quantitative models integrated segmentation dimensions including product type, packaging, application, customer type, and geographic region. Compound Annual Growth Rates were derived from regression analysis of historical and projected data. Key industry-specific forecast inputs included raw coconut supply projections and plant-based diet adoption rates.
Underlying measurement precision varies by segment; retail consumer and beverage applications carry tighter precision. Forecasts reflect assumptions on consumer preferences and regulatory stability. Climate volatility affecting coconut harvests or shifts in alternative plant-based milks could revise projections; periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Dairy Whiteners Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Reduced Fat Coconut Milk Market