
 Cream Emulsifier Market | 2026-2036
Cream Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Cream Emulsifier Market Analytics
Food-grade emulsifier certification is bifurcating the competitive landscape into premium clean-label suppliers and commodity-grade producers. BASF SE leverages its integrated oleochemicals platform to secure backward control over key fatty acid feedstocks. Cargill, Incorporated anchors North American supply through its extensive vegetable oil processing infrastructure. Kerry Group plc differentiates via application-specific formulation services that extend beyond ingredient supply into finished-product optimization.
A cream emulsifier is a surface-active agent, typically comprising mono- and diglycerides or phospholipid fractions, that reduces interfacial tension between immiscible lipid and aqueous phases to stabilize oil-in-water dispersions in food matrices. Industrial production employs glycerolysis of triglycerides or enzymatic esterification to achieve specified hydrophilic-lipophilic balance values between 3 and 6 for optimal dairy stability. Monoglycerides dominate volume owing to their established cost position in margarine and ice cream applications, while phospholipids represent the fastest-expanding category as lecithin-derived solutions capture clean-label bakery demand. The food industry end-user segment concentrates the largest margin pool, though cosmetics applications command premium pricing for pharmaceutical-grade emulsifier specifications.
FDA food additive regulations under 21 CFR 172 govern emulsifier safety thresholds in US dairy applications, while EFSA evaluates novel emulsifier submissions under the EU food improvement agent framework. REACH compliance obligations for chemical imports shape European supplier qualification requirements and barrier structures. Stakeholders must monitor evolving EFSA re-evaluations of refined vegetable oil contaminants and their downstream implications for emulsifier feedstock sourcing strategies.
Market Dynamics
Clean-label reformulation pressure is fragmenting supply relationships as bakery and dairy processors decouple from synthetic stabilizer portfolios. EU Green Deal chemical sustainability mandates are forcing dual-track qualification pathways that favor oleochemical feedstock traceability over petrochemical alternatives.
Growth Catalysts
- EFSA re-evaluation protocols:The EU food improvement agent framework is accelerating novel emulsifier approvals for plant-derived mono- and diglyceride alternatives. German precision dairy clusters are procuring premium-grade certified ingredients ahead of compliance deadlines.
- Enzymatic esterification:This production technology enables precise hydrophilic-lipophilic balance tuning for clean-label bakery applications. French and Italian artisan bakeries are specifying enzymatically processed emulsifiers for croissant and viennoiserie stability.
- Ice cream processing expansion:Cold-chain infrastructure investments across Southeast Asia are creating demand for heat-stable emulsifier systems. Thailand and Vietnam dairy processors are upgrading emulsifier specifications for tropical distribution.
Market Restraints
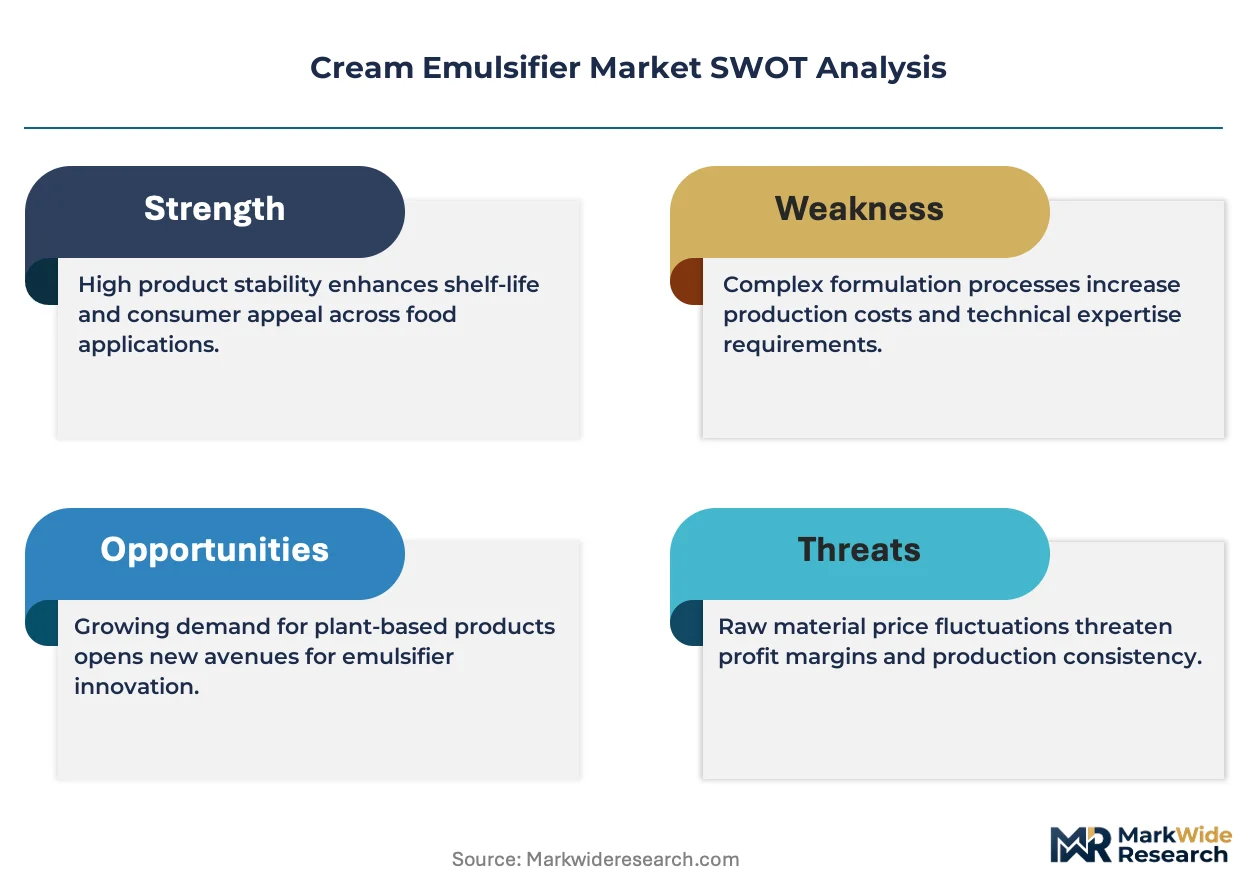
- Vegetable oil feedstock volatility:Palm and rapeseed oil price swings compress margin predictability for glycerolysis-based production. Southeast Asian oleochemical suppliers face working capital strain during commodity spikes.
- REACH compliance burden:European chemical import registration costs disadvantage small-batch specialty emulsifier entrants. ECHA documentation requirements extend supplier qualification timelines by 12-18 months.
- Phospholipid supply concentration:Soy and sunflower lecithin processing clusters in Ukraine and Argentina create geographic risk exposure for clean-label formulators seeking non-GMO certification.
Strategic Opportunities
- Algal phospholipid platforms:Marine-derived lecithin alternatives bypass agricultural commodity cycles and offer allergen-free positioning. Nordic biotech developers are piloting commercial-scale fermentation.
- Cosmeceutical grade expansion:Pharmaceutical-specification emulsifiers for dermal delivery systems command 3-4x food-grade pricing. South Korean and Japanese skincare manufacturers are qualifying new suppliers.
- EU Green Deal procurement incentives:Public-sector foodservice contracts now preference bio-based ingredient certificates. Dutch and Danish institutional catering tenders are incorporating emulsifier sustainability scoring.
Industry Challenges
- Food-grade certification timeline compression:FDA 21 CFR 172 petition processing and EFSA novel food parallel-track submissions strain regulatory affairs capacity. Mid-tier suppliers face 24-36 month approval cycles.
- Legacy equipment retrofit costs:Continuous enzymatic esterification systems require stainless-steel reactor upgrades incompatible with batch glycerolysis infrastructure. Capital deployment decisions are complicated by uncertain clean-label demand elasticity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cream Emulsifier Market |
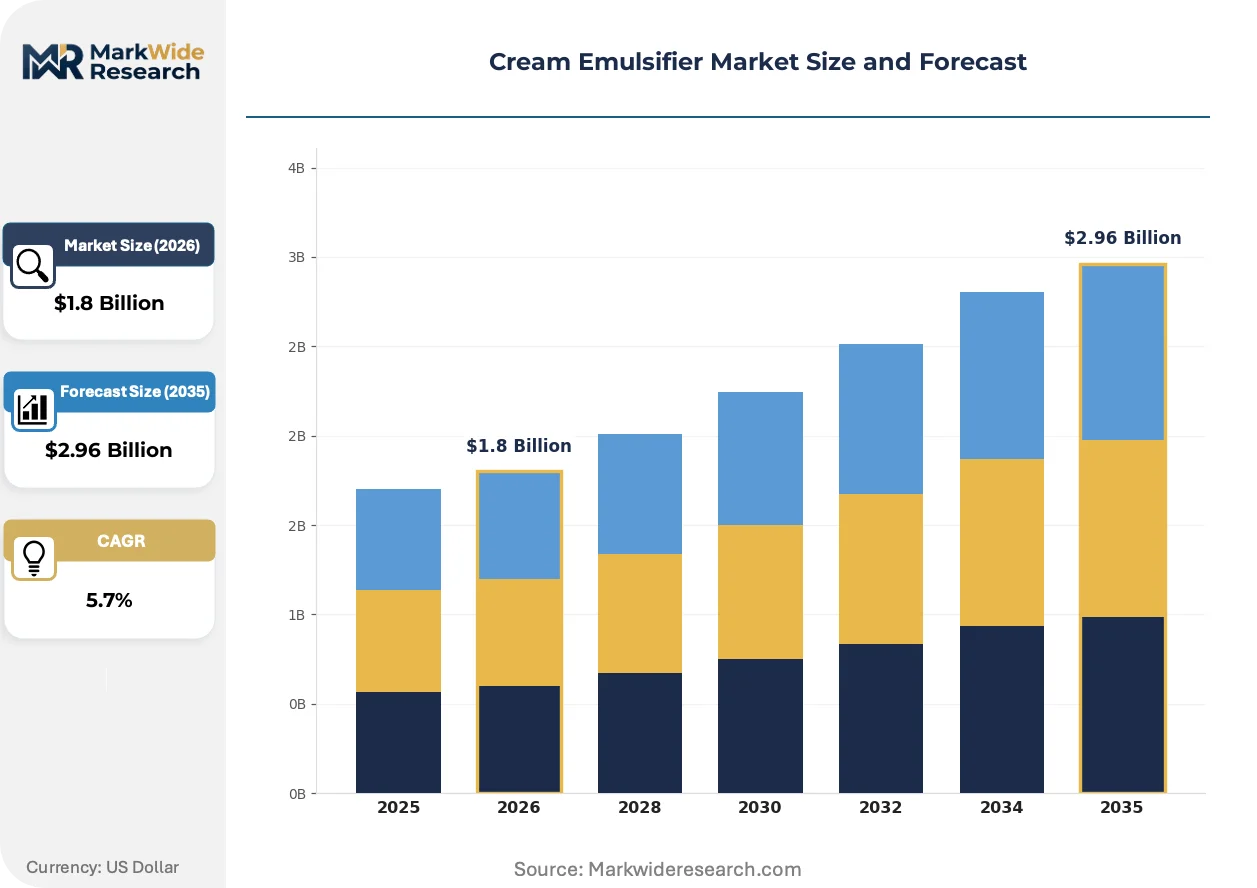
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoglycerides, Diglycerides, Phospholipids, Fatty Acids Application: Dairy Products, Bakery, Confectionery, Sauces End User: Food Industry, Beverage Industry, Cosmetics, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Cargill, Incorporated, Evonik Industries AG, Croda International Plc, Kerry Group plc, Lonza Group AG, International Flavors & Fragrances Inc., Corbion N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cream Emulsifier Market Evolving Landscape
Enzymatic processing platforms are displacing chemical glycerolysis as the dominant production paradigm, while regulatory chemistry is redefining acceptable feedstock provenance. These forces are compressing the supplier base toward integrated oleochemical operators with captive sustainability certification.
Enzymatic esterification using lipase biocatalysts enables precise molecular weight distribution control for tailored hydrophilic-lipophilic balance values. Premium bakery and dairy formulators in Germany, France, and Switzerland are specifying enzymatic grades for clean-label claims. This technology is bifurcating the competitive landscape into certified premium suppliers and commodity chemical processors facing margin compression.
REACH authorization requirements for chemical imports are extending supplier qualification timelines and documentation burdens. European emulsifier procurement teams are consolidating vendor panels toward pre-registered oleochemical platforms with established ECHA dossiers. Food-grade certification applicants without existing REACH compliance face 18-24 month competitive disadvantages in EU tender processes.
Direct procurement relationships between dairy processors and oleochemical refiners are displacing traditional ingredient distributor intermediaries. Large-scale ice cream manufacturers in Italy and Spain are negotiating volume commitments with Malaysian and Indonesian palm derivative processors. This channel restructuring is most visible in Mediterranean markets where processor scale justifies dedicated supply contracts.
Cream Emulsifier Market Segmentation
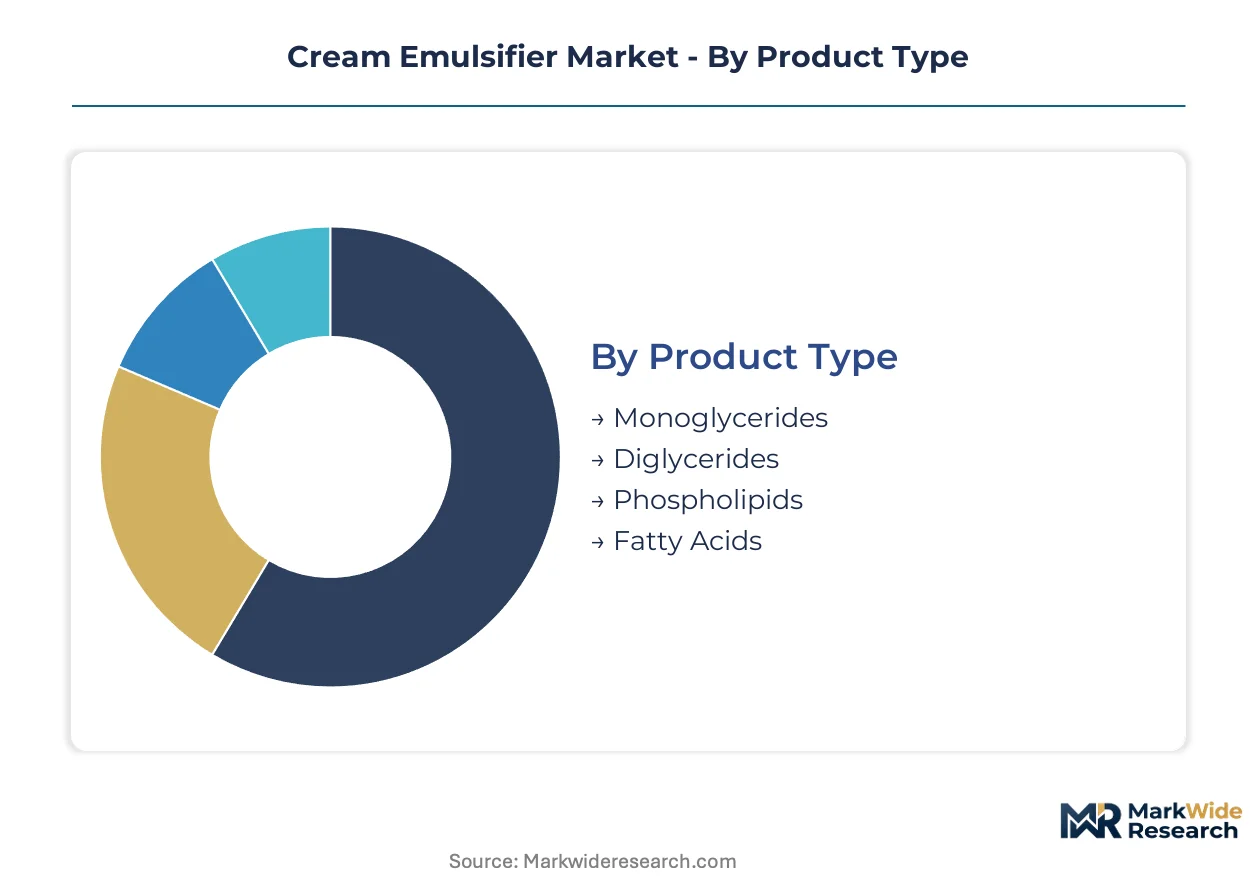
Cream emulsifier procurement channels diverge sharply by certification tier. Food-grade specifications flow through consolidated oleochemical distributors, while pharmaceutical-grade materials require direct manufacturer relationships with full traceability documentation.
Product Type:
Channel access varies dramatically by molecular class—monoglycerides move through commodity distributors, phospholipids through specialty chemical houses with identity preservation protocols.
- Monoglycerides:These monoacylglycerol derivatives achieve hydrophilic-lipophilic balance values between 3 and 6 through glycerolysis of triglyceride feedstocks. German precision dairy clusters procure enzymatically processed grades for clean-label ice cream stabilization ahead of EU Green Deal compliance deadlines.
- Phospholipids:Lecithin-derived fractions from soy and sunflower sources enable allergen-free positioning in artisan bakery applications. French and Italian croissant manufacturers specify non-GMO certified grades, though Ukrainian and Argentine supply concentration creates geographic risk exposure.
- Diglycerides:Diacylglycerol emulsifiers serve margarine and spread applications where intermediate HLB values suffice.
- Fatty Acids:Free fatty acid fractions function as co-emulsifiers in compound stabilizer systems for industrial dairy processors.
By volume, monoglycerides lead. By growth pace, phospholipids are expanding most quickly.
Application:
Cost tier stratification separates premium enzymatic grades for artisan producers from commodity chemical specifications for mass-market manufacturers.
- Dairy Products:Ice cream, whipped toppings, and processed cheese require heat-stable emulsifier systems with precise overrun control. Thai and Vietnamese processors upgrading cold-chain infrastructure are driving tropical-climate specification demand.
- Bakery:Viennoiserie and laminated dough applications demand enzymatically processed monoglycerides for clean-label claims without azodicarbonamide alternatives. Swiss and Austrian industrial bakeries pay 15-25% premiums for certified sustainable palm derivatives.
- Confectionery:Chocolate and compound coating formulations utilize lecithin for viscosity reduction and fat bloom prevention.
- Sauces:Mayonnaise and dressing emulsions require high-HLB systems for cold-process stability.
Dairy applications concentrate the largest margin pool. Bakery segments show the steepest expansion trajectory for certified clean-label grades.
End User:
Customer type determines specification stringency—pharmaceutical buyers impose pharmaceutical-grade purity thresholds that food processors rarely require.
- Food Industry:Industrial dairy and bakery processors account for the dominant volume share, with procurement consolidating toward direct oleochemical refiner relationships bypassing traditional distributors. Italian and Spanish ice cream manufacturers now negotiate volume commitments with Malaysian palm derivative processors.
- Cosmetics:Dermal delivery systems and skincare formulations command 3-4x food-grade pricing for pharmaceutical-specification emulsifiers. South Korean and Japanese manufacturers are actively qualifying new suppliers for cosmeceutical applications.
- Beverage Industry:Clouding agents and flavor emulsions for soft drinks represent a specialized sub-segment with distinct regulatory pathways.
- Pharmaceuticals:Oral and topical drug delivery systems require compendial-grade materials with full batch documentation.
Food industry volume dominates current procurement. Cosmetics represents the fastest-climbing value tier.
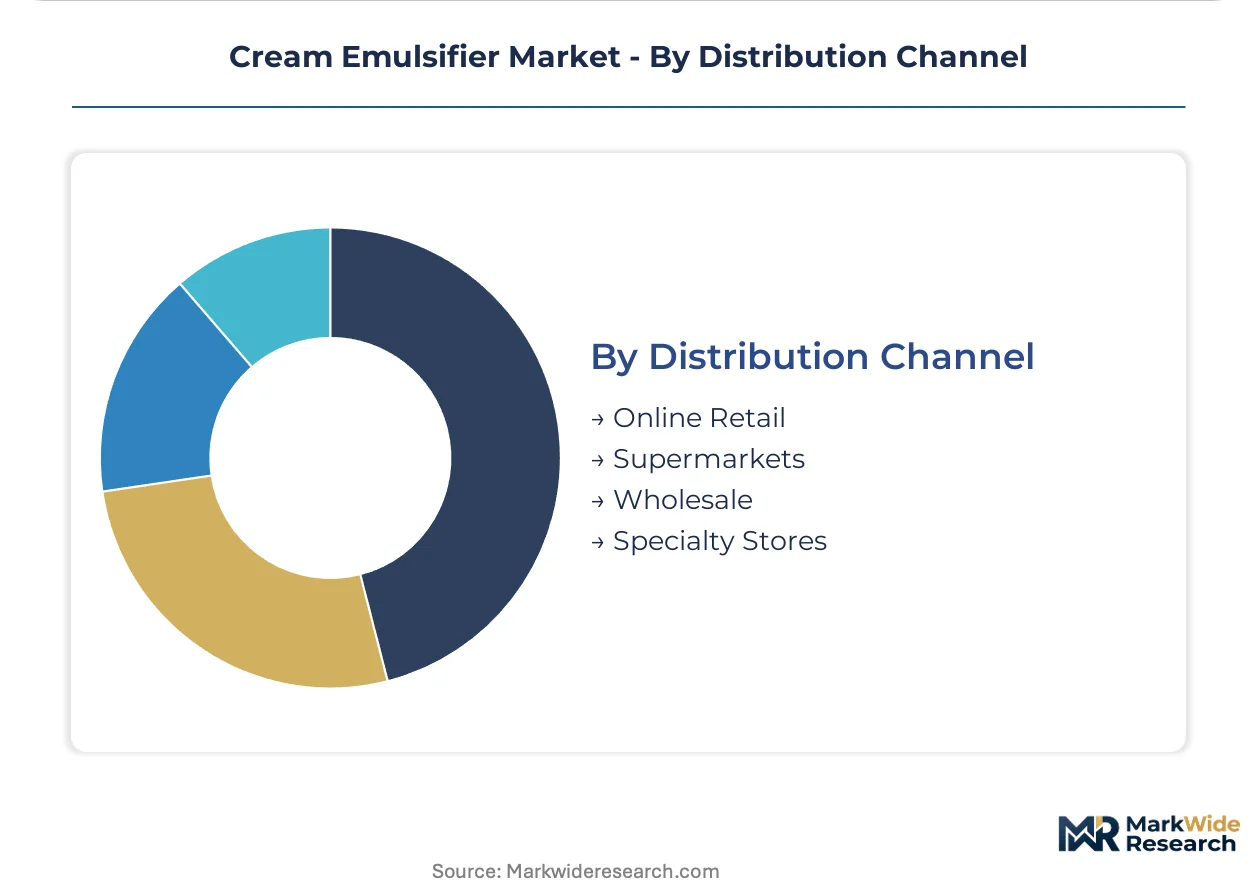
Distribution Channel:
Supply concentration shapes channel structure—bulk commodity flows through wholesale, specialty grades through identity-preserved direct sourcing.
- Wholesale:Industrial-scale dairy and bakery processors procure monoglyceride and diglyceride volumes through established oleochemical distributors with REACH-registered supply chains. Dutch and Danish institutional catering tenders now incorporate sustainability scoring that favors bio-based certificate holders.
- Online Retail:Small-batch artisan producers and cosmetics formulators access phospholipid and specialty fatty acid grades through digital platforms with technical documentation portals.
- Supermarkets:Consumer-packaged emulsifier blends for home baking occupy a niche retail position.
- Specialty Stores:Foodservice supply houses serve restaurant and catering channels with application-specific stabilizer systems.
Wholesale channels handle the greatest tonnage. Online retail is gaining share fastest among specialty-grade buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oleochemical refining capacity clusters in Southeast Asia and Western Europe, with downstream emulsifier formulation gravitating toward precision dairy processing hubs. Regulatory chemistry divergence between FDA 21 CFR pathways and EFSA novel food frameworks is fragmenting supplier qualification strategies across jurisdictions.
Germany
Precision dairy clusters in Bavaria and North Rhine-Westphalia drive premium enzymatic emulsifier procurement for clean-label ice cream stabilization. EFSA re-evaluation protocols under the EU food improvement agent framework are accelerating plant-derived mono- and diglyceride approvals ahead of Green Deal compliance deadlines. Stuttgart-area industrial bakeries specify certified sustainable palm derivatives for viennoiserie applications.
United States
FDA 21 CFR 172 petition processing governs food additive safety thresholds for dairy emulsifier applications, with industrial processors in Wisconsin and California consolidating direct refiner relationships. Cold-chain infrastructure expansion across the Southeast is creating demand for heat-stable stabilizer systems in regional ice cream manufacturing. Chicago-based oleochemical distributors anchor mid-continental supply logistics.
Thailand
Tropical-climate dairy processing upgrades in Bangkok and surrounding provinces are driving specification demand for heat-stable emulsifier systems. Cold-chain infrastructure investments across Southeast Asia position Thai processors as regional distribution hubs for heat-resistant stabilizer formulations. Samut Prakan industrial zones concentrate compound dairy ingredient blending operations.
France
Artisan bakery specifications for enzymatically processed emulsifiers in croissant and viennoiserie applications command 15-25% premiums over chemical glycerolysis grades. REACH compliance obligations for chemical imports extend supplier qualification timelines, favoring pre-registered oleochemical platforms with established ECHA dossiers. Lyon-area foodservice distributors are consolidating vendor panels toward bio-based certificate holders.
Japan
Cosmeceutical-grade emulsifier demand from South Korean and domestic skincare manufacturers commands pharmaceutical-specification pricing at 3-4x food-grade levels. METI industrial standards shape import qualification pathways for novel enzymatic processing technologies. Osaka-Kobe chemical processing corridors concentrate pharmaceutical-grade emulsifier formulation capabilities.
Cream Emulsifier Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enzymatic processing specialists commanding premium positioning against glycerolysis-based commodity producers. The supplier base compresses toward integrated oleochemical operators with captive sustainability certification and established regulatory dossiers. Three archetypes dominate: backward-integrated refiners with feedstock control, application-specific formulation service providers, and specialty phospholipid fractionators. Competitive moves center on direct procurement relationship cultivation with large-scale dairy processors and enzymatic reactor capacity expansion.
Among European-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated oleochemical archetype with backward control over fatty acid feedstocks. Kerry Group plc occupies a position within the formulation services tier, extending beyond ingredient supply into finished-product optimization. These three companies represent the competitive spectrum from commodity-scale production to premium application-specific service delivery.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Evonik Industries AG |
| Croda International Plc |
| Kerry Group plc |
| Lonza Group AG |
| International Flavors & Fragrances Inc. |
| Corbion N.V. |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for enzymatic-grade emulsifiers concentrate pricing power with Malaysian and Indonesian oleochemical refiners possessing backward integration into palm derivative streams. REACH-registered suppliers command 15-25% premiums over non-registered alternatives as ECHA documentation burdens extend qualification timelines.
Pricing Analysis
EU Green Deal chemical sustainability mandates dictate the pricing tier structure across enzymatic, chemical glycerolysis, and commodity spot grades. Certification level separates premium clean-label positioning from standard food-grade specifications, with volume scale driving economy-tier negotiations for industrial dairy processors. Cost compression in chemical glycerolysis tiers is intensifying because of vegetable oil feedstock volatility, while artisan bakery segments show least price sensitivity for certified sustainable derivatives.
Supply Chain Analysis
Ninety-day inventory cycles for phospholipid fractions expose formulators to Ukrainian and Argentine supply concentration risks. Malaysia, Indonesia, and Germany anchor global oleochemical refining capacity, with production drawing from palm oil, rapeseed oil, and soy lecithin feedstocks. Single-source vulnerability in sunflower lecithin processing creates geographic risk exposure for clean-label formulators. Distribution runs through consolidated wholesale channels for commodity grades and identity-preserved direct sourcing for pharmaceutical specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cream emulsifier market tracks cyclical recovery patterns tied to cold-chain infrastructure investment waves across Southeast Asian dairy processing. Procurement consolidation toward direct refiner relationships signals margin expansion potential for integrated operators.
For Market Incumbents: Shield enzymatic processing margins by securing captive palm derivative supply through Malaysian refiner partnerships. Invest in EFSA novel food dossier completion ahead of EU Green Deal compliance deadlines to preempt competitor certification fast-tracks. Backward integration into oleochemical refining insulates against vegetable oil commodity cycles.
For New Entrants and Emerging Players: EFSA novel food fast-track submissions for algal phospholipid platforms open white-space penetration in allergen-free bakery applications. Target South Korean and Japanese cosmeceutical manufacturers with pharmaceutical-grade specifications commanding premium multiples. Pursue direct procurement relationships with Thai ice cream processors upgrading tropical-climate stabilizer systems.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-driven ingredient consolidation play because enzymatic processing capacity scarcity concentrates value capture with certified operators. Acquisition targets include mid-tier enzymatic specialists with established REACH dossiers and artisan bakery channel relationships. Monitor EFSA re-evaluation protocol acceleration as inflection signal for premium-grade demand elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Derivative Refining | Captive feedstock supply secures margin stability against Malaysian and Indonesian commodity volatility. |
| Enzymatic Esterification Capacity Expansion | Clean-label certification unlocks 15-25% pricing premiums from German and French artisan bakery procurement. |
| EFSA Novel Food Dossier Investment | Pre-registered status compresses 18-24 month competitive disadvantages in EU institutional catering tenders. |
| Algal Phospholipid Platform Development | Marine-derived alternatives bypass Ukrainian and Argentine agricultural commodity concentration risks. |
| Direct Refiner Relationships with Dairy Processors | Bypassing traditional distributors captures margin pool consolidation in Italian and Spanish ice cream manufacturing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, EFSA novel food submission registers, and oleochemical industry association reports. Primary interviews engaged plant managers at Southeast Asian refiners, procurement leads at German precision dairy clusters, technical R&D directors at enzymatic processing specialists, and channel partners in French artisan bakery distribution. Bottom-up volume triangulation from individual facility capacities converges with top-down value estimates from trade flow analysis.
Segmentation dimensions modeled span product type, application, end-user industry, and certification tier across the analysis window. CAGRs derive from growth driver elasticity modeling against historical capacity expansion patterns and regulatory approval velocity. Forecast inputs incorporate cold-chain infrastructure investment pipelines and EFSA re-evaluation protocol timelines without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt vegetable oil supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding enzymatic processing adoption curves and phospholipid supply chain resilience. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Food Grade Distilled Monoglyceride Market
Food Additives and Ingredients
Brazil Feed Additives Market