
 Asia-Pacific Walnut Milk Market | 2026-2036
Asia-Pacific Walnut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Walnut Milk Market Outlook
Foodservice procurement across Asia-Pacific is consolidating as cafe chains and restaurant groups centralize non-dairy purchasing decisions under regional procurement hubs. Yili Group leverages its dairy distribution infrastructure to push walnut milk into mainstream retail channels across China. Vitasoy International Holdings anchors its position through decades of plant-based beverage expertise in Hong Kong and Southeast Asian markets. Hebei Yangyuan Zhihui Beverage Co., Ltd. competes with concentrated regional strength in northern China's traditional nut-processing corridor.
Walnut milk is an aqueous emulsion produced by grinding shelled walnuts with water, typically containing two to four percent walnut solids, then homogenizing and pasteurizing to achieve microbial stability and shelf-ready viscosity. The beverage serves as a lactose-free alternative in direct consumption, coffee preparation, and food manufacturing where creamy mouthfeel and subtle nuttiness replace dairy or soy bases. Unsweetened variants lead volume in health-positioned channels where sugar reduction drives selection, while flavored formats capture trial among younger consumers in convenience retail. Organic certification commands price premiums in Japanese and Australian supermarkets, though conventional products dominate mass-market penetration in China and Vietnam.
China's SAMR enforces GB standards for plant protein beverages that define minimum protein content and labeling requirements for walnut-based drinks. India's FSSAI regulates nut milk under its broader plant-based beverage framework, with state food safety commissioners conducting facility inspections. Japan's METI oversees agricultural product standards that affect walnut sourcing claims and organic certification recognition. Stakeholders must monitor how divergent national standards for protein fortification and allergen labeling evolve across the region's fragmented regulatory landscape.
Market Dynamics
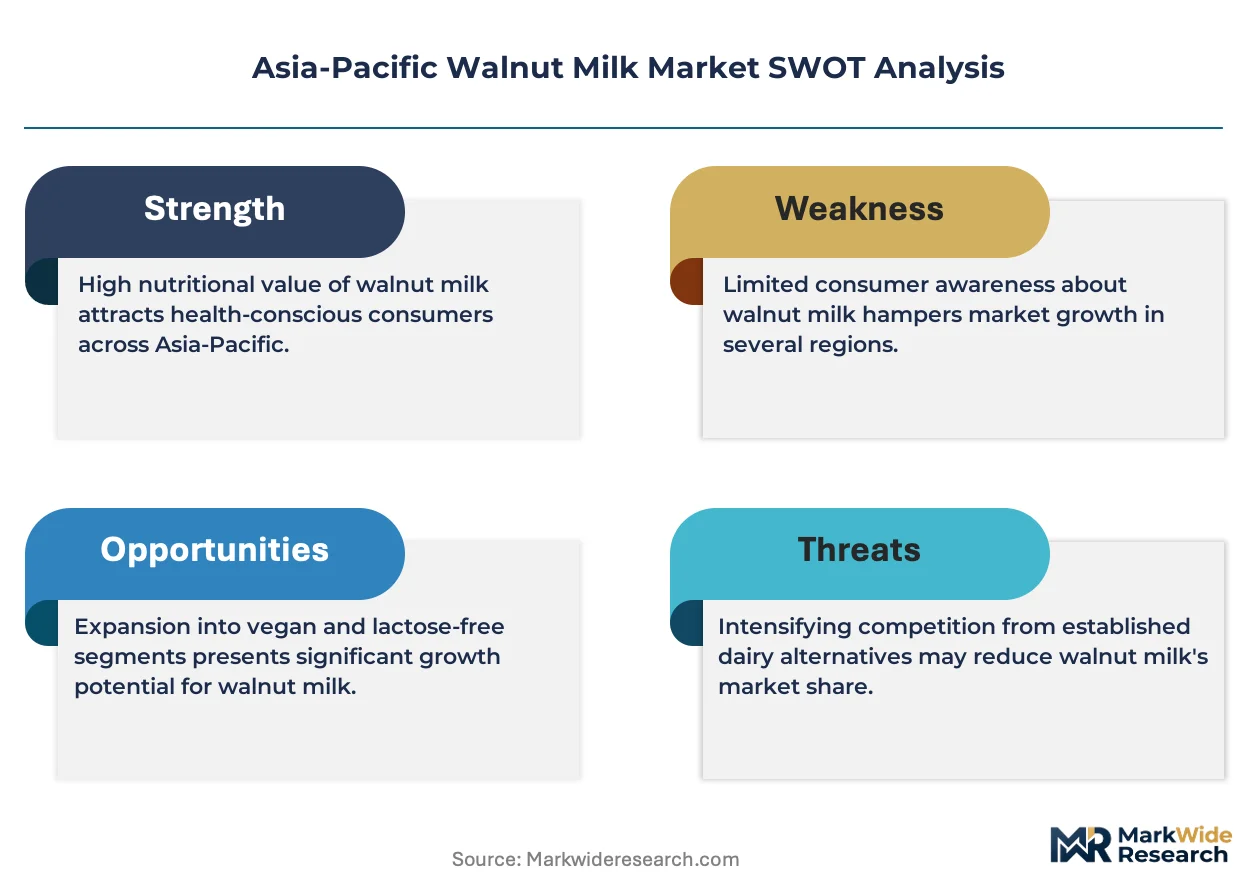
Foodservice procurement consolidation across Asia-Pacific is compressing supplier margins while accelerating volume commitments to large-scale walnut milk producers with certified manufacturing capabilities.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of plant protein beverage standards validates walnut milk as a legitimate dairy alternative, expanding shelf placement in mainstream retail.
- Cafe Chain Centralization:Regional procurement hubs at major coffee chains are standardizing non-dairy menus, locking in multi-year supply agreements with qualified walnut milk vendors.
- Organic Certification Pipeline:Japanese and Australian supermarket buyers are demanding certified organic variants, pulling premium-priced product through dedicated health channels.
Market Restraints
- Walnut Input Volatility:Xinjiang and Yunnan growing regions face climate-induced yield fluctuations that transmit directly to processor cost structures.
- Regional Supply Concentration:Northern China's traditional nut-processing corridor controls critical crushing and oil-extraction infrastructure, creating bottleneck vulnerability.
- Soy Milk Substitution:Established soy beverage infrastructure and consumer familiarity in Vietnam and Thailand limit walnut milk penetration in price-sensitive segments.
Strategic Opportunities
- India's FSSAI Framework:Clarified plant-based labeling guidelines create regulatory runway for nut-based beverage market development in tier-one cities.
- Bakery Application Expansion:Food manufacturers in Southeast Asia are reformulating confectionery and pastry bases with walnut milk for moisture retention and flavor differentiation.
- UHT Technology Convergence:Aseptic packaging advances combined with extended-shelf-life processing are opening convenience store channels previously closed to chilled distribution.
Industry Challenges
- Allergen Labeling Complexity:Divergent national standards for tree nut declaration across China, Japan, India, and Australia force multi-format packaging runs.
- Homogenization Equipment Sourcing:High-pressure processing systems capable of achieving stable walnut oil-in-water emulsion require 18-24 month procurement lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Walnut Milk Market |
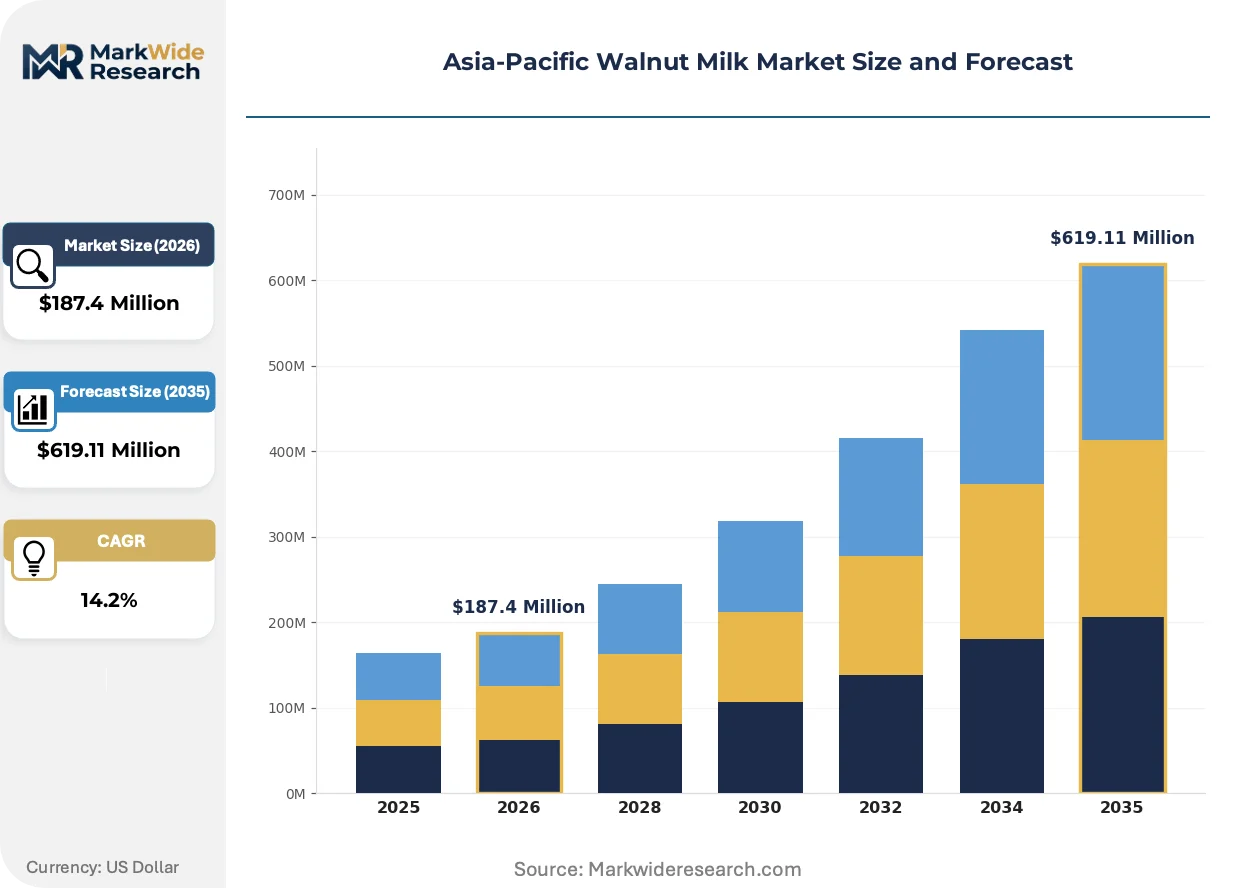
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Flavored, Organic Distribution Channel: Supermarkets, Health Stores, Online Retailers, Specialty Shops End User: Households, Restaurants, Cafes, Food Manufacturers Packaging Type: Bottle, Carton, Tetra Pak, Jar |
| Companies Covered | Simple Foods Co., Ltd. (137 Degrees), Yili Group, Hebei Yangyuan Zhihui Beverage Co., Ltd., Elmhurst Milked Direct LLC, Borges Agricultural & Industrial Nuts, H Milk Food Joint Stock Company (TH True Nut), RITA Food & Drink Co., Ltd., Vitasoy International Holdings, California Walnuts, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Walnut Milk Market Strategic Shifts
Processing technology standardization and regulatory clarity are converging to professionalize what remains a fragmented supplier base across the region.
High-pressure homogenization systems capable of sub-micron particle size reduction are consolidating quality benchmarks for walnut milk emulsion stability. Food manufacturers in China's bakery sector are adopting these systems to replace batch-scale blending equipment. The technology is consolidating production around processors with capital access, squeezing out artisanal producers dependent on conventional grinding methods.
India's FSSAI plant-based beverage framework is mandating protein content minimums and standardized nomenclature for nut-derived drinks. The regulation forces reformulation of existing products and retooling of labeling lines. Domestic brands targeting health-positioned urban consumers are responding fastest, while import-dependent players face compliance timeline compression.
Cafe chain procurement officers are consolidating non-dairy purchasing under regional hubs with technical audit capabilities. Traditional distributor networks serving independent coffee shops are losing volume to direct manufacturer relationships. This concentration is most visible in Shanghai, Beijing, and Singapore, where head-office procurement teams now mandate supplier sustainability certifications.
Asia-Pacific Walnut Milk Market Segmentation
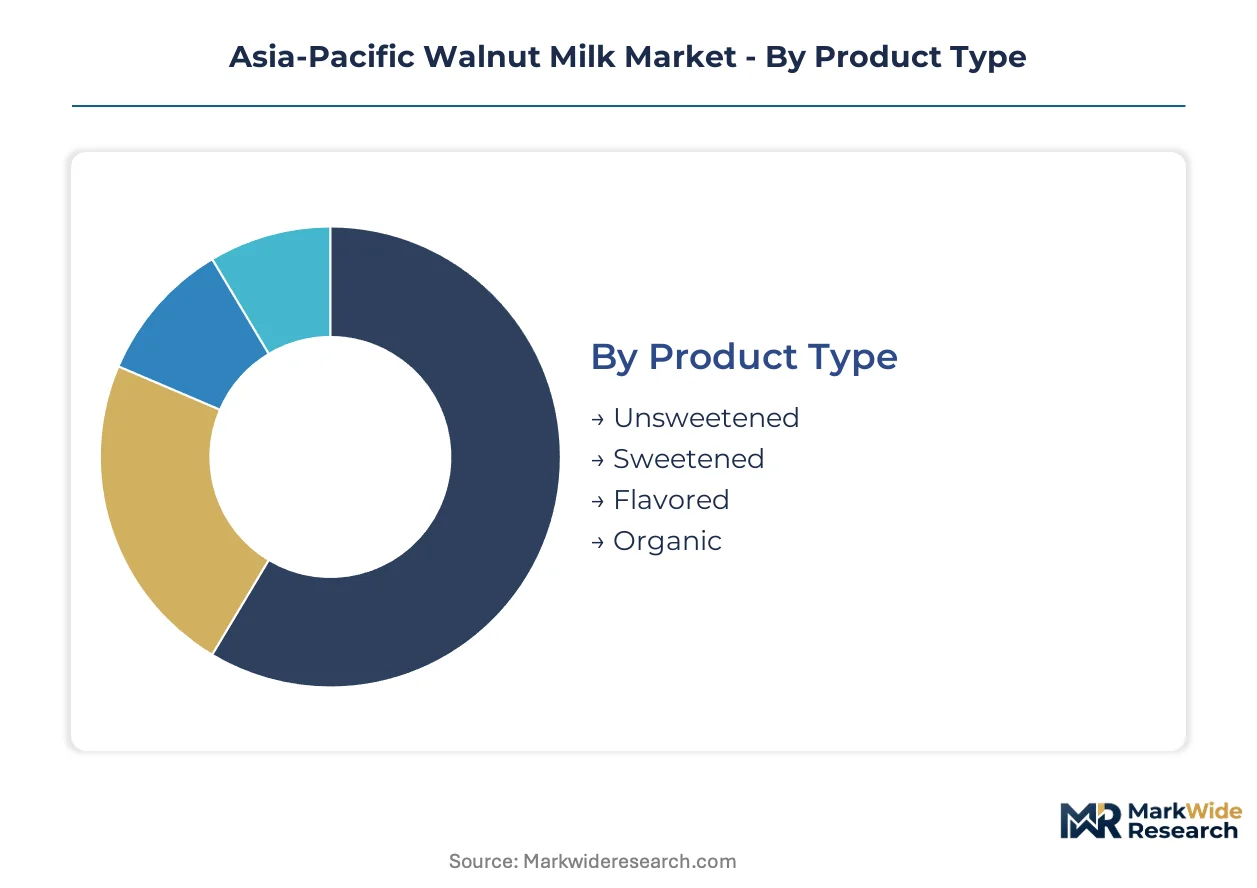
Walnut milk segmentation across Asia-Pacific reflects divergent consumer priorities: sugar reduction, organic certification, and foodservice functionality each command distinct product architectures. Manufacturers configure production lines around these splits to capture price premiums in health-positioned channels while maintaining volume in mass retail.
Product Type:
Reformulation cycles in Asia-Pacific walnut milk accelerate as health-positioned consumers upgrade from sweetened to unsweetened variants, pulling processor R&D investment toward clean-label stabilization systems.
- Unsweetened:Contains zero added sugars with walnut solids typically at two to four percent, relying on natural nut oils for mouthfeel. Demand concentrates in Shanghai and Beijing fitness-oriented retail channels where macro-tracking consumers prioritize ingredient minimalism.
- Organic:Certified under Japan's JAS standards or Australia's NASAA protocols, commanding shelf price multiples in premium supermarket aisles. Japanese and Australian buyers pull these variants through dedicated health channels despite constrained domestic walnut supply.
- Sweetened:Added cane sugar or maltodextrin at three to six percent for palatability in mass-market penetration.
- Flavored:Vanilla, chocolate, or coffee infusions targeting younger consumers in Vietnam and Thailand convenience retail.
Volume placements concentrate in Unsweetened; the faster expansion belongs to Organic.
Distribution Channel:
Channel cost structures in Asia-Pacific walnut milk stratify sharply: refrigerated supply chains absorb margin in supermarkets while ambient-stable formats unlock convenience store penetration.
- Supermarkets:Dominant volume channel requiring cold-chain logistics and slotting fee negotiations with chains like Aeon in Japan or Woolworths in Australia. China's Hema Fresh and Yonghui Superstores anchor mainstream adoption through dedicated plant-based beverage sections.
- Online Retailers:Tmall, JD.com, and Shopee aggregate trial-size purchases and subscription models for direct-to-consumer brands. Live-streaming commerce in China accelerates discovery among tier-two city consumers lacking specialty store access.
- Health Stores:Curated assortments with trained staff recommendation in Japan's Natural House and Australia's Go Vita networks.
- Specialty Shops:Independent organic retailers and nut-focused boutiques with localized sourcing stories.
Supermarkets anchor current revenue; Online Retailers are climbing the fastest as logistics infrastructure matures.
End User:
End-use specifications in Asia-Pacific walnut milk diverge on fat content, emulsion stability, and packaging format, forcing manufacturers to maintain parallel production configurations.
- Food Manufacturers:Industrial volumes for bakery, confectionery, and dairy-alternative reformulation requiring standardized protein content and neutral flavor profiles. Southeast Asian pastry producers in Malaysia and Indonesia adopt these inputs for moisture retention in premium product lines.
- Cafes:Barista-grade formulations with foaming stability for latte art and espresso compatibility. Regional procurement hubs at chains like Luckin Coffee and % Arabica consolidate purchasing power around certified manufacturing capabilities.
- Households:Direct consumption in family-size formats with extended shelf-life priorities.
- Restaurants:Bulk foodservice packs with cost-per-liter optimization for menu integration.
Food Manufacturers dominate procurement tonnage; Cafes show the steepest expansion trajectory as specialty coffee culture penetrates tier-one Asian cities.
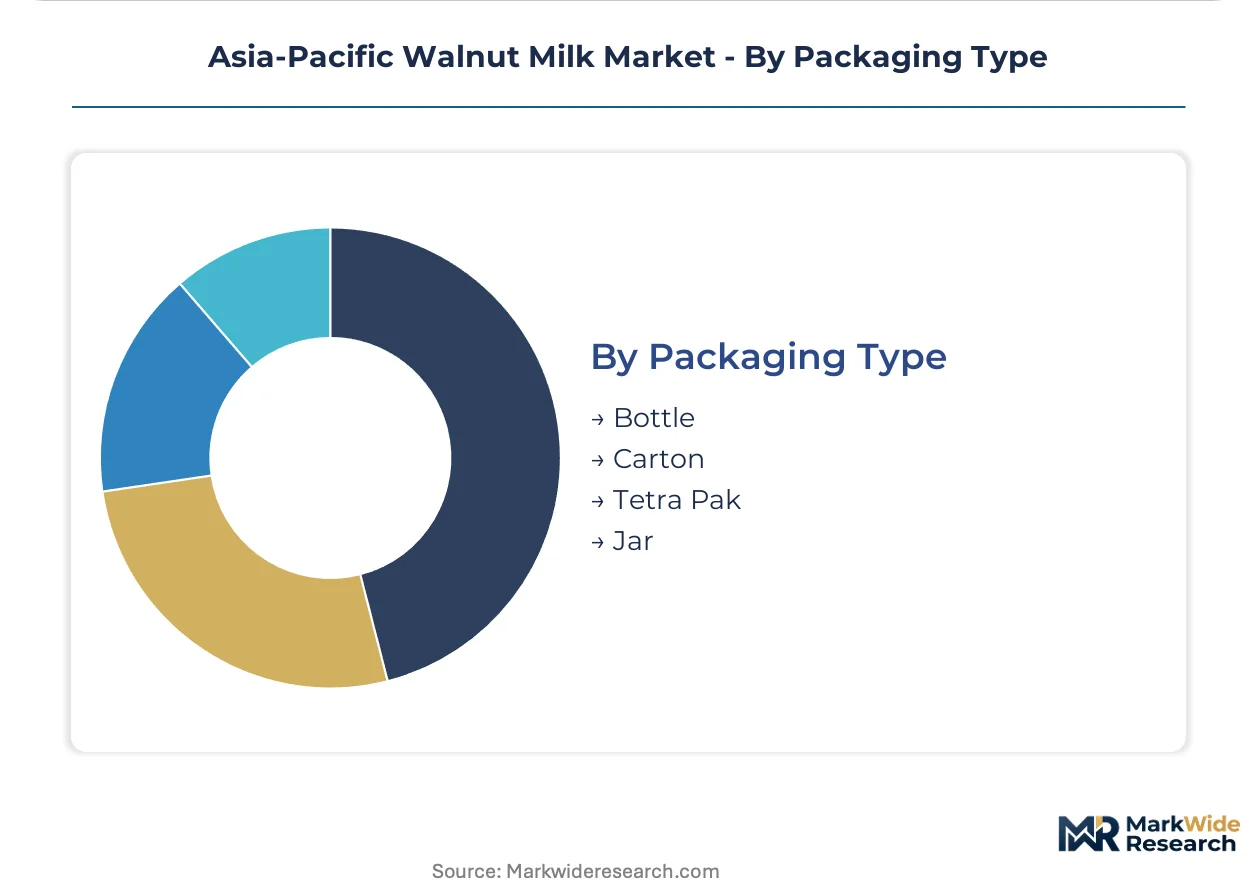
Packaging Type:
Packaging technology selection in Asia-Pacific walnut milk locks in shelf-life economics and channel access, with aseptic investments determining competitive viability.
- Tetra Pak:Aseptic carton systems enabling ambient distribution and twelve-month shelf stability without refrigeration. China's SAMR GB standards compliance integrates with these formats for nationwide retail penetration beyond cold-chain constraints.
- Bottle:PET and HDPE formats for chilled distribution with transparent product visibility. Australian and Japanese retailers favor these for refrigerated premium positioning.
- Carton:Gable-top chilled cartons for shorter shelf-life products in established cold-chain markets.
- Jar:Glass packaging for gift-oriented and ultra-premium organic segments in specialty channels.
Tetra Pak commands the widest geographic reach; Bottle formats gain share fastest in health-positioned chilled retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban health-conscious consumers in China's tier-one cities concentrate the region's premium demand, while Southeast Asian food manufacturers drive industrial procurement volumes for bakery and confectionery applications.
China
Shanghai and Beijing consumers pull organic and unsweetened variants through Hema Fresh and Yonghui Superstores. SAMR's GB standards enforcement validates walnut milk as a legitimate dairy alternative, expanding mainstream retail shelf placement. Hebei province's traditional nut-processing corridor anchors crushing and oil-extraction infrastructure for northern supply.
Japan
Health-positioned consumers in Tokyo and Osaka demand JAS-certified organic products through Natural House and Aeon networks. METI oversees agricultural product standards affecting walnut sourcing claims and organic certification recognition. Kanto region retailers favor transparent PET bottles for chilled premium positioning.
India
Tier-one city consumers in Mumbai and Delhi-NCR respond to clarified FSSAI plant-based labeling guidelines for nut-based beverages. State food safety commissioners conduct facility inspections under the broader plant-based beverage framework. Western India shows fastest brand response to protein content minimum mandates.
Australia
NASAA-certified organic variants command price multiples in Woolworths and Go Vita health channels. The country's agricultural product standards affect import recognition of foreign organic certifications. Sydney and Melbourne anchor demand concentration for premium chilled formats.
Vietnam
Younger consumers in Ho Chi Minh City and Hanoi drive flavored variant trial through convenience retail and Shopee platforms. Established soy beverage infrastructure limits walnut milk penetration in price-sensitive segments. Southern provinces concentrate foodservice distribution for cafe chain procurement.
Asia-Pacific Walnut Milk Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty organic and barista-grade positioning. The supplier base stratifies between dairy conglomerates leveraging existing cold-chain infrastructure and dedicated nut-beverage specialists with regional processing expertise. Three archetypes dominate: dairy diversifiers extending plant-based portfolios, nut-processing specialists with upstream sourcing control, and contract manufacturers serving private-label retail programs. Competitive moves center on regional procurement hub qualification and aseptic packaging capacity expansion.
Among China-based beverage conglomerates, Yili Group exemplifies dairy infrastructure leverage for mainstream retail penetration. Hebei Yangyuan Zhihui Beverage Co., Ltd. occupies a position within the nut-processing specialist tier, representing concentrated regional strength in northern China's traditional corridor. Vitasoy International Holdings anchors decades of plant-based beverage expertise across Hong Kong and Southeast Asian markets.
| Leading Market Players |
|---|
| Simple Foods Co., Ltd. (137 Degrees) |
| Yili Group |
| Hebei Yangyuan Zhihui Beverage Co., Ltd. |
| Elmhurst Milked Direct LLC |
| Borges Agricultural & Industrial Nuts |
| H Milk Food Joint Stock Company (TH True Nut) |
| RITA Food & Drink Co., Ltd. |
| Vitasoy International Holdings |
| California Walnuts |
| Others |
Value Chain & Pricing Dynamics
Captive walnut sourcing in Xinjiang and Yunnan provinces anchors both supply security and margin control for processors with in-house crushing infrastructure. China's SAMR GB standards compliance costs and foodservice procurement consolidation are compressing supplier margins while rewarding scaled producers with certified manufacturing capabilities.
Pricing Analysis
Volume placements in mass-market unsweetened formats run on thin margins while organic and barista-grade variants capture premium multiples. Pricing stratifies across JAS-certified organic, SAMR-compliant standard, and economy private-label tiers, with certification grade and cold-chain delivery cost driving differentiation. Cost compression in conventional segments is intensifying because cafe chain procurement hubs demand sustainability certifications and multi-year volume commitments. Food manufacturers in Southeast Asia show least price sensitivity due to reformulation value capture, while Vietnam's soy-accustomed consumers resist walnut milk at prevailing premiums.
Supply Chain Analysis
Single-source vulnerability sits with northern China's Hebei nut-processing corridor, where crushing and oil-extraction infrastructure concentrates. Raw material flows draw from Xinjiang, Yunnan, and imported California walnut shipments, with high-pressure homogenization equipment and aseptic carton packaging resting on 18-24 month procurement lead times. Climate-induced yield volatility in Chinese growing regions creates commodity price exposure that transmits directly to processor cost structures. Distribution runs through Tetra Pak ambient networks for nationwide penetration and chilled bottle formats for Japanese and Australian premium retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foodservice procurement consolidation and SAMR compliance cost escalation are forcing artisanal producers toward exit or acquisition, consolidating viable supply around scaled manufacturers with certified capabilities.
For Market Incumbents: Hedge against soy milk substitution in Southeast Asia by securing California walnut offtake agreements and expanding UHT aseptic capacity for convenience store channels. Reinforce barista-grade positioning through direct relationships with Luckin Coffee and % Arabica regional procurement hubs. Backward integration into Xinjiang crushing infrastructure reduces input volatility exposure.
For New Entrants and Emerging Players: The premium-to-economy price gap in India's tier-one cities offers white-space entry before FSSAI compliance timelines compress. Target Mumbai and Delhi-NCR health-positioned retail with protein-fortified variants exceeding FSSAI minimums. Pursue direct-to-consumer subscription models through Tmall and JD.com to bypass slotting fee barriers at Hema Fresh and Yonghui Superstores.
For Investors and Strategic Acquirers: Exit pathways concentrate in dairy conglomerates seeking plant-based diversification and nut-processing specialists with upstream sourcing control. The 5-10 year viability window favors processors with captive walnut supply and aseptic packaging capacity. Watch FSSAI enforcement intensity in India as inflection signal for regulatory-compressed consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Walnut Crushing | Captive Xinjiang supply reduces climate volatility exposure for processors. |
| Aseptic Packaging Capacity Expansion | Tetra Pak qualification unlocks convenience store channels beyond cold-chain constraints. |
| Barista-Grade Formulation Development | Foaming stability certification opens Luckin Coffee and % Arabica procurement hubs. |
| FSSAI Compliance Pre-Investment | Early protein content reformulation captures Mumbai and Delhi-NCR health retail. |
| Organic Certification Pipeline Buildout | JAS and NASAA credentials command shelf price multiples in Japanese and Australian networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant-based beverage R&D directors, foodservice procurement officers at regional cafe chains, supermarket category buyers, and nut-processing facility managers combined with SAMR GB standard documents, FSSAI circulars, and Japan's METI agricultural product standards. Bottom-up volume modeling from processor capacity and top-down demand triangulation from retail channel audits cross-validated projections.
Data-stream reconciliation across production surveys, import-export manifests, and channel inventory audits shaped the analytical framework. Segmentation dimensions modeled include product type, distribution channel, end-use application, and packaging technology across the projection horizon. CAGRs derived from trend extrapolation of protein beverage adoption curves and foodservice non-dairy menu penetration rates, with walnut input cost indices and aseptic packaging investment cycles as industry-specific forecast inputs.
Inputs from SAMR, FSSAI, and METI regulatory databases were available through the study window; gaps in real-time foodservice procurement contract terms introduce uncertainty bands around channel share assumptions. Forecasts reflect documented assumptions about climate yield stability and certification adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Almond Milk Market