
 Vegan Coffee Creamer Market | 2026-2036
Vegan Coffee Creamer Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Coffee Creamer Market Insights
Buyer concentration among vegan coffee creamer consumers is broadening from niche health-food shoppers toward mainstream grocery buyers and foodservice operators. Califia Farms leverages its refrigerated supply chain dominance to secure shelf space in conventional supermarkets. Nutpods sustains its position through specialized barista-formulated products targeting café accounts. Oatly anchors growth with its oat-base technology leadership and European manufacturing scale.
Vegan coffee creamer denotes a plant-derived emulsion formulated to replicate the mouthfeel, whitening capacity, and thermal stability of conventional dairy cream in coffee applications, typically containing 5-15% fat from hydrolyzed oat, coconut, or almond substrates alongside stabilizers such as gellan gum or lecithin. Oat milk creamers lead volume due to their neutral flavor profile and superior foamability, while coconut cream commands premium positioning in specialty channels where richness differentiates the product. Almond milk variants occupy mature, price-competitive territory with thinning margins, and soy cream competes primarily in value-oriented retail tiers where allergen concerns have constrained expansion.
The FDA's plant-based labeling framework and the USDA's organic certification requirements shape formulation transparency and ingredient sourcing standards across North American supply chains. EFSA's novel food assessments and the EU Green Deal's agricultural emissions targets influence European oat and almond sourcing protocols. Stakeholders must monitor evolving allergen disclosure mandates and carbon accounting rules that will determine which base ingredients and packaging formats retain market access.
Market Dynamics
The vegan coffee creamer market pivots on oat-base formulation advances that have displaced almond and soy substrates in premium applications, while FDA labeling guidance forces transparency claims that reshape competitive positioning across retail and foodservice channels.
Growth Catalysts
- Oat hydrolysis technology:Enzymatic processing of oat starches delivers superior foam stability and neutral flavor profiles that specialty coffee chains now specify in procurement contracts.
- USDA organic certification:Federal organic standards drive ingredient sourcing transparency, compelling suppliers to document non-GMO oat and coconut supply chains for retail placement.
- Foodservice channel expansion:Independent cafés and regional coffee chains are converting dairy equipment to dedicated plant-based systems, creating captive demand for barista-formulated creamers.
Market Restraints
- Oat protein concentrate shortages:Limited North American milling capacity for food-grade oat protein creates input cost volatility and forces reformulation with lower-performance substrates.
- EFSA novel food assessments:European safety evaluations for emerging plant proteins delay product launches by 18-24 months, compressing first-mover advantages for new entrants.
- Dairy cream price competitiveness:Conventional fluid cream maintains cost advantages in institutional foodservice, particularly in price-sensitive contract catering and vending channels.
Strategic Opportunities
- Carbon labeling mandates:The EU Green Deal's agricultural emissions accounting rules will favor oat and pea-based creamers with verified low-carbon supply chains, creating premium positioning.
- Direct-to-café distribution:Bypassing traditional distributors, manufacturers can build recurring revenue through subscription replenishment models with independent coffee shops.
- Precision fermentation lipids:Convergence of microbial fermentation and enzymatic esterification enables custom fat profiles that replicate dairy mouthfeel without agricultural land use.
Industry Challenges
- Food technologist scarcity:Formulation expertise in plant protein stabilization and emulsion science commands premium salaries, constraining R&D expansion at mid-tier manufacturers.
- Clean-label certification timelines:Non-GMO Project and Certified Vegan audits require 12-18 month validation cycles that delay seasonal product launches and reformulations.
- Legacy dairy equipment retrofitting:Shared processing lines demand extensive allergen cleaning protocols that extend changeover times and reduce effective plant capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Coffee Creamer Market |
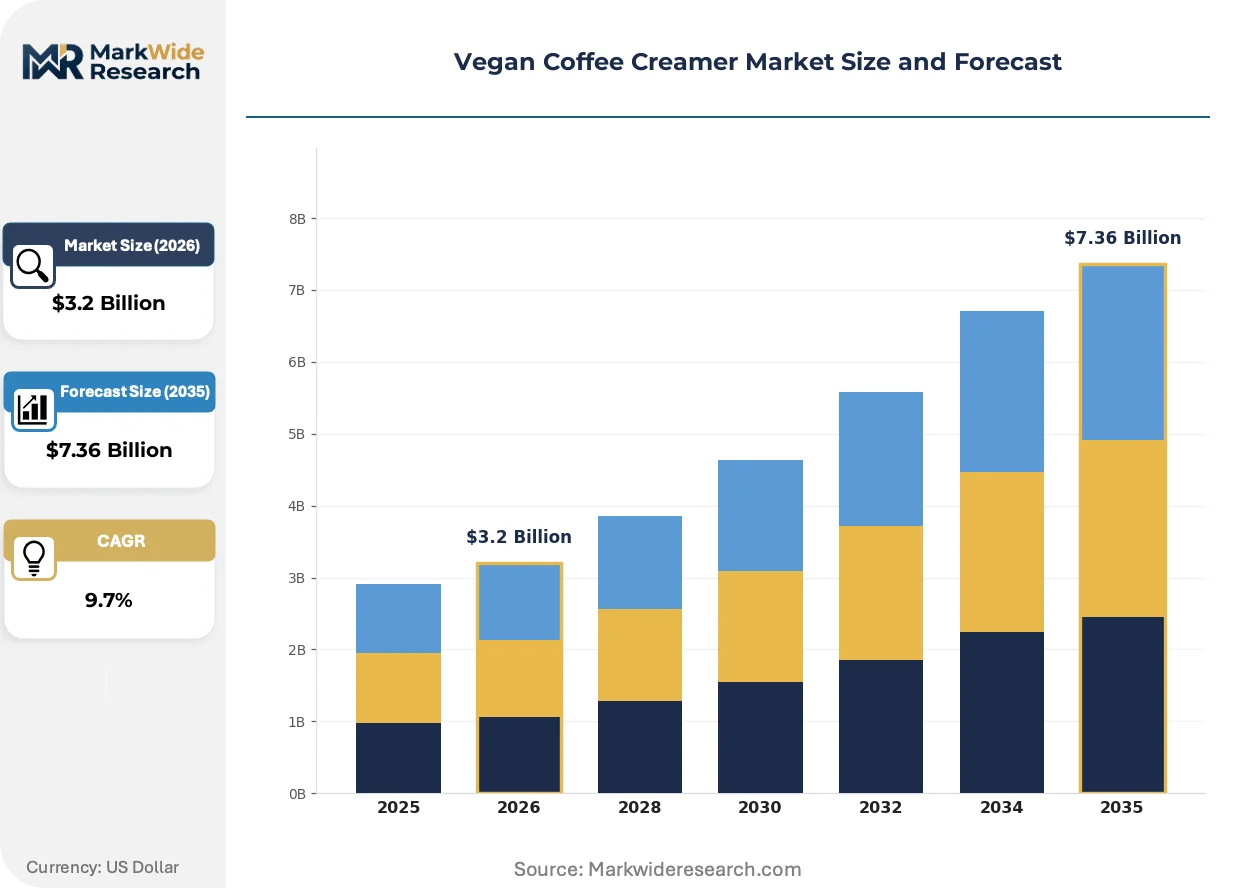
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $7.36 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Cream, Almond Milk, Oat Milk, Soy Cream Flavors: Vanilla, Hazelnut, Chocolate, Unsweetened Packaging Type: Cartons, Bottles, Pouches, Jars Distribution Channel: Supermarkets, Online Retail, Health Stores, Specialty Shops |
| Companies Covered | Califia Farms, Nutpods, Planet Oat, Silk, Danone, So Delicious, Ripple Foods, Oatly, Laird Superfood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Coffee Creamer Market Trends and Innovations
Formulation science and regulatory transparency requirements are compressing product development cycles while reshaping how manufacturers communicate ingredient provenance to skeptical buyers across retail and foodservice channels.
Enzymatic lipid structuring is unifying the functional gap between plant-derived and dairy fats by creating crystalline networks that withstand thermal shock in hot coffee applications. Major roasters and café chains are accelerating adoption of these structured emulsions in their private-label programs. This unification of performance standards is eroding the historical trade-off between clean-label positioning and functional reliability that constrained earlier-generation products.
REACH chemical safety registrations and the EU Green Deal's deforestation-free supply chain rules are forcing reformulation away from coconut cream sourced from unverified origins. Manufacturers must now document plantation-level traceability or switch to alternative bases. European retail channels are responding by delisting products lacking EUDR-compliant sourcing documentation ahead of enforcement deadlines.
Buyer concentration among institutional foodservice operators is compressing supplier negotiation cycles and demanding outcome-based performance guarantees on foam stability and shelf life. National coffee chains are consolidating vendor lists to three approved suppliers per region, displacing fragmented local distribution. This consolidation is most visible in the United States, where top-50 coffee chains now control over half of foodservice creamer volume and dictate formulation specifications directly.
Vegan Coffee Creamer Market Segmentation
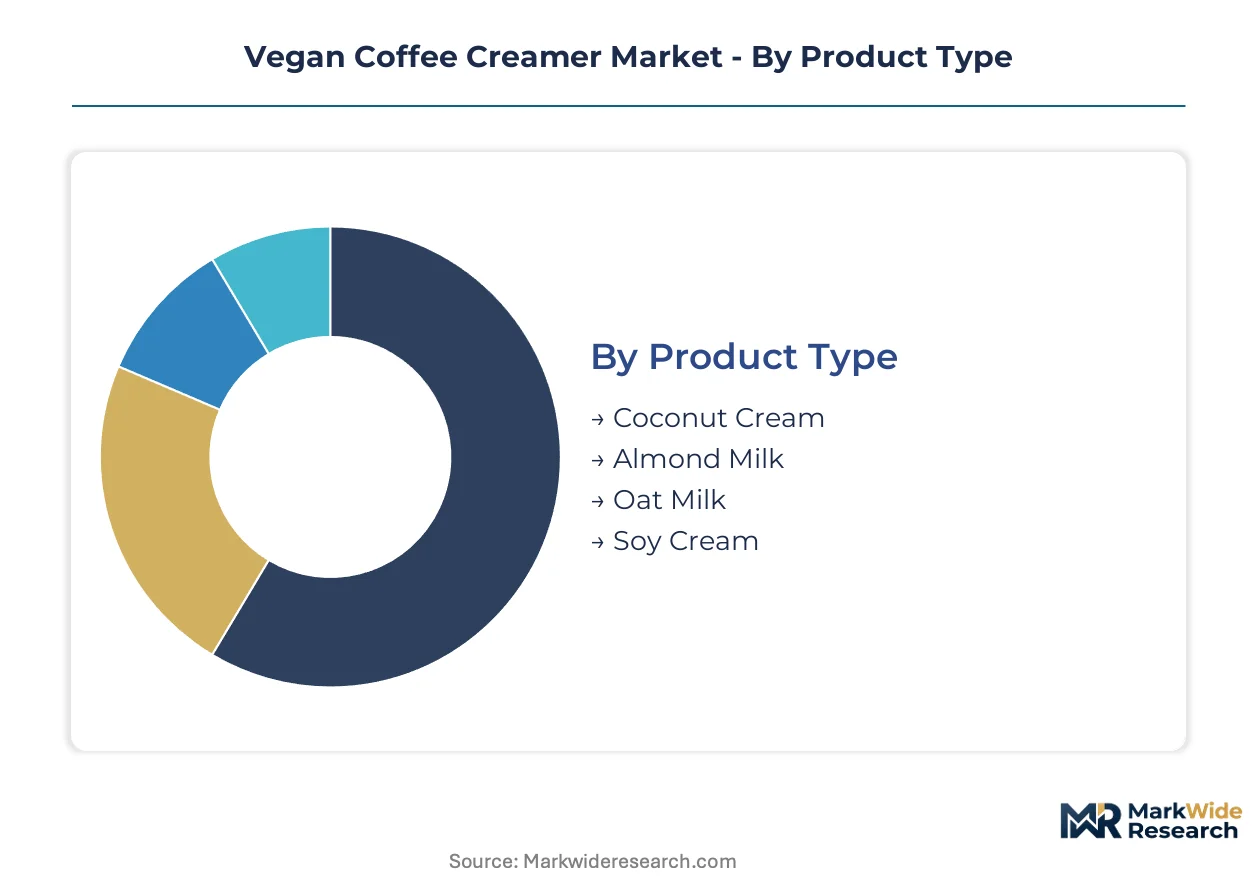
Vegan coffee creamer segmentation reveals how formulation technology, flavor engineering, and channel access determine which products capture household penetration versus foodservice adoption. Understanding these divides exposes where supply investments and procurement priorities concentrate.
Product Type:
Standalone creamer formats dominate retail shelf placement, while barista-formulated concentrates embed into café dispensing systems and commercial equipment.
- Oat Milk:Enzymatically hydrolyzed oat starches deliver neutral flavor and superior microfoam stability that specialty coffee chains specify in procurement contracts. United States retail channels now allocate majority shelf space to oat-base variants as foam performance becomes the primary selection criterion for home baristas.
- Coconut Cream:Higher fat concentration (10-15%) creates richness that commands premium positioning in specialty grocery and direct-to-café channels. REACH chemical safety registrations and EU deforestation-free supply chain rules are forcing plantation-level traceability documentation that raises input costs but secures European retail access.
- Almond Milk:Mature substrate facing margin compression in conventional supermarkets where price competition with private-label alternatives intensifies.
- Soy Cream:Confined primarily to value-tier retail placement due to persistent allergen labeling concerns that constrain foodservice adoption.
Volume placements concentrate in oat milk; the faster expansion belongs to coconut cream as traceability investments unlock premium European positioning.
Flavors:
Flavor selection stratifies by usage occasion intensity, with subtle profiles embedding into daily consumption routines while indulgent variants anchor occasional premium purchases.
- Unsweetened:Clean-label positioning aligns with keto and low-sugar dietary protocols that drive repeat purchase loyalty in United States natural grocery channels. Califia Farms and similar suppliers prioritize unsweetened SKUs for placement in Whole Foods and Sprouts where ingredient minimalism determines shelf access.
- Vanilla:Universal flavor bridge that converts conventional dairy users through familiar taste architecture without alienating palate expectations.
- Hazelnut:European taste preference that gains traction in United States specialty café applications where flavor differentiation supports menu premiumization.
- Chocolate:Seasonal and indulgence-positioned variant with concentrated demand in fourth-quarter retail promotions and limited café beverage programs.
Unsweetened variants command the highest household penetration rates; hazelnut is climbing the fastest as café chains expand flavored latte menus.
Packaging Type:
Packaging selection reflects cold chain infrastructure maturity and consumption velocity, with shelf-stable formats penetrating convenience-oriented channels while refrigerated options anchor quality perception.
- Cartons:Aseptic brick packaging enables ambient distribution that reduces logistics costs and expands retail footprint into convenience stores and vending channels where refrigeration is unavailable.
- Bottles:Refrigerated PET and HDPE formats signal freshness in dairy-alternative sections of conventional supermarkets, with transparent packaging supporting visual quality assessment.
- Pouches:Concentrated and single-serve formats target foodservice dispensing systems and on-the-go consumption occasions where portion control reduces waste.
- Jars:Powdered and ultra-concentrated variants for hospitality and institutional channels where storage efficiency and extended shelf life override convenience premiums.
Cartons hold the broadest retail distribution; pouches are gaining share fastest as café subscription replenishment models expand.
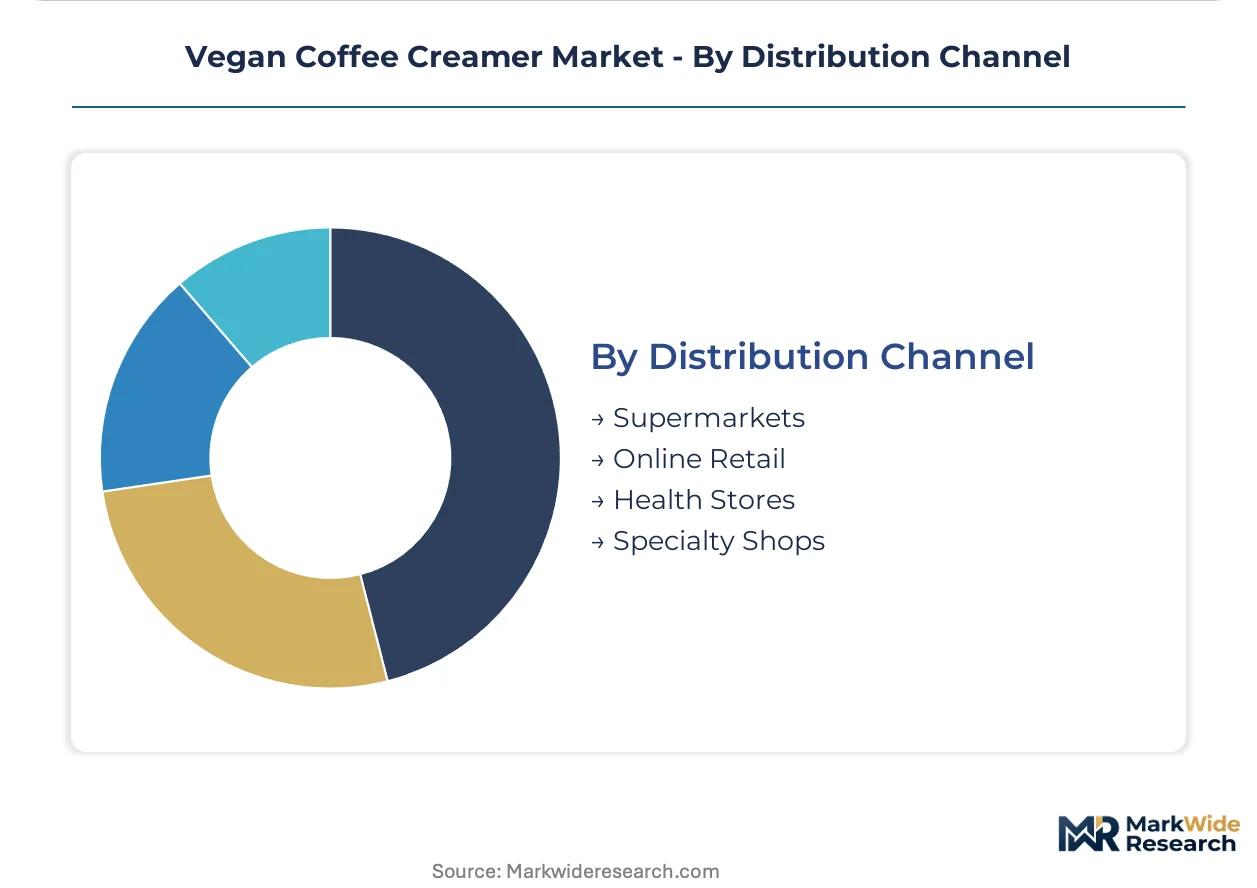
Distribution Channel:
Channel fragmentation reflects divergent buyer sophistication, with mass retail rewarding scale and packaging efficiency while specialty channels prioritize provenance storytelling and formulation transparency.
- Supermarkets:Conventional grocery placement demands slotting fee capacity and refrigerated supply chain compliance that favors established suppliers with national distribution infrastructure.
- Online Retail:Direct-to-consumer and marketplace channels enable subscription replenishment models that build recurring revenue and capture buyer preference data for flavor innovation.
- Health Stores:Natural grocery and co-op channels emphasize organic certification and non-GMO verification that commands price premiums from ingredient-conscious households.
- Specialty Shops:Independent cafés and regional coffee chains require barista-formulated performance guarantees on foam stability and thermal shock resistance.
Supermarkets generate the highest absolute volume; specialty shops deliver the steepest expansion trajectory as café chains consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian oat fields anchor raw material supply for enzymatic hydrolysis plants serving North American creamer manufacturers. Swedish milling technology firms license processing equipment to facilities in Minnesota and Saskatchewan. This geographic concentration of feedstock and processing infrastructure shapes regional competitive dynamics.
United States
Specialty coffee chains in Seattle and Portland drive procurement specifications for foam-stable oat formulations. FDA labeling guidance for plant-based dairy alternatives forces transparency claims that reshape retail shelf positioning. Califia Farms leverages refrigerated distribution infrastructure in California's Central Valley to secure conventional supermarket placement.
Germany
Discounters Aldi and Lidl concentrate private-label creamer volume in Berlin and Hamburg metropolitan areas. REACH chemical safety registrations and EU Green Deal agricultural emissions targets compel documentation of oat and coconut supply chains. Bavarian food technology clusters develop enzymatic lipid structuring for barista-formulated concentrates.
United Kingdom
London's independent café sector demands performance guarantees on thermal shock resistance in plant-based emulsions. EFSA novel food assessments for emerging proteins delay product launches by 18-24 months. Manchester and Birmingham distribution hubs consolidate vendor relationships for regional coffee chain procurement.
Sweden
Oatly's domestic manufacturing scale in Landskrona anchors European oat-base technology leadership. EU deforestation-free supply chain rules under EUDR force plantation-level traceability for coconut sourcing. Stockholm's foodservice operators specify carbon-labeled creamers aligned with national climate targets.
Netherlands
Rotterdam port facilities handle bulk coconut oil imports for creamer manufacturers serving Benelux markets. CSRD corporate sustainability reporting mandates shape ingredient sourcing transparency requirements. Eindhoven food technology institutes collaborate with manufacturers on precision fermentation lipid development.
Vegan Coffee Creamer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and direct-to-café subscription models. The market exhibits tiered concentration with three to five suppliers controlling foodservice procurement contracts for top-50 coffee chains. Strategic archetypes include oat-base technology specialists, refrigerated supply chain dominators, and barista-formulation pure-plays. Competitive moves center on M&A for milling capacity and strategic partnerships with specialty roasters.
Within the oat-base technology tier, Oatly exemplifies European manufacturing scale and enzymatic processing leadership. Califia Farms anchors refrigerated distribution dominance in United States conventional retail channels. Nutpods occupies the barista-formulated specialization position targeting café accounts with performance-guaranteed concentrates.
| Leading Market Players |
|---|
| Califia Farms |
| Nutpods |
| Planet Oat |
| Silk |
| Danone |
| So Delicious |
| Ripple Foods |
| Oatly |
| Laird Superfood |
| Others |
Pricing and Supply Chain Analysis
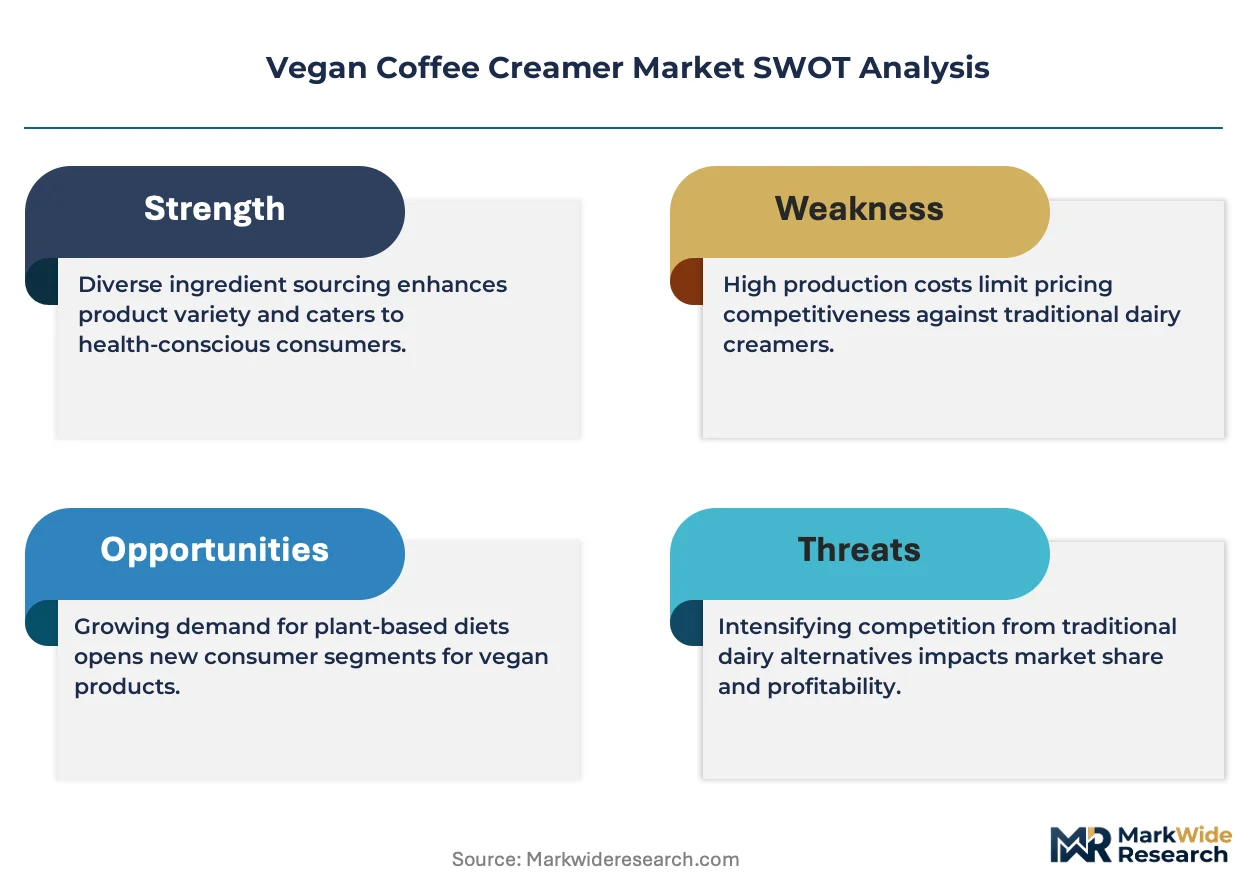
Barista-formulated premium tiers command triple-digit markups over conventional retail variants, a divergence that manifests in divergent supply chain configurations where performance-guaranteed concentrates draw from dedicated enzymatic processing facilities while commodity oat bases source from undifferentiated North American milling pools. FDA labeling transparency requirements and EU deforestation-free supply chain rules add compliance cost layers that concentrate pricing power among suppliers with documented traceability infrastructure.
Pricing Analysis
Performance guarantees on foam stability and thermal shock resistance bundle technical service into barista-formulated SKUs, while conventional retail variants strip out after-sales support to hit mass-market price points. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with USDA organic and non-GMO verification commanding shelf space premiums. Pricing pressure stems from oat protein concentrate shortages that force reformulation with lower-performance substrates. Institutional foodservice operators exhibit highest price sensitivity, while specialty café chains prioritize performance outcomes over per-unit cost.
Supply Chain Analysis
USDA organic and EU organic certification gating restricts supplier pools to documented non-GMO oat and coconut supply chains, compressing qualified vendor bases. Feedstock concentration centers on Canadian prairie provinces for enzymatic-grade oats, with Swedish milling technology licensing processing equipment to Minnesota and Saskatchewan facilities. Coconut oil inputs draw from Southeast Asian plantation networks now subject to EUDR traceability mandates. Single-source vulnerability runs through limited North American food-grade oat protein milling capacity. Distribution runs through refrigerated cold chain infrastructure for conventional retail, with direct-to-café subscription models bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegan coffee creamer market consolidation accelerates as EFSA novel food assessment timelines and clean-label certification cycles force capital-intensive compliance investments that marginalize under-resourced competitors.
For Market Incumbents: Deepen captive supply control over enzymatic oat processing capacity in Canadian prairie corridors to defend against oat protein concentrate volatility. Lock in multi-year procurement contracts with top-50 coffee chains before precision fermentation lipids mature as substitute threats. Prioritize carbon accounting infrastructure to capture EU Green Deal premium positioning. For New Entrants and Emerging Players: Precision fermentation lipid platforms offer technology-first wedge opportunities in barista-formulated concentrates where dairy mouthfeel replication commands price premiums. Target independent café subscription replenishment models in secondary United States metropolitan markets where vendor consolidation has not yet completed. Deploy direct sampling programs to bypass slotting fee barriers in conventional supermarket channels. For Investors and Strategic Acquirers: Re-rating potential sits with barista-formulation pure-plays given foodservice channel consolidation and outcome-based procurement contracting. Long-term viability over the coming decade hinges on defensible enzymatic processing IP and documented low-carbon supply chains. Watch for EUDR enforcement deadlines as inflection triggers for European market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Secures food-grade oat protein supply for foam-stable formulations demanded by specialty coffee chains. |
| Direct-to-Café Subscription Launch | Bypasses distributor markups while capturing recurring revenue from independent coffee shop accounts. |
| Carbon Labeling Certification Program | Aligns product portfolios with EU Green Deal agricultural emissions accounting rules for premium positioning. |
| Precision Fermentation R&D Partnership | Develops custom lipid profiles replicating dairy mouthfeel without agricultural land use constraints. |
| Backward Integration into Oat Milling | Captures margin compression from limited North American food-grade oat protein capacity. |
Research Methodology
Independent corroboration across food technology R&D directors, specialty coffee chain procurement officers, and refrigerated distribution logistics managers underwrites the qualitative findings. Primary interviews with plant-based formulation scientists, café equipment manufacturers, and natural grocery category buyers combined with secondary validation from FDA labeling guidance documents, USDA organic certification databases, and EU EUDR implementation notices. Bottom-up volume modeling triangulates against top-down value projections across oat milk, coconut cream, almond milk, and soy cream substrate categories.
Rate-of-change decomposition separates volume growth from price/mix effects across the analysis window. Segmentation dimensions modeled include substrate technology tier, flavor profile intensity, packaging cold chain requirement, and distribution channel sophistication. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Forecast inputs incorporate oat protein concentrate supply elasticity and precision fermentation lipid development timelines.
Several conditions sit outside the modeled scope, including abrupt shifts in dairy commodity pricing, accelerated precision fermentation regulatory approvals, and trade policy disruptions affecting coconut oil import flows. Forecasts reflect documented assumptions on enzymatic processing yield improvements and café chain vendor consolidation pace. A model refresh is warranted upon material change in EFSA novel food assessment timelines or EUDR enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Soy Milk Powder Market