
 Macadamia Milk Market | 2026-2036
Macadamia Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Macadamia Milk Market Outlook
Australia is narrowing its lead as the dominant processing hub for raw macadamia nut supply, with Queensland's Bundaberg and Gympie corridors attracting capital for wet-milling capacity. Milkadamia leverages its origin-story branding and orchard control to sustain premium positioning across North American natural grocery channels. Califia Farms competes through formulation diversity, extending its barista-blend engineering to macadamia bases for café applications. Suncoast Gold anchors Asia-Pacific distribution through long-standing relationships with Korean and Japanese importers.
Macadamia milk denotes an aqueous emulsion produced from ground macadamia nuts, typically containing two to four percent nut solids, homogenized with stabilizers such as gellan gum or sunflower lecithin to prevent fat separation and achieve a creamy mouthfeel comparable to dairy milk. The product serves as a functional ingredient in espresso beverages, baking formulations, and direct consumption where low-carbohydrate, high-monounsaturated-fat profiles command formulation preference. Unsweetened varieties dominate volume in household channels where sugar-conscious consumers drive repeat purchase, while creamer formats capture margin concentration through specialty coffee shop partnerships that specify foaming performance. Online retail channels represent the fastest-growing distribution pathway, though supermarkets still control the majority of physical shelf space and determine listing fees that shape new entrant viability.
Australia's Food Standards Code, administered by Food Standards Australia New Zealand, governs plant-based milk labeling and protein content claims, directly influencing how manufacturers communicate nutritional equivalence to consumers. The FDA in the United States maintains enforcement discretion on dairy terminology for plant-based alternatives, creating regulatory uncertainty that shapes marketing strategy and litigation exposure for brands operating across jurisdictions. Stakeholders must monitor evolving standards for allergen cross-contamination thresholds and carbon labeling requirements that will determine which producers retain shelf access in premium retail environments.
Market Dynamics
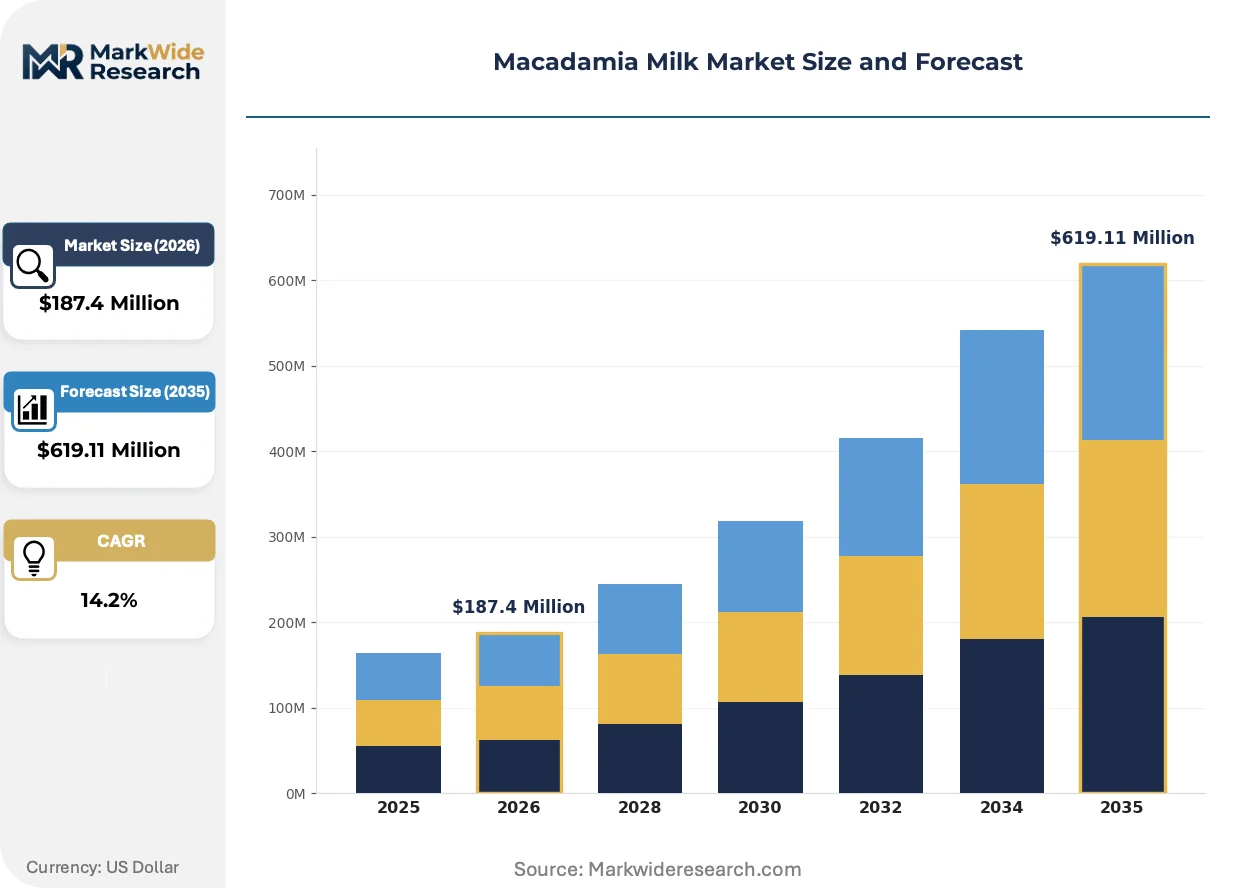
Queensland's wet-milling infrastructure expansion is compressing raw nut-to-beverage lead times, while Australia's Food Standards Code revisions on plant-based labeling are forcing reformulation investments that favor scaled processors with captive orchard supply.
Growth Catalysts
- Specialty coffee channel expansion:Australian café chains are specifying macadamia bases for signature beverages, creating pull-through demand that validates premium positioning in North American and Asian markets.
- FSSAI plant-based standards:India's 2024 notification on dairy analog labeling clarity is opening formal import pathways for Australian processors seeking shelf placement in Mumbai and Bangalore retail.
- Barista-blend engineering:Advances in sunflower lecithin homogenization are delivering foam stability metrics that match oat milk performance in espresso applications.
Market Restraints
- Raw nut supply concentration:Queensland's Bundaberg-Gympie corridor controls over 70% of global macadamia processing, exposing buyers to climate-driven crop volatility and port congestion at Brisbane.
- Input cost volatility:Gellan gum prices fluctuate with microbial fermentation feedstock costs, squeezing margin on unsweetened varieties where stabilizer loads are highest.
- Substitution pressure:Oat milk's manufacturing scale and neutral flavor profile continue capturing shelf space in mass retail, particularly in German and UK supermarkets.
Strategic Opportunities
- South Korean functional positioning:MFDS regulations permit monounsaturated fat content claims that align with local beauty-from-within trends, creating white space for premium SKUs in Seoul's Olive Young and CU convenience chains.
- Carbon labeling tailwinds:Australia's pending mandatory climate disclosure requirements will reward processors with orchard-level traceability, disadvantaging traders without backward integration.
- Creamer format innovation:Single-serve pods for hotel in-room coffee systems represent an underdeveloped channel where foaming performance commands 40-60% price premiums over standard cartons.
Industry Challenges
- Wet-milling talent scarcity:Queensland's processing corridor faces competition from mining and logistics sectors for mechanical and food safety technicians capable of operating aseptic filling lines.
- Cross-contamination certification timelines:BRCGS and FSSC 22000 audits for macadamia-dedicated facilities require 18-24 month validation cycles that delay new entrant market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macadamia Milk Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Creamer, Flavored Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Packaging Type: Bottle, Carton, Tetra Pack, Can End User: Households, Cafes, Restaurants, Food Manufacturers |
| Companies Covered | Milkadamia, Califia Farms, Pacific Foods, Suncoast Gold, Danone, Elmhurst Milked, Giraf Limited, Jindilli Beverages, macamilk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macadamia Milk Market Strategic Shifts
Enzymatic extraction protocols and precision fermentation are rewriting cost curves for nut-based emulsions, while regulatory clarity on carbon accounting is reshaping how origin stories translate to shelf-ready claims.
High-pressure processing is collapsing the traditional roasting-grinding-homogenization sequence into a single continuous flow. Australian processors in Gympie are piloting HPP lines that reduce nut-to-carton time from 72 hours to 8 hours. This compression is enabling just-in-time production for private-label contracts that previously required 30-day inventory buffers.
Australia's Food Standards Code revision on protein equivalence claims is forcing manufacturers to reformulate or reposition. The 2024 amendment requires minimum 3% protein for "milk" analog labeling, pushing processors toward protein-fortified blends or descriptor shifts to "beverage." Queensland-based suppliers with in-house laboratory capabilities are adapting faster than importers relying on third-party testing.
Café procurement is consolidating around performance-specified contracts that unbundle ingredient supply from barista training and equipment placement. Melbourne and Sydney roasters are negotiating direct supply agreements that lock in six-month pricing in exchange for exclusive menu placement. This shift is visible most acutely in Australia's specialty coffee corridor, where roastery-branded macadamia SKUs are displacing multi-brand distributor catalogs.
Macadamia Milk Market Segmentation
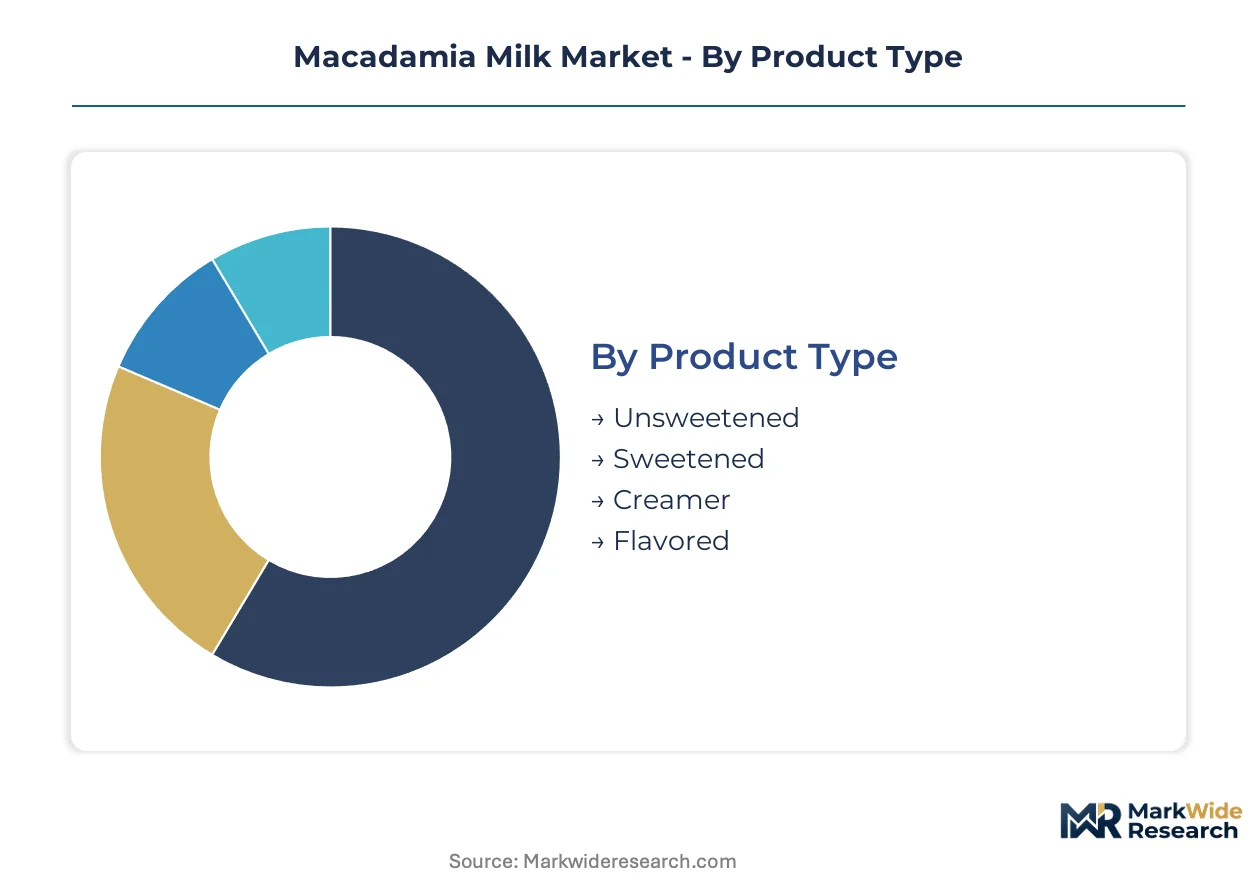
Macadamia milk's commercial structure fragments across formulation chemistry, channel economics, and end-use performance specifications. Each segmentation axis reveals distinct margin profiles and competitive entry barriers that shape processor investment priorities.
Product Type:
Mature SKUs dominate household volume while emerging formats capture specialty channel premiums through functional engineering.
- Unsweetened:Aqueous emulsion containing two to four percent nut solids with no added sugars, stabilized with gellan gum or sunflower lecithin. Queensland processors supply Brisbane supermarkets where sugar-conscious consumers drive repeat purchase velocity. Unsweetened retains volume leadership; creamer holds the steepest expansion curve.
- Sweetened:Formulations incorporating cane sugar, monk fruit, or erythritol to mask macadamia's natural bitterness. Australian café chains in Melbourne and Sydney specify lightly sweetened bases for signature beverages, creating pull-through demand in Asian export markets.
- Creamer:Higher fat concentration engineered for espresso foam stability and latte art performance. Barista-blend specifications from Suncoast Gold and Califia Farms lock in six-month supply contracts with roastery partners.
- Flavored:Vanilla, chocolate, and coffee-infused variants targeting direct consumption occasions. Korean Olive Young and CU convenience chains stock functional-positioned SKUs aligned with local beauty-from-within trends.
Unsweetened retains volume leadership; creamer holds the steepest expansion curve.
Distribution Channel:
Channel selection determines working capital intensity and listing fee exposure for new entrants.
- Online Retail:Direct-to-consumer and marketplace platforms with fastest-growing trajectory among Australian exporters targeting North American natural grocery shoppers. Milkadamia leverages origin-story digital content to sustain premium positioning without mass retail slotting fees.
- Supermarkets:Coles, Woolworths, and Aldi Australia control majority physical shelf space and determine category captaincy through listing fee structures. Brisbane corridor processors with captive orchard supply secure preferential placement during seasonal resets.
- Health Food Stores:Independent natural retailers and regional chains stocking certified organic and non-GMO verified SKUs. Higher margin tolerance supports smaller batch production from Gympie wet-milling facilities.
- Specialty Stores:Gourmet food emporiums and roastery-branded retail capturing experiential consumption occasions. Melbourne and Sydney specialty coffee corridors drive exclusive menu placement agreements.
Supermarkets retain volume leadership; online retail climbs the fastest.
Packaging Type:
Format selection balances shelf stability, logistics cube efficiency, and consumption occasion matching.
- Carton:Aseptic brick packs dominating household channel volume with 12-month ambient shelf life. Queensland processors favor cartons for export containerization efficiency to Korean and Japanese importers.
- Bottle:Refrigerated PET and HDPE formats signaling freshness in premium supermarket dairy cases. Higher logistics cost structure limits distribution radius from Bundaberg processing facilities.
- Tetra Pack:Multi-layer laminate with aluminum barrier for extended shelf stability in tropical climates. Indian FSSAI import pathways favor Tetra Pack for Mumbai and Bangalore retail penetration.
- Can:Single-serve aluminum formats for hotel in-room coffee systems and foodservice portion control. Foaming performance commands 40-60% price premiums over standard carton equivalents.
Carton retains volume leadership; can gains share fastest in hospitality channels.
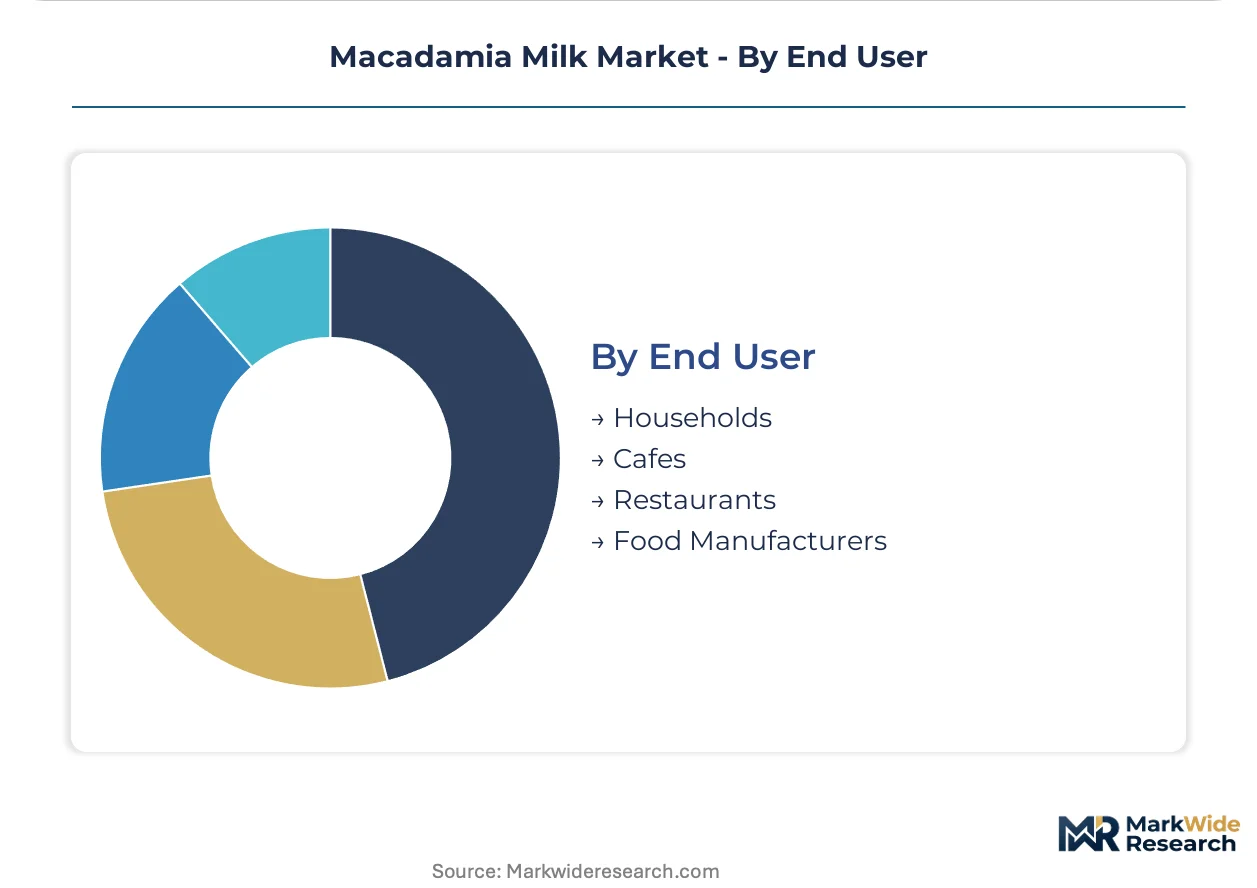
End User:
Demand concentrates in beverage preparation applications where fat emulsion performance determines specification.
- Cafes:Specialty coffee shops specifying macadamia bases for signature beverages and latte art competitions. Direct supply agreements lock in six-month pricing in exchange for exclusive menu placement.
- Households:Direct consumption and home baking applications where low-carbohydrate, high-monounsaturated-fat profiles command formulation preference. Unsweetened varieties dominate repeat purchase in sugar-conscious segments.
- Restaurants:Fine dining and casual dining operators incorporating macadamia milk into dessert and sauce applications. Brisbane and Sydney restaurant groups source through broadline distributors with just-in-time delivery requirements.
- Food Manufacturers:Industrial ingredient buyers for ice cream, yogurt, and bakery mix formulations. Protein-fortified blends meet Australia's Food Standards Code minimum 3% protein threshold for milk analog labeling.
Households retain volume leadership; cafes hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's Bundaberg-Gympie corridor processes over 70% of global macadamia supply, compressing nut-to-beverage lead times and anchoring wet-milling investment. This concentration exposes downstream buyers to climate volatility and Brisbane port congestion. Four countries concentrate demand and regulatory momentum.
United States
Specialty coffee chains in Los Angeles and New York specify macadamia bases for signature beverages, validating premium positioning. The FDA maintains enforcement discretion on dairy terminology for plant-based alternatives, creating regulatory uncertainty that shapes marketing strategy. Califia Farms and Milkadamia compete through formulation diversity and origin-story branding across natural grocery channels.
Australia
Food Standards Australia New Zealand revised the Food Standards Code in 2024, requiring minimum 3% protein for "milk" analog labeling and forcing reformulation investments. Queensland's processing corridor attracts capital for wet-milling capacity expansion near Bundaberg. Melbourne and Sydney roasters negotiate direct supply agreements locking in six-month pricing for exclusive menu placement.
South Korea
MFDS regulations permit monounsaturated fat content claims that align with Seoul's beauty-from-within consumption trends. Olive Young and CU convenience chains stock functional-positioned SKUs targeting premium urban consumers. Korean importers maintain long-standing relationships with Australian processors for Tetra Pack distribution efficiency.
India
FSSAI's 2024 notification on dairy analog labeling clarity opens formal import pathways for Mumbai and Bangalore retail penetration. Sugar-conscious consumers in metropolitan centers drive repeat purchase of unsweetened varieties. Australian exporters favor Tetra Pack formats for tropical climate shelf stability in Indian distribution.
Japan
Health-conscious consumers in Tokyo and Osaka prioritize low-carbohydrate, high-monounsaturated-fat profiles in household channels. METI standards on carbon labeling are reshaping how origin stories translate to shelf-ready claims. Japanese importers source through established Asia-Pacific distribution relationships anchored by Queensland supply.
Macadamia Milk Market Competitive Environment
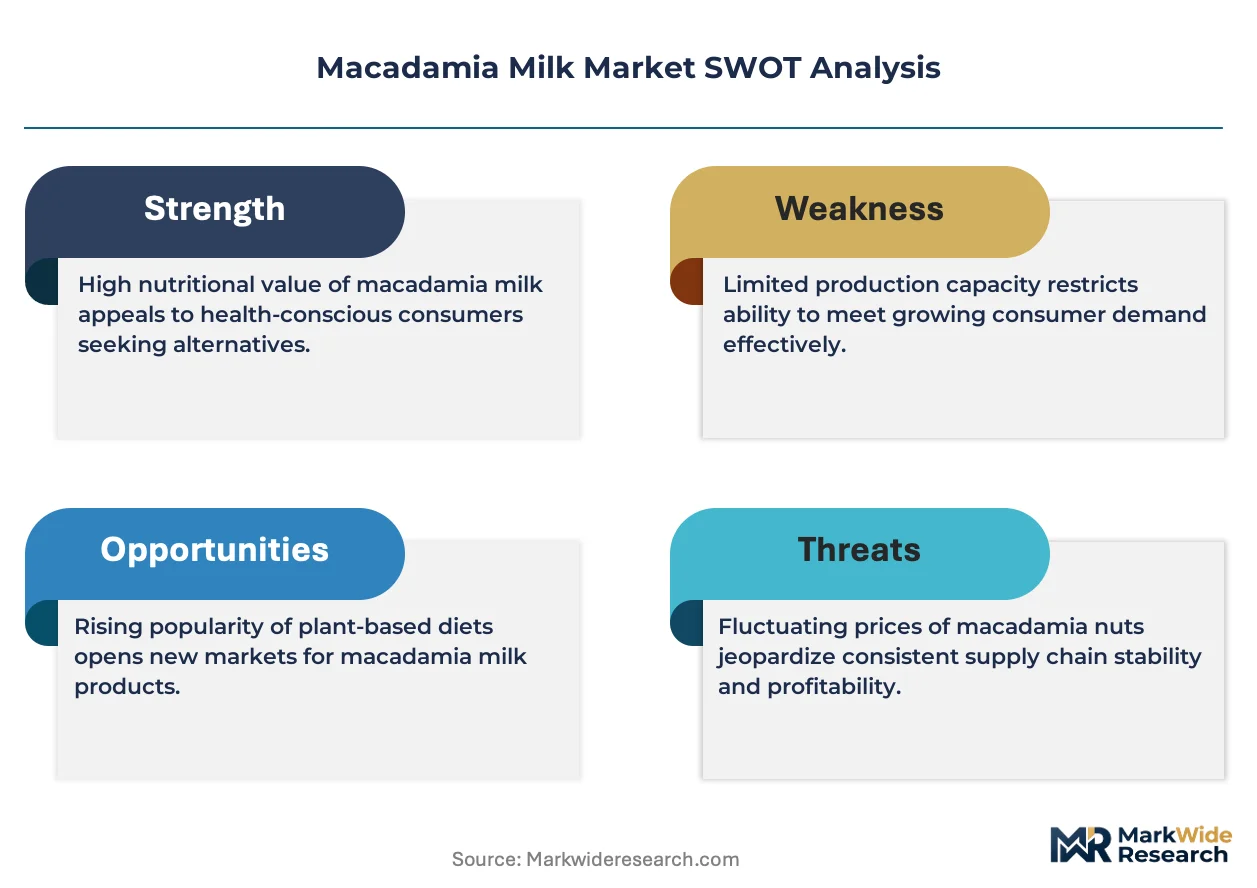
Platform integrators command the system tier; component specialists sit upstream. The macadamia milk market structures around orchard-controlled processors with captive supply and formulation-engineered brands competing through barista-performance specifications. Three archetypes dominate: origin-story marketers with backward integration into Queensland orchards, formulation diversifiers extending oat-milk engineering expertise, and private-label suppliers leveraging Queensland's wet-milling capacity compression. Competitive moves concentrate on exclusive café supply contracts and protein-fortified reformulation to meet Australia's revised labeling standards.
Among Australia-based orchard-integrated processors, Milkadamia and Suncoast Gold exemplify the origin-story archetype, leveraging Queensland supply control to sustain premium positioning. Califia Farms represents the formulation-diversification approach, extending barista-blend engineering capabilities developed in oat milk into macadamia bases. These three anchors illustrate how competitive advantage splits between supply security and performance specification.
| Leading Market Players |
|---|
| Milkadamia |
| Califia Farms |
| Pacific Foods |
| Suncoast Gold |
| Danone |
| Elmhurst Milked |
| Giraf Limited |
| Jindilli Beverages |
| macamilk |
| Others |
Value Chain & Pricing Dynamics
Queensland's Bundaberg-Gympie corridor controls over seventy percent of global macadamia processing, anchoring margin capture upstream while downstream pricing power fragments across formulation tiers and channel access. Wet-milling capacity scarcity near Brisbane compresses raw nut-to-beverage lead times, concentrating value extraction with orchard-integrated processors and forcing traders to absorb logistics volatility.
Pricing Analysis
Australia's Food Standards Code dictates the pricing tier structure through its protein equivalence thresholds and labeling compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates origin-certified barista blends from private-label commodity cartons and import-dependent economy SKUs. Price differentiation rests on certification grade and captive orchard supply, with unsweetened household varieties facing the sharpest margin compression due to stabilizer cost volatility. Specialty coffee channels exhibit the lowest price sensitivity, while mass retail supermarkets drive hardest on listing fee negotiations.
Supply Chain Analysis
Climate-driven crop volatility in Queensland exposes buyers to supply disruption, with Brisbane port congestion compounding lead time uncertainty. Raw nut supply draws from Australia, South Africa, and Kenya, while gellan gum and sunflower lecithin feedstock dependencies tether formulation costs to microbial fermentation and oilseed markets. Single-source vulnerability concentrates in Queensland's wet-milling infrastructure, where aseptic filling line capacity limits new entrant access. Distribution runs through roastery direct agreements, supermarket category captains, and Asia-Pacific import relationships with Korean and Japanese distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Macadamia milk sits at an inflection where enzymatic extraction and precision fermentation are collapsing cost curves, while Australia's protein-labeling mandates are forcing rapid reformulation investment that favors scaled processors.
For Market Incumbents: Insulate margin position through backward integration into Queensland orchard assets and captive wet-milling capacity, locking in supply security against climate volatility. Accelerate barista-blend certification investments to defend specialty coffee channel access against oat milk substitution pressure. Prioritize direct supply agreements with Melbourne and Sydney roasters that exchange six-month pricing locks for exclusive menu placement. For New Entrants and Emerging Players: Build out South Korean functional positioning through MFDS-compliant monounsaturated fat claims targeting Seoul's beauty-from-within retail channels, where premium SKUs command shelf space at Olive Young and CU convenience chains. Target India's FSSAI-cleared import pathway with Tetra Pack formats for Mumbai and Bangalore metropolitan penetration, exploiting labeling clarity that Australian exporters are still navigating. Lead with carbon-traceability storytelling to differentiate against established players lacking orchard-level disclosure. For Investors and Strategic Acquirers: Capital is best deployed toward orchard-integrated processors with Queensland wet-milling assets and in-house laboratory capabilities for rapid reformulation compliance. Long-term viability favors backward-integrated archetypes over trading-dependent brands exposed to raw nut price volatility. Watch Australia's mandatory climate disclosure implementation as the signal for which processors will retain premium retail access.| Strategic Initiative | Industry Significance |
|---|---|
| Orchard Backward Integration | Captive supply secures margin pool concentration against Queensland climate volatility. |
| Barista-Blend Certification | Foam stability specifications unlock exclusive café supply contracts with Melbourne roasters. |
| Enzymatic Extraction Scale-Up | High-pressure processing lines compress nut-to-carton time for just-in-time private-label production. |
| Carbon Labeling Compliance | Australia's pending mandatory disclosure rewards processors with orchard-level traceability systems. |
| South Korean Functional Positioning | MFDS fat-content claims align with Seoul beauty-from-within trends at Olive Young retail. |
Study Parameters
Desk research of trade flow databases, Food Standards Australia New Zealand regulatory filings, and Asia-Pacific import customs records preceded structured interviews with wet-milling plant managers, specialty coffee roaster procurement leads, supermarket category buyers, and Korean distributor import specialists. Primary fieldwork across Queensland's Bundaberg-Gympie corridor validated capacity expansion timelines and orchard supply concentration. Secondary sources included FSSAI notification documents, MFDS labeling guidelines, and café equipment manufacturer specification sheets. Bottom-up volume modeling triangulated against top-down category spend estimates.
Forecast assumptions held fixed the current regulatory enforcement posture of FDA, FSSAI, and Food Standards Australia New Zealand across the analysis window, while varying raw nut yield scenarios and stabilizer input cost bands. Segmentation dimensions modeled included formulation chemistry, distribution channel economics, packaging format logistics, and end-use performance specifications. CAGRs derived from spline interpolation of annual volume estimates, with cross-validation against historical oat milk and almond milk adoption curves. Industry-specific inputs incorporated Brisbane port throughput capacity and aseptic filling line installation lead times.
Stress conditions across Queensland drought frequency, gellan gum fermentation feedstock availability, and FSSAI import clearance timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and specialty coffee channel expansion velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Germany Dairy Alternatives Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
North America Non-Dairy Milk Market