
 Low Fat Coconut Milk Market | 2026-2036
Low Fat Coconut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Coconut Milk Market Analytics
Cold-press extraction and aseptic packaging is tilting production economics toward fresher-tasting, longer-shelf-life formats that bypass traditional retort processing. Thai Coconut Public Company Limited leverages integrated plantations and processing facilities in Samut Sakhon to control raw material flow. Silk anchors its position through refrigerated distribution partnerships with mainstream grocers across the United States. The Hain Celestial Group differentiates via organic certification density and specialty channel placement in natural foods retail.
Low fat coconut milk denotes coconut extract with reduced fat content, typically achieved through centrifugal separation to yield 5-8% fat compared to 17-24% in standard coconut milk, then standardized with water and stabilizers for consistent viscosity in cooking and beverage applications. Organic product type commands premium shelf positioning and tighter supply contracts as certification requirements constrain eligible sourcing regions. Online retail distribution is accelerating fastest among channels, though supermarkets still dominate absolute volume throughput due to impulse purchase behavior and established dairy-alternative planogram placement.
FDA labeling standards for plant-based milk alternatives and EFSA health claim protocols for saturated fat reduction shape product positioning and permissible marketing language in core export markets. Thailand's Ministry of Commerce and Board of Investment administer export quality grading and processing facility registration that determines market access eligibility for international buyers. Stakeholders must monitor evolving regulatory divergence between jurisdictions on acceptable fortification levels and nomenclature rules for coconut-derived beverages labeled as milk alternatives.
Market Dynamics
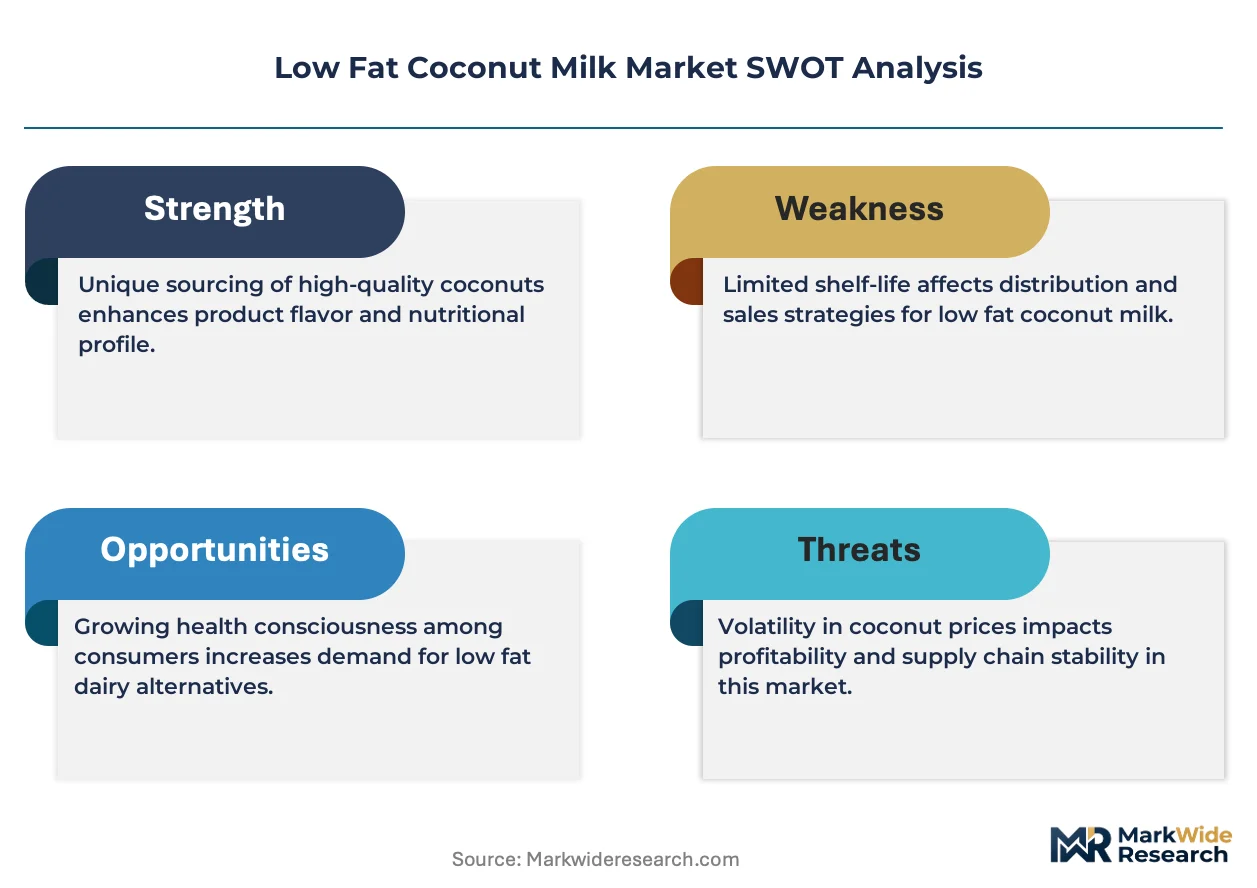
Centrifugal separation technology is compressing production costs for 5-8% fat coconut milk while FDA and EFSA clean-label mandates are eliminating synthetic stabilizers from export-grade formulations.
Growth Catalysts
- ASEAN Export Grading Protocols:Thailand's Ministry of Commerce quality tiers unlock preferential shelf placement in EU and US retail chains for certified processors.
- Plant-Based Beverage Manufacturing:North American dairy alternative producers are expanding low fat coconut milk procurement as a neutral-flavor base for barista and cooking applications.
- Cold-Press Extraction Methods:Non-thermal processing preserves volatile aromatic compounds that retort sterilization degrades, creating taste differentiation in premium segments.
Market Restraints
- Raw Material Concentration:Over 60% of global copra supply originates from Philippine and Indonesian smallholder cooperatives with weather-dependent yield volatility.
- FDA Nomenclature Restrictions:Plant-based milk alternative labeling standards limit health claim language and create compliance costs for cross-border marketing.
- Technical Viscosity Limits:Fat reduction below 6% compromises emulsion stability without hydrocolloid additives, conflicting with clean-label positioning.
Strategic Opportunities
- Online Retail Channel Expansion:Direct-to-consumer subscription models bypass supermarket slotting fees and capture recurring revenue from specialty diet adherents.
- EU Green Deal Alignment:Organic certification density qualifies processors for preferential procurement under corporate sustainability purchasing mandates.
- Functional Beverage Convergence:Fortification with MCT oil and protein isolates positions low fat coconut milk within sports nutrition and ketogenic diet verticals.
Industry Challenges
- Organic Certification Timelines:Three-year conversion periods for conventional coconut plantations constrain eligible supply for premium contract volumes.
- Aseptic Packaging Capital Requirements:Cold-fill line investments exceed $4 million per installation, creating entry barriers for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Coconut Milk Market |
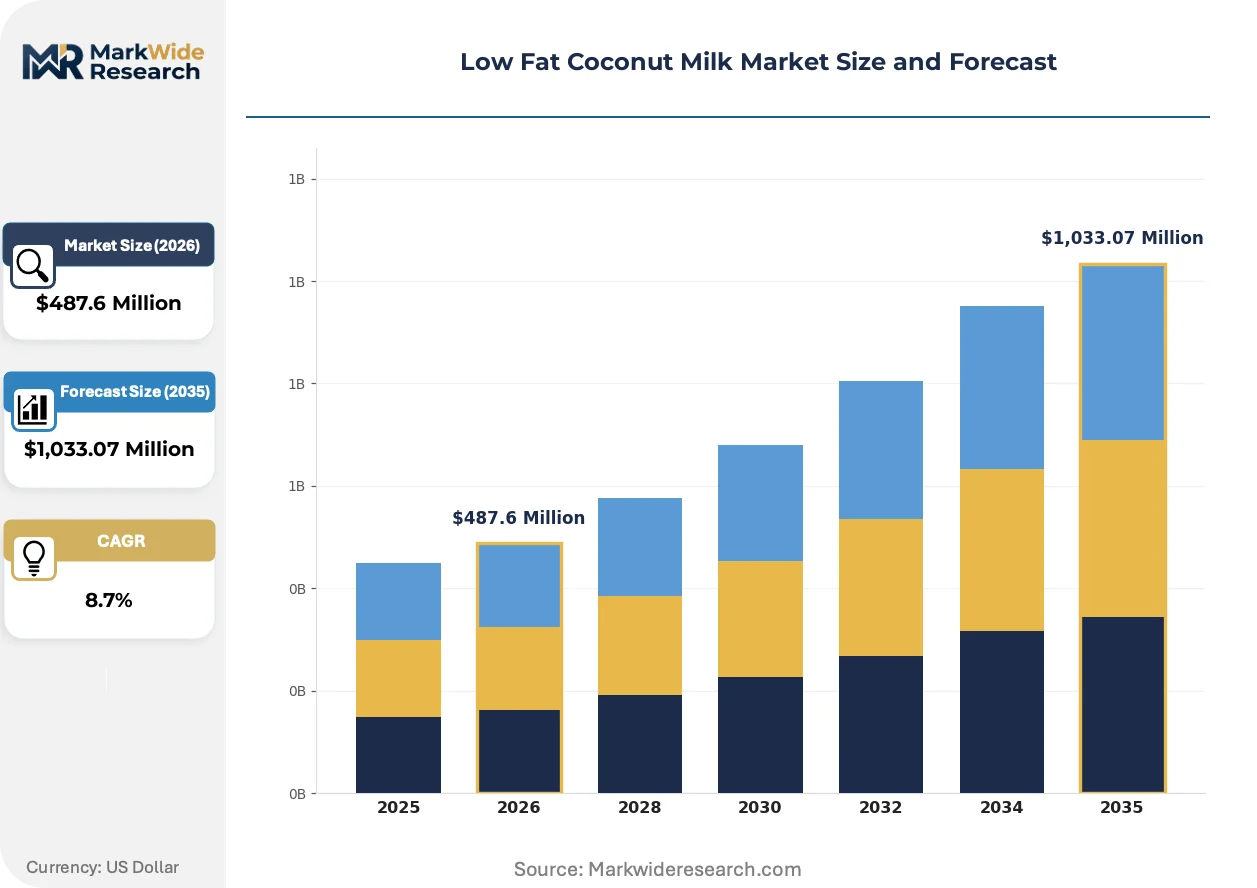
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Flavored, Unsweetened Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops End User: Households, Food Service Providers, Beverage Manufacturers, Dairy Alternatives Packaging Type: Cartons, Cans, Bottles, Pouches |
| Companies Covered | Thai Coconut Public Company Limited, Silk (Whitewave), Pureharvest, GraceKennedy Limited, AroyD, Thai Agri Foods Public Company Limited, So Delicious Dairy Free, Pacific Foods, The Hain Celestial Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Coconut Milk Market Evolving Landscape
Processing technology convergence and regulatory stringency are bifurcating the market into commodity retort-stable supply and premium cold-chain-dependent formats with divergent margin structures.
High-pressure processing is hybridizing with aseptic filling to extend refrigerated shelf life without thermal degradation of flavor volatiles. Specialty coffee chains and natural foods retailers are adopting these formats at 15-20% price premiums to standard UHT products. The technology is hybridizing supply chain requirements, forcing investments in cold distribution infrastructure that exclude traditional dry-grocery wholesalers.
EFSA health claim protocols for saturated fat reduction are restricting permissible marketing language on coconut-derived beverages sold in EU member states. Processors must reformulate to sub-1.5% saturated fat thresholds or abandon cardiovascular health positioning entirely. Organic and specialty channel brands are responding by pivoting toward sustainability and origin storytelling rather than nutritional claims.
Refrigerated distribution partnerships are displacing ambient shelf-stable procurement in mainstream US grocery. Retailers are consolidating dairy-alternative planogram space behind brands with proven velocity and consistent cold-chain performance. This concentration is most visible in coastal metropolitan markets where natural foods retail penetration exceeds national averages by 40 percentage points.
Low Fat Coconut Milk Market Segmentation
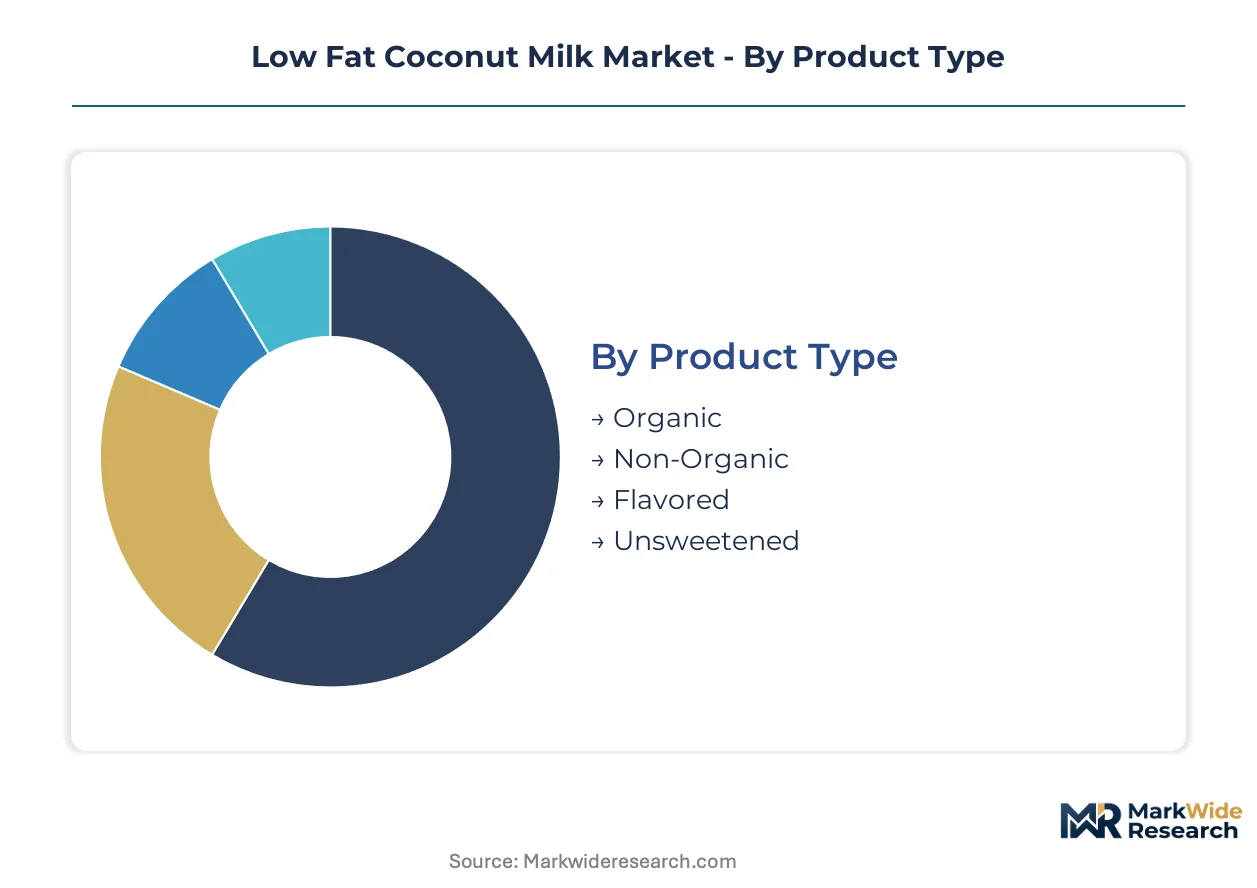
Segmentation in low fat coconut milk reveals how procurement patterns diverge between commodity food service supply and premium retail positioning. Each dimension—product certification, channel access, end-use application, and packaging format—creates distinct margin profiles and supply chain requirements that processors must navigate simultaneously.
Product Type:
Mature conventional segments coexist with emerging certified and functional variants across the product spectrum.
- Organic:Certification under USDA Organic or EU Organic regulations restricts sourcing to plantations completing three-year conversion periods. Thai processors in Samut Sakhon and Ratchaburi provinces command premium contract pricing from North American natural foods retailers who face corporate sustainability purchasing mandates.
- Non-Organic:Conventional low fat coconut milk derived from standard plantation supply dominates institutional procurement and private-label manufacturing. Philippine and Indonesian smallholder cooperatives feed this segment with price-sensitive bulk supply.
- Flavored:Vanilla and chocolate variants target beverage manufacturers seeking neutral dairy-alternative bases with built-in taste profiles.
- Unsweetened:Zero-added-sugar formulations align with ketogenic diet protocols and clean-label positioning in specialty channels.
Non-Organic handles the majority of throughput; Organic is expanding most quickly on share.
Distribution Channel:
Channel economics separate high-velocity ambient supply from cold-chain-dependent premium placement.
- Supermarkets:Established dairy-alternative planogram placement drives impulse purchases through ambient UHT formats. Slotting fees and velocity requirements favor processors with proven refrigerated distribution partnerships.
- Online Retail:Direct-to-consumer subscription models bypass traditional wholesaler markups and capture recurring revenue from specialty diet adherents. Cold-chain logistics integration remains the critical capability gap.
- Health Food Stores:Independent natural foods retailers prioritize organic certification density and origin storytelling over price competition.
- Specialty Shops:Asian grocery chains and gourmet food retailers stock Thai-imported canned formats for cooking applications.
Supermarkets anchor absolute volume throughput; Online Retail is climbing the fastest on share.
End User:
Demand fragmentation splits between household consumption patterns and industrial-scale ingredient procurement.
- Households:Retail-packaged cartons and cans serve home cooking and direct consumption. Clean-label requirements under FDA guidance shape permissible additive content.
- Beverage Manufacturers:North American plant-based beverage producers source low fat coconut milk as a neutral-flavor base for barista and ready-to-drink applications.
- Food Service Providers:Restaurants and institutional kitchens prioritize cost-stable canned supply with extended shelf life.
- Dairy Alternatives:Specialized processors blend coconut milk with oat, almond, or pea protein for hybrid dairy-alternative formulations.
Households represent the largest addressable base; Beverage Manufacturers are gaining share fastest.
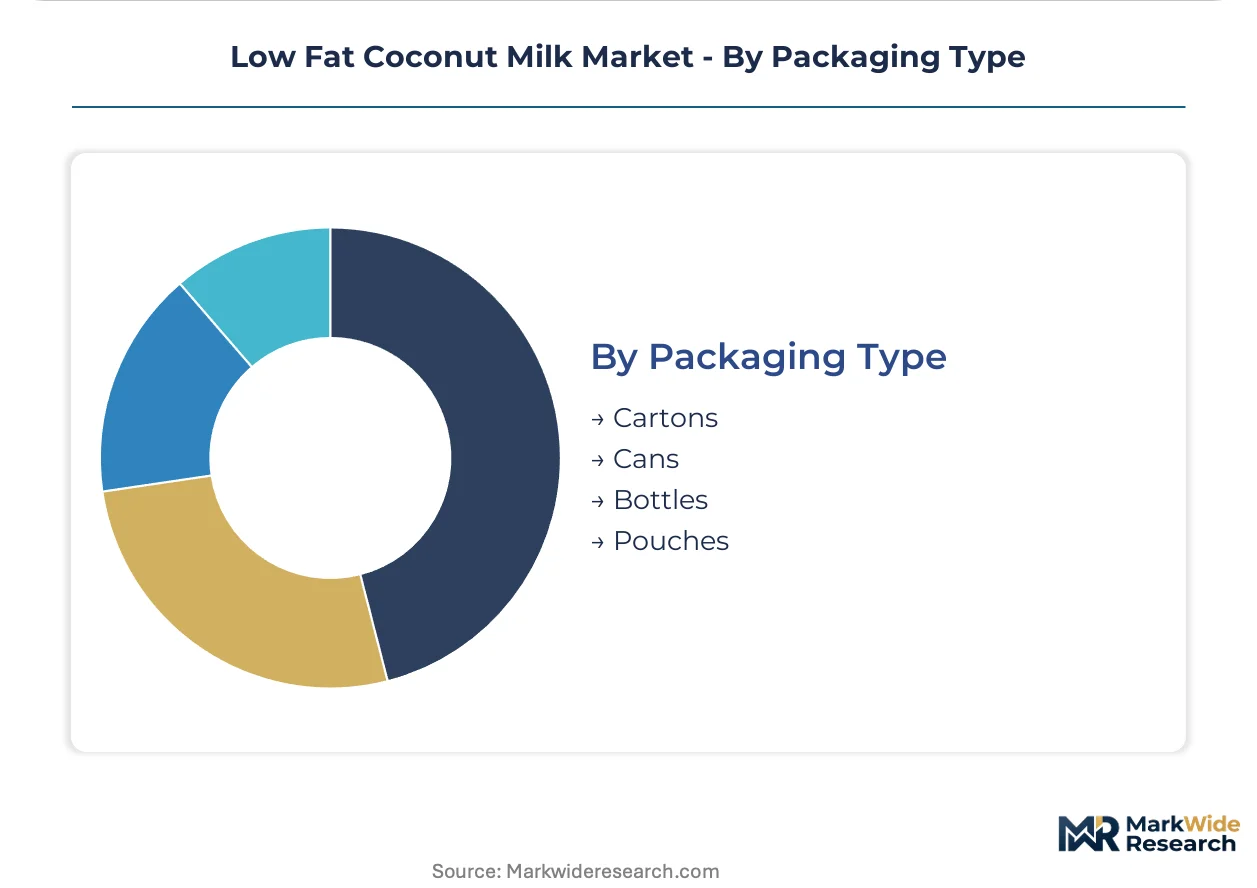
Packaging Type:
Packaging technology divides the market between retort-stable legacy formats and cold-chain premium positioning.
- Cartons:Aseptic carton filling enables extended shelf life without refrigeration for ambient retail distribution. Tetra Pak and SIG Combibloc equipment dominates installed capacity.
- Cans:Traditional tinplate cans remain the default for food service and export markets requiring tropical climate resilience.
- Bottles:Refrigerated PET and HDPE bottles serve fresh-tasting premium segments in coastal US metropolitan markets.
- Pouches:Flexible stand-up pouches reduce shipping cube and target single-serve convenience applications.
Cartons command the dominant throughput position; Bottles are expanding most steeply in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plant-based beverage manufacturers in the United States drive the largest import demand for low fat coconut milk as a dairy-alternative base, while Thai processors control upstream supply through integrated plantation and processing infrastructure.
United States
Mainstream grocers in coastal metropolitan markets consolidate dairy-alternative planogram space behind cold-chain-proven brands. FDA labeling standards for plant-based milk alternatives constrain permissible health claim language on coconut-derived beverages. Refrigerated distribution partnerships in California and New York Metro anchor premium product placement.
Thailand
Samut Sakhon and Ratchaburi provinces host integrated plantation-processing clusters that supply certified organic volumes to North American natural foods retailers. Thailand's Ministry of Commerce administers export quality grading that determines EU and US retail access eligibility. Board of Investment incentives support aseptic packaging line investments exceeding four million dollars per installation.
Germany
Specialty coffee chains and natural foods retailers adopt cold-chain-dependent formats at price premiums to standard UHT products. EFSA health claim protocols for saturated fat reduction restrict cardiovascular positioning on coconut-derived beverages. Hamburg and Berlin distribution hubs concentrate organic-certified import volumes for EU-wide redistribution.
Indonesia
Smallholder cooperatives in Sulawesi and Sumatra feed commodity-grade copra supply for conventional low fat coconut milk production. The country's national food safety regulator enforces processing facility registration for export market eligibility. Weather-dependent yield volatility constrains volume predictability for contract manufacturers.
United Kingdom
Independent natural foods retailers prioritize organic certification density and origin storytelling over price competition. EU Green Deal alignment qualifies processors for corporate sustainability purchasing mandates. London and Southeast England retail clusters show penetration rates for natural foods retail exceeding national averages substantially.
Low Fat Coconut Milk Market Competitive Landscape
Channel-controlling players compete with product-specialist players for shelf positioning and procurement contracts across ambient and refrigerated formats. The vendor base separates into plantation-integrated processors, brand-marketing specialists, and private-label manufacturers. Three archetypes dominate: upstream-integrated Thai processors with captive raw material supply; North American brand owners with refrigerated distribution partnerships; and diversified natural foods conglomerates with organic certification density. Competitive moves concentrate on cold-chain infrastructure investment and organic certification acquisition.
Within the plantation-integrated tier, Thai Coconut Public Company Limited exemplifies upstream control through Samut Sakhon processing facilities. Among North American brand marketers, Silk and So Delicious Dairy Free occupy positions defined by refrigerated distribution depth in mainstream grocery. The Hain Celestial Group, Inc. sits within the diversified natural foods conglomerate archetype, representing organic certification density strategies.
| Leading Market Players |
|---|
| Thai Coconut Public Company Limited |
| Silk (Whitewave) |
| Pureharvest |
| GraceKennedy Limited |
| AroyD |
| Thai Agri Foods Public Company Limited |
| So Delicious Dairy Free |
| Pacific Foods |
| The Hain Celestial Group, Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Philippine and Indonesian copra processing is compressing margins for commodity-grade suppliers while Thai integrated processors maintain pricing power through organic certification scarcity and cold-chain service premiums.
Pricing Analysis
Cost-plus contracts indexed to copra futures dominate procurement between Southeast Asian processors and North American beverage manufacturers. Three-tier pricing structure across organic-certified, conventional aseptic, and retort-stable economy levels reflects certification density and cold-chain investment. Pricing pressure stems from smallholder yield volatility in Sulawesi and Sumatra. Private-label manufacturers exhibit highest price sensitivity; specialty coffee chains accept 15-20% premiums for high-pressure processed formats.
Supply Chain Analysis
Contract-manufacturing concentration rests with Thai Coconut Public Company Limited and Thai Agri Foods Public Company Limited, which control integrated plantation-processing clusters in Samut Sakhon and Ratchaburi. Raw material flows draw from Philippine and Indonesian smallholder cooperatives, with Thai estates feeding premium certified volumes. Single-source vulnerability concentrates in weather-dependent copra harvests across equatorial growing belts. Distribution runs through refrigerated logistics partnerships in coastal US metropolitan markets and ambient wholesale channels for institutional supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story: FDA and EFSA clean-label mandates create switching costs for established processors with validated additive-free formulations and certified supply bases.
For Market Incumbents: Pre-empt margin erosion by securing three-year organic plantation conversion contracts before competitor lock-in. Expand cold-chain capacity in California and New York Metro distribution hubs to defend shelf positioning against emerging aseptic entrants. Prioritize high-pressure processing R&D to extend refrigerated shelf life without thermal degradation. For New Entrants and Emerging Players: Pursue direct-to-consumer subscription models in ketogenic and sports nutrition verticals, where brand loyalty exceeds price elasticity. Target online retail channels with unsweetened functional variants fortified with MCT oil. Anchor go-to-market strategy through influencer partnerships in specialty diet communities rather than supermarket slotting fee competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plantation-integrated processors with captive organic supply and long-term North American beverage manufacturing contracts. Five-to-ten-year viability favors upstream-integrated Thai operators over brand-marketing specialists vulnerable to private-label displacement. Monitor FDA nomenclature rulemaking on plant-based milk alternative labeling as inflection indicator for marketing compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acquisition | Three-year plantation conversion periods create supply scarcity premiums for early movers under EU Green Deal procurement mandates. |
| Cold-Chain Infrastructure Expansion | Refrigerated distribution partnerships in California and New York Metro anchor premium placement in consolidating dairy-alternative planograms. |
| High-Pressure Processing Adoption | Non-thermal technology extends shelf life without flavor volatile degradation, supporting 15-20% price premiums in specialty coffee chains. |
| Direct-to-Consumer Channel Launch | Subscription models bypass supermarket slotting fees and capture recurring revenue from ketogenic diet adherents. |
| Functional Beverage Fortification | MCT oil and protein isolate additions position low fat coconut milk within sports nutrition verticals with higher margin profiles. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plantation operations managers, beverage manufacturing procurement leads, natural foods retail category buyers, and cold-chain logistics specialists; and secondary validation through FDA labeling guidance documents, EFSA health claim protocols, Thailand Ministry of Commerce export grading standards, and customs trade records. Bottom-up volume triangulation across product type, distribution channel, and end-use segments was cross-checked against top-down market sizing.
Forecast inputs considered copra supply elasticity, clean-label regulatory trajectory, and cold-chain infrastructure buildout rates across the projection horizon. Segmentation dimensions modeled include certification status, packaging technology, and channel temperature requirements. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Industry-specific inputs incorporated organic conversion cycle duration and aseptic packaging line investment thresholds.
Sensitivities concentrate around FDA nomenclature finalization, EFSA saturated fat claim restrictions, and El Niño-induced copra yield volatility. Forecasts reflect documented assumptions on regulatory enforcement timing and plantation conversion completion rates. Quarterly review of Thai export grading tier allocations and North American refrigerated distribution partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
Flax Milk Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
North America Drinkable Yogurt Market