
 Dairy-Free Creams Market | 2026-2036
Dairy-Free Creams Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy-Free Creams Market Analytics
Foodservice operators are rotating toward dairy-free cream formulations as residential buyers moderate pantry stocking. Oatly Group AB leverages oat-base fermentation expertise to secure café partnerships across Nordic and North American markets. Danone S.A. anchors its position through refrigerated distribution scale in European retail. Blue Diamond Growers competes on almond supply chain control, sourcing from California grower cooperatives.
Dairy-free creams are emulsion-based fat systems formulated from plant lipids, typically containing 10-35% fat content with stabilizers such as gellan gum or lecithin to replicate dairy mouthfeel and whipping functionality. Manufacturers employ high-pressure homogenization to achieve particle size distribution below 2 microns, ensuring thermal stability in sauces and desserts. Coconut cream leads product type volumes due to saturated fat content that mimics heavy cream performance, while cashew cream captures premium positioning in raw vegan desserts. Application demand skews toward cooking and sauces in foodservice channels, whereas vegan desserts drive retail velocity through specialty shops.
EFSA governs novel food ingredient approvals for emerging plant bases, while FDA maintains standards of identity debates that shape label claims and interstate commerce. REACH restricts certain emulsifier chemistries, compelling reformulation investments across European suppliers. Stakeholders must monitor evolving plant protein labeling disputes and carbon footprint disclosure rules that will determine shelf placement economics and foodservice contract eligibility.
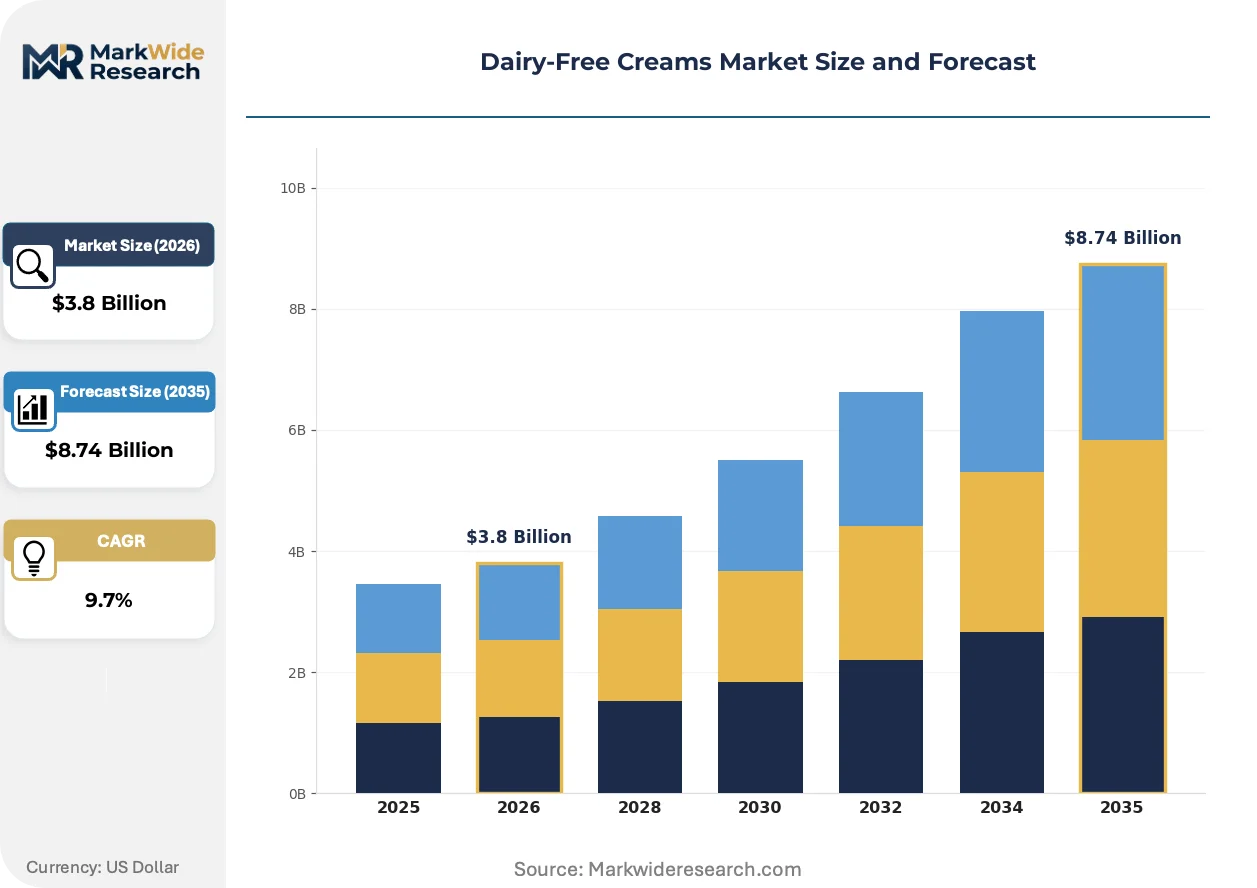
Market Dynamics
EU F-Gas Regulation and REACH compliance frameworks are tightening emulsifier and packaging chemical standards, forcing manufacturers to reformulate stabilizer systems and validate new ingredient pathways across European supply chains.
Growth Catalysts
- Specialty coffee channel expansion:Artisanal cafés in Germany and the United Kingdom are rotating toward plant-based whipped toppings as standard menu offerings, creating procurement pull through foodservice distributors.
- REACH-driven clean-label migration:European manufacturers are accelerating gellan gum and lecithin adoption to replace restricted emulsifier chemistries, opening formulation service contracts with ingredient suppliers.
- Oat-base fermentation scale-up:Nordic processing infrastructure is expanding capacity for enzymatic oat lipid extraction, reducing raw material cost volatility for dairy-free cream producers.
Market Restraints
- Coconut supply concentration:Saturated fat-dependent formulations rely on Southeast Asian and South Asian plantation harvests, exposing margins to climate-induced yield swings and shipping lane congestion.
- High-pressure homogenization capex:Particle size targets below 2 microns require specialized equipment that mid-scale producers struggle to finance, creating capacity bottlenecks.
- Almond water intensity:California drought cycles inflate nut input costs and attract regulatory scrutiny from EPA water-use monitoring, compressing margin structures for almond-base creams.
Strategic Opportunities
- French vegan dessert channel:Paris and Lyon specialty shops remain underpenetrated by cashew cream positioning, offering premium pricing capture for raw formulation suppliers.
- Carbon footprint disclosure rules:EU CSRD mandates are creating first-mover advantage for processors with lifecycle-certified supply chains, influencing foodservice contract eligibility.
- Refrigerated distribution convergence:Cold-chain logistics providers are integrating plant-based SKUs into existing dairy routes, lowering last-mile cost barriers for retail velocity.
Industry Challenges
- Novel food approval timelines:EFSA substantiation pathways for emerging plant bases extend 18-24 months, delaying product launches and freezing R&D pipelines.
- Emulsion stability expertise scarcity:Food science programs produce limited specialists in plant lipid rheology, constraining formulation team expansion for scaling manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy-Free Creams Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Cream, Almond Cream, Cashew Cream, Soy Cream Application: Cooking, Baking, Sauces, Vegan Desserts End User: Residential, Restaurants, Food Services, Catering Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Häagen-Dazs, Daiya Foods Inc., Danone S.A., Unilever PLC, Blue Diamond Growers, Oatly Group AB, So Delicious Dairy Free, Coconut Bliss, Ben & Jerry's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy-Free Creams Market Evolving Landscape
Formulation science and regulatory disclosure requirements are actively restructuring competitive advantage in dairy-free creams, separating processors with in-house emulsion capabilities from contract-dependent competitors.
High-pressure homogenization with microfluidization extensions is decomposing the traditional barrier between foodservice and retail quality tiers. Equipment suppliers in Germany and Italy are deploying smaller-footprint systems for artisanal producers. This capability diffusion is eroding the scale advantages previously held by industrial dairy alternatives processors.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon-free refrigeration retrofits across European cold-chain infrastructure. Foodservice distributors in France and the United Kingdom face compliance deadlines that favor partners with certified low-carbon logistics. Coconut cream suppliers with integrated cold storage investments are capturing shelf placement economics from reformulation-lagged competitors.
Café procurement committees are consolidating supplier rosters from multi-source ingredient buying to single-platform partnerships covering base, flavor, and topping categories. Oatly Group AB and Danone S.A. have structured bundled offerings that displace standalone whipped topping vendors. This concentration is most visible in Nordic markets where sustainability scoring determines contract renewal.
Dairy-Free Creams Market Segmentation
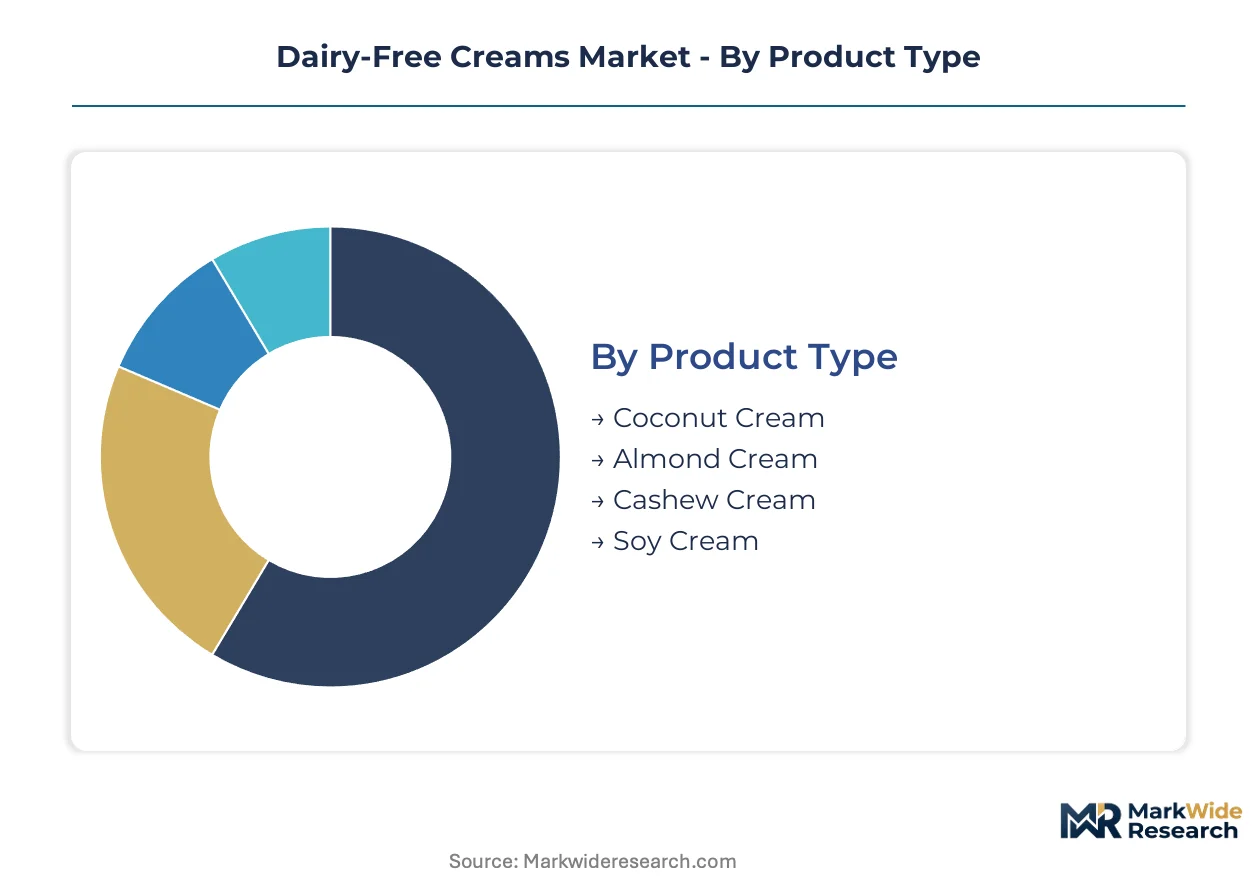
Plant lipid sourcing and emulsion stability requirements create divergent margin profiles across dairy-free cream categories. Each segment demands distinct cold-chain infrastructure and formulation expertise that shapes supplier specialization.
Product Type:
Export-led segments dominate European procurement, while domestic production clusters around Nordic oat processing and Mediterranean almond crushing.
- Coconut Cream:Saturated fat content between 17-24% enables stable whipping performance for pastry applications. German and French foodservice distributors prioritize Southeast Asian-sourced coconut cream for thermal stability in sauces, though shipping lane congestion creates intermittent supply gaps.
- Almond Cream:California grower cooperatives supply raw nut base to European processors, with EFSA novel food pathways required for enzymatic lipid extraction innovations. Water intensity scrutiny from EPA monitoring compresses margin structures during drought cycles.
- Cashew Cream:Premium positioning in raw vegan dessert channels across Paris and Lyon specialty shops.
- Soy Cream:Established supply chains from Midwest crushing facilities serve institutional foodservice contracts.
Coconut cream holds the largest share; momentum sits with cashew cream in premium dessert positioning.
Application:
Volume concentration skews toward heat-stable formulations, while margin capture favors cold-process applications requiring particle size precision below 2 microns.
- Cooking:High-pressure homogenization ensures thermal stability for reduction sauces and soups. German restaurant chains specify coconut-base cooking creams for consistent emulsion performance under sustained heat stress.
- Sauces:Foodservice procurement committees in the United Kingdom consolidate supplier rosters toward single-platform partnerships covering base and flavor categories.
- Baking:Whipping functionality demands fat content above 15% for aeration stability.
- Vegan Desserts:Raw formulation suppliers capture premium pricing in underpenetrated French specialty channels.
Cooking applications anchor volume demand; vegan desserts are climbing the fastest on per-unit margin expansion.
End User:
Customer type determines packaging format and delivery frequency, with institutional buyers driving bulk procurement and residential channels requiring retail-ready shelf stability.
- Food Services:Café procurement consolidation across Nordic markets favors bundled offerings from processors with sustainability scoring certification. REACH-compliant emulsifier reformulation opens formulation service contracts with ingredient suppliers.
- Restaurants:Paris and Lyon fine-dining establishments specify cashew cream for raw vegan plating.
- Catering:Event-scale demand requires ambient-stable UHT formats for logistics flexibility.
- Residential:Pantry stocking moderation shifts procurement toward smaller-format retail SKUs.
Food services command the largest procurement volumes; residential channels are gaining share fastest through supermarket expansion.
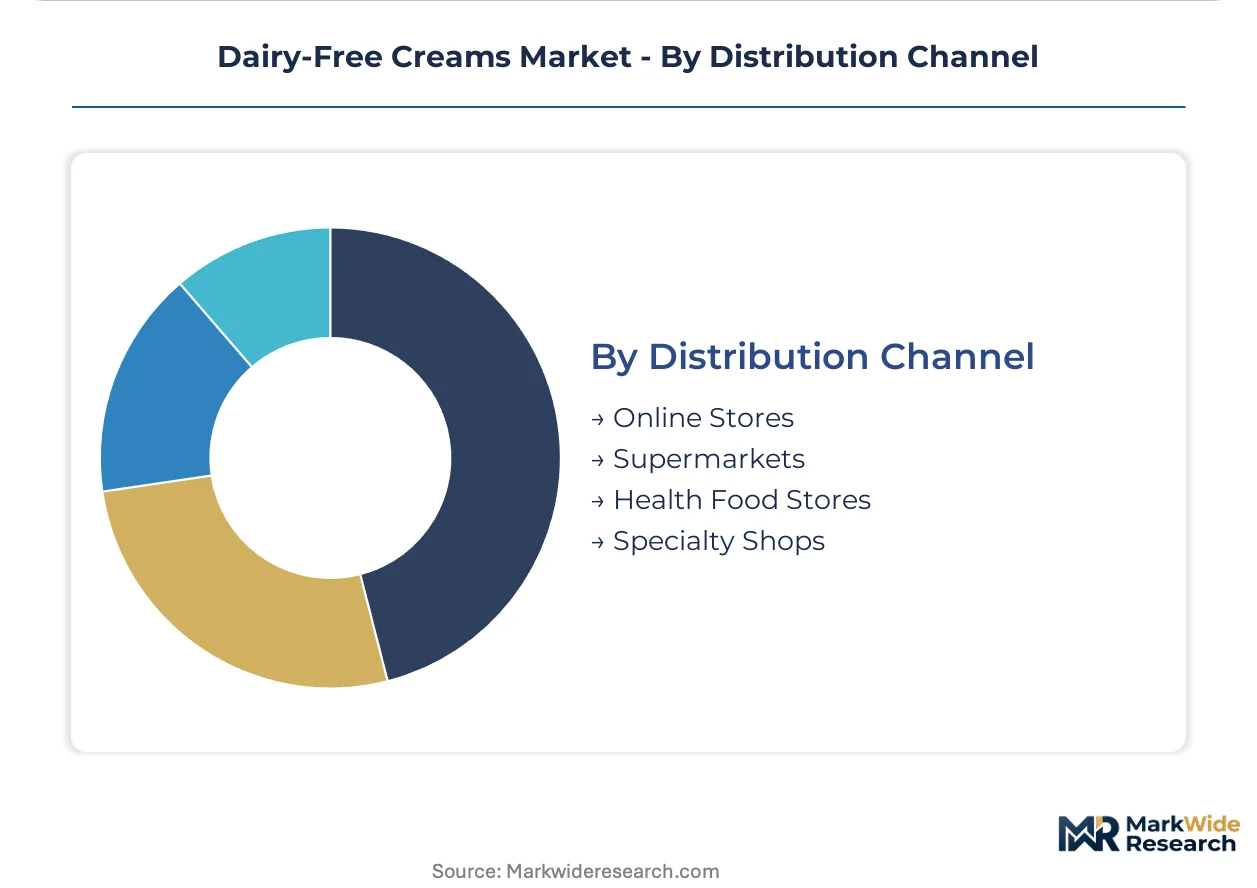
Distribution Channel:
Channel selection determines margin retention, with direct-to-retail capturing higher per-unit economics than distributor-mediated foodservice routes.
- Supermarkets:Refrigerated distribution convergence into existing dairy cold-chain routes lowers last-mile cost barriers. Danone S.A. anchors shelf placement through refrigerated logistics scale.
- Specialty Shops:Paris and Lyon vegan dessert boutiques source cashew cream through direct supplier relationships.
- Online Stores:Ambient-stable formats enable nationwide shipping without cold-chain dependency.
- Health Food Stores:Regional chains in Germany prioritize organic-certified coconut cream SKUs.
Supermarkets dominate volume throughput; specialty shops deliver steepest margin expansion through premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites continental distribution reach for dairy-free cream processors serving Northern European foodservice channels.
Germany
Specialty coffee chains in Berlin and Hamburg drive procurement of plant-based whipped toppings through consolidated distributor partnerships. The EU F-Gas Regulation compels hydrofluorocarbon-free refrigeration retrofits across Bavarian cold-storage facilities. Cologne and Düsseldorf host formulation laboratories where REACH-compliant emulsifier substitutes undergo accelerated validation.
United Kingdom
Artisanal bakeries in London and Manchester rotate toward oat-base cooking creams as standard inventory items. EFSA novel food pathways govern enzymatic lipid extraction innovations entering British retail. The Midlands logistics corridor integrates plant-based SKUs into existing dairy refrigerated routes, compressing last-mile delivery economics.
France
Fine-dining establishments in Paris and Lyon specify cashew cream for raw vegan dessert plating. EU CSRD carbon footprint disclosure mandates reshape foodservice contract eligibility for processors with lifecycle-certified supply chains. The Île-de-France region concentrates R&D activity for gellan gum stabilizer reformulation.
United States
California grower cooperatives supply almond base to domestic processors, though EPA water-use monitoring intensifies margin pressure during drought cycles. FDA standards of identity debates shape interstate label claims for plant-based cream alternatives. Pacific Northwest oat processing infrastructure expands enzymatic extraction capacity for lipid stream production.
Sweden
Nordic café procurement committees consolidate supplier rosters toward bundled base-and-topping platforms. REACH restrictions on legacy emulsifier chemistries accelerate clean-label migration among Stockholm-area formulators. Malmö's refrigerated distribution hubs converge plant-based and traditional dairy logistics, lowering route density costs for cross-border deliveries.
Dairy-Free Creams Market Competitive Landscape
Concentration sits with diversified food conglomerates and specialized plant-based processors. The vendor base spans three tiers: multinational refrigerated distribution networks, oat-fermentation specialists with café channel lock-in, and nut-supply-chain controllers with grower cooperative backing. Strategic moves center on bundled platform offerings that displace standalone ingredient vendors and cold-chain infrastructure investments that capture shelf placement economics.
Within the diversified conglomerate tier, Danone S.A. and Unilever PLC occupy positions anchored by refrigerated logistics scale across European retail networks. Among plant-based specialists, Oatly Group AB exemplifies the oat-fermentation archetype with Nordic and North American café partnership structures. Blue Diamond Growers represents the upstream-integrated model, sourcing from California almond grower cooperatives to secure input cost stability.
| Leading Market Players |
|---|
| Häagen-Dazs |
| Daiya Foods Inc. |
| Danone S.A. |
| Unilever PLC |
| Blue Diamond Growers |
| Oatly Group AB |
| So Delicious Dairy Free |
| Coconut Bliss |
| Ben & Jerry's |
| Others |
Value Network & Pricing Analysis
High-pressure homogenization capacity utilization above 80% in German and Italian equipment clusters creates scale-driven cost floors that squeeze mid-tier processors while rewarding volume leaders with procurement leverage over coconut and oat lipid suppliers.
Pricing Analysis
Volume-discount tiering structures separate industrial foodservice contracts from artisanal bakery procurement, with coconut cream commanding premium positioning against almond-base alternatives due to whipping stability performance. Price differentiation hinges on REACH-compliant emulsifier certification and cold-chain reliability scoring, with foodservice buyers in Nordic markets exhibiting lowest sensitivity due to bundled platform requirements. Cost compression in almond-base tiers is intensifying because California drought cycles inflate nut input costs. Residential retail channels show highest price sensitivity, moderating toward smaller-format SKUs.
Supply Chain Analysis
Just-in-time inventory strategies dominate foodservice distribution through Rotterdam and Hamburg cold-chain hubs, while strategic stockpiling of Southeast Asian coconut cream buffers climate-induced harvest volatility for German and French processors. Geographic supply concentration centers on Indonesia and the Philippines for coconut lipid, California for almond base, and Sweden for oat processing infrastructure. Raw material dependencies include saturated fat-rich coconut oil, enzymatically extracted oat lipids, and gellan gum stabilizers. Single-source vulnerability runs through Malacca Strait shipping lanes. Distribution runs through refrigerated logistics providers integrating plant-based SKUs into existing dairy routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EFSA novel food approval timelines and REACH compliance investments create switching costs that freeze out formulation-lagged competitors.
For Market Incumbents: Shield refrigerated distribution scale through cold-chain infrastructure investments in Rotterdam and Hamburg hubs that capture shelf placement economics from reformulation-lagged rivals. Anchor bundled platform offerings covering base, flavor, and topping categories to displace standalone whipped topping vendors facing REACH-driven emulsifier migration costs.
For New Entrants and Emerging Players: Lead with cashew cream positioning in underpenetrated Paris and Lyon vegan dessert boutiques where premium pricing capture exceeds industrial foodservice margin structures. Target direct supplier relationships with specialty shops bypassing distributor consolidation, leveraging microfluidization equipment footprints to match retail quality tiers without industrial scale requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with in-house emulsion capabilities and lifecycle-certified supply chains qualifying for EU CSRD contract eligibility. Long-term viability rests on cold-chain infrastructure ownership and EFSA approval pipeline depth. Signal to monitor: EFSA substantiation pathway acceleration for emerging plant bases that would unlock frozen R&D pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Emulsifier Reformulation | Opens formulation service contracts with ingredient suppliers facing restricted chemistries. |
| Refrigerated Distribution Convergence | Lowers last-mile cost barriers through integration into existing dairy cold-chain routes. |
| Carbon Footprint Certification Investment | Captures EU CSRD foodservice contract eligibility from lifecycle-uncertified competitors. |
| Microfluidization Equipment Deployment | Erodes scale advantages of industrial processors by diffusing quality-tier capabilities. |
| Upstream Oat Processing Capacity Expansion | Reduces raw material cost volatility through Nordic enzymatic lipid extraction infrastructure. |
Research Methodology
The analysis maps coconut cream, almond cream, cashew cream, and soy cream sub-sectors, each validated through formulation scientists, foodservice procurement directors, and refrigerated logistics operators. Primary interviews with plant-based R&D heads, distributor category managers, and specialty shop buyers combined with secondary validation from EFSA novel food registers, REACH restriction updates, and EU cold-chain infrastructure databases. Bottom-up volume modeling and top-down value triangulation cross-checked segment assumptions.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product lipid source, application heat-stability requirements, end-user procurement scale, and distribution channel cold-chain dependency. CAGRs derived from volume trajectory analysis incorporating oat-base fermentation scale-up curves and coconut supply concentration risk adjustments.
The analysis sits within stated boundaries; outcomes outside EFSA approval timeline assumptions or REACH enforcement intensity would require recalibration. Forecasts reflect documented assumptions about foodservice consolidation velocity and emulsion stability expertise scarcity. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down schedules and carbon disclosure mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Vegan Butter Market