
 Hazelnut Milk Market | 2026-2036
Hazelnut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Hazelnut Milk Market Foresight
Multi-source hazelnut procurement is consolidating as larger processors reduce dependency on Turkish and Georgian spot markets. Borges International Group leverages its Mediterranean crushing infrastructure to secure preferential kernel supply. Pacific Foods sustains West Coast manufacturing scale through long-term contracts with Oregon hazelnut cooperatives. Elmhurst differentiates via its HydroRelease zero-waste extraction technology, yielding cleaner label positioning against conventional emulsified products.
Hazelnut milk denotes an aqueous suspension of ground roasted Corylus avellana kernels, typically homogenized with 2-4% fat content and stabilized with gellan or locust bean gum for thermal tolerance in espresso applications. The product serves commercial barista operations and retail consumers seeking dairy alternatives with lower environmental water intensity than almond. Unsweetened and barista blend categories now capture the deepest margin pools, as café operators prioritize neutral flavor profiles and microfoam stability over vanilla or chocolate variants. Tetra pack formats dominate shelf-stable distribution through supermarkets, while glass bottles anchor premium placement in health food stores where organic certification commands price premiums.
FDA nutrition labeling rules and USDA organic certification govern US product claims, while EFSA novel food assessments and EU organic regulation shape European market entry. REACH compliance for food-contact packaging materials increasingly filters smaller brands from multi-country retail expansion. Stakeholders must monitor evolving EUDR deforestation due diligence requirements, which will soon mandate traceable hazelnut origin documentation through supply chain tiers.
Market Dynamics
Specialty coffee chains in Germany and France are accelerating hazelnut milk placement on menus, compressing the window for conventional dairy alternatives while tightening procurement specifications for barista-grade thermal stability.
Growth Catalysts
- EU Plant Protein Regulation:The framework streamlines novel food approvals for protein-rich beverages, reducing time-to-market for fortified hazelnut milk formulations entering continental retail.
- Confectionery supply networks:Italy's Lombardy and Piedmont regions host established kernel processing clusters that now feed directly into beverage manufacturing, shortening ingredient transit distances.
- F-Gas standards:Evolving cold-chain requirements under the regulation are pushing foodservice distributors toward shelf-stable Tetra pack formats with extended ambient distribution reach.
Market Restraints
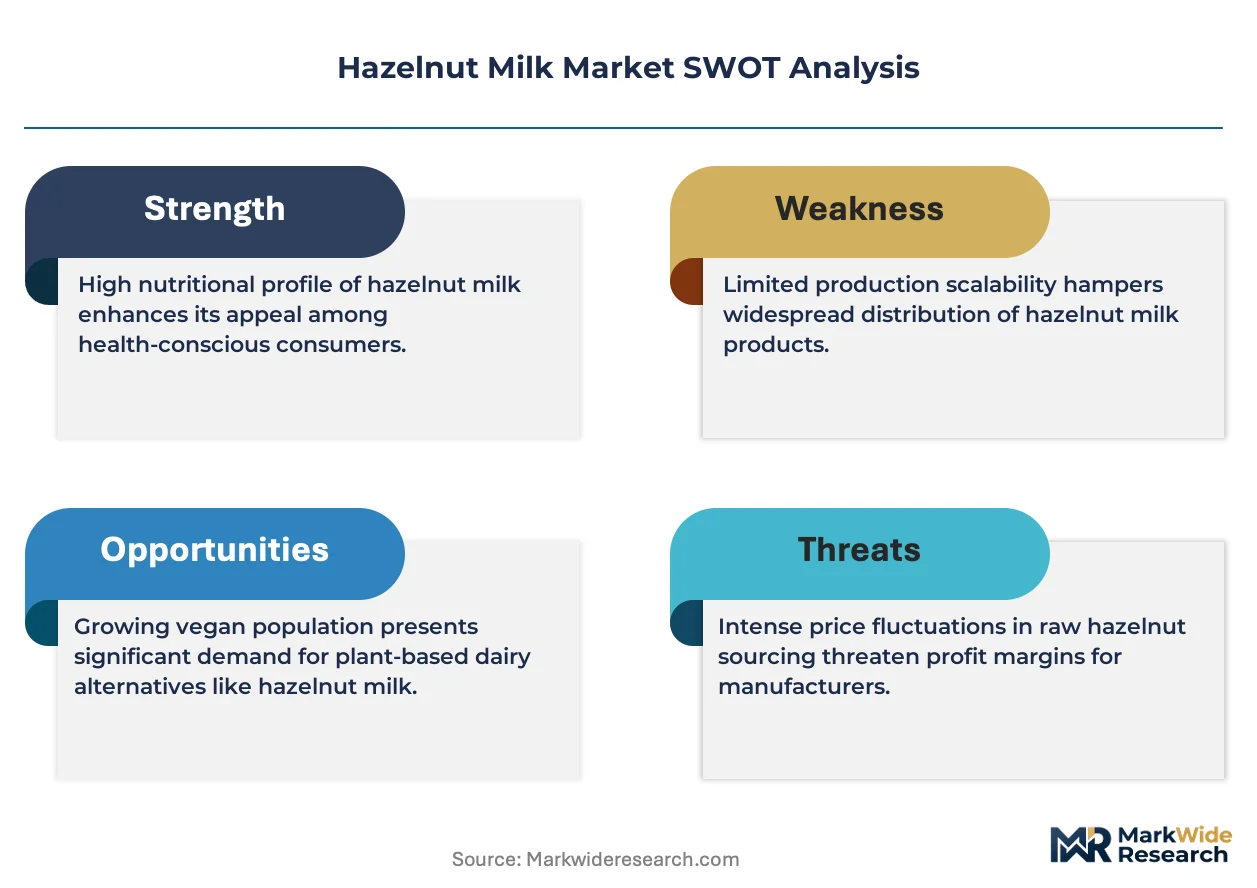
- Turkish and Georgian spot market dependency:Kernel price volatility from these origin markets creates margin compression for processors lacking long-term contract coverage.
- REACH compliance for packaging:Food-contact material certification requirements filter smaller brands from multi-country retail expansion across EU member states.
- Almond milk substitution:Lower water-intensity claims for hazelnut remain poorly differentiated in consumer messaging against entrenched almond positioning in North American retail.
Strategic Opportunities
- EUDR deforestation due diligence:The incoming traceability mandate creates first-mover advantage for processors with tiered supply chain documentation already in place.
- Unsweetened barista blends:Café operators in Paris and Berlin are prioritizing neutral flavor profiles and microfoam stability over vanilla variants, opening premium positioning for clean-label extraction technologies.
- Health food store channel:Glass bottle formats with organic certification command price premiums in this channel, which remains underdeveloped relative to supermarket shelf-stable placement.
Industry Challenges
- HydroRelease extraction expertise:Zero-waste processing capabilities require specialized engineering talent that concentrates among a narrow supplier base.
- Organic certification timelines:USDA and EU organic audit cycles create working capital strain for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazelnut Milk Market |
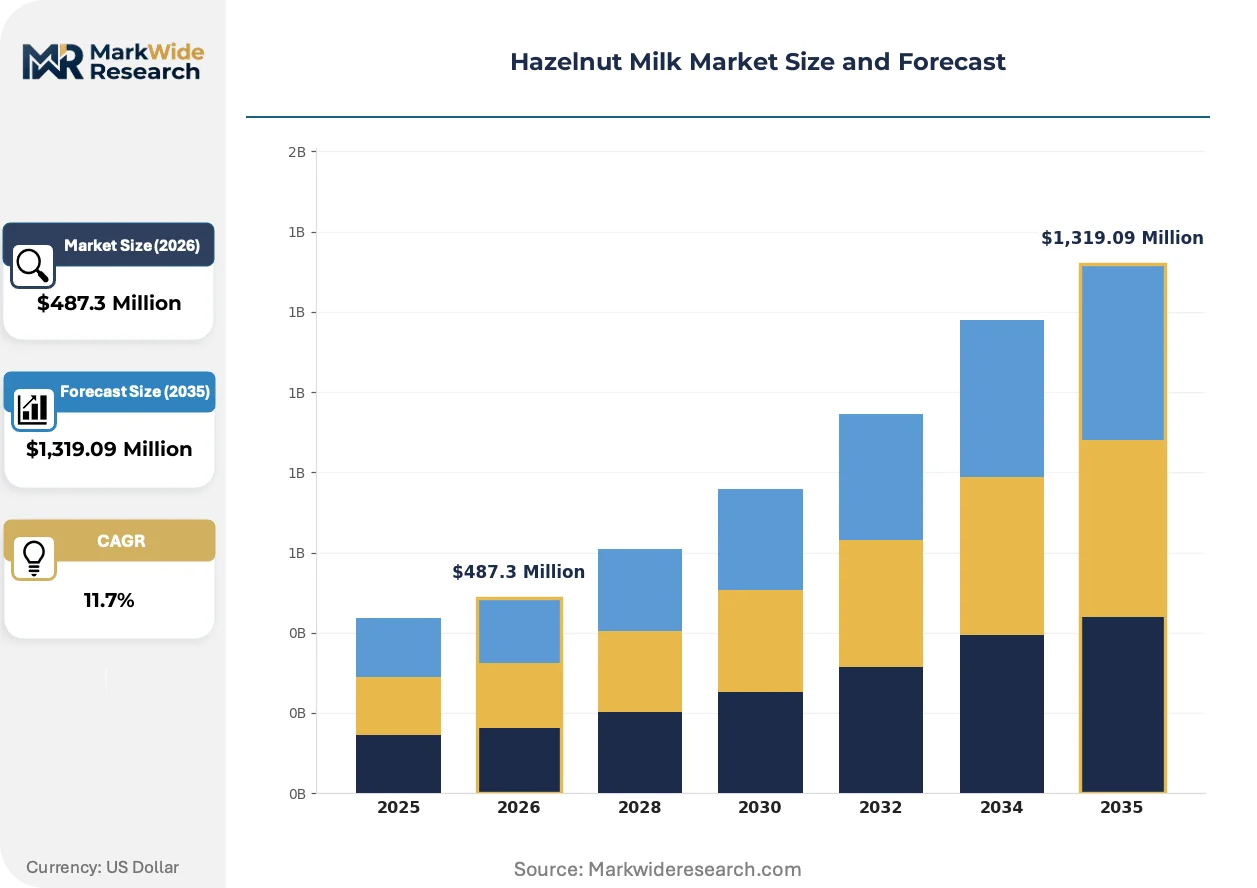
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetened, Unsweetened, Barista Blend, Organic Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops Customer Type: Vegetarians, Vegans, Lactose Intolerant, Health-Conscious Consumers |
| Companies Covered | Borges International Group, Pacific Foods, Alpro, Barista Coffee Company, Drinkhooray!, Elmhurst, Rude Health, Ferrero Group, Fomilk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazelnut Milk Market Shifts & Advancements
Processing technology and regulatory traceability requirements are converging to reshape competitive positioning, with extraction methods and supply chain visibility emerging as primary differentiation vectors.
HydroRelease zero-waste extraction technology is electrifying clean-label positioning in the barista segment. Pacific Foods and Elmhurst have deployed this aqueous separation method to eliminate conventional emulsifiers from their formulations. The technology is compressing the ingredient deck from seven-plus additives to two or three components, enabling premium pricing against standard emulsified products.
EFSA novel food assessments combined with EU organic regulation are tightening entry barriers for fortified and flavored variants. Processors must now submit comprehensive toxicological data for new protein concentration levels. The unsweetened segment is responding by simplifying formulations to reduce regulatory exposure and accelerate approval timelines.
Café procurement specifications are hardening around thermal tolerance and microfoam stability metrics. Chains in Munich and Lyon now require third-party validation of espresso compatibility before menu placement. This behavioral shift is most visible in northern Italy, where roasting equipment manufacturers are integrating hazelnut milk calibration protocols into new machine installations.
Hazelnut Milk Market Segmentation
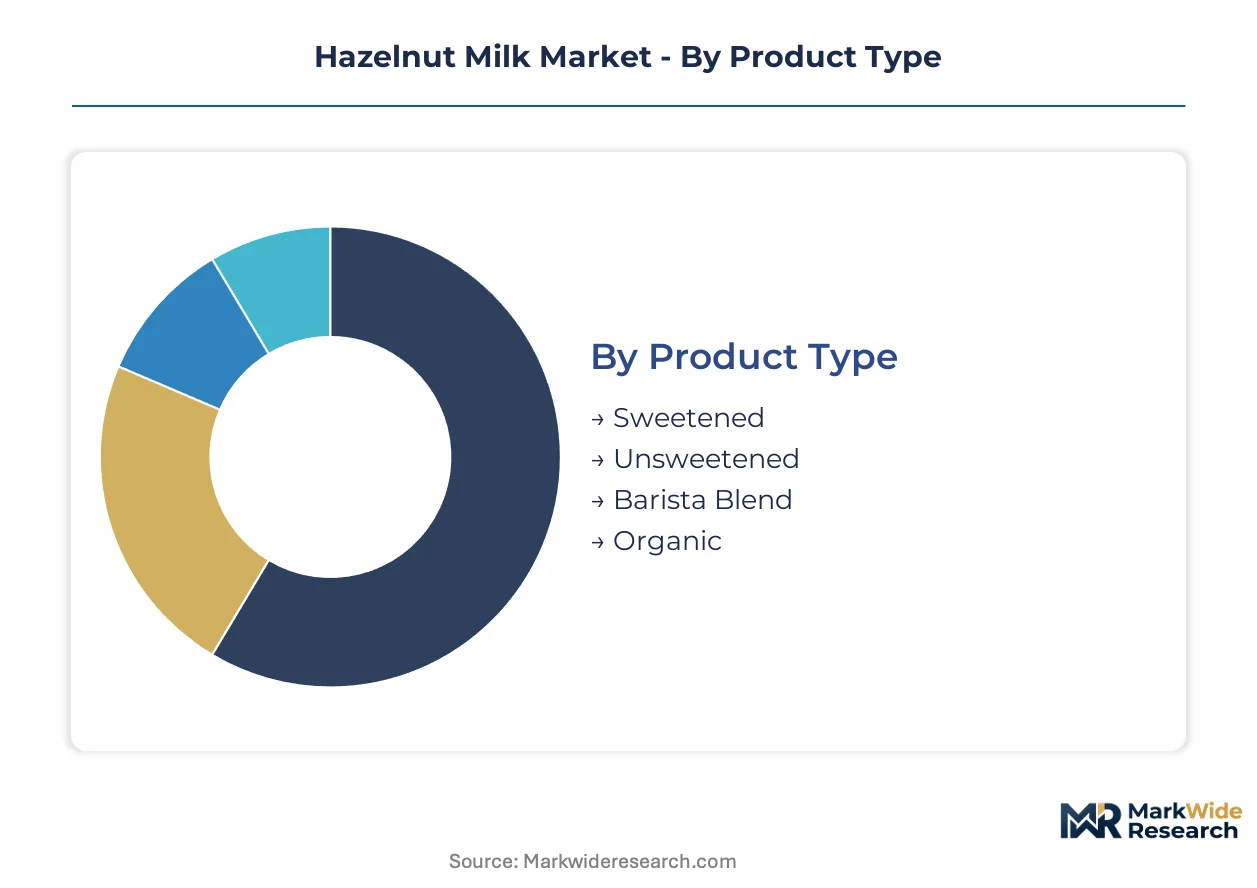
Hazelnut milk segmentation reflects divergent buyer priorities across café operations and household consumption. Procurement specifications for commercial barista applications differ sharply from retail shelf placement requirements, creating distinct margin architectures within each product category.
Product Type:
Barista-grade thermal stability commands the highest procurement premiums as café operators prioritize foam structure over flavor additives.
- Sweetened:Vanilla and chocolate variants incorporate cane sugar or agave at 6-8% concentration. Demand concentrates in US Midwest retail where conventional flavor profiles dominate household repeat purchase.
- Unsweetened:Single-ingredient formulations with 2-4% native fat content achieve clean-label positioning. Paris and Berlin café chains specify unsweetened bases for menu neutrality, compressing vanilla variant placement.
- Barista Blend:Gellan gum stabilization at 0.2% enables 65°C steam tolerance without protein precipitation. Munich specialty coffee chains now require third-party espresso compatibility validation before procurement approval.
- Organic:USDA and EU organic certification mandates kernel sourcing from audited orchards without synthetic pesticide application. Glass bottle formats in health food stores extract 40-60% price premiums over conventional Tetra pack equivalents.
Volume sits with unsweetened retail formats; growth tilts toward barista blends as commercial procurement specifications harden.
Packaging Type:
Cold-chain economics and shelf-life requirements split procurement between ambient-stable and refrigerated distribution networks.
- Bottles:Glass and PET formats anchor premium placement in health food stores where organic certification visibility drives selection. Elmhurst and Pacific Foods dominate this channel with transparent ingredient messaging.
- Tetra Packs:Aseptic carton technology enables 12-month ambient shelf life without refrigeration. F-Gas Regulation compliance costs are compressing foodservice distributor preference toward shelf-stable formats with extended distribution reach.
- Cans:Aluminum formats serve single-serve convenience positioning in grab-and-go retail. Limited thermal tolerance restricts barista application.
- Pouches:Flexible packaging reduces shipping cube for direct-to-consumer subscription models. Oregon hazelnut cooperative supply contracts support West Coast concentrated production for this channel.
Procurement weight concentrates in Tetra Packs; expansion is climbing fastest in bottles as organic certification commands retail price premiums.
Distribution Channel:
Channel selection determines certification requirements and margin capture potential through differential shelf placement economics.
- Supermarkets:Mass retail placement requires EUDR traceability documentation and REACH-compliant food-contact materials. Shelf-stable Tetra packs dominate this channel with promotional pricing pressure.
- Online Retail:Direct-to-consumer subscription models enable pouched formats with reduced shipping overhead. Pacific Foods leverages Oregon cooperative supply for West Coast fulfillment density.
- Health Food Stores:Organic certification and glass bottle formats extract maximum price premiums. This channel remains underdeveloped relative to supermarket penetration.
- Specialty Shops:Italian confectionery supply networks from Lombardy and Piedmont feed directly into boutique beverage retail with shortened transit distances.
Revenue concentrates in supermarkets; margin expansion is shifting fastest toward health food stores as organic certification premiums widen.
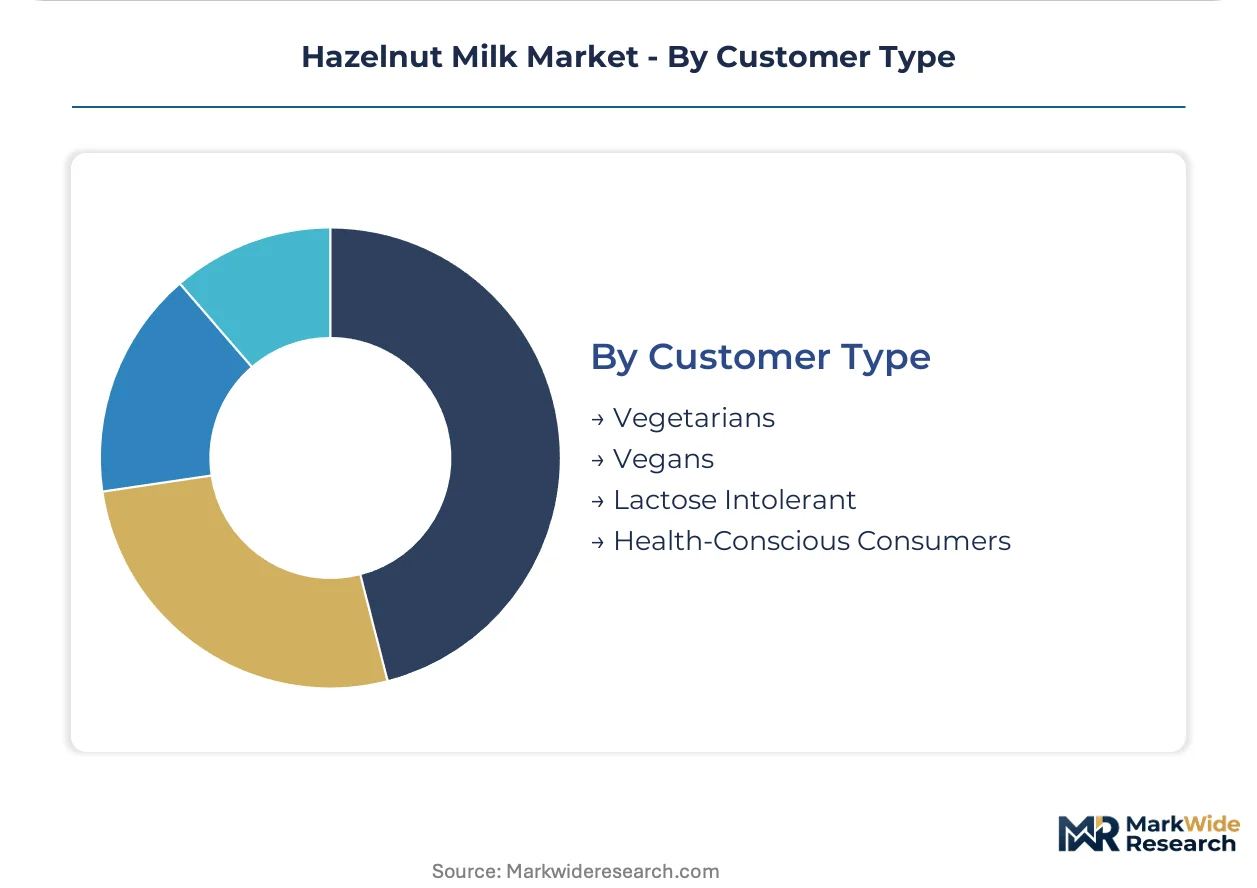
Customer Type:
Dietary restriction severity and environmental motivation intensity create distinct willingness-to-pay thresholds across consumer segments.
- Vegetarians:Flexitarian consumers treat hazelnut milk as occasional dairy reduction rather than strict substitution. Price sensitivity limits premium positioning.
- Vegans:Ethical consistency requirements drive organic and clean-label preference with reduced price elasticity. Health food store channel concentration aligns with this segment.
- Lactose Intolerant:Functional necessity creates stable baseline demand without strong brand loyalty. Supermarket promotional pricing captures this volume.
- Health-Conscious Consumers:Environmental water intensity claims versus almond milk attract sustainability-motivated buyers. Messaging differentiation remains underdeveloped in North American retail.
Volume anchors with lactose-intolerant households; value capture is expanding most quickly among health-conscious consumers as environmental claims sharpen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's Black Sea coast and Georgia's western growing belts anchor raw hazelnut supply, while processing gravity clusters in Mediterranean Europe and North American manufacturing nodes convert kernel into finished beverage.
Germany
Munich and Berlin café chains now mandate third-party espresso compatibility validation before hazelnut milk procurement approval. The F-Gas Regulation tightens cold-chain compliance, pushing foodservice distributors toward shelf-stable Tetra pack formats. Bavarian roasting equipment manufacturers integrate hazelnut milk calibration protocols into new machine installations.
France
Paris specialty coffee operators prioritize neutral flavor profiles and microfoam stability, compressing vanilla variant placement on menus. REACH compliance for food-contact packaging materials filters smaller brands from multi-country retail expansion. The Île-de-France region hosts formulation R&D clusters serving barista-grade stabilization requirements.
Italy
Lombardy and Piedmont confectionery-grade kernel supply networks feed directly into beverage processing, shortening ingredient transit distances. EFSA novel food assessments shape fortified formulation entry timelines. Turin-based equipment fabricators supply roasting infrastructure calibrated for hazelnut milk thermal tolerance.
United States
Oregon hazelnut cooperatives sustain West Coast manufacturing scale through long-term contract coverage with beverage processors. FDA nutrition labeling rules and USDA organic certification govern product claims and working capital requirements. The Pacific Northwest concentrates pouched format production for direct-to-consumer subscription channels.
United Kingdom
London health food stores extract 40-60% price premiums for organic-certified glass bottle formats over conventional Tetra pack equivalents. EUDR deforestation due diligence requirements will soon mandate traceable hazelnut origin documentation through supply chain tiers. British retail procurement specifications increasingly require tiered supply chain visibility ahead of regulatory deadlines.
Hazelnut Milk Market Competitive Landscape
Global majors compete with regional champions across extraction technology and procurement contract structures. The vendor base organizes around Mediterranean kernel sourcing advantages, North American clean-label positioning, and European barista-grade formulation expertise. Three archetypes dominate: integrated processors with captive crushing infrastructure, technology-led specialists deploying aqueous separation methods, and brand-led operators leveraging organic certification premiums. Competitive moves concentrate on long-term supply contracts with origin cooperatives and zero-waste extraction licensing arrangements.
Within the integrated processor tier, Borges International Group leverages its Mediterranean crushing infrastructure to secure preferential kernel supply. Pacific Foods and Elmhurst occupy positions on the technology-led vector, with the latter exemplifying HydroRelease zero-waste extraction capabilities that compress ingredient decks and enable premium positioning. These three entities represent distinct competitive anchors: geographic supply control, manufacturing scale through cooperative contracts, and clean-label differentiation through proprietary separation technology.
| Leading Market Players |
|---|
| Borges International Group |
| Pacific Foods |
| Alpro |
| Barista Coffee Company |
| Drinkhooray! |
| Elmhurst |
| Rude Health |
| Ferrero Group |
| Fomilk |
| Others |
Supply & Pricing Matrix
EUDR deforestation due diligence mandates gate qualified hazelnut supply and premium-tier pricing access, compressing margins for processors lacking tiered origin documentation while rewarding early-compliant operators with health food store price premiums.
Pricing Analysis
Service bundling separates validated espresso compatibility testing from unbundled base product supply, with Munich café chains now requiring third-party thermal tolerance certification as a procurement prerequisite. Three-tier pricing structure across organic-certified premium, barista-grade standard, and conventional economy levels reflects certification grade and volume scale differentiation. Cost compression in economy Tetra pack tiers is intensifying because Turkish spot market volatility feeds directly into processor input costs. Lactose-intolerant households exhibit highest price sensitivity, while vegan consumer segments demonstrate reduced elasticity for clean-label extraction technologies.
Supply Chain Analysis
Regional distribution centers in northern Italy and the Pacific Northwest anchor hub-and-spoke patterns for kernel aggregation and finished beverage dispatch. Raw supply draws from Turkey, Georgia, and Oregon cooperative networks, with confectionery-grade kernel streams from Lombardy and Piedmont feeding directly into beverage processing. Single-source vulnerability concentrates in Black Sea origin dependency, where geopolitical disruption risks cascade through spot pricing mechanisms. Distribution runs through ambient-stable Tetra pack logistics for supermarket penetration, while refrigerated glass bottle channels serve health food store premium placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EUDR traceability documentation functions as a cost-of-compliance moat, with tiered supply chain visibility requirements filtering undercapitalized entrants from multi-country retail expansion.
For Market Incumbents: Acquire HydroRelease extraction licensing arrangements to consolidate clean-label positioning against conventional emulsified competitors. Borges International Group's Mediterranean crushing infrastructure demonstrates how captive kernel supply insulates margin structures from Turkish spot volatility. Pacific Foods' Oregon cooperative contracts illustrate long-term offtake agreements as defensive leverage against origin price swings. For New Entrants and Emerging Players: Health-conscious sustainability-motivated buyers represent an underserved archetype with sharpenable environmental water intensity messaging against entrenched almond positioning. White space concentrates in North American retail where hazelnut differentiation remains underdeveloped, and in health food store glass bottle channels extracting organic certification premiums. Direct-to-consumer subscription models with pouched formats offer a penetrable go-to-market angle through Oregon supply density. For Investors and Strategic Acquirers: EUDR implementation timeline acceleration is the leading indicator that compliant supply chain documentation will command acquisition premiums within a five-to-ten year viability window. Target processors with existing tiered origin traceability systems and HydroRelease technology licensing portfolios. Watch for F-Gas Regulation compliance cost spikes signaling shelf-stable format preference inflection among foodservice distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kernel Crushing | Borges International Group's Mediterranean infrastructure secures preferential supply against Turkish spot volatility. |
| Clean-Label Extraction Technology Licensing | Elmhurst's HydroRelease deployment compresses ingredient decks from seven additives to two or three components. |
| EUDR Traceability System Implementation | Tiered origin documentation satisfies incoming EU deforestation due diligence mandates ahead of regulatory deadlines. |
| Long-Term Cooperative Supply Contracts | Pacific Foods' Oregon hazelnut agreements sustain West Coast manufacturing scale with price predictability. |
| Barista-Grade Thermal Stability Certification | Third-party espresso compatibility validation unlocks Munich and Berlin café chain procurement approval. |
Research Methodology
Independent corroboration across beverage processor procurement directors, café chain operations managers, and Oregon cooperative supply coordinators underwrites the qualitative findings. Primary interviews with hazelnut kernel traders, Tetra pack packaging engineers, and EFSA regulatory consultants combined with secondary validation from EU Plant Protein Regulation filings, REACH food-contact material certifications, and USDA organic audit records. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Rate-of-change decomposition across the analysis window segmented projections by product type, packaging format, distribution channel, and customer dietary restriction severity. CAGRs derived from historical volume trajectories adjusted for EUDR implementation pace, F-Gas Regulation cold-chain cost shifts, and barista-grade thermal stability specification hardening. Hazelnut kernel price volatility indices and espresso equipment calibration protocol adoption curves served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EUDR traceability mandate enforcement timing and Turkish origin geopolitical stability. Outputs reflect documented assumptions around regulatory implementation schedules and cooperative contract renewal rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
North America Drinkable Yogurt Market