
 Sugar-Free Soy Milk Powder Market | 2026-2036
Sugar-Free Soy Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Free Soy Milk Powder Market Insights
Consolidation among nutritional sector buyers is realigning procurement leverage toward large-scale contract manufacturers. Vitasoy International Holdings Limited leverages its Asian distribution infrastructure to anchor supply relationships with institutional food service operators. Archer Daniels Midland Company competes through backward integration into non-GMO soybean crushing and in-house spray-drying capacity. Orgain differentiates via certified organic positioning and direct-to-consumer channel control in North America.
Sugar-free soy milk powder consists of dehydrated soy milk solids with negligible mono- and disaccharide content, typically achieving less than 0.5 grams sugars per serving through enzymatic conversion or selective ultrafiltration prior to spray-drying at 180-200°C inlet temperatures. The material functions primarily as a shelf-stable dairy alternative base for beverage reconstitution, bakery applications, and clinical nutrition formulations. Instant Powder dominates volume due to reconstitution speed requirements in food service environments, while Dry Blend captures expanding margin pools from custom fortification with vitamins and minerals for nutritional sector clients. Online Retail is accelerating fastest among distribution channels, though Wholesale retains structural importance for bulk procurement by manufacturing customers.
FDA enforcement of added sugars disclosure on Nutrition Facts panels shapes formulation decisions for US-bound production, while China's SAMR oversees GB standards compliance for domestic and export-certified facilities. The EU's EFSA novel food authorization pathway creates entry barriers for enzymatically modified soy protein variants not previously consumed in member states. Stakeholders must monitor evolving protein content claim thresholds across jurisdictions to preempt reformulation costs and market access restrictions.
Market Dynamics
Consolidation among nutritional sector buyers is compressing supplier margins and privileging contract manufacturers with enzymatic conversion capabilities and spray-drying scale. FDA labeling enforcement and China's SAMR GB standards are tightening formulation compliance costs simultaneously.
Growth Catalysts
- Diabetic Nutrition Formulations:Clinical nutrition buyers in China and North America are expanding procurement of enzymatically treated soy protein for glycemic-controlled meal replacements.
- GB Standards Modernization:China's SAMR has tightened protein content claim thresholds, accelerating facility upgrades among domestic spray-dryers seeking export certification.
- Ultrafiltration Cost Reduction:Membrane technology advances are lowering sugar removal costs below enzymatic conversion for mid-scale processors.
Market Restraints
- Non-GMO Soybean Premium Volatility:Identity-preserved soybean premiums in Brazil and the United States swing 15-40% seasonally, compressing margin visibility for organic-positioned brands.
- EFSA Novel Food Pathway:Enzymatically modified protein variants face 18-24 month authorization timelines for EU market entry, freezing innovation pipelines.
- Oat Protein Substitution:Barista-grade oat milk powder is capturing food service reconstitution demand previously held by soy bases.
Strategic Opportunities
- Senior Nutrition Channels:Japan's METI-registered Foods for Specified Health Uses pathway offers premium positioning for isoflavone-fortified variants targeting sarcopenia prevention.
- Direct-to-Consumer Fortification:Custom vitamin-mineral dry blends via subscription platforms bypass wholesale margin compression in North America.
- Carbon Accounting Integration:China's dual carbon goals are creating procurement preference for processors with verified Scope 3 soybean traceability.
Industry Challenges
- Spray-Drying Energy Intensity:Natural gas-fired inlet systems at 180-200°C face carbon border adjustment exposure under EU CBAM implementation timelines.
- Cross-Contamination Certification:Gluten-free and allergen-free dual certification requires segregated production lines extending facility qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Free Soy Milk Powder Market |
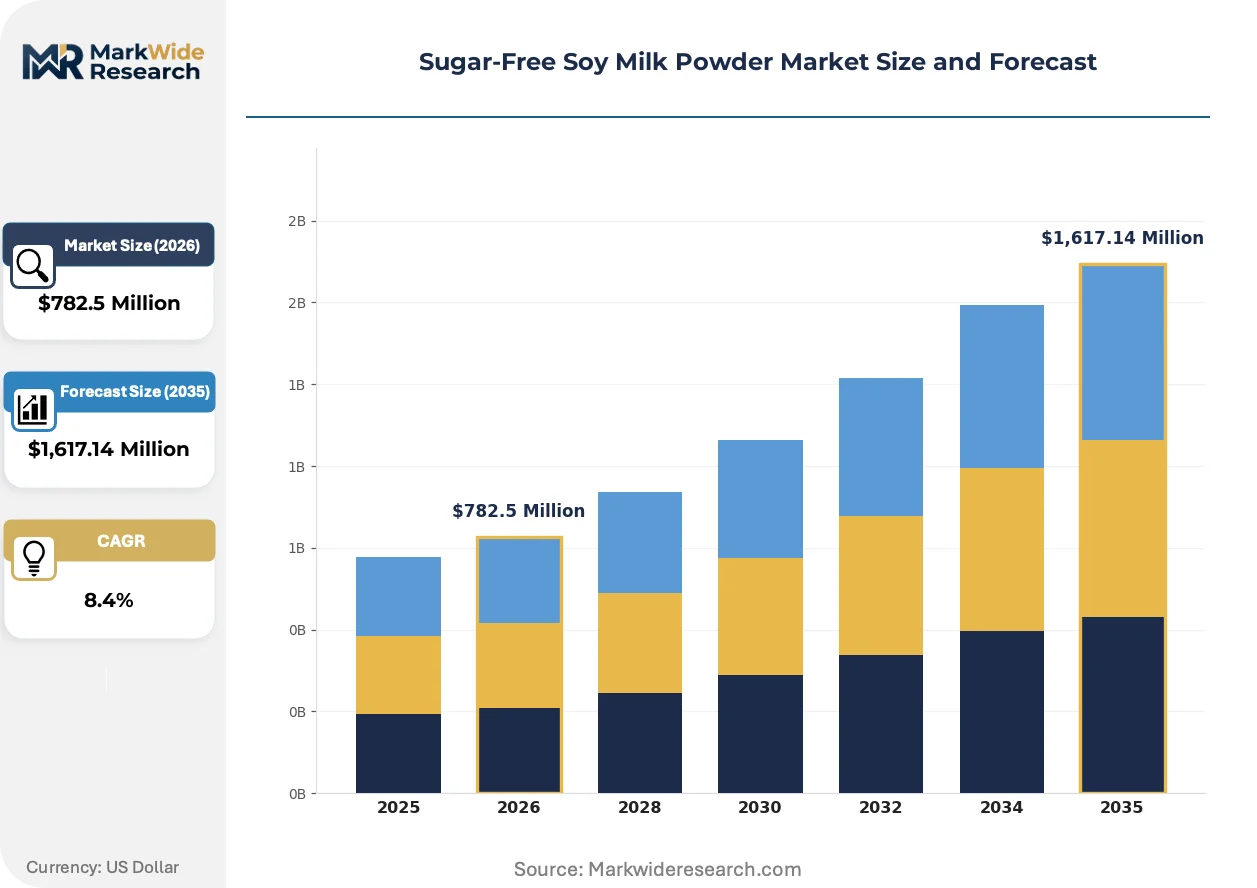
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,617.14 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Powder, Liquid Concentrate, Dry Blend, Ready-to-Use End User: Household, Food Service, Retail, Nutritional Sector Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Ingredient: Non-GMO Soybeans, Stabilizers, Natural Flavorings, Emulsifiers |
| Companies Covered | Yonho, Soyspring, GUKI, Now Foods, Silk, Bob's Red Mill, Orgain, Vitasoy International Holdings Limited, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Free Soy Milk Powder Market Trends and Innovations
Formulation science and regulatory compliance are converging to reshape competitive advantage around enzymatic precision and spray-drying energy efficiency. Three developments are restructuring supply relationships and procurement criteria.
Enzymatic lactase conversion adapted for soy oligosaccharide reduction is consolidating technical leadership among processors with in-house biotechnology capabilities. Nutritional sector buyers in Germany and the Netherlands are qualifying suppliers on mono- and disaccharide residuals below 0.3 grams per serving. This capability threshold is compressing the qualified supplier base toward integrated crush-to-powder operators.
EFSA's 2023 guidance on plant protein digestibility claims is forcing reformulation of products marketed to clinical nutrition channels. Manufacturers must now submit PDCAAS or DIAAS validation for protein quality assertions, extending product development cycles by 8-12 months. EU-bound production lines are responding by integrating in vitro protein digestibility testing prior to scale-up.
Food service procurement departments are unbundling beverage base supply from equipment and technical service contracts. Institutional buyers in China's tier-one cities are issuing separate tenders for powder supply, reconstitution training, and machine maintenance. This disaggregation is visible most acutely in Shanghai and Beijing, where multinational hotel chains are consolidating soy milk powder procurement at regional headquarters level while outsourcing on-site preparation support.
Sugar-Free Soy Milk Powder Market Segmentation
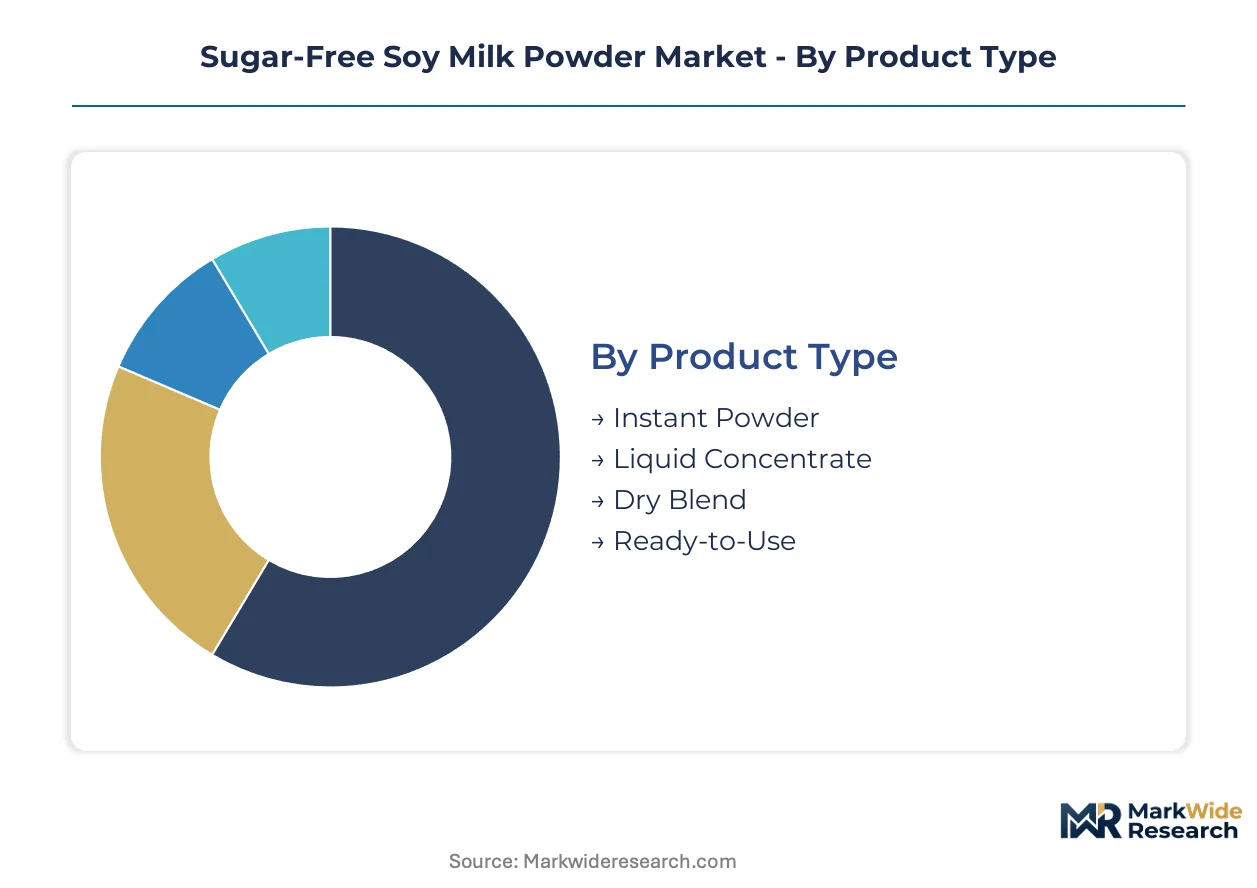
Segmentation in sugar-free soy milk powder reveals how enzymatic conversion capabilities and spray-drying scale concentrate supply relationships. Procurement leverage shifts dramatically across product formats and end-use channels, with nutritional sector buyers commanding stricter specification thresholds than food service operators.
Product Type:
Supply concentration clusters around processors with integrated crush-to-powder infrastructure and in-house spray-drying towers operating at 180-200°C inlet temperatures.
- Instant Powder:Spray-dried particles with rapid reconstitution properties dominate food service procurement in China's tier-one cities. Shanghai hotel chains and Beijing institutional cafeterias specify sub-30-second dispersion times for high-throughput beverage service.
- Dry Blend:Custom vitamin-mineral fortification for clinical nutrition commands premium positioning. Nutritional sector buyers in Germany and the Netherlands require mono- and disaccharide residuals below 0.3 grams per serving, compressing the qualified supplier base toward biotech-integrated operators.
- Liquid Concentrate:Reduced transport costs versus powder formats attract regional dairy alternatives processors in Brazil.
- Ready-to-Use:Shelf-stable RTD formats bypass reconstitution entirely, capturing convenience-oriented household demand in Japan.
Instant Powder absorbs the bulk of installed capacity; Dry Blend is expanding most quickly.
End User:
Cost tier differentiation separates specification-intensive buyers from price-sensitive mass market channels.
- Nutritional Sector:Clinical nutrition formulators and diabetic meal replacement manufacturers enforce the strictest sugar thresholds. FDA labeling enforcement on added sugars disclosure and China's SAMR GB standards compliance create dual qualification burdens for suppliers serving both markets.
- Food Service:Institutional operators in China's urban centers unbundle powder supply from equipment contracts. Multinational hotel chains now consolidate procurement at regional headquarters while outsourcing on-site preparation support separately.
- Household:Direct-to-consumer subscription platforms in North America bypass wholesale margin compression through custom fortification offerings.
- Retail:Private-label shelf placement competes on price positioning against branded organic lines in US health food channels.
Nutritional Sector commands the steepest expansion trajectory as clinical buyers tighten glycemic control specifications.
Distribution Channel:
Volume concentration in wholesale reflects manufacturing customer procurement patterns, while margin expansion concentrates in direct channels.
- Wholesale:Bulk procurement by bakery and beverage manufacturers sustains throughput for mid-scale spray-dryers. China's domestic soybean processing capacity expansion supports regional distributor consolidation.
- Online Retail:Subscription-based custom fortification platforms in North America capture recurring revenue with higher lifetime value than transactional wholesale accounts.
- Supermarkets:Mainstream retail placement requires competitive pricing against oat protein substitutes in barista-grade applications.
- Health Food Stores:Certified organic and non-GMO positioning supports premium shelf placement in Germany and Netherlands specialist channels.
Wholesale retains structural importance for volume; Online Retail is climbing the fastest as direct-to-consumer fortification scales.
Ingredient:
Customer type segmentation separates identity-preserved supply chains from commodity input sourcing.
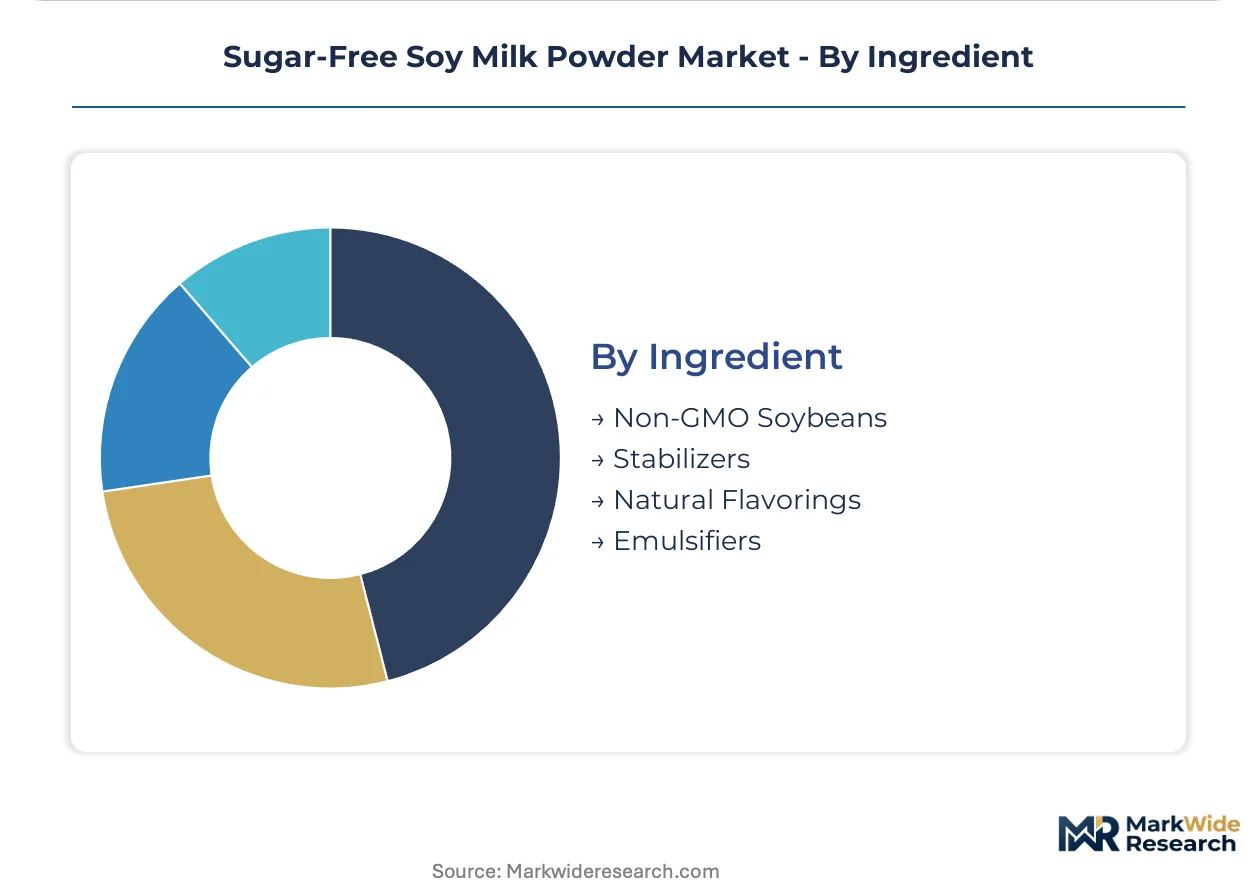
- Non-GMO Soybeans:Identity-preserved premiums in Brazil and the United States swing 15-40% seasonally, compressing margin visibility for organic-positioned brands. Backward integration into non-GMO crushing anchors supply security for scale processors.
- Stabilizers:Carrageenan and gellan gum selection affects reconstitution texture for instant powder applications in food service environments.
- Natural Flavorings:Vanilla and cocoa masking profiles target household consumers in North America subscription channels.
- Emulsifiers:Lecithin functionality supports fat dispersion in clinical nutrition formulations requiring precise caloric density.
Non-GMO Soybeans anchor supply chain configuration; Natural Flavorings is gaining share fastest as taste differentiation intensifies in direct channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement leverage through domestic soybean processing expansion and health-conscious urban consumption clusters. Germany and the Netherlands enforce the strictest glycemic thresholds for clinical nutrition imports. Brazil's identity-preserved soybean premiums create sourcing volatility for organic-positioned brands.
China
Shanghai and Beijing institutional cafeterias drive bulk procurement of instant powder formats with sub-30-second reconstitution specifications. SAMR's GB standards modernization tightens protein content claim thresholds, forcing facility upgrades among domestic spray-dryers seeking export certification. Yangtze River Delta processing clusters absorb the majority of enzymatic conversion capacity investments.
United States
FDA enforcement of added sugars disclosure on Nutrition Facts panels shapes formulation decisions for domestic and export-bound production. Clinical nutrition buyers in the Northeast and California expand procurement of enzymatically treated soy protein for diabetic meal replacements. Chicago and Minneapolis anchor spray-drying infrastructure serving North American contract manufacturing demand.
Germany
EFSA's 2023 plant protein digestibility guidance forces PDCAAS or DIAAS validation for quality assertions, extending product development cycles. Nutritional sector buyers in Hamburg and Munich qualify suppliers on mono- and disaccharide residuals below 0.3 grams per serving. Bavarian biotechnology clusters consolidate enzymatic precision capabilities for EU clinical nutrition supply.
Japan
METI-registered Foods for Specified Health Uses pathway offers premium positioning for isoflavone-fortified variants targeting sarcopenia prevention. Kanto and Kansai metropolitan areas concentrate senior nutrition channel demand. Tokyo-based formulators integrate carbon accounting preferences aligned with procurement policies under national dual carbon goals.
Brazil
Identity-preserved non-GMO soybean premiums swing 15-40% seasonally, compressing margin visibility for organic-positioned brands. São Paulo and Paraná processing clusters face competition from oat protein substitutes in barista-grade applications. Regional dairy alternatives processors explore liquid concentrate formats to reduce transport costs versus powder alternatives.
Sugar-Free Soy Milk Powder Market Competitive Landscape
Chinese producers anchor one tier through domestic soybean processing scale and SAMR-certified export infrastructure; North American specialists hold premium positioning through organic certification and direct-to-consumer channel control. The vendor base stratifies across integrated crush-to-powder operators, biotechnology-integrated processors with in-house enzymatic capabilities, and contract manufacturers serving institutional food service procurement. Competitive moves concentrate on backward integration into non-GMO soybean crushing and spray-drying capacity expansion.
Within the integrated multinational tier, Vitasoy International Holdings Limited and Archer Daniels Midland Company exemplify divergent strategic positioning. Vitasoy leverages Asian distribution infrastructure to anchor supply relationships with institutional operators. Archer Daniels Midland competes through upstream control over non-GMO soybean crushing and captive spray-drying capacity. Among North American specialists, Orgain represents direct-to-consumer archetype control through certified organic positioning and subscription platform integration.
| Leading Market Players |
|---|
| Yonho |
| Soyspring |
| GUKI |
| Now Foods |
| Silk |
| Bob's Red Mill |
| Orgain |
| Vitasoy International Holdings Limited |
| Archer Daniels Midland Company |
| Others |
Pricing and Supply Chain Analysis
Identity-preserved non-GMO soybean premiums in Brazil and the United States swing 15-40% seasonally, cascading through crush-to-powder operations into three-tier pricing stratification across premium organic, standard non-GMO, and economy commodity tiers. Procurement leverage concentrates among nutritional sector buyers enforcing mono- and disaccharide thresholds below 0.3 grams per serving, compressing margin visibility for processors lacking enzymatic conversion capabilities.
Pricing Analysis
Volume concentrates in wholesale contract manufacturing serving food service reconstitution demand, while margin expansion clusters in direct-to-consumer subscription platforms offering custom vitamin-mineral fortification. Price differentiation hinges on organic certification tier and spray-drying energy efficiency credentials. Cost compression in standard non-GMO tiers intensifies because oat protein substitutes capture barista-grade beverage applications. Nutritional sector buyers in Germany and the Netherlands exhibit lowest price sensitivity due to clinical formulation requirements, whereas private-label retail channels in North America face acute pressure from plant-based protein commoditization.
Supply Chain Analysis
Skilled technician availability in Yangtze River Delta processing clusters and Chicago-Minneapolis spray-drying corridors constrains enzymatic conversion capacity expansion. Supply concentrates in China, the United States, and Brazil, drawing from identity-preserved soybean crushing, membrane filtration equipment, and natural gas-fired inlet systems. Single-source vulnerability runs through Brazilian non-GMO seed stock propagation. Distribution runs through regional distributor consolidation in China's domestic processing expansion zones, with institutional procurement unbundling powder supply from equipment contracts in Shanghai and Beijing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugar-free soy milk powder sector sits in a technology-transition phase as enzymatic oligosaccharide reduction displaces legacy ultrafiltration for glycemic-controlled formulations.
For Market Incumbents: Cement spray-drying scale advantages through captive non-GMO crushing capacity in Brazil and the United States, insulating margin visibility from identity-preserved premium volatility. Invest in in-house biotechnology capabilities for enzymatic precision below 0.3 grams mono- and disaccharide residuals to defend qualification status with German and Dutch clinical nutrition buyers against oat protein substitution threats. For New Entrants and Emerging Players: Senior nutrition channels in Japan's METI-registered Foods for Specified Health Uses pathway offer underserved positioning for isoflavone-fortified sarcopenia prevention variants. Carbon-accounting-integrated processors with verified Scope 3 soybean traceability capture procurement preference under China's dual carbon goals. Deploy subscription-based custom fortification platforms to bypass wholesale margin compression in North America household segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor biotechnology-integrated mid-scale processors in China's Yangtze River Delta facing SAMR GB standards compliance upgrade costs. Long-term viability centers on enzymatic conversion IP and spray-drying energy efficiency positioning for EU CBAM exposure mitigation. Monitor EFSA novel food authorization pipeline velocity as inflection indicator for innovation pipeline thaw.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Non-GMO Crushing | Captive soybean supply anchors margin visibility against Brazilian premium volatility. |
| Enzymatic Conversion Capacity Expansion | In-house biotechnology capabilities compress qualified supplier base toward integrated operators. |
| Direct-to-Consumer Subscription Launch | Custom fortification platforms bypass wholesale margin compression in North America. |
| Carbon Accounting Integration | Verified Scope 3 traceability aligns with China's dual carbon procurement preferences. |
| Senior Nutrition Channel Certification | METI-registered FOSHU pathway unlocks premium positioning in Japan sarcopenia prevention. |
Research Methodology
Independent corroboration across spray-dryer operations managers, nutritional sector procurement directors, and enzymatic biotechnology specialists underwrites the qualitative findings. Primary interviews with institutional food service operators, clinical nutrition formulators, and SAMR compliance consultants combined with secondary validation from FDA labeling guidance, EFSA novel food registers, and China's GB standards documentation. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions span product format, end-user channel, distribution structure, and ingredient certification tier. CAGRs derive from installed spray-drying capacity utilization trajectories and enzymatic conversion adoption curves. Forecast inputs incorporate non-GMO soybean premium volatility patterns and EFSA authorization timeline distributions.
Revisions become necessary when EFSA novel food pathway durations extend beyond standard ranges, Brazilian identity-preserved premiums spike above seasonal bands, or oat protein substitution accelerates in food service reconstitution applications. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Low-Calorie Cream Market