
 Adaptogen Drink Market | 2026-2036
Adaptogen Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptogen Drink Market Insights
Premium functional-grade positioning is bifurcating the adaptogen drink landscape into clinically dosed formulations and lifestyle-oriented wellness products. Four Sigmatic leverages mycelial extraction technology to sustain its Nordic heritage positioning in mushroom-based beverages. Rebbl anchors its supply chain through ethically sourced botanical partnerships that dominate the coconut milk adaptogen segment. Rasa specializes in caffeine-free herbal alternatives that compete directly with conventional coffee rituals.
An adaptogen drink is a functional beverage containing standardized concentrations of botanical compounds such as ashwagandha root extract, reishi polysaccharides, or rhodiola rosavins, formulated to modulate cortisol response and support homeostatic balance. Manufacturing typically involves low-temperature extraction to preserve bioactive integrity, followed by aseptic filling for shelf-stable liquid formats or spray-drying for powder applications. Ready-to-drink formats command the deepest margin pools due to convenience premiums and refrigerated distribution control, while powder segments attract formulation flexibility among wellness enthusiasts and health coaches seeking customizable dosing. Tea-based delivery systems occupy a mature growth trajectory with established consumption rituals, whereas cognitive enhancement applications are capturing accelerated interest from nutraceutical retailers.
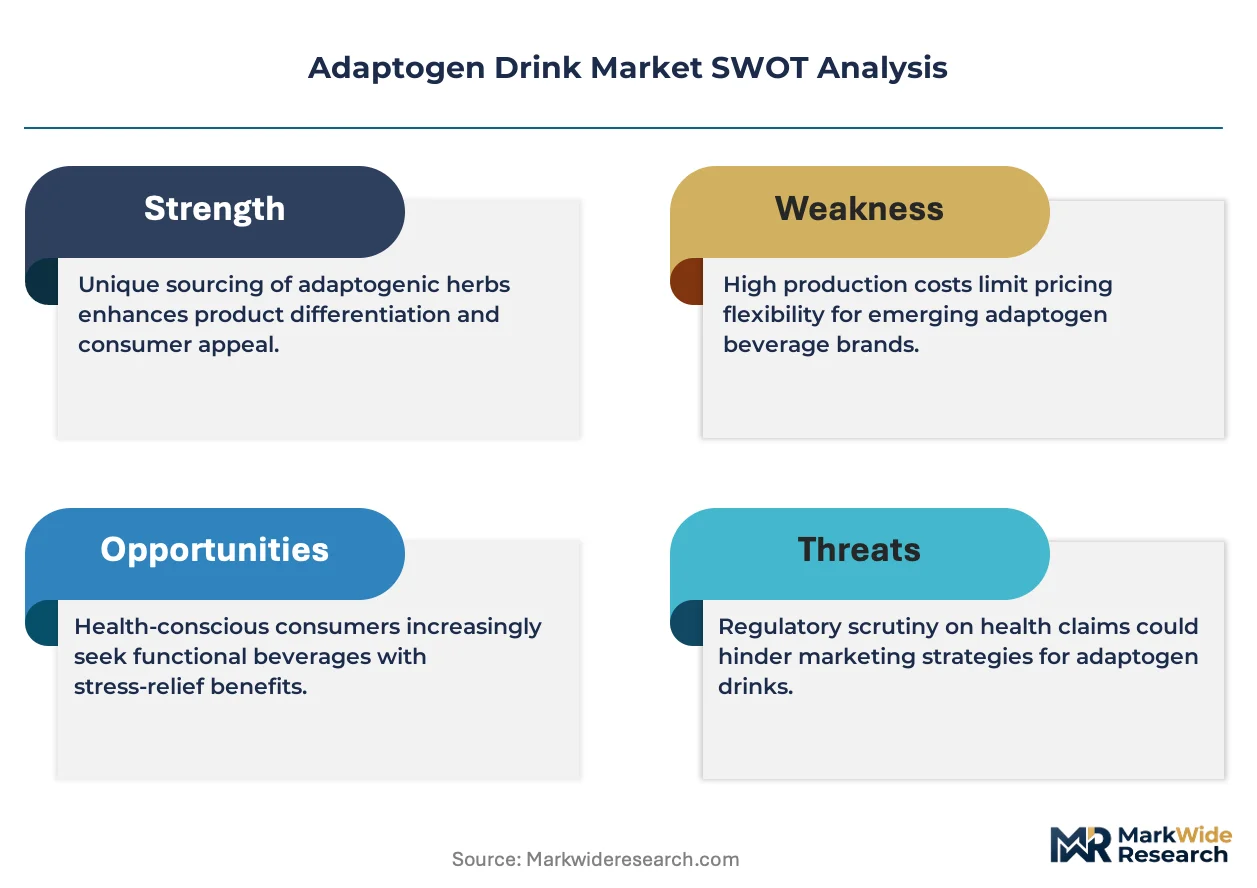
FDA oversight of dietary supplement labeling under DSHEA, EFSA novel food assessments for emerging botanical ingredients, and Health Canada NNHPD licensing requirements collectively determine market access timelines and substantiation burdens for adaptogen drink manufacturers. These frameworks compel brands to invest in clinical validation or restrict claims to structure-function language, directly influencing R&D allocation and regional launch sequencing. Stakeholders must monitor evolving enforcement patterns around adaptogenic health claims to anticipate which formulation categories will face expanded compliance obligations.
Market Dynamics
Clean-label formulation mandates from FDA and EFSA are forcing manufacturers to abandon synthetic excipients and standardize botanical extraction protocols, compressing product development timelines while elevating compliance costs across all production scales.
Growth Catalysts
- DSHEA-compliant structure-function claims:FDA's dietary supplement framework permits cortisol-modulation and homeostatic-balance language without full drug approval, accelerating market access for functional beverage entrants.
- Mushroom mycelial fermentation:Bioreactor-based cultivation of reishi and lion's mane mycelium is displacing wild harvesting, securing year-round supply consistency for ready-to-drink manufacturers.
- Direct-to-consumer subscription models:United States wellness enthusiasts are consolidating repeat purchases through brand-owned channels, bypassing retail margin stacking and capturing lifetime value data.
Market Restraints
- EFSA novel food assessment timelines:Emerging botanical ingredients such as ashwagandha extracts face 18-24 month safety evaluation windows, delaying European launches and freezing capital in pending applications.
- Wild-crafted herb supply concentration:Rhodiola rosea harvesting concentrates in Siberian and Altai Mountain regions, exposing formulations to geopolitical disruption and climate-induced yield volatility.
- Refrigerated distribution infrastructure gaps:Cold-chain requirements for live-culture and fresh-pressed adaptogen SKUs limit penetration into rural and developing markets lacking temperature-controlled logistics.
Strategic Opportunities
- India Ayurveda export corridor:FSSAI-certified manufacturing facilities in Kerala and Karnataka offer GMP-compliant production at cost structures 40% below Western equivalents, enabling price-competitive entry into Middle Eastern markets.
- Workplace wellness vending integration:Corporate campus micro-markets and tech-sector pantries represent underpenetrated channels where employers subsidize stress-management beverages as productivity tools.
- ISO 22000 certification convergence:Harmonized food safety management standards are reducing multi-market audit burdens, allowing single-facility production for simultaneous FDA, EFSA, and Health Canada compliance.
Industry Challenges
- Phytochemistry standardization expertise:Brands lack in-house analytical chemists capable of validating rosavin, withanolide, and polysaccharide content consistency across harvest batches, forcing reliance on third-party laboratories with 6-8 week turnaround times.
- Aseptic filling capex requirements:Shelf-stable liquid formats demand $4-8 million tunnel pasteurization and sterile bottling lines, creating capital barriers for mid-scale entrants competing against powder-format alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptogen Drink Market |
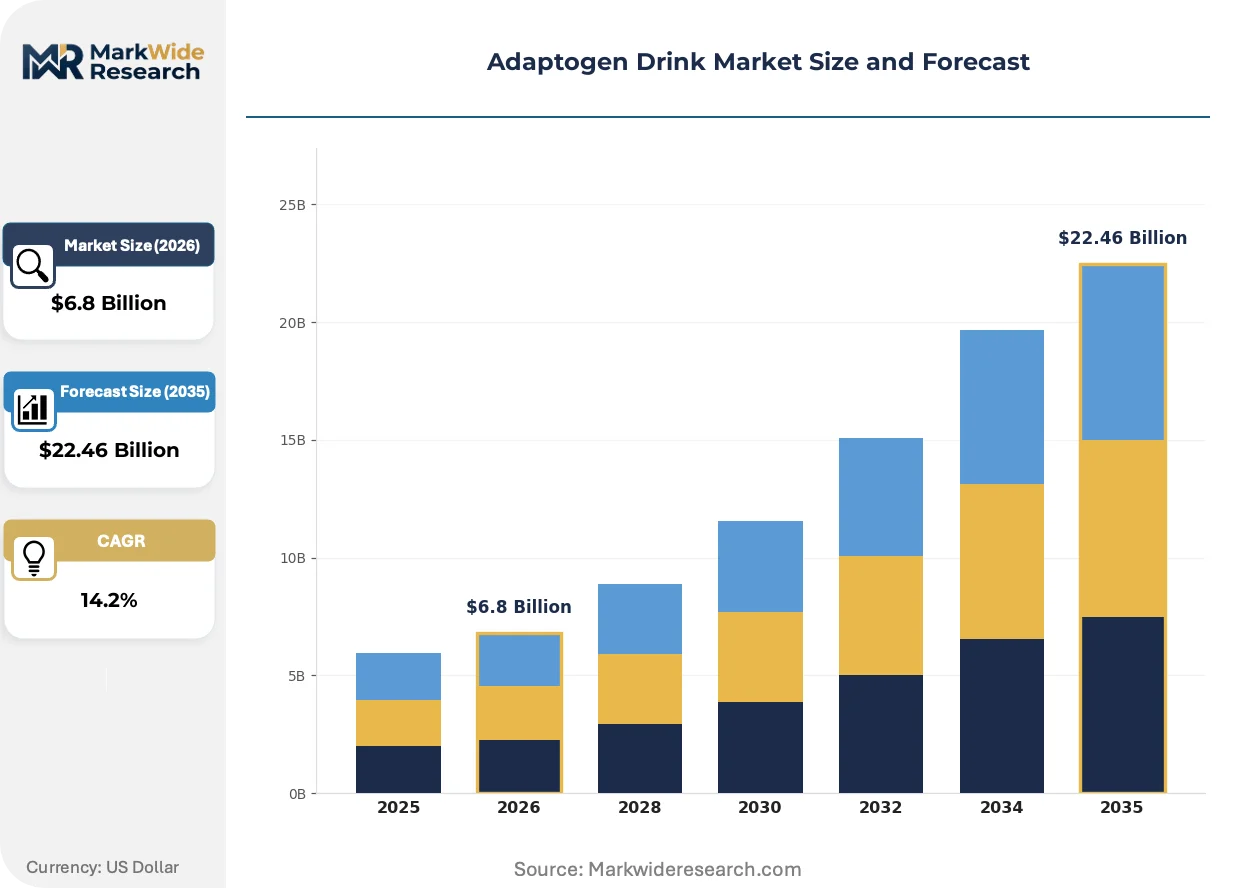
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid Extract, Tea, Ready-to-Drink, Capsules Formulation: Herbal Blend, Single Extract, Fruit Infused, Spiced, Botanical Mix Application: Stress Relief, Cognitive Enhancement, Immune Support, Energy Boost, Mood Improvement Customer Type: Wellness Enthusiasts, Fitness Centers, Nutraceutical Retailers, Health Coaches, Lifestyle Clinics |
| Companies Covered | Rebbl, Four Sigmatic, Kin Euphorics, Sunwink, Wylde One, Goodmylk Co., Moon Juice, Rasa, Om Mushroom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptogen Drink Market Trends and Innovations
Extraction technology maturation and regulatory claim standardization are converging to separate clinically substantiated formulations from lifestyle-positioned wellness products, creating distinct competitive arenas with divergent R&D investment profiles.
Ultrasonic-assisted extraction using ethanol-water gradients is supplanting conventional heat-based methods in premium manufacturing facilities. This technology preserves heat-labile triterpenes in reishi and betulinic acid compounds in chaga, enabling brands to market standardized bioactive concentrations that justify price premiums above commodity mushroom powders. Contract manufacturers in Oregon and Vermont are retrofitting production lines to accommodate this equipment, compressing batch processing times from 48 hours to 6 hours while improving yield recovery rates.
EFSA's 2023 guidance on botanical health claims is tightening substantiation requirements for adaptogen-related cortisol and stress-response language. Manufacturers must now compile human intervention studies or restrict claims to general wellness maintenance, compelling brands to allocate 15-20% of operating budgets to clinical validation partnerships with European universities. German and Dutch regulatory consultants are experiencing 300% inquiry volume increases as brands navigate novel food versus food supplement classification boundaries.
Health coaches and functional medicine practitioners are consolidating purchasing influence through collective buying platforms that aggregate orders across clinical practices. These professional networks negotiate direct-from-manufacturer pricing that undercuts distributor markups by 25-35%, forcing legacy wholesale channels to unbundle educational content and formulation support as value-adds. California and Colorado wellness practitioner cooperatives are pioneering this procurement evolution, with similar models emerging in Ontario and British Columbia naturopathic networks.
Adaptogen Drink Market Segmentation
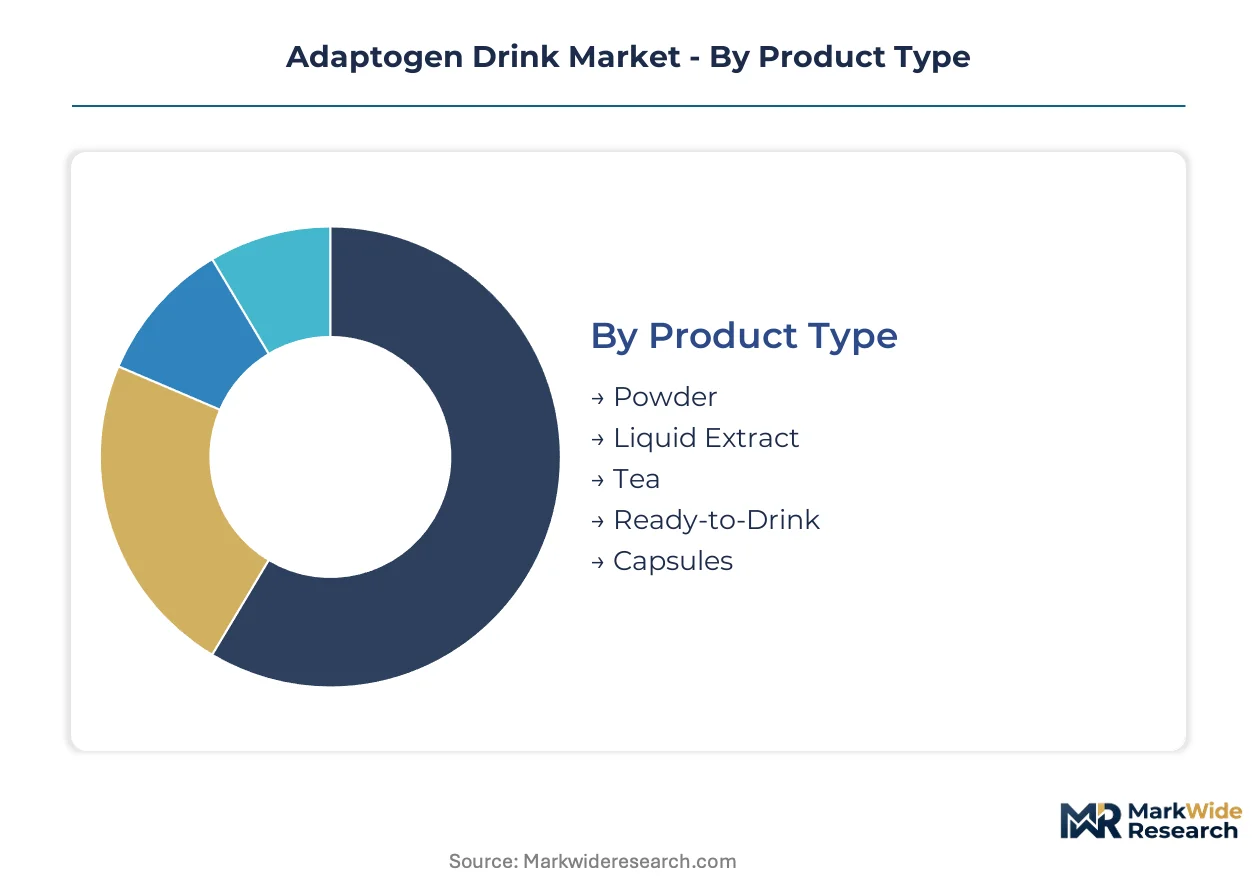
Channel distribution patterns vary sharply across adaptogen drink formats, with refrigerated ready-to-drink SKUs commanding premium shelf placement while powders flow through practitioner networks. Understanding these segment-channel linkages reveals where margin pools concentrate and which formulations justify cold-chain infrastructure investment.
Product Type:
Ready-to-drink formats dominate convenience retail and direct-to-consumer subscription channels, while powders capture practitioner-directed volume through health coach networks.
- Ready-to-Drink:Shelf-stable liquid formulations in aseptic bottles or refrigerated cans deliver standardized dosing for on-premise consumption. United States specialty grocers and corporate micro-markets drive repeat purchase velocity through cold-case placement.
- Powder:Spray-dried extracts enable customizable dosing protocols favored by functional medicine practitioners. Health coach cooperatives in California and Colorado aggregate bulk orders that bypass traditional distributor markups.
- Liquid Extract:Concentrated tinctures requiring dilution appeal to ritual-oriented consumers seeking precise titration control.
- Tea:Traditional delivery systems leverage established consumption ceremonies with lower per-unit pricing and broader retail accessibility.
- Capsules:Encapsulated formats compete directly with supplement aisles rather than beverage channels, carrying distinct regulatory classification requirements.
Ready-to-drink dominates installed base. Powder is where expansion concentrates.
Formulation:
Cost tier stratification separates clinically validated single extracts from lifestyle-positioned blends, with premium pricing attached to bioactive standardization.
- Single Extract:Isolated botanical concentrates such as KSM-66 ashwagandha or reishi polysaccharide extracts enable precise structure-function claims under FDA DSHEA guidelines. Nutraceutical retailers in the United States demand third-party validated rosavin and withanolide content for premium positioning.
- Herbal Blend:Multi-botanical formulations combine adaptogens with complementary nervines and trophorestoratives. Wellness enthusiasts seeking ritual complexity drive volume through subscription channels that emphasize flavor profile differentiation.
- Botanical Mix:Functional beverage hybrids incorporating non-adaptogen botanicals for targeted physiological effects.
- Fruit Infused:Palatability-focused formulations masking earthy adaptogen notes with natural fruit concentrates for mass-market acceptance.
- Spiced:Ayurvedic-inspired flavor profiles leveraging cardamom, ginger, and cinnamon for digestive synergy claims.
Single extract commands the steepest price premiums. Herbal blend is climbing the fastest in absolute volume terms.
Application:
Customer type determines which benefit claims resonate, with corporate wellness programs prioritizing productivity-linked outcomes over general wellness positioning.
- Stress Relief:Cortisol-modulation formulations targeting HPA axis regulation represent the largest addressable application. Workplace wellness vending integrations in United States tech campuses specifically subsidize these SKUs as productivity tools.
- Cognitive Enhancement:Nootropic-adaptogen combinations featuring lion's mane and rhodiola capture accelerated interest from nutraceutical retailers. EFSA's tightened botanical health claim requirements are forcing manufacturers toward general wellness maintenance language in European markets.
- Immune Support:Reishi and chaga polysaccharide formulations positioned for immunomodulation.
- Energy Boost:Rhodiola and cordyceps combinations competing with conventional caffeine delivery systems.
- Mood Improvement:Serotonergic and GABAergic adaptogen pairings targeting affective balance.
Stress relief dominates installed base. Cognitive enhancement is where expansion concentrates.
Customer Type:
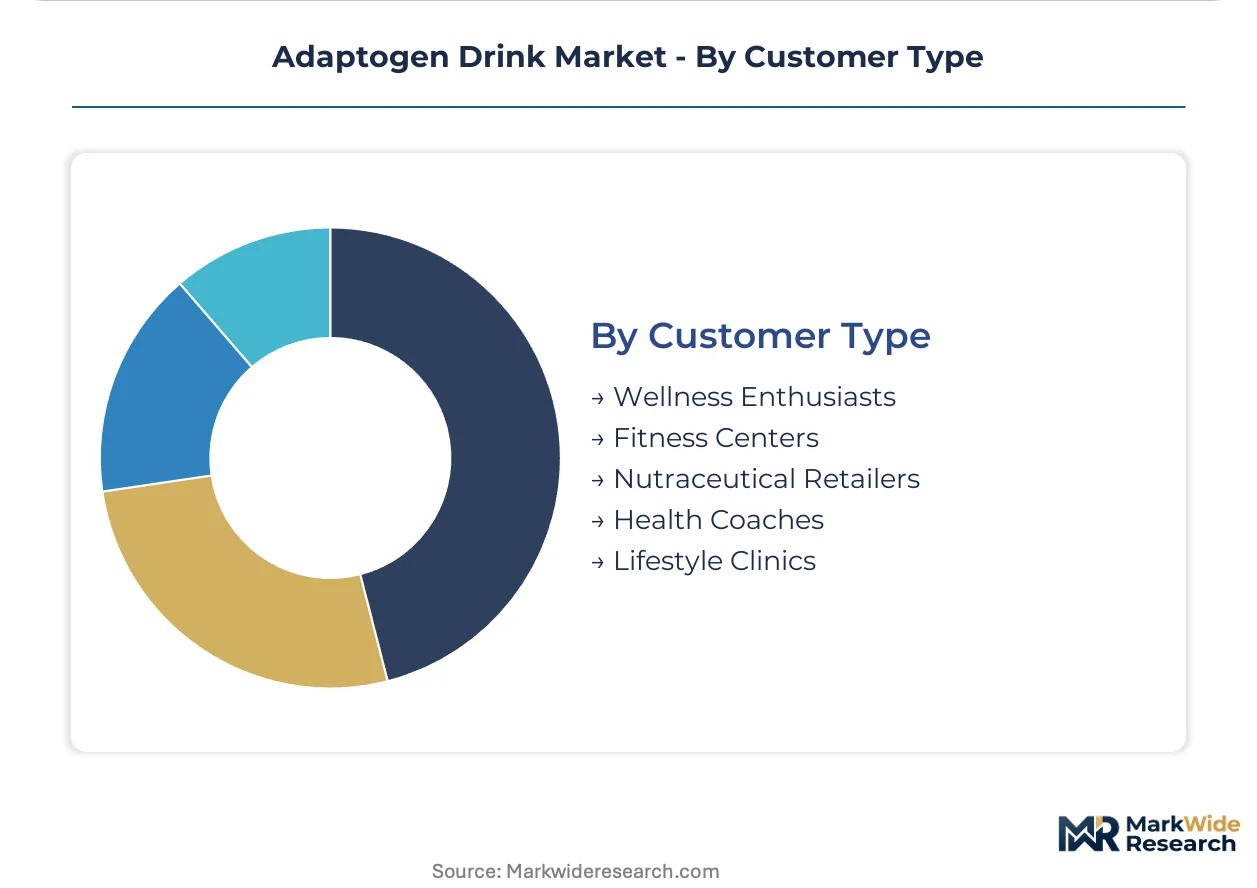
Volume concentration varies by procurement sophistication, with practitioner networks consolidating purchasing power through collective buying platforms.
- Health Coaches:Functional medicine practitioners and certified health coaches exercise disproportionate influence through recommendation authority. Ontario and British Columbia naturopathic networks are pioneering cooperative procurement models that aggregate clinical practice orders for manufacturer-direct pricing.
- Wellness Enthusiasts:Direct-to-consumer subscribers prioritize convenience and brand narrative alignment over clinical validation. United States urban clusters demonstrate the deepest penetration of mushroom-based ritual replacements for conventional coffee consumption.
- Nutraceutical Retailers:Specialty supplement chains demanding third-party testing documentation and structure-function claim compliance.
- Fitness Centers:On-premise consumption venues seeking post-workout recovery positioning for adaptogen beverages.
- Lifestyle Clinics:Integrative medicine facilities incorporating adaptogen protocols into comprehensive patient management programs.
Wellness enthusiasts dominate installed base. Health coaches represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for adaptogen beverages tilt toward net imports across Western European markets, while India and China maintain surplus positions in raw botanical extraction. The United States absorbs the deepest volume concentration through direct-to-consumer channels.
United States
Wellness enthusiasts in California and Colorado drive subscription-based repeat purchases through brand-owned digital channels. FDA DSHEA framework permits structure-function claims for cortisol-modulation language without full drug approval. Brooklyn and Austin host the densest clustering of mushroom-based beverage startups leveraging mycelial fermentation technologies.
Germany
EFSA novel food assessment requirements create 18-24 month entry delays for ashwagandha and emerging botanical extracts. German regulatory consultants in Berlin and Munich report 300% inquiry volume increases as brands navigate food supplement classification boundaries. Bavaria houses GMP-certified contract manufacturers serving pan-European distribution.
India
FSSAI-certified facilities in Kerala and Karnataka offer production cost structures 40% below Western equivalents, enabling competitive Middle Eastern export positioning. The country's Ayurveda heritage supports standardized ashwagandha root extract supply for global formulation houses. Mumbai and Bangalore concentrate adaptogen R&D partnerships between domestic extractors and international brands.
Canada
Health Canada NNHPD licensing requirements compel clinical validation investments for stress-relief positioning in domestic retail. Ontario and British Columbia naturopathic networks pioneer cooperative procurement models aggregating clinical practice orders. Vancouver hosts the deepest penetration of mushroom-based ritual replacements for conventional coffee consumption.
Australia
TGA therapeutic goods classification creates dual pathways for adaptogen beverages as either food supplements or listed medicines. Sydney and Melbourne wellness practitioner networks consolidate purchasing influence through collective buying platforms. Queensland agricultural zones supply native botanical candidates for novel adaptogen formulation pipelines.
Adaptogen Drink Market Competitive Landscape
Concentration sits with clinically positioned single-extract specialists and lifestyle-oriented wellness blenders, creating a bifurcated structure where premium pricing attaches to bioactive standardization. The vendor base separates into three archetypes: mycelial fermentation technologists, ethically sourced botanical partnerships, and caffeine-free herbal alternative formulators. Capacity expansion through bioreactor-based cultivation and strategic partnerships with FSSAI-certified Indian extractors represent the dominant competitive vectors.
Within the Nordic heritage positioning tier, Four Sigmatic exemplifies mycelial extraction technology deployment. Rebbl anchors the ethically sourced botanical partnership model in coconut milk adaptogen segments. Rasa occupies the caffeine-free herbal alternative position competing directly with conventional coffee rituals.
| Leading Market Players |
|---|
| Rebbl |
| Four Sigmatic |
| Kin Euphorics |
| Sunwink |
| Wylde One |
| Goodmylk Co. |
| Moon Juice |
| Rasa |
| Om Mushroom |
| Others |
Pricing and Supply Chain Analysis
Bioreactor-scale mycelial fermentation capacity in Oregon and Vermont compresses unit economics for shelf-stable liquid formats, concentrating supply-side leverage among facilities with tunnel pasteurization investments while elevating price floors for mid-scale powder competitors lacking comparable scale.
Pricing Analysis
Health coach cooperatives anchor pricing stratification across premium, standard, and economy tiers through collective procurement platforms that negotiate manufacturer-direct discounts. Price differentiation hinges on bioactive standardization certification and volume scale, with clinically validated single extracts commanding premiums above lifestyle blends. Cost compression in the standard tier intensifies as FSSAI-certified Indian extractors expand Middle Eastern export volumes. Wellness enthusiasts demonstrate lowest price sensitivity for subscription-based convenience, while nutraceutical retailers drive hardest bargain through third-party testing requirements.
Supply Chain Analysis
Strategic stockpiling of rhodiola rosea root dominates inventory strategy among European formulators facing Siberian harvest volatility, whereas United States ready-to-drink manufacturers prefer just-in-time mycelial biomass delivery from domestic bioreactors. Raw material sourcing draws from India for ashwagandha extracts, Siberia and the Altai Mountains for rhodiola, and domestic cultivation facilities for reishi and lion's mane mycelium. Single-source vulnerability concentrates in wild-crafted herb harvesting regions exposed to geopolitical disruption. Distribution runs through direct-to-consumer subscription channels and refrigerated specialty retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptogen beverage penetration remains in early-cycle expansion, with workplace wellness vending integrations representing substantial untapped volume concentration among United States tech campuses.
For Market Incumbents: Consolidate supply chain control through backward integration into FSSAI-certified extraction facilities in Kerala and Karnataka, securing cost structures below Western equivalents. Defend margin position by accelerating ISO 22000 certification convergence to reduce multi-market audit burdens. Counter emerging entrant pressure in the caffeine-free herbal alternative segment through clinical validation partnerships that substantiate structure-function claims. For New Entrants and Emerging Players: Practitioner-directed procurement gaps in Ontario and British Columbia naturopathic networks offer the most penetrable white-space entry. Target health coach cooperatives aggregating clinical practice orders with manufacturer-direct pricing undercutting legacy wholesale markups. Launch through collective buying platforms emphasizing formulation education and customizable dosing protocols. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mycelial fermentation specialists with proprietary extraction protocols over commodity botanical blenders. Long-term viability across the projection horizon rests on clinical validation capabilities enabling regulatory compliance across FDA, EFSA, and Health Canada frameworks. Monitor EFSA enforcement patterns around adaptogenic health claims as the inflection indicator for which formulation categories face expanded substantiation burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Domestic mycelial fermentation secures year-round supply consistency for ready-to-drink manufacturers. |
| Clinical Validation Partnership | European university collaborations enable EFSA-compliant structure-function claims for cortisol-modulation language. |
| Direct-to-Consumer Platform Launch | Brand-owned subscription channels bypass retail margin stacking and capture lifetime value data. |
| FSSAI-Certified Manufacturing Footprint | Kerala and Karnataka facilities enable price-competitive entry into Middle Eastern export markets. |
| Workplace Wellness Vending Integration | Corporate campus micro-markets position stress-management beverages as employer-subsidized productivity tools. |
Research Methodology
The analysis maps ready-to-drink, powder, and liquid extract sub-sectors, each validated through formulation scientists, health coach network coordinators, nutraceutical retail buyers, and contract manufacturing executives. Primary interviews with Oregon and Vermont bioreactor operators, Kerala extraction facility managers, and German regulatory consultants combined with secondary validation from FDA DSHEA guidance documents, EFSA novel food assessment records, FSSAI certification registries, and Health Canada NNHPD licensing databases. Bottom-up volume aggregation across product type, formulation, application, and customer type segments triangulates against top-down market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. The analytical framework incorporates product type, formulation tier, application use case, customer procurement sophistication, and regional regulatory cluster as segmentation dimensions. CAGRs derive from adoption curve modeling calibrated to wellness enthusiast subscription velocity and health coach cooperative expansion trajectories. Forecast inputs include mycelial fermentation capacity utilization rates and EFSA novel food assessment pipeline backlogs.
Forecasts assume regulatory continuity in FDA DSHEA enforcement, EFSA botanical health claim guidance, and Health Canada NNHPD licensing frameworks; material policy shifts would require re-modeling. Specific risk factors include EFSA substantiation requirement tightening, Siberian harvest disruption from climate-induced yield volatility, and refrigerated distribution infrastructure gaps in rural markets. Revision becomes warranted when health coach cooperative procurement penetration crosses threshold levels that fundamentally restructure legacy wholesale channel economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Vegan Protein Bars Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Antioxidant Beverages Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Functional Dairy Products Market