
 Vegan Cheese Alternatives Market | 2026-2036
Vegan Cheese Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Cheese Alternatives Market Insights
Foodservice buyer concentration is expanding as major restaurant chains and institutional catering networks consolidate procurement around dedicated plant-based suppliers. Daiya Foods leverages its manufacturing scale to anchor North American foodservice contracts. Violife competes through its specialized positioning in European retail channels.
Vegan cheese alternatives denote non-dairy formulations engineered from plant lipids, starches, and proteins to replicate the melt, stretch, and flavor profiles of conventional cheese, typically achieving 15-30% fat content through emulsion technology. These products serve commercial food manufacturing and retail consumption where allergen exclusion and lactose intolerance drive specification requirements. Shredded cheese formats lead volume due to pizza and prepared meal applications, while cashew-based formulations command premium positioning in specialty shops. Coconut oil bases dominate mass-market production because of their cost structure and functional stability.
FDA labeling standards and EFSA novel food frameworks shape ingredient approval timelines and nutritional claim permissibility across major supply destinations. USDA organic certification and EU organic regulations create tiered market access conditions that filter producer participation. Stakeholders must monitor evolving protein fortification standards and front-of-pack labeling mandates as these frameworks determine which formulations qualify for health-positioned retail placement.
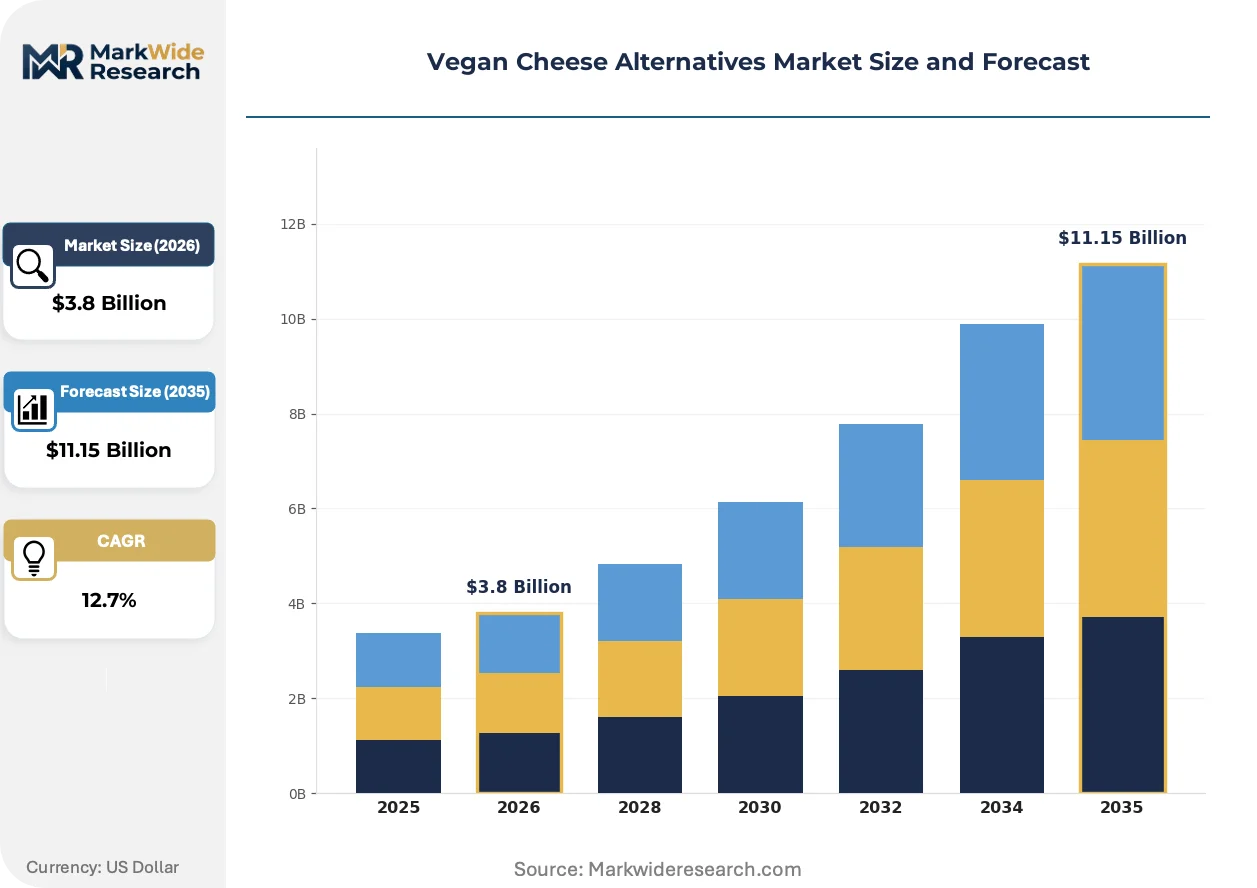
Market Dynamics
Foodservice procurement consolidation is compressing supplier margins while EFSA novel food frameworks accelerate ingredient approval timelines, creating a bifurcated market where scale players anchor chain contracts and specialty formulators capture premium retail positioning.
Growth Catalysts
- EFSA Novel Food Regulations:Accelerated safety review protocols in Europe are compressing time-to-market for new protein sources and lipid alternatives, enabling faster product pipeline expansion.
- Cashew Protein Fermentation:Advanced enzymatic processing is improving melt and stretch functionality in premium formulations, opening foodservice pizza and prepared meal applications previously closed to plant-based alternatives.
- German Retail Concentration:Discounter and supermarket chain expansion of dedicated plant-based sections is creating shelf-space pull-through that drives manufacturing volume commitments.
Market Restraints
- Coconut Oil Price Volatility:Tropical supply disruptions and weather pattern instability are creating input cost swings that compress mass-market margins.
- Emulsion Stability Ceiling:Current lipid-protein binding technologies hit functional limits above 30% fat content, constraining flavor replication in hard cheese alternatives.
- USDA Organic Certification Bottlenecks:Processing facility compliance timelines and ingredient traceability requirements are extending product launch cycles by 8-14 months for certified organic positioning.
Strategic Opportunities
- Precision Fermentation Lipids:Convergence of microbial engineering and downstream processing is enabling animal-identical fat structures without agricultural supply chain dependencies.
- Quick-Service Restaurant Breakfast:Morning daypart menu expansion into egg-and-cheese sandwiches represents underpenetrated volume opportunity for slice and sauce formats.
- EU Green Deal Procurement Mandates:Public sector catering contracts with carbon footprint disclosure requirements are creating specification advantages for low-impact manufacturing processes.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation chemistry expertise spanning emulsion science, protein functionality, and sensory mapping remains concentrated among a narrow specialist cohort.
- Dual Certification Complexity:Simultaneous pursuit of USDA Organic and EU organic equivalence demands parallel documentation systems that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Cheese Alternatives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.15 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Cheese, Shredded Cheese, Slices, Blocks Base Ingredient: Coconut Oil, Almonds, Cashews, Soybeans Packaging Type: Plastic Tub, Pouch, Jar, Bulk Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Daiya Foods, Violife, Miyoko's Creamery, Follow Your Heart, Kite Hill, Treeline Cheese, Parmela Creamery, Chao Cheese, Nurishh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Cheese Alternatives Market Trends and Innovations
Fermentation-derived ingredients and precision processing are fragmenting traditional supply relationships while regulatory disclosure mandates reshape competitive differentiation around verified sustainability metrics.
Precision fermentation of dairy-identical proteins is decentralizing raw material sourcing away from tropical agriculture dependencies. Specialty ingredient startups are licensing strains to contract manufacturers, enabling regional production hubs that bypass commodity lipid markets. This technology is decentralizing supply chain risk and compressing the geographic radius between production and consumption.
EFSA's updated novel food guidance on microbial biomass is tightening safety documentation requirements for fermentation-derived ingredients. Manufacturers must submit extended toxicology dossiers that extend approval timelines and favor well-capitalized applicants with dedicated regulatory affairs functions. European retail channels are responding by prioritizing suppliers with established novel food approvals over unvalidated newcomers.
Direct-to-foodservice distribution is bypassing traditional broker networks as chain procurement teams build in-house plant-based category expertise. Major restaurant operators are conducting supplier audits and co-development agreements that lock in exclusive formulations. This pattern is most visible in Germany and the Netherlands where institutional catering contracts specify local manufacturing proximity.
Vegan Cheese Alternatives Market Segmentation
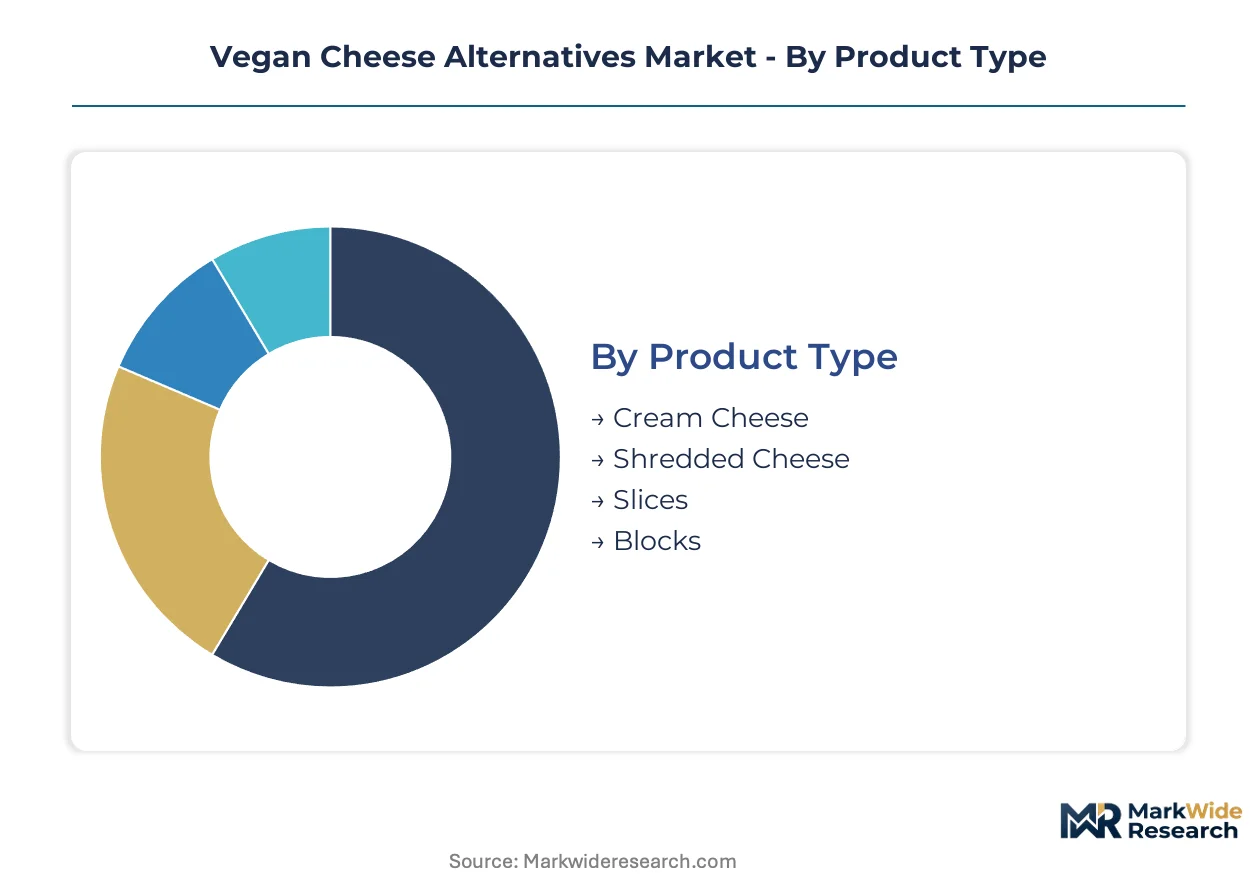
Vegan cheese alternatives fragment across functional formats, lipid bases, and procurement channels that each carry distinct margin profiles and specification requirements. Understanding these segment boundaries reveals where manufacturing scale advantages concentrate versus where premium positioning commands price premiums.
Product Type:
Format selection tracks directly to end-use application cycles, with foodservice operators refreshing formulations quarterly while retail consumers exhibit stronger brand loyalty within familiar formats.
- Shredded Cheese:Engineered for melt and stretch performance through modified starch-protein matrices, this format dominates pizza chain procurement in Germany and quick-service sandwich applications where bulk melting consistency drives specification. EFSA emulsion stability standards constrain fat content ceilings, limiting hard cheese replication.
- Cream Cheese:Spreadable formulations leverage high-moisture cashew or coconut oil bases with stabilizer systems for bagel and dessert applications. Demand concentrates in North American retail channels where breakfast occasion expansion and dairy-free bakery integration sustain volume commitments.
- Slices:Processed singles for sandwich assembly rely on coconut oil-dominant cost structures with carrageenan binding for sheet integrity. Institutional catering contracts in the Netherlands specify local manufacturing proximity for this format.
- Blocks:Hard cheese alternatives for shredding or crumbling employ fermented cashew protein with extended aging protocols. Specialty shops in France and Switzerland capture premium positioning through artisanal production narratives.
Shredded cheese sits at the top of the volume ranking, with cream cheese climbing the fastest as breakfast daypart menu expansion accelerates.
Base Ingredient:
Raw material selection determines cost tier positioning and supply chain risk exposure, with tropical agriculture dependencies creating margin volatility that precision fermentation technologies aim to displace.
- Coconut Oil:Refined and fractionated tropical lipids provide functional stability at mass-market price points through established commodity supply chains. Weather pattern disruptions in Southeast Asia create input cost swings that compress margins for standard-format producers.
- Cashews:High-protein tree nuts enable premium melt behavior and clean-label positioning through enzymatic processing. Fermentation-derived cashew protein alternatives are gaining share fastest in European specialty channels as EFSA novel food approvals accelerate.
- Almonds:California-sourced nuts support allergen-conscious formulations with lighter flavor profiles suited to European retail preferences. Water scarcity constraints in the Central Valley are forcing supply diversification into Spanish and Italian orchards.
- Soybeans:Legacy protein base with established processing infrastructure retains foodservice volume through cost efficiency, though GMO and allergen concerns limit premium channel access. USDA organic certification bottlenecks extend launch timelines for certified positioning.
Coconut oil commands the volume lead, with cashew-based formulations expanding most quickly as precision processing improves functionality.
Packaging Type:
Packaging selection reflects channel destination and shelf-life requirements, with sustainability mandates reshaping material specifications across European retail.
- Plastic Tub:Injection-molded polypropylene containers dominate cream cheese and spreadable formats through established dairy industry supply chains. German discounters are driving recycled content mandates that increase unit costs.
- Pouch:Flexible film structures for shredded cheese reduce transport cube and enable high-speed filling. Stand-up pouch adoption is climbing fastest in online retail channels where shipping efficiency matters.
- Jar:Glass containers support premium positioning and extended shelf stability for fermented block formats. Swiss and French specialty retailers specify jar packaging for artisanal product lines.
- Bulk:Foodservice totes and pails for institutional catering minimize per-unit packaging cost. EU Green Deal procurement mandates are creating specification advantages for returnable bulk systems in Netherlands public sector contracts.
Plastic tub formats retain volume leadership, with pouch structures gaining share fastest as e-commerce penetration deepens.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth, with direct procurement consolidation compressing traditional broker networks.
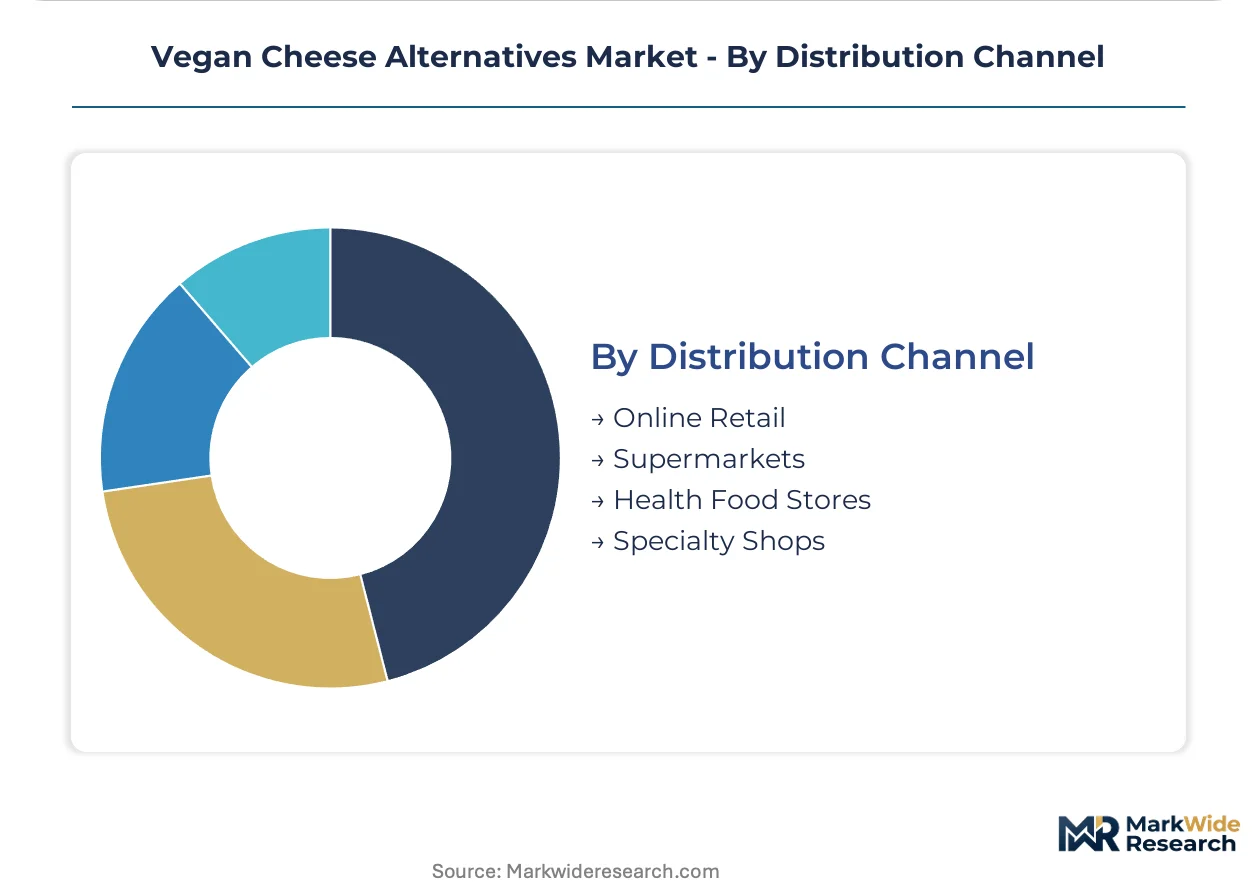
- Supermarkets:Chain-controlled shelf space and promotional calendars dominate mass-market volume in Germany, where dedicated plant-based section expansion creates pull-through. Retailer private label development is displacing branded placement in standard formats.
- Online Retail:Direct-to-consumer and platform-based sales enable subscription models and flavor variety exploration. Cold chain logistics investments are expanding geographic reach fastest for premium formulations.
- Health Food Stores:Curated assortments and educated staff support premium positioning and ingredient transparency narratives. Independent channel consolidation in France and Italy is reducing supplier count per door.
- Specialty Shops:Artisanal cheese retailers and vegan boutiques command highest price realization for fermented block and aged formats. Local manufacturing proximity requirements in Netherlands institutional contracts are bypassing this channel for foodservice volume.
Supermarkets anchor volume rankings, with online retail climbing fastest as fulfillment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and formulation chemists cluster in Germany's Ruhr industrial belt, California's Sacramento Valley, and Switzerland's Lake Geneva corridor, anchoring regional innovation capacity for emulsion science and protein functionality development.
Germany
Discounter chains Aldi and Lidl are expanding dedicated plant-based sections, pulling manufacturing volume commitments from suppliers. EFSA novel food regulations are accelerating safety review timelines for new protein sources. The Cologne-Düsseldorf corridor hosts contract manufacturing hubs serving Dutch institutional catering contracts with local proximity requirements.
United States
Quick-service restaurant chains are consolidating procurement around dedicated plant-based suppliers for breakfast sandwich applications. FDA labeling standards determine nutritional claim permissibility across interstate commerce. California's Sacramento Valley anchors precision fermentation startup clusters developing microbial lipid alternatives to tropical agriculture dependencies.
Netherlands
Institutional catering networks are specifying carbon footprint disclosure requirements under EU Green Deal procurement mandates. EFSA emulsion stability standards constrain fat content ceilings in hard cheese replication. The Rotterdam port cluster handles bulk ingredient imports for foodservice totes serving public sector contracts with returnable bulk system specifications.
Switzerland
Specialty retailers are commanding premium price realization for artisanal fermented block formats in Geneva and Zurich boutique channels. Swissmedic maintains alignment with EFSA novel food frameworks for cross-border retail placement. The Lake Geneva corridor concentrates food technologist talent for enzymatic processing applications in aged cheese alternatives.
United Kingdom
Supermarket chains are displacing branded placement with private label development in standard shredded formats. REACH compliance requirements shape ingredient sourcing for emulsion stabilizers and binding agents. Greater Manchester hosts distribution hubs for flexible film pouch structures gaining share in online retail channels.
Vegan Cheese Alternatives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with scale players anchoring North American foodservice contracts and specialty formulators capturing European retail premium positioning. The vendor base separates into three strategic archetypes: mass-market manufacturers leveraging coconut oil cost structures, premium cashew-based artisanal producers, and precision fermentation technology licensors. M&A activity concentrates on capacity expansion in German contract manufacturing, while strategic partnerships lock in exclusive formulations for quick-service restaurant chains.
Within the mass-market manufacturing tier, Daiya Foods exemplifies scale-driven North American foodservice anchoring, while Violife occupies a position specialized in European retail channel penetration. Miyoko's Creamery represents the artisanal premium archetype with fermented cashew protein positioning in specialty shops. These three players illustrate the geographic and tier-based segmentation that defines competitive positioning across procurement channel consolidation.
| Leading Market Players |
|---|
| Daiya Foods |
| Violife |
| Miyoko's Creamery |
| Follow Your Heart |
| Kite Hill |
| Treeline Cheese |
| Parmela Creamery |
| Chao Cheese |
| Nurishh |
| Others |
Pricing and Supply Chain Analysis
Food technologist clusters in Germany's Ruhr industrial belt and California's Sacramento Valley create labor-cost differentials that widen pricing-tier spreads between precision-fermentation premium formulations and commodity coconut-oil mass-market products.
Pricing Analysis
Bundled co-development agreements with quick-service restaurant chains command premium pricing through exclusive formulation lock-ins, while unbundled spot procurement for retail shredded formats competes on unit economics. Three-tier pricing structure across premium fermented blocks, standard coconut-oil slices, and economy private-label shreds reflects EFSA novel food certification costs and volume scale. Pricing pressure stems from German discounter private-label expansion displacing branded placement. Foodservice operators exhibit lowest price sensitivity due to menu-margin absorption, while retail consumers in supermarket channels drive hard bargaining.
Supply Chain Analysis
Reverse-logistics flows for returnable bulk totes serving Netherlands institutional catering contracts create circular-economy specifications that filter supplier participation. Raw material sourcing concentrates in Southeast Asia for coconut oil, California and Southern Europe for almonds, and India for cashew protein. Fermentation-derived lipid alternatives draw from contract manufacturing hubs in Germany and the Netherlands. Single-source vulnerability in tropical agriculture dependencies exposes margins to weather-driven commodity swings. Distribution runs through direct-to-foodservice channels consolidating around chain procurement teams with in-house plant-based expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where German retail concentration and EFSA novel food frameworks reward suppliers with verified sustainability credentials and established regulatory dossiers.
For Market Incumbents: Lock in exclusive quick-service restaurant breakfast sandwich contracts before precision fermentation entrants achieve commercial scale. Anchor capacity expansion in the Cologne-Düsseldorf corridor to satisfy Dutch institutional catering proximity requirements. Defend against cashew-protein fermentation substitutes by deepening emulsion science R&D partnerships with Ruhr Valley food technologist clusters. For New Entrants and Emerging Players: Capture white-space in Swiss and French specialty retail channels where artisanal fermented block formats command premium realization with minimal incumbent saturation. Target Netherlands public sector catering contracts specifying carbon footprint disclosure and returnable bulk systems. Enter through precision fermentation lipid licensing to contract manufacturers, bypassing tropical agriculture supply chain dependencies entirely. For Investors and Strategic Acquirers: Food conglomerates with existing plant-based portfolios are the most active acquirer in this space, seeking fermentation technology licenses and German contract manufacturing capacity. Long-term viability hinges on regulatory approval moats and manufacturing proximity to European foodservice procurement consolidation. Monitor EFSA novel food approval timelines for fermentation-derived proteins as the inflection signal distinguishing scalable platforms from commodity ingredient traders.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Lipid Licensing | Enables animal-identical fat structures without Southeast Asian weather dependencies. |
| German Contract Manufacturing Expansion | Satisfies Dutch institutional catering local proximity requirements under EU Green Deal. |
| EFSA Novel Food Dossier Investment | Accelerates time-to-market for cashew-protein fermentation alternatives in European retail. |
| Quick-Service Restaurant Co-Development | Locks in exclusive slice and sauce formats for underpenetrated breakfast daypart menus. |
| Returnable Bulk System Deployment | Meets Netherlands public sector carbon footprint disclosure and circular procurement mandates. |
Research Methodology
Direct dialogue with foodservice procurement directors, plant-based category managers at German supermarket chains, EFSA regulatory affairs consultants, and contract manufacturing executives in the Ruhr Valley grounded qualitative insights. Secondary validation drew from EFSA novel food submission databases, USDA organic certification records, EU Green Deal procurement disclosure filings, and customs trade data on tropical lipid imports. Bottom-up volume estimates from manufacturer capacity announcements and top-down demand calibration from foodservice chain menu placement tracking were triangulated for consistency.
Segment-level value outputs emerged from modeling across product format, lipid base ingredient, packaging type, and distribution channel dimensions throughout the forecast period. CAGRs were derived from slope analysis of annual volume trajectories incorporating EFSA approval timeline assumptions and German retail shelf-space expansion rates. Industry-specific inputs included emulsion stability technology curves and precision fermentation commercialization milestones from California startup clusters.
Underlying measurement precision varies by segment; shredded cheese and coconut-oil base estimates carry tighter precision than fermented block and precision fermentation categories where commercial deployment remains nascent. Forecasts embed assumptions around EFSA regulatory velocity and tropical supply chain stability that practitioners should monitor for early revision signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Dry Cream Substitute Market
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
A2 Milk Powder Market