
 Non-Dairy Ice Cream Market | 2026-2036
Non-Dairy Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Dairy Ice Cream Market Analysis
Subscription-based recurring delivery of non-dairy frozen desserts is repositioning how brands build loyalty and secure predictable revenue streams. Oatly Group leverages its oat milk supply chain to control ingredient quality from crop to cone. Unilever sustains broad retail shelf presence through multi-brand portfolio depth across conventional and specialty grocers. Danone differentiates through fermented base technologies that improve texture in almond and coconut formulations.
Non-dairy ice cream denotes frozen desserts formulated without mammalian milk, typically employing emulsified plant milks with fat contents between 10% and 20% to achieve comparable mouthfeel and overrun. These products serve commercial and retail channels targeting vegan consumers, lactose-intolerant populations, and flexitarian households seeking reduced-saturated-fat indulgences. Almond milk formulations occupy the largest volume share due to established consumer familiarity and neutral flavor compatibility, while cashew milk bases are gaining traction in premium tiers for superior creaminess. Coconut milk variants dominate in private-label offerings where cost efficiency and tropical flavor profiles align with mass-market positioning.
The FDA enforces allergen labeling under FALCPA, compelling manufacturers to declare tree nut and soy contents that dominate plant-based bases. EFSA evaluates novel protein claims under EU health claim regulations, shaping how brands communicate nutritional equivalence to dairy. Health Canada and FSANZ in Australia maintain parallel standards for dairy alternative nomenclature, preventing misleading product naming. Stakeholders must monitor evolving protein fortification rules and carbon footprint disclosure requirements that will determine which base ingredients and sourcing geographies gain regulatory preference.
Market Dynamics
Clean-label mandates and protein-fortification standards are compressing formulation flexibility while oat and coconut supply networks consolidate around Nordic and Southeast Asian processing clusters.
Growth Catalysts
- FALCPA allergen disclosure:The FDA's labeling requirements have standardized ingredient transparency, accelerating consumer trust in plant-based frozen desserts across US retail channels.
- Fermented base technologies:Cultured almond and coconut formulations are improving texture parity with dairy, expanding acceptance among flexitarian households previously resistant to alternative proteins.
- Subscription delivery infrastructure:Direct-to-consumer frozen logistics networks in Germany and Australia are securing recurring revenue streams and reducing customer acquisition costs for specialty brands.
Market Restraints
- Tree nut input volatility:Almond and cashew commodity prices fluctuate with California and Vietnamese harvest cycles, compressing margin predictability for mid-tier producers.
- EFSA novel protein evaluation timelines:Extended regulatory review periods for emerging legume and pea protein bases delay product launches across European markets.
- Soy substitution threat:Resurgent consumer preference for traditional soy milk formulations in East Asian markets limits expansion potential for newer oat and hemp alternatives.
Strategic Opportunities
- Underpenetrated Australian food service:Quick-service restaurant chains and cinema concessionaires represent untapped bulk procurement channels for soft-serve and scoop formats.
- EU Green Deal carbon footprint disclosure:Upcoming mandatory environmental labeling creates first-mover advantage for brands with verified low-emission oat supply chains from Nordic growers.
- Precision fermentation convergence:Integration of microbial dairy protein production with plant-based fat systems enables hybrid formulations that bypass allergen concerns while delivering authentic mouthfeel.
Industry Challenges
- Clean-label formulation expertise gap:Shortage of food scientists skilled in stabilizer-free emulsion systems slows R&D cycles for brands pursuing minimal ingredient declarations.
- Cold chain capex intensity:Expansion into direct-to-consumer channels requires substantial investment in insulated packaging and last-mile frozen logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Dairy Ice Cream Market |
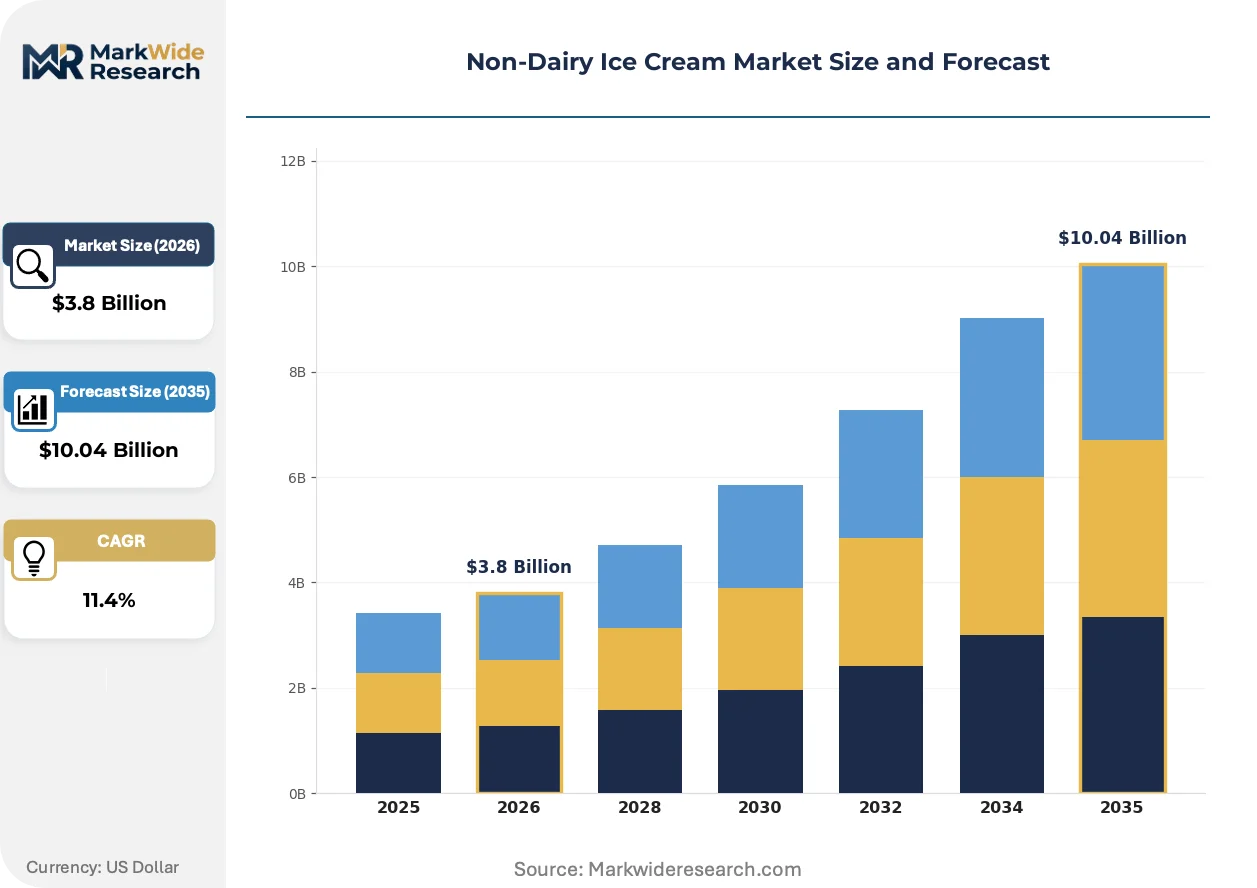
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Milk, Almond Milk, Soy Milk, Cashew Milk Flavor Profile: Vanilla, Chocolate, Strawberry, Mint Chip Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores End User: Dietary Restrictions, Vegan Consumers, Health-Conscious Shoppers, Families |
| Companies Covered | Oatly Group, Tofutti Brands, Unilever, NadaMoo, So Delicious Dairy Free, Danone, Ben & Jerry's, Van Leeuwen Ice Cream, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Dairy Ice Cream Market Emerging Trajectories
Formulation science and regulatory disclosure requirements are converging to reshape how plant-based frozen desserts achieve sensory parity and market access.
Precision fermentation of dairy-identical proteins is absorbing the texture limitations that have historically constrained coconut and almond base performance. Premium brands in the United States and Germany are integrating these ingredients into hybrid formulations, enabling cleaner labels while maintaining overrun stability. The technology is absorbing market share from purely plant-based alternatives in the indulgence segment where mouthfeel expectations are most demanding.
EFSA's evolving stance on protein equivalence claims under EU health claim regulations is tightening substantiation requirements for nutritional comparisons to dairy. Manufacturers must now commission clinical studies or comprehensive amino acid profiling to support marketing assertions, elevating compliance costs. This regulatory pressure is most acute in Germany and France, where functional food positioning drives purchase decisions among health-conscious consumers.
Buyer concentration in conventional grocery is fragmenting as specialty retailers and direct subscription channels capture experimentation-oriented consumers. Mass-market supermarkets are responding with expanded private-label assortments, compressing shelf space for emerging brands. This channel rotation is most visible in Australia, where independent grocers and online frozen specialists are outperforming traditional retail growth rates.
Non-Dairy Ice Cream Market Segmentation
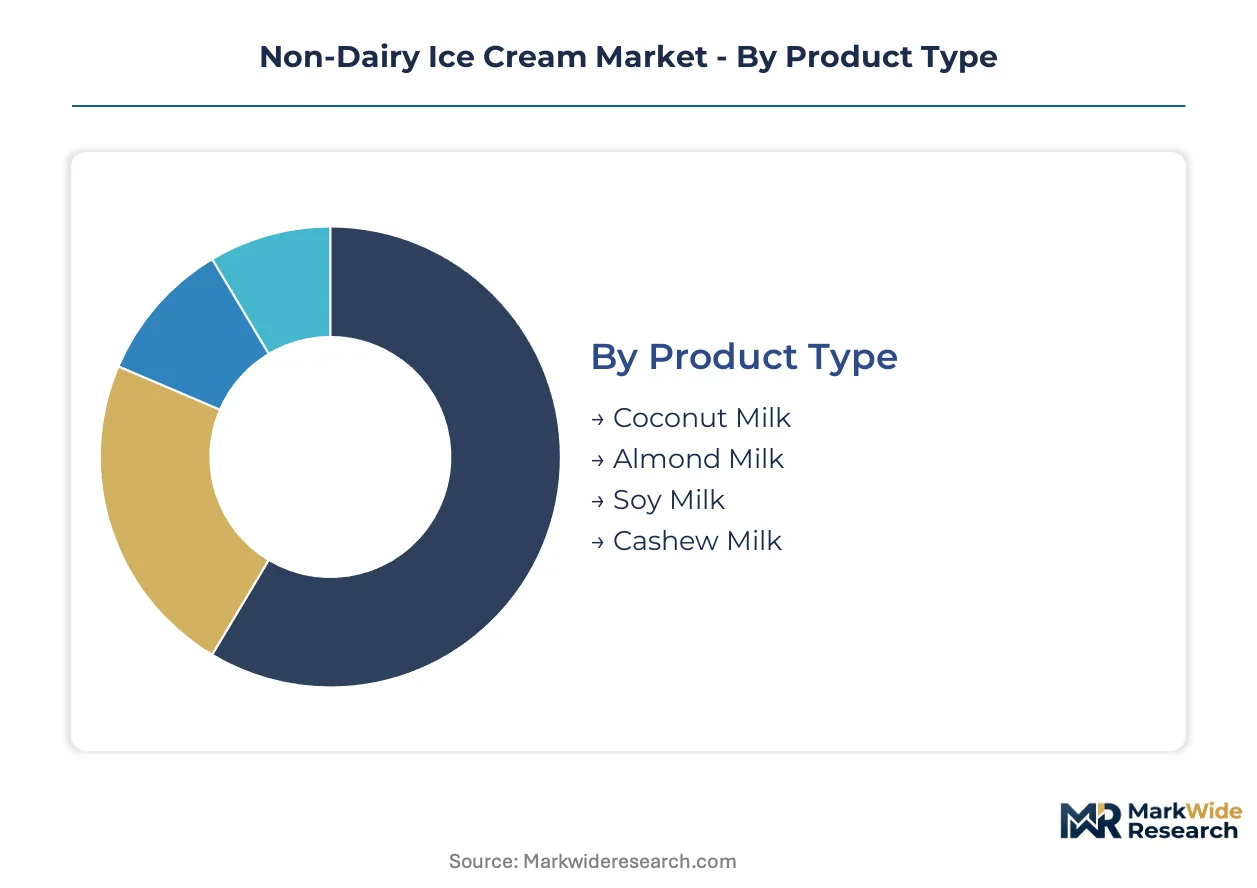
Segmentation in non-dairy ice cream reveals how formulation chemistry, channel economics, and consumer identity intersect to determine pricing power and loyalty mechanics. Manufacturers must align base ingredient sourcing with the specific performance expectations of each buyer archetype.
Product Type:
Buyers differentiate primarily by mouthfeel tolerance and allergen sensitivity, which dictates acceptable fat sources and emulsion stability requirements.
- Almond Milk:Neutral flavor profile and established consumer familiarity make this base dominant in US retail channels. Demand concentrates in conventional supermarkets where flexitarian households prioritize recognizable ingredients over premium texture.
- Coconut Milk:Higher saturated fat content delivers superior creaminess that supports premium positioning in German and Australian specialty retail. Tropical flavor associations limit versatility but secure loyalty among indulgence-seeking vegan consumers.
- Soy Milk:Lowest input costs and longest manufacturing heritage sustain mass-market private-label production, particularly in East Asian markets where soy tolerance remains culturally embedded.
- Cashew Milk:Superior fat emulsion properties enable cleaner stabilizer-free labels, attracting health-conscious shoppers willing to pay formulation premiums for minimal ingredient declarations.
Almond milk leads volumes today; cashew milk is gaining share fastest.
Flavor Profile:
Flavor selection signals usage occasion and permissible price point, with classic profiles anchoring household replenishment and novel variants driving trial.
- Vanilla:The default reference standard for base quality assessment across all distribution channels, commanding disproportionate shelf space in conventional grocery due to its role in recipe applications and topping compatibility.
- Chocolate:Cocoa intensity masks base protein off-notes, making this flavor critical for oat and hemp formulations where taste parity with dairy remains technically challenging.
- Strawberry:Fruit inclusion requirements complicate clean-label formulation but secure placement in family-oriented multipacks where visual appeal drives child purchase influence.
- Mint Chip:Chip texture integration demands precise freezing curve control, limiting production to manufacturers with advanced continuous freezer capabilities and constraining supply to premium tiers.
Vanilla maintains volume leadership; mint chip shows the steepest expansion trajectory among premium-positioned variants.
Distribution Channel:
Channel selection determines required cold chain investment, margin structure, and brand control over pricing and positioning.
- Supermarkets:Scale economics and promotional funding requirements favor multi-brand portfolios with sufficient marketing budgets to secure end-cap placement and temporary price reduction programs.
- Online Retail:Direct-to-consumer frozen logistics infrastructure enables subscription-based recurring revenue models, with insulated packaging innovation reducing per-unit delivery costs for German and Australian specialists.
- Convenience Stores:Impulse purchase dynamics favor single-serve formats with extended freezer stability, constraining formulation to higher stabilizer content that conflicts with clean-label positioning.
- Health Food Stores:Curated assortment criteria prioritize certified organic and non-GMO verification, creating gatekeeper effects that filter out mass-market brands regardless of ingredient quality.
Supermarkets dominate current volume capture; online retail is climbing the fastest as frozen last-mile infrastructure matures.
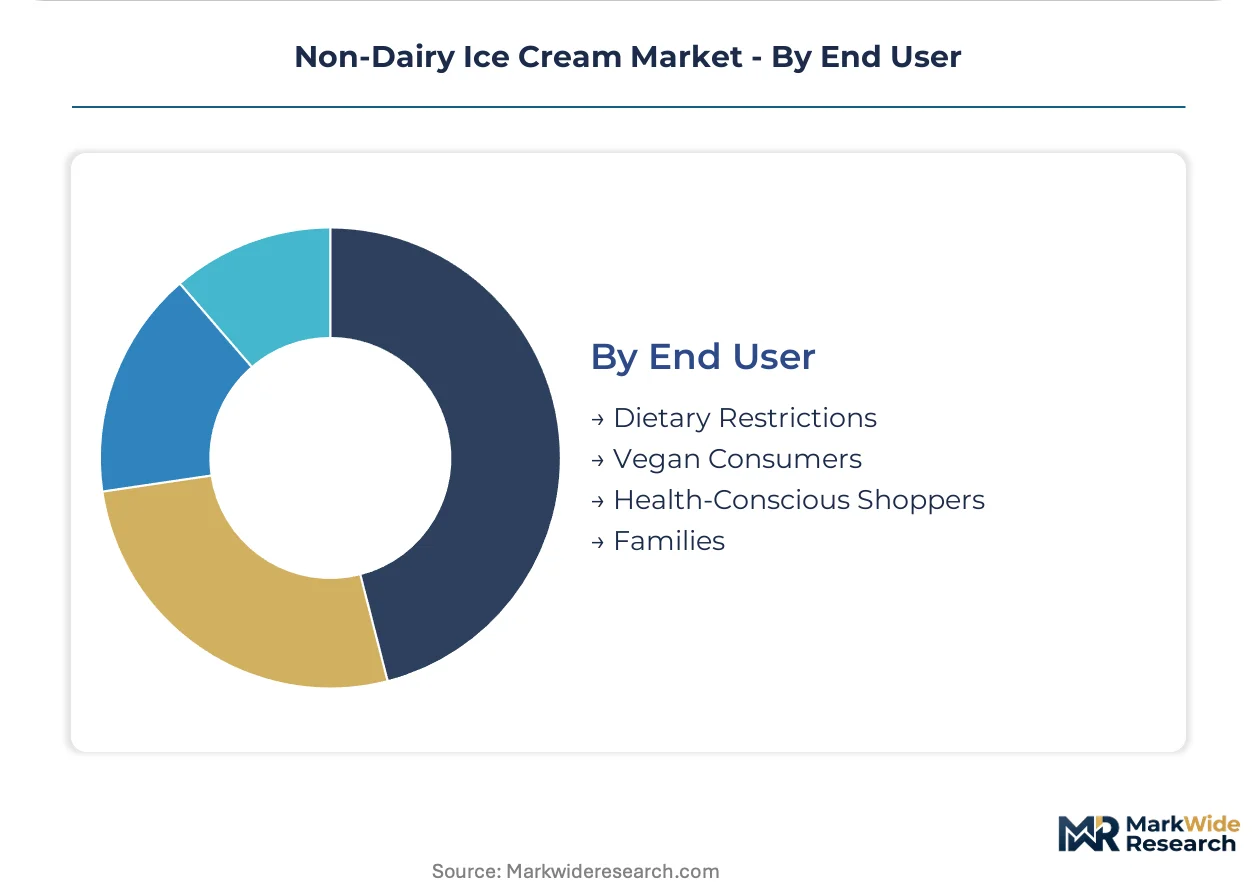
End User:
User motivation—medical necessity, ethical commitment, or wellness aspiration—shapes acceptable price elasticity and reformulation responsiveness.
- Dietary Restrictions:Lactose intolerance and milk protein allergy create non-discretionary demand with low price sensitivity, driving loyalty to brands with rigorous allergen control protocols and transparent supply chain documentation.
- Vegan Consumers:Ethical positioning requirements extend to packaging sustainability and corporate advocacy, with this segment accepting taste trade-offs that flexitarian buyers reject.
- Health-Conscious Shoppers:Nutritional equivalence claims to dairy protein and calcium content drive purchase decisions, requiring brands to invest in clinical substantiation under EFSA and FDA labeling scrutiny.
- Families:Multi-serve format preference and child-friendly flavor range requirements concentrate demand in conventional retail channels where price-per-volume metrics dominate comparison shopping.
Families represent the largest addressable base today; health-conscious shoppers are expanding most quickly as functional food positioning gains traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting non-dairy ice cream production toward jurisdictions with lower compliance costs for novel protein claims and carbon footprint verification. Manufacturers are relocating formulation R&D and contract manufacturing to exploit gaps between FDA, EFSA, and FSANZ approval timelines.
United States
FDA's FALCPA enforcement has standardized allergen transparency, accelerating consumer trust in plant-based frozen desserts across retail channels. The agency's evolving stance on precision fermentation labeling creates uncertainty for hybrid protein formulations. California's Central Valley anchors almond milk supply chains, while Brooklyn and Austin clusters concentrate artisanal brand headquarters near venture capital and DTC logistics infrastructure.
Germany
EFSA's protein equivalence substantiation requirements drive clinical study investments among brands targeting health-conscious flexitarian households. The EU Green Deal's impending carbon footprint disclosure mandates favor oat supply chain verification from Nordic growers. Berlin and Hamburg harbor the densest concentration of fermented base technology startups and precision fermentation pilot facilities.
Australia
FSANZ's parallel standards for dairy alternative nomenclature prevent misleading product naming while permitting novel base ingredient experimentation. Rapid expansion of vegan and lactose-intolerant consumer bases outpaces domestic manufacturing capacity. Melbourne and Sydney clusters dominate food service distribution networks, with Queensland emerging as coconut milk processing hub due to tropical ingredient proximity.
United Kingdom
Post-Brexit regulatory divergence from EFSA creates expedited approval pathways for emerging legume and pea protein bases. Clean-label formulation standards tighten faster than continental Europe, compressing stabilizer tolerance in retail formulations. London's specialty retail density and Manchester's contract manufacturing infrastructure concentrate brand commercialization activity.
Canada
Health Canada's allergen disclosure rules align with FDA stringency while permitting faster novel ingredient notifications than EFSA timelines. Cross-border supply chain integration with US oat and almond processors reduces input cost volatility. Toronto and Vancouver clusters concentrate brand headquarters and direct-to-consumer frozen logistics innovation.
Non-Dairy Ice Cream Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with portfolio conglomerates dominating supermarket shelf space and artisanal labels capturing subscription channels. The vendor base organizes around three archetypes: oat supply chain integrators, fermented base technology specialists, and multi-brand consumer goods portfolios. Consolidation pressure intensifies as cold chain capex requirements and regulatory compliance costs favor scaled players. Dominant competitive moves include backward integration into Nordic oat sourcing and precision fermentation licensing agreements.
Within the oat supply chain integrator tier, Oatly Group exemplifies vertical control from crop cultivation through retail distribution. Among multi-brand conglomerates, Unilever and Danone occupy positions spanning conventional and specialty grocery channels. These entities anchor competitive dynamics through portfolio breadth and regulatory lobbying capacity rather than single-brand loyalty mechanics.
| Leading Market Players |
|---|
| Oatly Group |
| Tofutti Brands |
| Unilever |
| NadaMoo |
| So Delicious Dairy Free |
| Danone |
| Ben & Jerry's |
| Van Leeuwen Ice Cream |
| Nestlé |
| Others |
Supply Flow & Price Mechanics
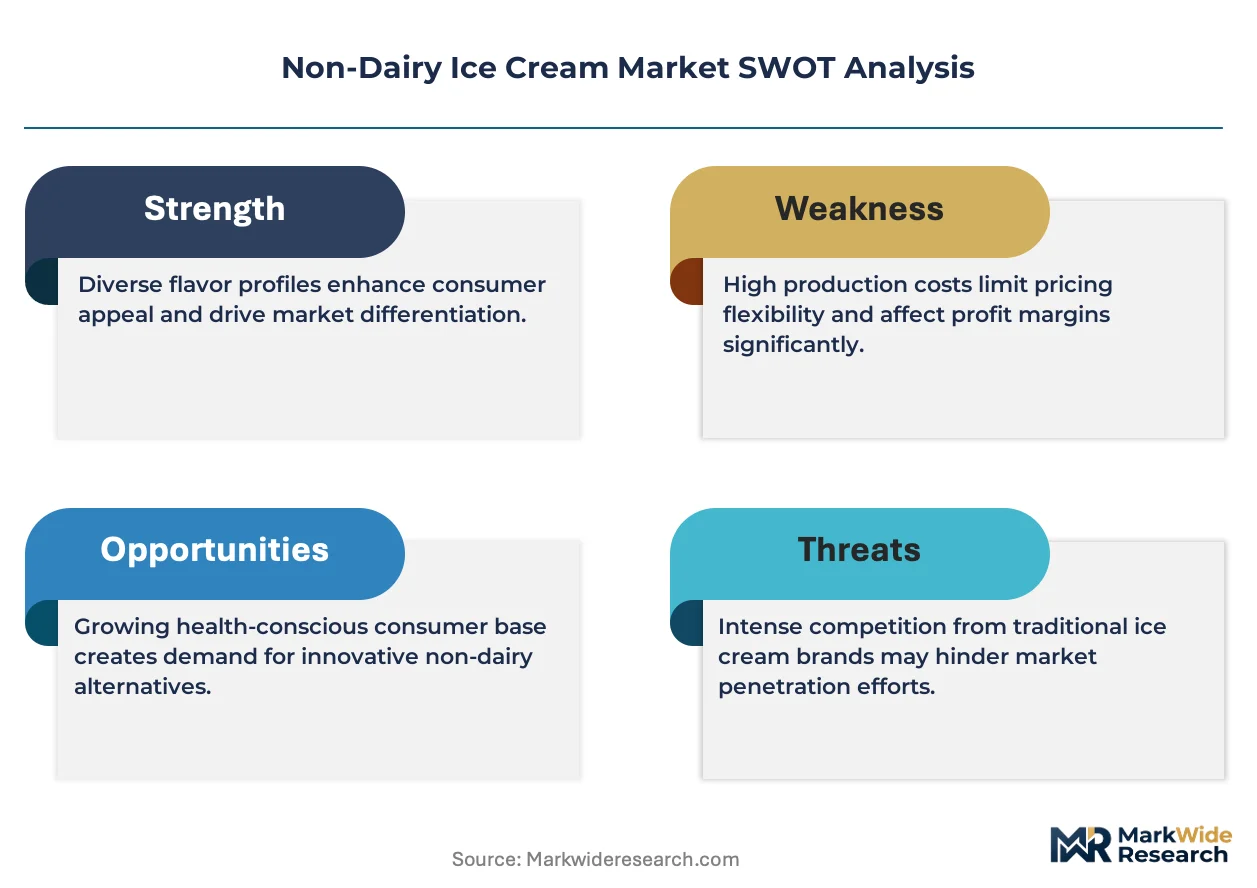
Premium-cashew and commodity-coconut base divergence separates formulation tiers in non-dairy ice cream, with clean-label positioning commanding shelf space premiums while mass-market private-label competes on input cost arbitrage from Southeast Asian processing clusters. This tier split manifests in divergent margin structures: premium brands absorb Nordic oat and Vietnamese cashew premiums for stabilizer-free claims, while economy players exploit coconut milk's tropical proximity to compress landed costs.
Pricing Analysis
Retailer markup layers dominate final price formation, with specialty grocers extracting 35-50 point premiums over conventional supermarkets for identical SKUs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence—organic and non-GMO verification support top-tier positioning—while volume scale discounts anchor club channel economics. Pricing pressure stems from almond commodity volatility in California's Central Valley, where drought cycles compress margin predictability for mid-tier producers. Health-conscious shoppers exhibit lowest price sensitivity, accepting formulation premiums for minimal ingredient declarations; families in conventional retail show highest elasticity, comparing price-per-volume metrics across multipack formats.
Supply Chain Analysis
Dual-sourcing requirements from major retailers mandate multi-supplier qualification for oat bases, compelling brands to qualify both Nordic and North American processors despite quality differentials. Geographic supply concentration centers on Vietnam and India for cashew, Indonesia and Philippines for coconut, and Sweden and Finland for oat—each cluster tethered to distinct processing infrastructure and harvest calendars. Raw material dependencies span tree nut proteins, tropical fats, and fermented culture inputs, with cold chain logistics consuming disproportionate working capital versus ambient packaged goods. Single-source vulnerability concentrates in California almond supply, where water rights disputes and climate volatility threaten input security. Distribution runs through temperature-controlled warehousing networks, with last-mile frozen delivery representing the fastest-growing but capex-intensive channel expansion vector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-dairy ice cream has entered a late-cycle quality phase where texture parity and clean-label credibility determine survival, as flexitarian households upgrade from compromise purchases to premium indulgence expectations.
For Market Incumbents: Hedge against precision fermentation disruption by securing licensing agreements with microbial dairy protein developers before hybrid formulations commoditize pure plant-based positioning. Fortify Nordic oat supply contracts against Green Deal carbon verification requirements that will disadvantage non-Nordic sourcing. Channel control through direct subscription infrastructure offers defensive moat against private-label shelf compression in conventional grocery. For New Entrants and Emerging Players: Independent grocers in Australia represent the most penetrable channel partner type, with underdeveloped frozen dessert assortments and experimentation-oriented consumer bases. White-space targets include quick-service restaurant soft-serve procurement and cinema concession bulk formats where incumbent presence remains thin. Precision fermentation-enabled hybrid formulations offer differentiation wedge against established plant-only portfolios. For Investors and Strategic Acquirers: Consolidation pressure builds where cold chain capex requirements and EFSA protein equivalence study costs exceed standalone brand economics, favoring scaled multi-brand portfolios. Long-term viability hinges on backward integration into oat cultivation or precision fermentation licensing rather than formulation-only positioning. Fermented base technology patents and verified low-carbon supply chain documentation signal acquisition-ready capability depth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Oat Cultivation | Captures Green Deal carbon verification advantage before mandatory disclosure rules activate. |
| Precision Fermentation Licensing Agreement | Enables hybrid protein formulations that bypass tree nut allergen concerns while delivering authentic mouthfeel. |
| Direct-to-Consumer Frozen Logistics Buildout | Secures recurring revenue streams and reduces customer acquisition costs in German and Australian markets. |
| EFSA Protein Equivalence Clinical Study Investment | Substantiates nutritional claims for health-conscious flexitarian positioning in German and French retail. |
| Quick-Service Restaurant Soft-Serve Partnership | Unlocks underpenetrated Australian food service channel with bulk procurement economics. |
Methodological Framework
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region's stakeholder ecosystem. The analysis combines structured interviews with brand managers, category buyers at specialty and conventional retailers, supply chain planners, and food science R&D directors with secondary validation from FDA FALCPA filings, EFSA novel food notifications, FSANZ dairy alternative nomenclature rulings, and retail audit databases tracking frozen dessert velocity. Bottom-up volume modeling triangulates against top-down market sizing from trade association aggregates and customs records.
Granularity-level framing applies country-specific regulatory cluster distinctions and channel-specific cold chain economics across the projection horizon. Segmentation dimensions modeled include base ingredient chemistry, flavor profile, distribution channel format, and end-user motivation archetype. CAGRs derive from logistic curve fitting to historical adoption patterns, adjusted for protein fortification regulatory milestones and precision fermentation commercialization timelines. Forecast inputs incorporate oat and cashew commodity price cycles, frozen last-mile delivery cost curves, and retailer private-label expansion intentions.
Revisions become necessary when EFSA accelerates novel protein evaluation timelines, California almond harvests deviate from projected yields, or precision fermentation achieves cost parity with plant-based bases earlier than modeled. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Cheese Alternative Market