
 Neuromorphic Chip Market | 2026-2036
Neuromorphic Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Neuromorphic Chip Market Intelligence
The direct engagement model between chip developers and automotive Tier-1 suppliers is reshaping how advanced driver-assistance systems are designed. Intel Corporation leverages its established relationships with OEMs to integrate its Loihi research platform into future vehicle architectures. Qualcomm competes by adapting its mobile processing expertise for edge AI applications in connected cars. BrainChip differentiates through its event-based neural processor IP, targeting low-power sensor processing.
A neuromorphic chip is a specialized integrated circuit designed to mimic the structure and function of the human brain's neural networks. These chips operate on the principle of spiking neural networks (SNNs), processing data in an event-driven, asynchronous manner, which drastically reduces power consumption compared to traditional CPUs. Within applications, pattern recognition commands significant research focus, while autonomous systems represent a fast-growing commercial segment. Research institutions currently constitute a primary end-user base, but adoption by consumer electronics manufacturers is accelerating for on-device AI.
Development is influenced by international standards like ISO 26262 for functional safety in automobiles, particularly in the United States and Germany. Concurrently, the EU AI Act introduces risk-based compliance requirements that will shape algorithm training and deployment on these chips. Data processing at the edge also aligns with GDPR principles by minimizing data transfers. Stakeholders must now decide how to balance proprietary architectural development with the need for a standardized software ecosystem to scale applications.
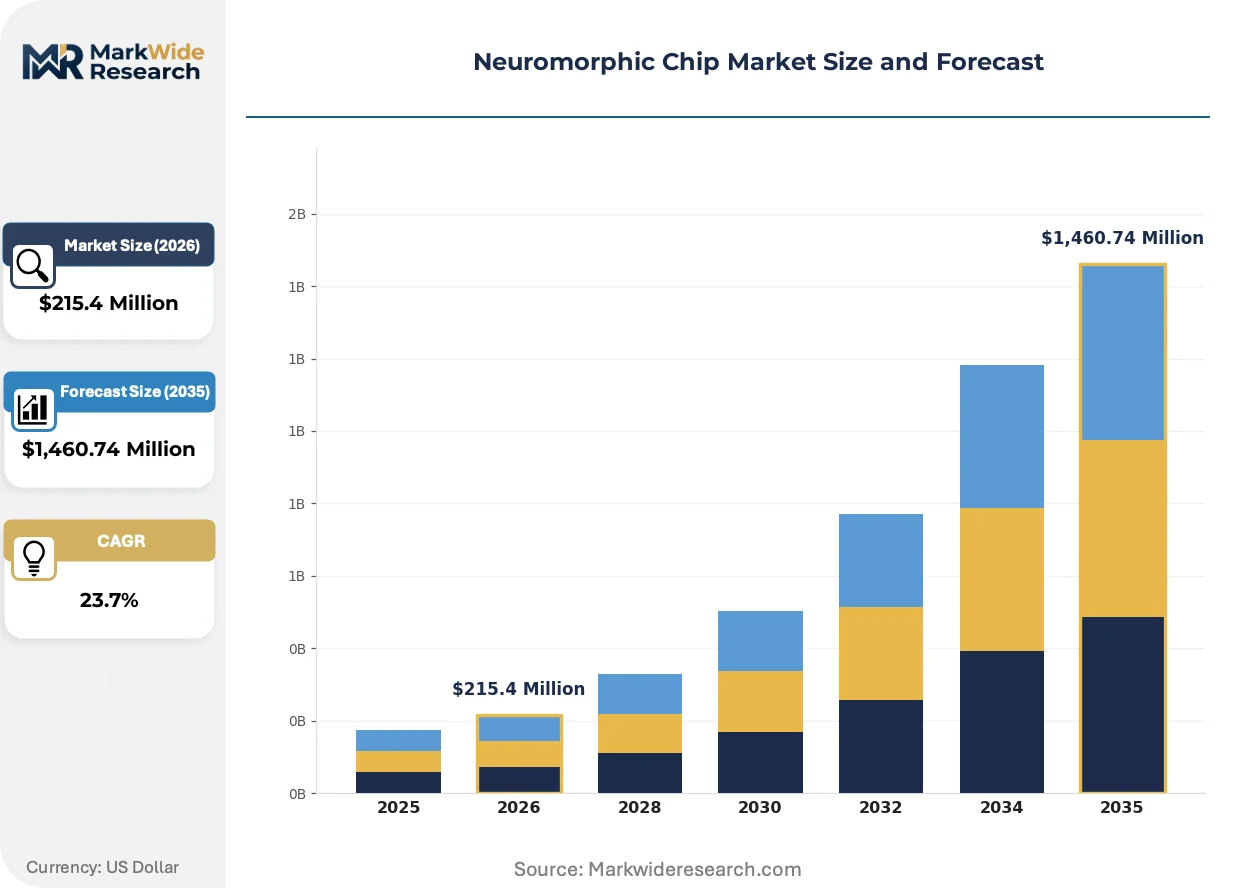
Market Dynamics
The central tension shaping the neuromorphic chip market is the conflict between proprietary, high-performance hardware architectures and the industry-wide need for a standardized software and programming ecosystem to enable scalable application development and deployment across diverse platforms.
Growth Catalysts
- Memristor-Based Architectures:The maturation of memristor technology enables the development of denser, more power-efficient synaptic circuits, which is critical for creating large-scale, commercially viable spiking neural networks.
- Autonomous Systems Demand:Rapid development in autonomous vehicles and robotics creates significant pull for low-latency, low-power processing at the edge, a core value proposition of neuromorphic hardware.
- Government Research Funding:Defense and advanced research initiatives, particularly in the United States, provide substantial non-dilutive funding and an initial end-user base, de-risking early-stage technology development.
Market Restraints
- Programming Complexity:The event-driven, asynchronous nature of spiking neural networks requires a paradigm shift in software development, and the lack of mature, high-level programming tools creates a steep learning curve.
- High Fabrication Costs:Manufacturing novel neuromorphic designs using non-standard materials like memristors entails significant initial capital expenditure and process development, limiting economies of scale.
- GPU Substitution Threat:The incumbent ecosystem and continuous performance gains of traditional GPUs for AI inference present a powerful and accessible alternative, slowing neuromorphic adoption in less power-constrained applications.
Strategic Opportunities
- On-Device Consumer AI:Integrating neuromorphic co-processors into smartphones and wearables offers a path to deliver sophisticated, always-on AI features without compromising battery life, an underpenetrated application area.
- Sensor Fusion at the Edge:The convergence of neuromorphic chips with event-based sensors, such as dynamic vision sensors, creates highly efficient systems for real-time scene analysis and object tracking.
- Data Privacy Compliance:Regulations like GDPR in Europe create a tailwind for edge processing that minimizes personal data transfer, positioning neuromorphic chips as a privacy-enhancing technology.
Industry Challenges
- Ecosystem Standardization:The absence of a universal software abstraction layer or instruction set architecture fragments the market, hindering application portability and slowing the creation of a robust third-party developer community.
- Specialized Talent Scarcity:A significant skills gap exists for engineers who possess the cross-disciplinary expertise in neuroscience, SNN algorithms, and custom silicon design required for advanced development.
- Legacy System Integration:Designing effective data pathways and control interfaces to integrate asynchronous neuromorphic processors with synchronous, von Neumann-based host systems remains a major technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuromorphic Chip Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $1,460.74 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Neuromorphic Chips, Mixed-Signal Neuromorphic Chips, Analog Neuromorphic Chips, Spiking Neural Chips Technology: Memristor-Based, CMOS-Based, Phase-Change Memory, Spintronic Devices, Optical Neuromorphic Systems Application: Robotics Control, Pattern Recognition, Signal Processing, Autonomous Systems, Brain-Machine Interfaces End User: Research Institutions, Defense Organizations, Consumer Electronics Manufacturers, Automotive Tier-1 Suppliers |
| Companies Covered | SK hynix, BrainChip, Intel Corporation, SynSense, Innatera Nanosystems, IBM, GrAI Matter Labs, Qualcomm, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuromorphic Chip Market Strategic Shifts & Innovations
The market's trajectory is defined by the transition from academic research platforms to commercially deployable, application-specific integrated circuits. This evolution is driven by architectural innovation, new regulatory frameworks, and shifting customer engagement models that prioritize system-level performance.
Hybrid digital-analog architectures represent a key product evolution. These designs combine the synaptic efficiency and low power of analog circuits with the precision and scalability of digital communication fabrics. High-performance computing and data center operators are exploring these systems to reduce the energy footprint of large-scale AI model training and inference. This approach is hybridizing conventional computing infrastructure with brain-inspired hardware, enabling gradual integration without requiring a complete system replacement.
Regulatory mandates like the EU AI Act are directly influencing hardware design choices. The Act’s risk-based framework for AI systems places new emphasis on algorithmic transparency, robustness, and energy efficiency, particularly in critical sectors. Automotive and medical device manufacturers are most affected, now actively assessing how the inherent low-power and real-time processing capabilities of neuromorphic chips can help build compliant, trustworthy systems for high-risk applications.
Co-development partnerships are displacing traditional component-sourcing models. Instead of procuring off-the-shelf chips, automotive OEMs and industrial automation firms are engaging directly with neuromorphic IP developers to design custom silicon. This direct engagement model bypasses conventional distribution channels, allowing for deeper system integration and hardware tailored to specific sensor suites and workloads. This trend is most visible in the automotive sectors of Germany and the United States.
Neuromorphic Chip Market Segmentation
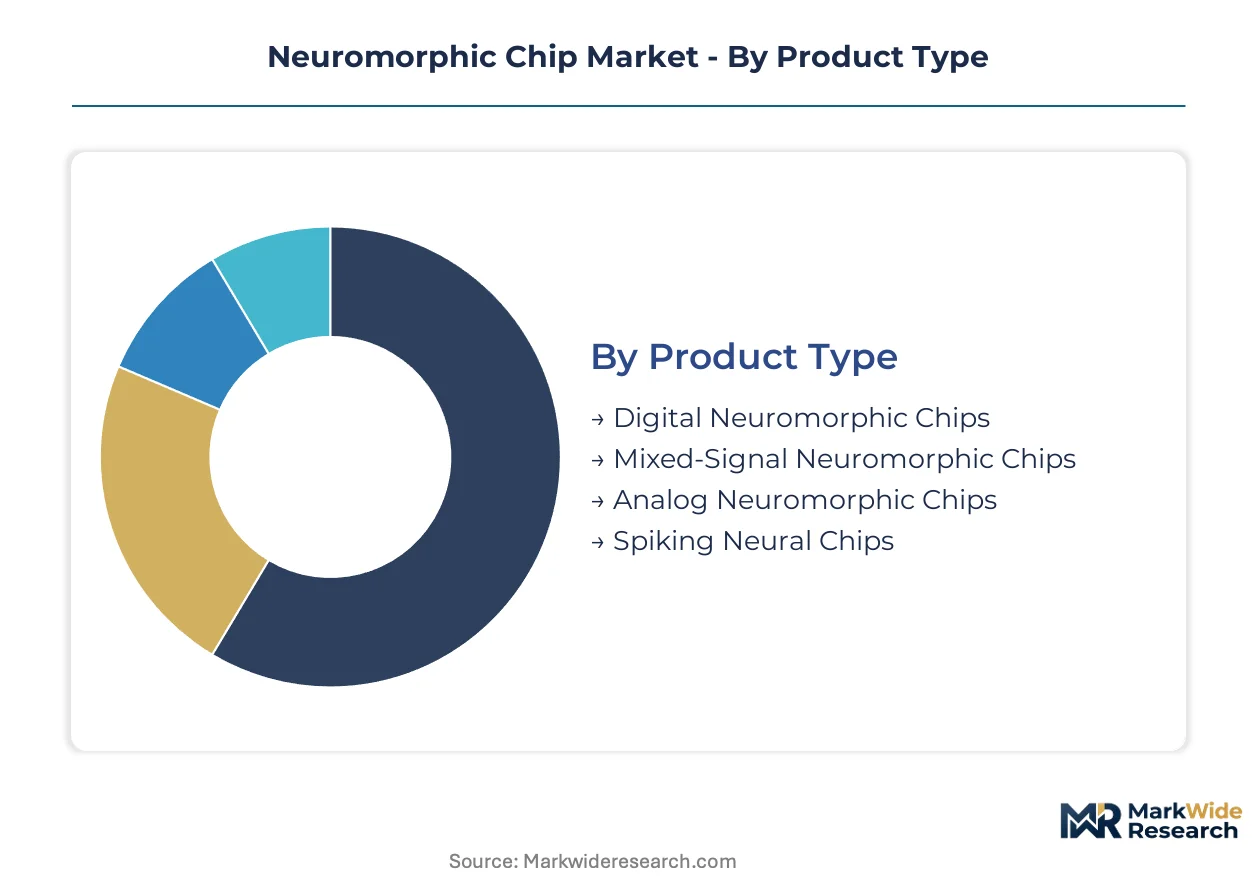
The neuromorphic chip market segmentation provides a granular view of the diverse technologies and applications driving its expansion. Understanding these distinctions is crucial for identifying key growth areas and strategic investment opportunities across the value chain.
Product Type:
Product type segmentation distinguishes between the fundamental architectural designs and operational principles of neuromorphic chips.
- Digital Neuromorphic Chips:These chips utilize digital circuits to simulate neural networks, offering high precision and programmability for complex AI tasks. Demand concentrates in high-performance computing applications within the United States, driven by the need for scalable AI model training.
- Spiking Neural Chips:These integrated circuits mimic biological neurons by processing information through discrete events or "spikes," enabling ultra-low power, event-driven computation. Autonomous systems in Germany are a key demand area, requiring real-time, energy-efficient processing for edge AI.
- Mixed-Signal Neuromorphic Chips:These designs combine analog and digital components, balancing power efficiency with computational accuracy for specific neuromorphic workloads.
- Analog Neuromorphic Chips:These chips leverage analog circuits for highly efficient, often sensor-interfaced, neural network processing at the extreme edge.
Digital Neuromorphic Chips commands the established base. The steepest expansion runs through Spiking Neural Chips.
Technology:
Technological differentiation highlights the diverse materials and fabrication methods underpinning neuromorphic hardware development.
- Memristor-Based:Memristors are non-volatile resistive switching devices that mimic biological synapses, enabling high-density, low-power memory and in-memory computing. Advanced research initiatives globally drive demand for these architectures, seeking energy-efficient neural network implementations.
- CMOS-Based:Complementary metal-oxide-semiconductor technology provides a mature and scalable fabrication process for neuromorphic chips, leveraging existing semiconductor infrastructure. Consumer electronics manufacturers in Japan utilize CMOS-based designs for on-device AI applications, benefiting from cost-effectiveness.
- Phase-Change Memory:This non-volatile memory technology offers fast switching and multi-level storage, suitable for synaptic weight storage in advanced neuromorphic systems.
- Spintronic Devices:Spintronics exploits electron spin for computation and storage, promising ultra-low power and high-speed neuromorphic processing capabilities.
- Optical Neuromorphic Systems:These systems use light to perform neural computations, offering high bandwidth and parallel processing capabilities for future AI accelerators.
The market is significantly driven by CMOS-Based implementations, while Memristor-Based technology shows substantial future potential.
Application:
The application landscape illustrates the varied end-use cases where neuromorphic chips deliver distinct performance advantages.
- Autonomous Systems:Neuromorphic chips provide low-latency, energy-efficient processing for real-time decision-making in self-driving vehicles and robotics. Automotive Tier-1 suppliers in Germany are a primary demand source, integrating these chips for advanced driver-assistance systems.
- Pattern Recognition:These chips excel at identifying complex patterns in data streams, crucial for tasks like image, speech, and gesture recognition. Research institutions and defense organizations in the United States drive significant demand for sophisticated pattern recognition capabilities.
- Robotics Control:Neuromorphic processors enable adaptive and energy-efficient control systems for complex robotic movements and interactions.
- Signal Processing:These chips efficiently process sensor data from various sources, including audio, video, and biometric inputs, at the edge.
- Brain-Machine Interfaces:This application involves direct communication between the brain and external devices, with neuromorphic chips facilitating real-time neural signal interpretation.
Demand for Pattern Recognition remains strong, with Autonomous Systems demonstrating rapid commercialization.
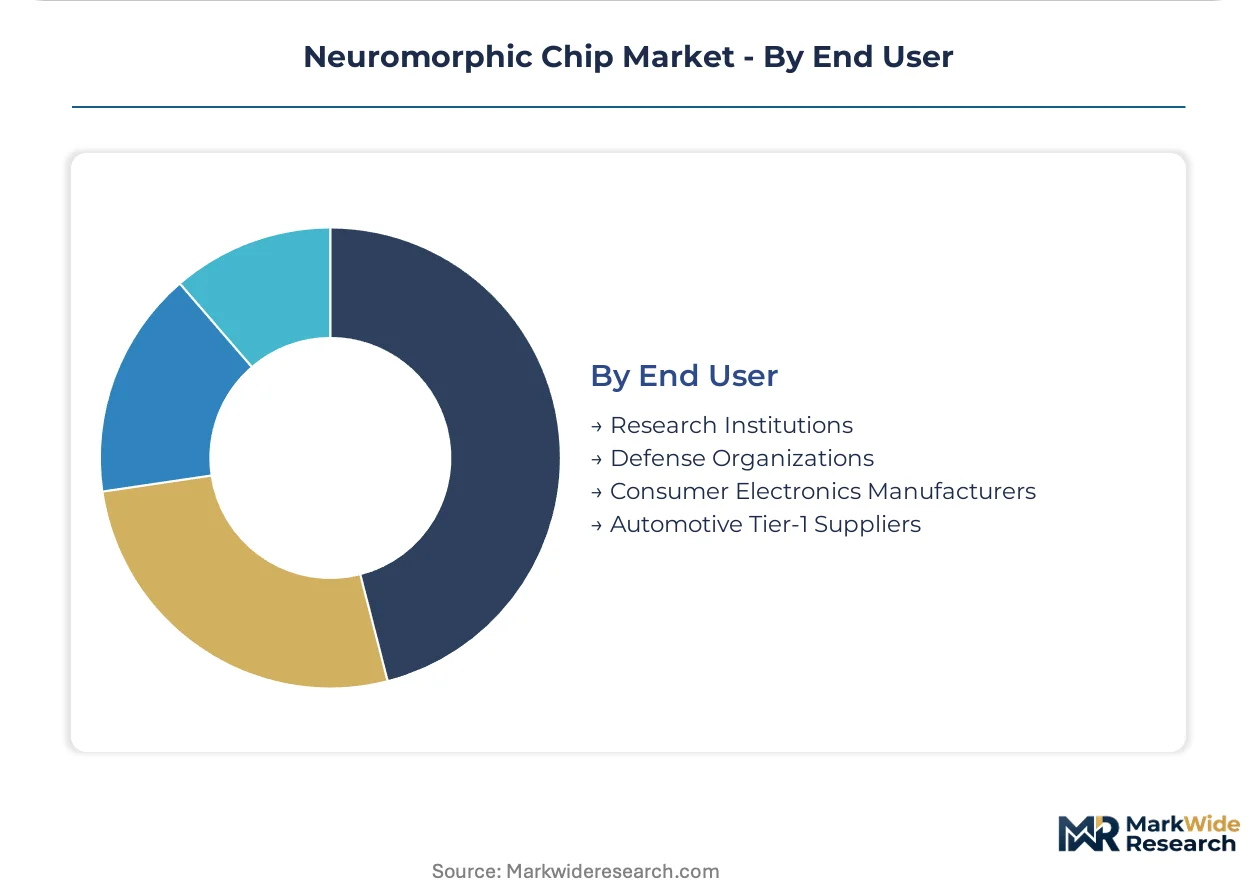
End User:
Customer type analysis identifies the primary organizations and industries driving the adoption and development of neuromorphic solutions.
- Research Institutions:Academic and government laboratories conduct fundamental research into neuromorphic computing architectures, algorithms, and applications. These institutions in the United States receive substantial government funding for de-risking early-stage technology development.
- Consumer Electronics Manufacturers:Companies integrate neuromorphic co-processors into devices like smartphones and wearables to enable sophisticated, always-on AI features with minimal power consumption. Japanese and South Korean manufacturers are actively exploring these integrations for on-device AI.
- Defense Organizations:Military and intelligence agencies utilize neuromorphic chips for secure, real-time data analysis, surveillance, and autonomous defense systems.
- Automotive Tier-1 Suppliers:These suppliers integrate neuromorphic hardware into advanced driver-assistance systems and autonomous driving platforms for vehicle OEMs.
Initial adoption centers on Research Institutions, but Consumer Electronics Manufacturers represents a key growth vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for neuromorphic chips exhibits regional asymmetry, with advanced research centers in the United States commanding premium valuations for early-stage IP. Conversely, volume-driven consumer electronics markets in Japan prioritize cost-effectiveness and scalable manufacturing. This divergence influences investment strategies and technological focus across different geographical segments.
United States
The United States drives demand for digital neuromorphic chips, particularly within high-performance computing and defense applications. Government funding, channeled through agencies like DARPA, de-risks early-stage technology development. Major innovation hubs like Silicon Valley and Boston continue to attract specialized talent and foster advanced research initiatives.
Germany
German automotive Tier-1 suppliers show strong demand for neuromorphic chips in autonomous systems, requiring real-time, energy-efficient processing. Regulations like ISO 26262 for functional safety heavily influence hardware design for critical applications. Automotive centers in Bavaria and Baden-Württemberg are actively engaging in co-development partnerships with chip designers.
Japan
Japanese consumer electronics manufacturers are integrating CMOS-based neuromorphic designs for on-device AI, focusing on cost-effectiveness and scalability. The Ministry of Economy, Trade and Industry (METI) supports advanced semiconductor research and development programs. Technology clusters in Tokyo and Osaka are pioneering new applications for AI in wearables and smart devices.
South Korea
South Korean consumer electronics firms are rapidly exploring neuromorphic co-processors for sophisticated, always-on AI features in mobile devices. Government initiatives, often guided by the Ministry of Science and ICT, promote domestic semiconductor innovation and talent development. Seoul's vibrant tech ecosystem fosters collaborations between chip developers and device manufacturers.
Neuromorphic Chip Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential intellectual property and foundational hardware. The market exhibits a tiered structure, with established semiconductor giants competing alongside agile neuromorphic startups specializing in distinct architectural approaches. Three strategic archetypes define the landscape: diversified semiconductor powerhouses, pure-play neuromorphic IP vendors, and application-specific solution providers. Dominant competitive moves include strategic partnerships for ecosystem development and targeted technology licensing to accelerate application deployment across new sectors.
Among the key players shaping neuromorphic hardware, Intel Corporation exemplifies a diversified semiconductor powerhouse, leveraging its established OEM relationships to integrate its Loihi research platform into future vehicle architectures. Qualcomm, a prominent mobile processing expert, occupies a significant position in adapting its mobile processing expertise for edge AI applications in connected cars. BrainChip, an Australian-based company, sits within the pure-play neuromorphic IP vendor archetype, differentiating through its event-based neural processor IP by targeting low-power sensor processing solutions. These companies collectively anchor architectural development and commercialization efforts.
| Leading Market Players |
|---|
| SK hynix |
| BrainChip |
| Intel Corporation |
| SynSense |
| Innatera Nanosystems |
| IBM |
| GrAI Matter Labs |
| Qualcomm |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes and European air freight corridors experience cost volatility, directly influencing the supply concentration of specialized components and the downstream price differentiation for neuromorphic chips.
Pricing Analysis
Configured-to-order neuromorphic IP commands a premium, contrasting with the per-unit transactional pricing for standard CMOS-based chips. Price differentiation stems from customization levels for specific workloads and adherence to functional safety certifications like ISO 26262. Pricing pressure intensifies in the consumer electronics segment due to volume demands. Conversely, defense organizations and advanced research institutions exhibit lower price sensitivity for cutting-edge capabilities.
Supply Chain Analysis
Specialized materials, including high-purity silicon wafers and novel memristor precursors, form the upstream feedstock for neuromorphic chip fabrication. Supply concentration centers on Taiwan for advanced foundries, South Korea for memory components, and Japan for critical materials. Geopolitical tensions affecting key manufacturing hubs present a structural risk. Downstream distribution runs through direct engagement models between chip developers and automotive Tier-1 suppliers, alongside traditional semiconductor channels for more generalized products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neuromorphic chip market represents a significant service-attach opportunity, with software development kits and algorithm optimization services expanding faster than hardware sales.
For Market Incumbents: Harden established OEM relationships by co-developing application-specific solutions, particularly within automotive and defense sectors. Expand the proprietary software ecosystem to mitigate the GPU substitution threat and attract a broader developer base. Invest in R&D for hybrid digital-analog architectures to balance performance and power efficiency, while pursuing functional safety certifications like ISO 26262.
For New Entrants and Emerging Players: Pursue niche white-space applications such as on-device consumer AI for wearables or advanced sensor fusion at the extreme edge. Target low-power sensor processing in industrial automation, leveraging IP licensing as a go-to-market strategy. Focus on developing highly specialized SNN algorithms and software tools that simplify integration with existing systems, overcoming programming complexity.
For Investors and Strategic Acquirers: Pure-play neuromorphic IP vendors with demonstrated architectural innovation and strong patent portfolios represent attractive long-term acquisition targets. Evaluate companies specializing in memristor technology or those building robust software abstraction layers for SNNs. The signal to watch is significant design wins in high-volume applications or the emergence of a widely adopted, standardized software ecosystem.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnerships for Ecosystem Development | Accelerates application deployment and fosters a robust third-party developer community for neuromorphic solutions. |
| Platform Integration with Existing Systems | Ensures seamless interoperability of asynchronous neuromorphic processors with synchronous von Neumann architectures. |
| Targeted Technology Licensing Agreements | Expands market penetration by enabling broader access to specialized neuromorphic IP across diverse industries. |
| Acquisition of Specialist SNN Algorithm Firms | Enhances core competency in spiking neural network development and accelerates advanced AI application creation. |
| Investment in Functional Safety Certification | De-risks commercialization in critical applications like autonomous vehicles, aligning with regulations such as ISO 26262. |
Research Approach
Findings reconcile primary fieldwork against secondary review of academic journals, company financial reports, government research grants, and industry association reports. Interviews with neuromorphic chip architects, automotive Tier-1 R&D leads, defense procurement specialists, and consumer electronics product managers provided granular insights. A bottom-up and top-down triangulation approach validated market sizing and segmentation across all data points.
Forecast inputs considered include technological advancements in memristor-based architectures and CMOS scalability, coupled with demand drivers from autonomous systems and on-device AI. The analytical framework modeled segmentation dimensions such as product type, technology, application, end-user, and regional regulatory frameworks over the projection horizon. Compound annual growth rates were derived through trend analysis and extrapolation of historical data, factoring in R&D spending on SNNs and ADAS adoption rates.
Sensitivities concentrate around rapid technological shifts, unforeseen regulatory changes, and global economic fluctuations impacting R&D budgets. Forecasts reflect assumptions documented through extensive primary and secondary research. Cross-checking against external benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Automotive Smart Chip Market
Chipset and Processors
Microserver Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
Global ARM Microcontrollers Market