
 Audio Processor Market | 2026-2036
Audio Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Processor Market Outlook
Multi-source procurement for audio DSP cores is repositioning how tier-one electronics manufacturers manage silicon supply. Texas Instruments sustains broad manufacturing scale across analog and digital audio product lines. Qualcomm dominates mobile-centric audio processing through its Snapdragon platform integration. Cirrus Logic specializes in high-fidelity codec solutions that anchor premium consumer electronics designs.
An audio processor is a dedicated semiconductor device that manipulates analog or digital sound signals through filtering, compression, equalization, and spatial effects processing, typically operating at sample rates of 44.1 kHz to 192 kHz with 16- to 32-bit resolution. Its primary purpose is to enable real-time acoustic enhancement in devices ranging from smartphones to automotive head units and professional mixing consoles. Digital Signal Processors command the largest value pool due to their programmability and power efficiency in battery-operated devices. Integrated Circuits represent the fastest-growing category as system-in-package designs consolidate amplification, conversion, and processing functions. Professional Audio applications maintain above-average margins despite smaller volumes, driven by studio-grade fidelity requirements and low-latency demands.
The Federal Communications Commission shapes wireless audio processor deployment through spectrum allocation rules affecting Bluetooth and Wi-Fi implementations. The European Union's Radio Equipment Directive mandates interoperability and electromagnetic compatibility standards that filter non-compliant designs from regional distribution. China's Ministry of Industry and Information Technology enforces GB standards for electromagnetic emissions that constrain product architectures serving domestic OEMs. Stakeholders must monitor how automotive functional-safety certifications and evolving wireless protocol standards reshape R&D allocation across fabless and integrated device manufacturer business models.
Market Dynamics
The EU F-Gas Regulation is forcing semiconductor manufacturers toward lower-power DSP architectures while automotive OEMs simultaneously integrate advanced cabin audio across vehicle tiers. This dual pressure from environmental compliance and premium feature democratization is compressing traditional product lifecycles and rewiring procurement relationships between chip vendors and tier-one electronics manufacturers.
Growth Catalysts
- Automotive infotainment integration:OEMs across Germany, Japan, and the United States are mandating immersive audio as standard equipment even in mid-tier vehicle segments, expanding the addressable hardware base beyond luxury nameplates.
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating migration to energy-efficient DSP designs that reduce thermal management overhead in enclosed consumer electronics housings.
- China smartphone SoC procurement:Domestic handset brands in Shenzhen and Beijing are driving volume procurement of integrated audio SoCs with dedicated neural processing units for real-time enhancement.
Market Restraints
- Advanced node wafer cost volatility:7nm and 5nm fabrication at TSMC and Samsung Foundry carries pricing instability that compresses margin structures for fabless audio processor designers.
- IP licensing concentration:ARM Holdings and Cadence Design Systems control essential DSP instruction set architectures, creating royalty stacking that elevates unit economics for programmable solutions.
- Analog-to-digital conversion physics:Thermal noise floors in high-resolution sigma-delta modulators impose fundamental limits on dynamic range extension without disproportionate power scaling.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor assembly and testing are attracting audio processor packaging investments to serve domestic mobile and automotive OEMs.
- Hearing aid personalization:Over-the-counter hearing aid regulations in the United States are opening channel access for adaptive audio processors with self-fitting algorithms.
- Edge AI audio inference:Convergence of tinyML frameworks with ultra-low-power DSP cores is enabling on-device speech recognition without cloud dependency in battery-constrained wearables.
Industry Challenges
- Functional safety certification timelines:Automotive ISO 26262 ASIL-B and ASIL-C qualifications for audio DSPs in driver monitoring systems extend development cycles by 18-24 months.
- Legacy analog integration complexity:Professional audio equipment manufacturers face friction merging digital signal paths with vintage tube and transformer-based signal chains in hybrid studio consoles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Processor Market |
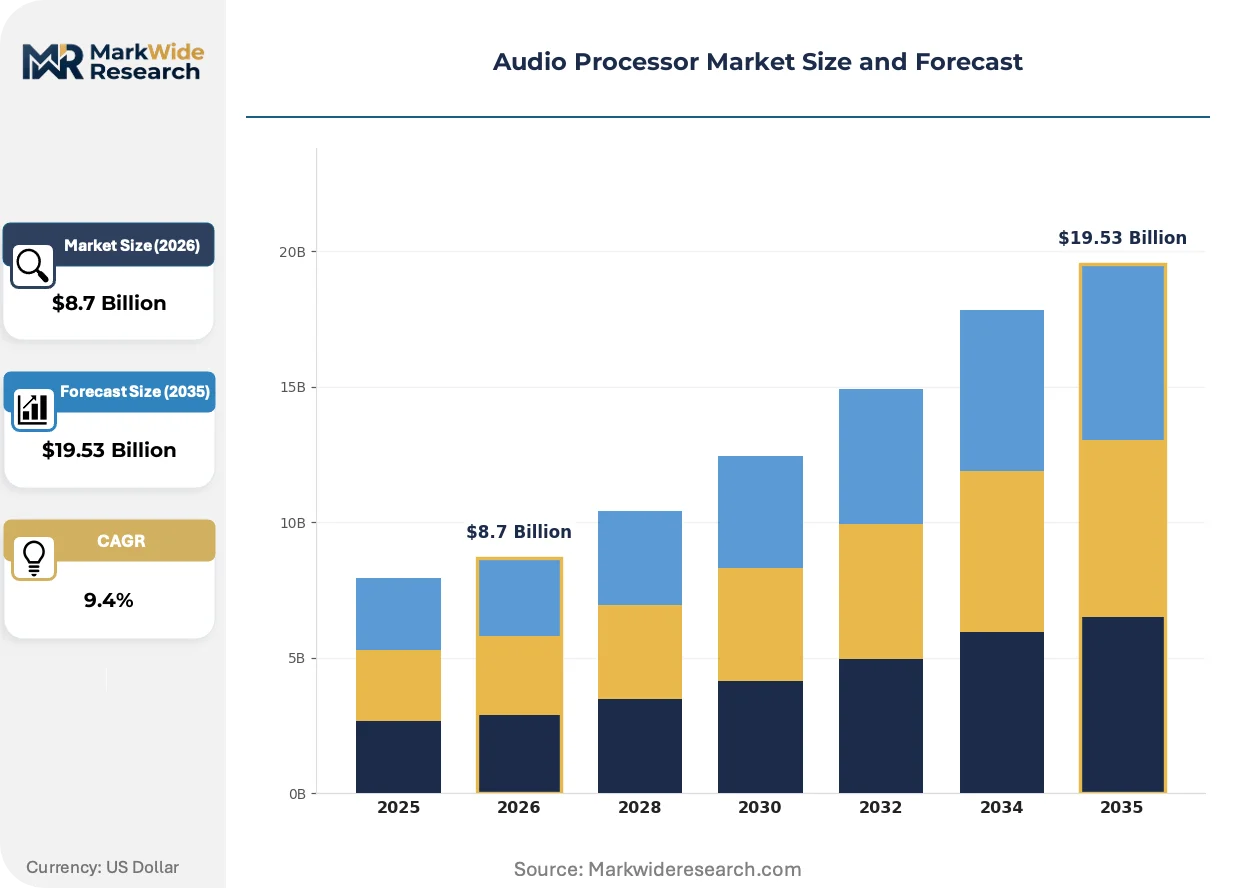
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Signal Processors, Analog Processors, Integrated Circuits, Microcontrollers Application: Consumer Electronics, Automotive Systems, Professional Audio, Broadcasting Technology: Bluetooth, Wi-Fi, Wired Connectivity, Multi-room Audio End User: Musicians, Audio Engineers, Sound Designers, Home Users |
| Companies Covered | STMicroelectronics, MediaTek, Texas Instruments, Asahi Kasei Microdevices, Cirrus Logic, NXP Semiconductors, Qualcomm, ON Semiconductor, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Processor Market Strategic Shifts
Neural audio processing is compressing the boundary between capture and reproduction, enabling real-time spatial rendering that previously required dedicated post-production pipelines. This capability diffusion is redistributing value from professional equipment toward integrated consumer silicon.
Beamforming microphone arrays with onboard machine learning inference are automating noise suppression and voice isolation in conferencing hardware and automotive cabins. Enterprise IT procurement teams are specifying these capabilities as baseline requirements for hybrid work endpoints. The technology is automating acoustic environment adaptation that previously demanded manual calibration or dedicated acoustic treatment.
The EU F-Gas Regulation's phasedown schedule is mandating thermal design power reductions that push audio DSP architectures toward specialized accelerator blocks rather than general-purpose programmable cores. Semiconductor designers are responding with heterogeneous compute fabrics that partition workloads across dedicated neural, spectral, and temporal processing engines. Automotive tier-one suppliers serving European OEMs face the steepest compliance curves as 2027 interim targets approach.
Smartphone brands in China are consolidating audio subsystem procurement under platform-level SoC decisions rather than discrete codec selection. This concentration is elevating the importance of pre-integrated audio IP within mobile processor platforms and compressing the standalone high-fidelity codec market to premium flagship tiers. The shift is most pronounced in Shenzhen's handset ecosystem where vertical integration between device brands and silicon design houses accelerates platform lock-in.
Audio Processor Market Segmentation
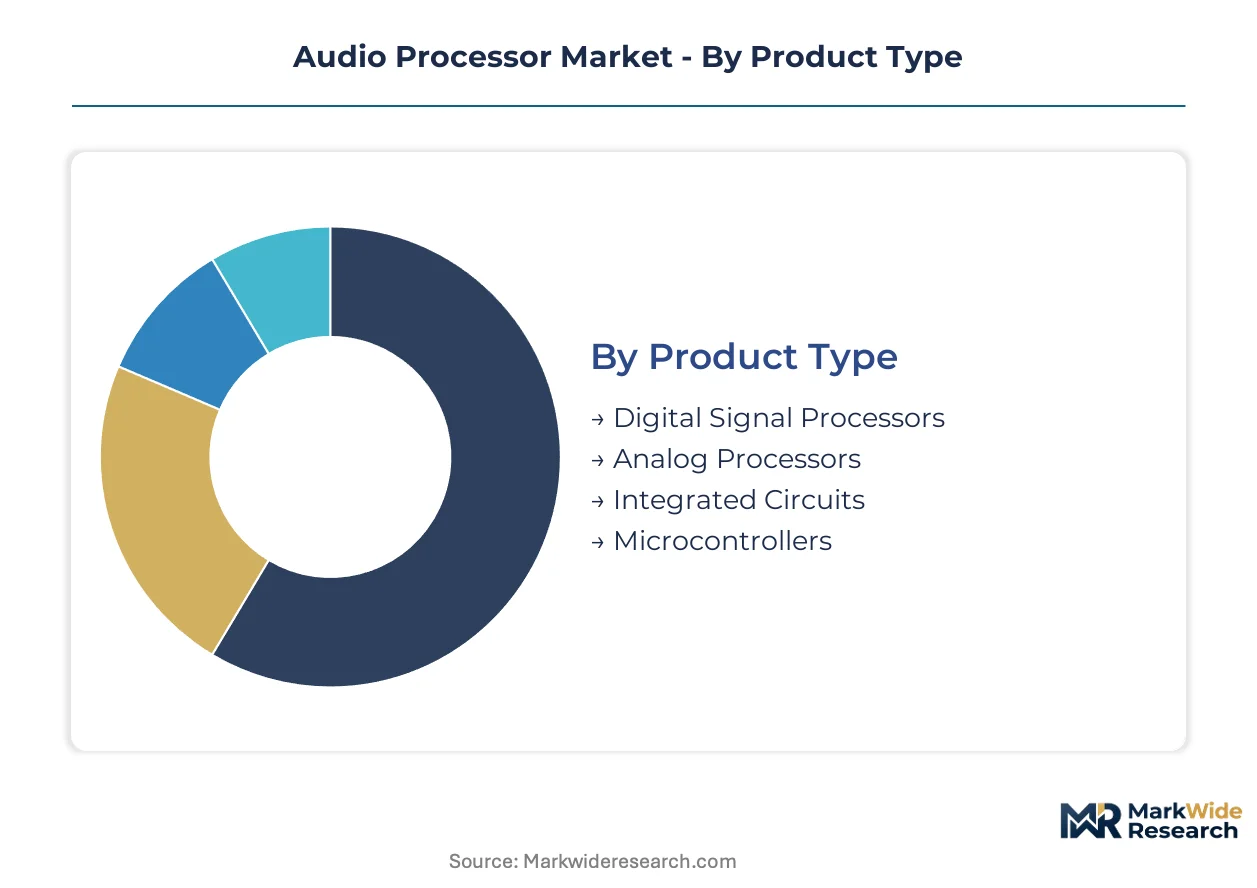
Audio processor segmentation reveals how silicon architecture choices cascade into divergent margin structures and procurement relationships. Product type splits expose the tension between programmable flexibility and dedicated integration, while application boundaries trace how automotive safety requirements and consumer portability demands reshape design priorities.
Product Type:
Volume concentration sits with programmable architectures that serve multiple end-uses through software reconfiguration, while premium capture flows toward specialized integration that collapses function into minimal footprint.
- Digital Signal Processors:Programmable cores execute filtering, compression, and spatial algorithms through optimized instruction sets with hardware multiply-accumulate units. Automotive tier-one suppliers in Germany and Japan specify these for cabin audio systems where firmware updates must extend vehicle lifecycles. The EU F-Gas Regulation's thermal constraints favor DSPs with dynamic voltage scaling over fixed-function alternatives.
- Integrated Circuits:System-in-package designs consolidate ADCs, DACs, amplifiers, and processing cores onto single die or multi-chip modules. Shenzhen smartphone OEMs drive procurement of these consolidated solutions to reduce bill-of-materials complexity in space-constrained flagships. This segment is expanding most quickly as foundry packaging capabilities mature.
- Analog Processors:Continuous-time circuits handle preamplification, tone shaping, and dynamic range compression without digitization. Professional studio equipment manufacturers in Nashville and London specify these for signal paths where converter latency disrupts performer monitoring.
- Microcontrollers:General-purpose compute cores with modest audio-specific peripherals execute simple playback and record functions. White-label consumer electronics assemblers in Dongguan deploy these for cost-optimized portable speakers and entry-level headphones.
Today's leader: Digital Signal Processors. Tomorrow's challenger: Integrated Circuits.
Application:
Automotive qualification requirements create the steepest barriers to entry, while consumer electronics volumes attract the densest competitive field.
- Automotive Systems:Head units, amplifier modules, and active noise cancellation processors must satisfy AEC-Q100 reliability grades and ISO 26262 functional safety targets. German OEMs mandate immersive audio even in mid-tier vehicles, expanding addressable silicon content per car. Thermal budgets tighten as cabin electronics density rises and EU F-Gas compliance pressures mount.
- Consumer Electronics:Smartphones, tablets, wearables, and smart speakers prioritize milliwatt-scale active power and sub-milliwatt sleep states. Domestic brands in Beijing and Shenzhen negotiate directly with foundries for allocated wafer capacity on audio-integrated mobile SoCs.
- Professional Audio:Mixing consoles, studio monitors, and live sound processors demand sub-millisecond latency and 24-bit/192 kHz fidelity. Nashville recording facilities and London post-production houses specify discrete converter and processing stages over integrated solutions.
- Broadcasting:Radio transmission chains and streaming infrastructure require 24/7 reliability with redundant signal paths. National broadcasters in Tokyo and Paris maintain procurement relationships with vendors holding decades-long service commitments.
Automotive Systems command the highest qualification investment. Consumer Electronics delivers the steepest volume expansion trajectory.
Technology:
Wireless protocols are displacing physical interconnects in portable and installed applications, though wired persistence in latency-critical professional environments.
- Bluetooth:Low-energy and high-quality audio codecs enable cordless headphones, hearing aids, and portable speakers with sub-10 milliwatt receive power. FCC spectrum allocations in the United States and MIIT certifications in China shape which codec implementations reach market.
- Wi-Fi:Higher throughput supports uncompressed multi-channel streaming and whole-home audio synchronization. Residential installations in suburban United States markets specify these for architectural speaker systems.
- Wired Connectivity:USB, Thunderbolt, and proprietary digital interfaces maintain dominance where latency budgets exclude radio stack processing. Professional studios in Los Angeles and London require these for tracking sessions.
- Multi-room Audio:Networked speaker systems with synchronized playback across zones depend on precision clock distribution and buffer management. Custom installation channels in Australian metropolitan markets specify these for residential projects.
Bluetooth owns the installed base. Wi-Fi is climbing the fastest in new specification adoption.
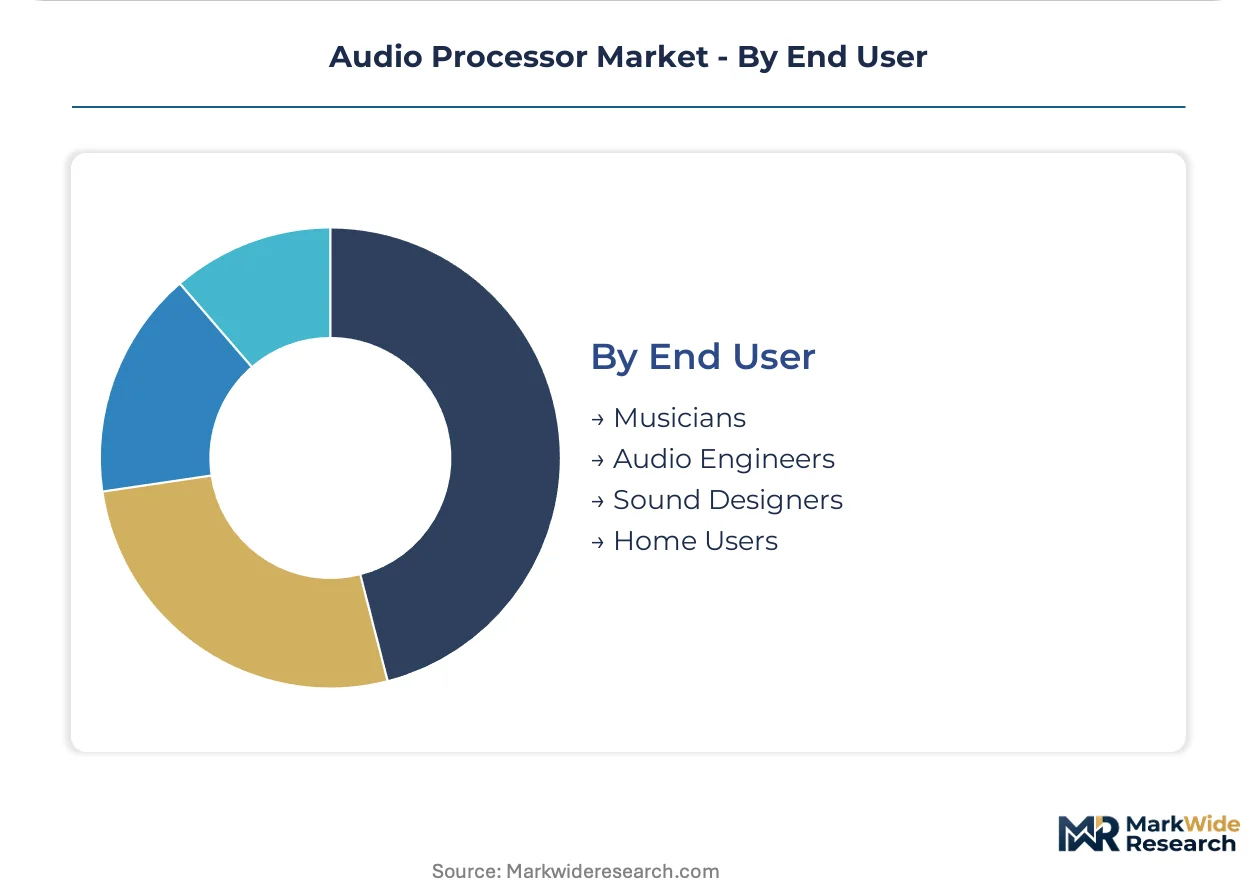
End User:
Professional practitioners prioritize specification transparency and repairability, while home users delegate technical decisions to integrated platform ecosystems.
- Audio Engineers:Recording, mixing, and mastering professionals specify equipment with published THD+N specifications and calibrated monitor controllers. Post-production facilities in Burbank and Soho maintain vendor relationships spanning decades.
- Musicians:Performers require portable processors with road-worthy enclosures and immediate tactile control. Touring professionals based in Austin and Manchester drive demand for ruggedized floor units and rack processors.
- Sound Designers:Game, film, and interactive media creators use specialized spatial audio tools and synthesis environments. Development studios in Montreal and Stockholm specify these for immersive content pipelines.
- Home Users:Casual listeners purchase through retail channels with feature-based differentiation and ecosystem compatibility as primary selectors. Mass-market distribution in São Paulo and Jakarta serves this segment through consumer electronics retailers.
Audio Engineers sustain premium pricing. Home Users represent the volume frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors global audio processor procurement, with domestic smartphone brands negotiating directly with foundries for integrated SoC capacity. Automotive infotainment demand in Stuttgart and Detroit is reshaping regional silicon priorities. Regulatory fragmentation across FCC spectrum rules, EU F-Gas phasedown schedules, and MIIT certification requirements is forcing multiregional qualification strategies.
United States
Automotive OEMs in Detroit mandate immersive audio as standard equipment across mid-tier vehicle segments, expanding silicon content per vehicle. FCC spectrum allocation rules for Bluetooth and Wi-Fi implementations constrain wireless audio processor architectures. Austin's semiconductor design cluster hosts fabless audio DSP specialists serving professional and consumer markets.
Germany
EU F-Gas Regulation compliance deadlines are accelerating migration to energy-efficient DSP designs with reduced thermal management overhead. Stuttgart-based automotive tier-one suppliers face steep 2027 interim targets for cabin electronics thermal budgets. Bavaria's industrial corridor concentrates precision manufacturing for professional audio equipment exports.
China
Domestic smartphone brands in Beijing and Shenzhen drive volume procurement of integrated audio SoCs with dedicated neural processing units. MIIT enforces GB standards for electromagnetic emissions that constrain product architectures serving domestic OEMs. The Pearl River Delta's vertically integrated electronics ecosystem accelerates platform lock-in between device brands and silicon design houses.
Japan
METI industrial policy supports domestic semiconductor capabilities for automotive and consumer audio applications. Automotive OEMs in Nagoya specify AEC-Q100 reliability grades and ISO 26262 functional safety targets for cabin audio processors. Tokyo's broadcasting infrastructure maintains procurement relationships with vendors holding decades-long service commitments for 24/7 reliability.
India
PLI scheme production-linked incentives for semiconductor assembly and testing are attracting audio processor packaging investments. Domestic mobile and automotive OEMs in Bangalore and Chennai source locally packaged solutions to reduce import dependency. Karnataka's electronics manufacturing cluster is expanding testing capacity for audio-integrated mobile SoCs.
Audio Processor Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue edge AI inference and ultra-low-power wearables. The vendor base spans integrated device manufacturers with captive fabrication, fabless specialists licensing DSP IP, and system-in-package integrators consolidating amplification and conversion functions. Three archetypes dominate: programmable DSP platform vendors, high-fidelity codec specialists, and mobile SoC integrators with captive audio subsystems. Competitive moves center on heterogeneous compute fabric development and strategic foundry partnerships for advanced node access.
Within the programmable DSP tier, Texas Instruments and Qualcomm exemplify divergent scale strategies. Texas Instruments sustains broad manufacturing across analog and digital audio product lines. Qualcomm anchors mobile-centric processing through platform-level integration. Cirrus Logic occupies a specialist position in high-fidelity codec solutions serving premium consumer electronics designs.
| Leading Market Players |
|---|
| STMicroelectronics |
| MediaTek |
| Texas Instruments |
| Asahi Kasei Microdevices |
| Cirrus Logic |
| NXP Semiconductors |
| Qualcomm |
| ON Semiconductor |
| Analog Devices |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up fabless audio DSP specialists in Austin and Shenzhen exercise pricing discipline through captive foundry relationships while automotive tier-one procurement teams in Stuttgart leverage EU F-Gas compliance deadlines to compress thermal-design-power premiums. This ownership pattern concentrates supply negotiation leverage among vertically integrated platform vendors.
Pricing Analysis
Wafer cost pass-through from TSMC and Samsung Foundry operations governs contract pricing for 7nm and 5nm audio SoC designs. Three-tier pricing structure across automotive-grade AEC-Q100, industrial-tier, and consumer-economy levels separates qualification investment from volume scale. Cost compression in mid-tier smartphone codecs is intensifying because domestic Chinese OEMs negotiate direct foundry allocation. Automotive tier-one buyers in Germany exhibit lowest price sensitivity due to ISO 26262 certification requirements.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for audio processor packaging and testing operations. Foundry supply concentrates in Taiwan, South Korea, and China with advanced-node fabrication feeding from silicon wafers, EUV photoresist, and specialty packaging substrates. Single-source vulnerability sits with TSMC's leading-edge capacity allocation. Distribution runs through tier-one electronics manufacturers serving automotive OEMs and Shenzhen handset integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU F-Gas thermal compliance costs in Germany and PLI-subsidized assembly economics in India.
For Market Incumbents: Acquire heterogeneous compute fabric IP portfolios to counter edge-AI inference specialists threatening programmable DSP margins. Secure allocated wafer capacity at Samsung Foundry as insurance against TSMC allocation constraints. Deepen backward integration into specialty ADC/DAC design teams in Tokyo and Austin to defend codec premium positioning. For New Entrants and Emerging Players: Begin with over-the-counter hearing aid channels in the United States where FDA regulatory clarity meets unserved self-fitting demand. Target India's domestic mobile OEM procurement offices in Bangalore for audio-integrated SoC packaging partnerships. Pursue direct foundry relationships bypassing established distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among analog processor specialists serving Nashville and London studio markets where digital displacement pressures obscure repairable equipment loyalty. Five-to-ten year viability favors heterogeneous compute fabric vendors with automotive safety certification pipelines. Monitor EU F-Gas 2027 interim compliance deadlines as inflection signal for thermal-design-power acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Heterogeneous Compute Fabric Development | Partitions workloads across neural, spectral, and temporal engines for EU F-Gas compliance. |
| Automotive Safety Certification Investment | ISO 26262 ASIL-B qualification opens Stuttgart and Detroit tier-one supplier relationships. |
| Edge AI Audio Inference Integration | TinyML convergence enables on-device speech recognition in Shenzhen wearable designs. |
| Strategic Foundry Partnership | Allocated 5nm capacity at Samsung Foundry insures against TSMC allocation volatility. |
| India PLI Scheme Localization | Karnataka packaging investments reduce import dependency for domestic mobile OEMs. |
Study Parameters
Multiple input streams — primary interviews with automotive tier-one procurement managers, fabless audio DSP design executives, and foundry capacity planners; secondary validation through SEC semiconductor filings, MIIT certification databases, and EU regulatory gazettes — were reconciled through bottom-up and top-down triangulation.
Historical shipment trajectories were cross-referenced against panel input from semiconductor industry analysts to anchor growth assumptions across the projection horizon. Segmentation modeling spanned product architecture, application qualification tier, wireless protocol implementation, and regional regulatory cluster. CAGR derivation incorporated foundry capacity expansion schedules and automotive platform lifecycle commitments.
Caveats apply where EU F-Gas phasedown acceleration, TSMC allocation rationing, or automotive production volatility could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
Automotive Chip Market