
 Microserver Market | 2026-2036
Microserver Market Size, Share, and Industry Trends Forecast 2026-2036
Microserver Market Intelligence
Expertise in system-on-chip (SoC) integration and low-power design is bifurcating the competitive landscape, separating specialized vendors from broadline IT hardware providers. Hewlett Packard Enterprise leverages its extensive portfolio to serve large enterprise and cloud service provider clients. Dell Technologies competes with integrated solutions spanning servers, storage, and networking for enterprise environments. Advanced Micro Devices differentiates through its high-performance x86 processor offerings targeted at data-intensive workloads.
A microserver is a compact, low-power server designed for dedicated, lightweight workloads, often in a shared infrastructure. These systems typically utilize system-on-chip (SoC) processors with ARM or x86 architecture and are engineered for high-density deployments. Rack-mounted microservers command a significant share due to compatibility with existing data center infrastructure. The edge computing application segment, however, drives new deployments, fueled by enterprise demand for localized data processing and analytics.
Energy efficiency standards, such as those within the EU Green Deal and the US EPA's ENERGY STAR program, directly influence hardware design choices and procurement criteria. Concurrently, data localization mandates in countries like India and Brazil shape deployment strategies for cloud service providers using these platforms. Vendor success is contingent upon navigating these disparate regulatory pressures while managing supply chain complexities for critical components like SoCs and memory modules.
Market Dynamics
The central structural force shaping the microserver market is the collision between escalating demand for distributed, low-latency computing at the network edge and the stringent power consumption and thermal constraints of these dense environments.
Growth Catalysts
- System-on-Chip Advancement:The maturation of ARM-based System-on-Chip (SoC) designs provides a foundation for low-power, high-density servers tailored for dedicated workloads like web hosting and content delivery, moving beyond the traditional dominance of x86 architecture.
- Edge Computing Demand:Enterprise adoption in industrial IoT and telecommunications drives deployment of microservers for localized data processing, reducing latency and backhaul costs for real-time analytics and control systems.
- Data Localization Mandates:Regulations in countries like India and Brazil require data to be stored and processed within national borders, compelling cloud service providers to build smaller, distributed data centers where microservers offer an efficient scaling model.
Market Restraints
- Limited Processing Power:Microservers are inherently designed for lightweight, scale-out tasks and lack the computational performance required for complex, monolithic enterprise applications or high-performance computing (HPC) workloads, limiting their addressable market.
- SoC Supply Concentration:The manufacturing of advanced SoC processors is highly concentrated in a few foundries, primarily in Taiwan, creating significant supply chain risk and price volatility for all microserver vendors.
- Integration Complexity:The software and management tools for large-scale microserver deployments can be less mature than those for traditional enterprise servers, creating a higher total cost of ownership (TCO) when factoring in operational and integration expenses.
Strategic Opportunities
- Private 5G Networks:The rollout of private 5G and multi-access edge computing (MEC) infrastructure by enterprises and mobile network operators creates a new application frontier for microservers to handle localized network functions and low-latency services.
- Energy Efficiency Mandates:Sustainability regulations, including the EU Green Deal and the US EPA's ENERGY STAR program for servers, create a strong procurement tailwind for energy-efficient microserver architectures that help data centers meet compliance targets.
- Infrastructure Buildout in Southeast Asia:Rapid digitalization and IT infrastructure investment across Southeast Asian nations offer a significant greenfield opportunity for vendors to establish microserver-based data centers optimized for regional cloud and edge services.
Industry Challenges
- Management Software Interoperability:Integrating heterogeneous microserver environments, particularly those mixing ARM and x86 architectures, with existing data center infrastructure management (DCIM) platforms presents a major operational challenge for IT teams.
- Lack of Form Factor Standardization:Beyond the conventional rack-mount format, a wide variety of custom and proprietary microserver designs hinders hardware interchangeability, complicates maintenance, and can lead to vendor lock-in for customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microserver Market |
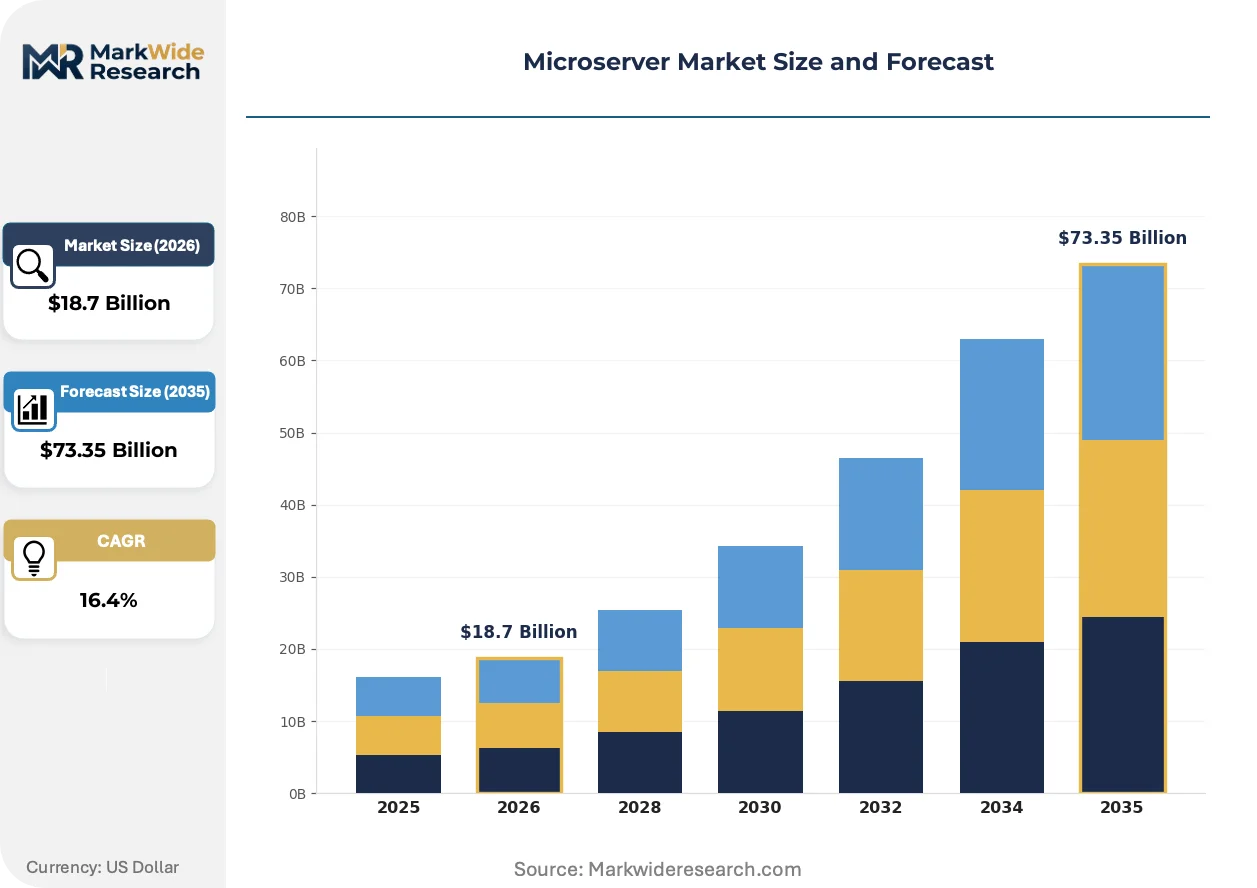
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack-Mounted Microservers, Blade Microservers, Tower Microservers, Compact Microservers Technology: ARM Architecture, x86 Architecture, Virtualization, Containerization End User: SMEs, Large Enterprises, Cloud Service Providers, Data Centers Application: Web Hosting, Big Data Analytics, Cloud Computing, Edge Computing |
| Companies Covered | Hewlett Packard Enterprise, Dell Technologies, Intel Corporation, Advanced Micro Devices, Super Micro Computer, Fujitsu Limited, Cisco Systems, Lenovo Group, Quanta Computer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microserver Market Strategic Shifts & Innovations
Hardware specialization is accelerating as the market moves from general-purpose servers toward purpose-built systems. This evolution prioritizes energy efficiency and workload optimization, with designs tailored specifically for tasks like edge analytics, content delivery, and simple web services.
System-on-Chip (SoC) technology integrates core processing, memory, and input/output functions onto a single, power-efficient semiconductor. Cloud service providers and edge infrastructure operators are adopting these integrated designs for dedicated, scale-out workloads. This core technology is miniaturizing the server footprint, enabling unprecedented compute density within existing data center racks and new edge locations.
The EU's Corporate Sustainability Reporting Directive (CSRD) and related Green Deal policies are forcing companies to report detailed energy and carbon metrics. This regulatory pressure makes energy efficiency a primary criterion in server procurement for data center operators and large enterprises. The rack-mounted microserver segment is directly impacted, as its low-power characteristics offer a clear path to improving Power Usage Effectiveness (PUE) and meeting sustainability goals.
A shift toward workload-specific infrastructure acquisition is altering traditional server buying patterns. Instead of a one-size-fits-all approach, organizations now select hardware based on the unique demands of an application, such as choosing an ARM-based microserver for a lightweight containerized service. This granular purchasing behavior is most prominent among hyperscale cloud providers in the United States and large financial services firms building private clouds.
Microserver Market Segmentation
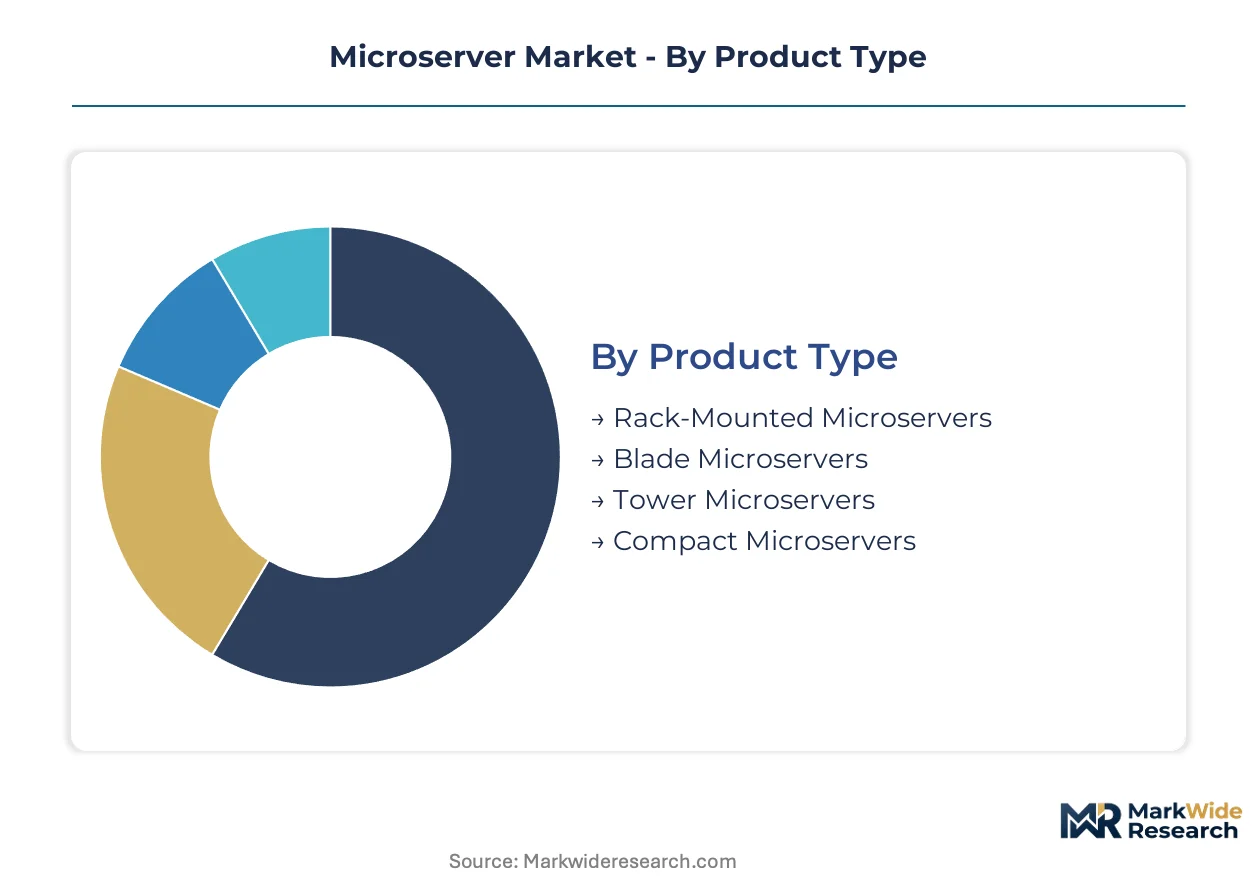
Understanding the microserver market through segmentation reveals distinct demand patterns and procurement strategies across various sectors. This granular view helps identify where specialized hardware designs and operational efficiencies are most valued by end-users.
Product Type:
The product type segmentation illustrates how microservers are distributed and deployed across different infrastructure models, influencing procurement channels.
- Rack-Mounted Microservers:These systems are designed for installation in standard server racks, offering high density and integration with existing data center cooling and power. Their demand concentrates in large data center hubs in the United States, driven by hyperscale cloud providers seeking efficient scaling.
- Blade Microservers:These modular systems integrate compute, storage, and networking into a single chassis, appealing to enterprises seeking simplified management and high density. Their adoption is notable among telecommunications firms in France for specialized network functions.
- Tower Microservers:These standalone units offer flexibility for small office environments or specialized edge deployments requiring less infrastructure and easier setup. Small and medium-sized businesses in Canada frequently procure these for localized applications.
- Compact Microservers:These are highly miniaturized units, often fanless, designed for deployment in constrained environments at the network edge, enabling localized processing. Enterprise adoption in industrial IoT applications in Germany drives demand for these small footprint devices.
By volume, Rack-Mounted Microservers lead the market. By growth pace, Compact Microservers are ahead.
Technology:
Technology choices in microservers dictate performance-per-watt and overall operational cost structures for deployers across various regions.
- ARM Architecture:Processors based on ARM's RISC instruction set offer superior energy efficiency and lower thermal output, making them ideal for high-density, low-power microserver deployments. Hyperscale cloud providers in Ireland are increasingly adopting ARM-based systems to meet stringent energy efficiency mandates under the EU Green Deal.
- x86 Architecture:These processors, primarily from Intel and AMD, provide established performance and broad software compatibility for diverse workloads, including more demanding enterprise applications. Demand for x86 microservers remains strong in financial services firms in London, where legacy application compatibility is critical.
- Virtualization:This technology allows multiple isolated virtual machines to run on a single physical microserver, optimizing resource utilization for varied workloads. Data centers in Japan leverage virtualization for efficient resource allocation and management.
- Containerization:Leveraging lightweight, portable software packages, containerization enables efficient application deployment and scaling on microserver platforms, particularly for cloud-native services. Developers in India are increasingly using containerization for agile application deployment.
Supply concentration for advanced microserver technologies remains with a few specialized semiconductor manufacturers globally.
End User:
End-user segments for microservers are defined by their specific application needs and operational scale, influencing purchasing priorities and deployment models.
- SMEs:Small and medium-sized enterprises utilize microservers for basic IT infrastructure, such as web hosting and file serving, valuing simplicity and cost-effectiveness. Businesses in Australia often seek straightforward, manageable microserver solutions.
- Large Enterprises:These organizations deploy microservers for specific departmental applications or edge computing initiatives, seeking localized processing capabilities. Automotive manufacturers in Germany use microservers for factory automation and data processing at the edge.
- Cloud Service Providers:These entities deploy microservers at massive scale to host web services, content delivery, and various cloud-native applications, prioritizing energy efficiency and high density. Major cloud providers in Virginia drive significant procurement, seeking to optimize their infrastructure for cost and power.
- Data Centers:Operators of colocation and enterprise data centers integrate microservers to expand compute capacity for lightweight, scale-out workloads, improving Power Usage Effectiveness (PUE). Demand in Singapore's data center market focuses on high-density solutions that support regional digital transformation initiatives.
Cloud Service Providers and Data Centers command higher volume purchases, influencing overall market margins for microserver vendors.
Application:
The application landscape for microservers dictates the volume and type of processing demands, shaping hardware configurations and deployment locations.
- Web Hosting:Microservers efficiently manage numerous websites and online services, offering dedicated resources for low-to-medium traffic volumes. Hosting providers in the Netherlands widely employ microservers for their energy efficiency.
- Big Data Analytics:While not for heavy computational tasks, microservers can handle distributed data ingestion and pre-processing for large datasets at the edge. Telecommunications companies in Brazil use microservers for localized data filtering.
- Cloud Computing:Microservers support distributed, scalable cloud infrastructure, handling lightweight, containerized workloads for public and private cloud environments. Hyperscale cloud providers in Texas utilize microservers to build out highly efficient, modular compute blocks.
- Edge Computing:This application involves processing data closer to its source, reducing latency for real-time analytics and control in industrial IoT and telecommunications. Enterprise adoption of edge computing in Japan for smart factories is expanding microserver deployments.
Edge Computing represents the fastest-growing application segment, while Web Hosting is a more mature but stable market for microservers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US EPA's ENERGY STAR program influences hardware design and procurement criteria for microservers, particularly in data centers. This regulatory pressure, combined with demand from hyperscale cloud providers, drives significant market activity. The global microserver landscape reflects diverse regional priorities and regulatory frameworks.
United States
Hyperscale cloud providers and enterprise edge computing initiatives drive demand for microservers in the United States. The US EPA's ENERGY STAR program encourages the adoption of energy-efficient solutions for data center infrastructure. Virginia's data center alley remains a prominent hub for large-scale microserver deployments, supporting vast cloud services.
India
India's developing IT infrastructure and stringent data localization mandates compel cloud service providers to deploy microservers. The Indian government's PLI scheme for IT hardware encourages domestic manufacturing and adoption of advanced computing solutions. Bangalore's tech hub sees substantial investment in distributed data centers utilizing microserver architectures.
Germany
Industrial IoT applications and advanced factory automation contribute to microserver demand in Germany. The EU Green Deal policies promote sustainable IT practices, favoring energy-efficient microserver designs. Automotive manufacturers in Bavaria integrate compact microservers for localized data processing at the production edge.
Japan
Japan's smart factories and efficient data center resource allocation fuel microserver deployments. METI's energy efficiency standards guide hardware procurement, emphasizing low-power solutions. Tokyo's dense data center market leverages microservers for high-density, virtualized environments supporting regional digital services.
Ireland
Hyperscale cloud providers in Ireland increasingly adopt microservers to meet stringent energy efficiency mandates. The EU Green Deal regulations make ARM-based microservers attractive for reducing operational carbon footprints. Dublin's robust cloud infrastructure continues to expand with new microserver deployments for distributed workloads.
Microserver Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the microserver market. This structure reflects a bifurcation between generalist IT hardware providers and niche innovators focused on specific use cases. Specialized vendors often target energy-efficient designs and SoC integration as key differentiators. Dominant competitive moves include strategic partnerships for technology co-development and portfolio diversification into edge computing solutions.
Within the integrated leaders tier, Hewlett Packard Enterprise and Dell Technologies exemplify broad enterprise solution providers. Advanced Micro Devices represents a key processor technology provider, influencing hardware design across the market. These entities leverage extensive portfolios to address diverse client needs, from large data centers to specialized edge deployments.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Dell Technologies |
| Intel Corporation |
| Advanced Micro Devices |
| Super Micro Computer |
| Fujitsu Limited |
| Cisco Systems |
| Lenovo Group |
| Quanta Computer |
Cost & Logistics Intelligence
Capacity reservation contracts in the microserver market lock in supply access and provide price visibility for critical System-on-Chip (SoC) components. This structure helps manage the inherent volatility of advanced semiconductor manufacturing.
Pricing Analysis
Geographic price spreads for microservers vary significantly, with higher costs observed in regions like India and Brazil due to localized infrastructure requirements. The dominant pricing model is contract-based long-term offtake for hyperscale cloud providers, alongside per-unit transactional sales for smaller enterprises. Price differentiation stems from volume scale and the performance-per-watt efficiency of ARM-based designs, combined with after-sales service bundles. Pricing softness is evident in the x86 segment due to intense competition, with SMEs exhibiting the highest price sensitivity compared to hyperscale cloud providers who prioritize long-term value.
Supply Chain Analysis
The highly concentrated manufacturing of advanced System-on-Chip (SoC) processors in Taiwan represents a critical chokepoint for the microserver supply chain. This supply chain draws from specialized foundries in South Korea and the United States for critical components like memory modules and high-performance interconnects. Single-source vulnerability for these complex SoCs poses a significant supply chain risk, impacting delivery timelines and costs. Distribution runs through direct sales channels to hyperscale cloud providers and enterprise IT departments, complemented by a network of value-added resellers for smaller deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microserver market requires a robust substitution defense against the threat of more powerful, general-purpose servers adopting greater energy efficiency. Incumbents must navigate this evolving landscape to maintain market relevance and capture growth.
For Market Incumbents: Compound investment in ARM-based SoC integration to counter the threat from x86 architectural advancements in power efficiency. Pursue strategic partnerships with specialized software vendors to enhance management tools for large-scale microserver deployments, addressing integration complexity. Develop comprehensive energy efficiency certification programs to meet evolving EU Green Deal and US EPA standards, reinforcing market leadership. Deepen vertical integration into critical component manufacturing to mitigate supply chain concentration risks.
For New Entrants and Emerging Players: Lead with purpose-built compact microserver solutions for the industrial IoT edge computing segment in Germany and Japan. Target underpenetrated regional markets in Southeast Asia with energy-efficient, localized data processing capabilities. The most penetrable segment is small-to-medium enterprises requiring simplified management for localized applications. Focus on a value-based go-to-market angle emphasizing total cost of ownership reduction through superior power efficiency.
For Investors and Strategic Acquirers: Specialized SoC design houses and advanced packaging firms represent attractive acquisition targets for long-term viability in the microserver market. These entities offer critical intellectual property and manufacturing expertise for next-generation, low-power architectures. The market's structural shift towards hardware specialization presents sustained growth opportunities over the next decade. A key signal to watch is the increasing adoption rate of ARM-based microservers by hyperscale cloud providers, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance ARM SoC Integration | Improves performance-per-watt metrics for hyperscale cloud providers in Ireland. |
| Develop Edge-Optimized Management Software | Reduces operational complexity for enterprise industrial IoT deployments in Germany. |
| Expand Compact Microserver Portfolio | Addresses demand for localized processing in constrained edge environments in Japan. |
| Secure Long-Term Foundry Agreements | Mitigates supply chain risks for critical SoC components from Taiwan. |
| Invest in Sustainable Hardware Design | Meets EU Green Deal and US EPA ENERGY STAR compliance targets for data centers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews to gather qualitative insights and validate quantitative findings. These included data center architects, enterprise IT procurement officers, SoC design engineers, and cloud service provider infrastructure leads. Secondary validation leveraged public company filings, government energy efficiency reports (e.g., US EPA, METI), and industry association publications. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and market sizing integrity.
The market forecast was developed using a robust analytical framework across the analysis window, integrating historical data with projected trends. Segmentation dimensions modeled included product type, technology, end-user, and application, alongside regional regulatory impacts. Compound Annual Growth Rates were derived from an assessment of adoption curves and technological maturation. Key forecast inputs included projected hyperscale cloud provider infrastructure spending and industrial IoT deployment rates.
The analysis sits within stated boundaries; outcomes outside of anticipated SoC supply stability or significant shifts in data localization policies would require recalibration. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Practitioners should keep alternative scenarios live as global semiconductor trade policies and energy efficiency mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
United States Data Center Processor Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
Auto Chip Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
5G Processor Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market